
 Antisense Therapy Market | 2026-2036
Antisense Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Antisense Therapy Market Insights
Specialty pharmacy distribution for antisense therapies is fragmenting as hospital systems and outpatient infusion centers build direct relationships with manufacturers. Ionis Pharmaceuticals sustains one of the deepest clinical pipelines in hereditary transthyretin amyloidosis and Huntington's disease. Biogen dominates spinal muscular atrophy with its established antisense platform, while Alnylam Pharmaceuticals differentiates through RNAi convergence strategies that blur traditional modality boundaries.
Antisense therapy deploys synthetic single-stranded oligonucleotides, typically 15–25 nucleotides in length, designed to bind complementary mRNA sequences and modulate protein expression through RNase H-mediated degradation or splice switching. ASOs occupy the most mature commercial position among product types, with approved therapies for spinal muscular atrophy and familial chylomicronemia syndrome generating predictable revenue. Neurological disorders represent the therapy area where unmet need and validated targets converge most sharply, though cancer applications are attracting expanded discovery investment.
FDA's orphan drug designation and breakthrough therapy pathways shape development economics by extending exclusivity and compressing review timelines. EMA's PRIME scheme and Japan's PMDA Sakigake designation create parallel fast-track ecosystems that influence trial site selection and regulatory strategy. Stakeholders must monitor how CMS and national health technology assessment bodies calibrate reimbursement for single-course antisense treatments against chronic therapy paradigms.
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME eligibility are compressing development timelines for RNA-targeting modalities, while hospital systems build direct procurement relationships that bypass traditional specialty pharmacy distribution.
Growth Catalysts
- Orphan Drug Exclusivity:FDA's seven-year market exclusivity for rare disease indications creates protected revenue windows for antisense developers targeting hereditary transthyretin amyloidosis and spinal muscular atrophy.
- Japan's PMDA Sakigake:Japan's regenerative medicine and advanced therapy fast-track designation accelerates priority review timelines, attracting trial site investment from sponsors seeking earlier Asian market entry.
- Hereditary Disease Pipelines:Validated genetic targets in Huntington's disease and Duchenne muscular dystrophy are pulling manufacturing capacity toward neurological disorder production.
Market Restraints
- Phosphorothioate Raw Material Concentration:Sulfur-modified oligonucleotide backbone chemistry depends on specialized reagent suppliers concentrated in Switzerland and Germany, creating single-source vulnerability.
- CMS Reimbursement Calibration:Medicare's National Coverage Determination process creates uncertainty for single-course gene-modifying therapies priced against chronic maintenance paradigms.
- Delivery Vector Limitations:Blood-brain barrier penetration remains the binding constraint for central nervous system applications, restricting addressable patient populations.
Strategic Opportunities
- Germany's Diagnosis-Related Group Reform:Germany's G-DRG system adjustments for innovative therapies create reimbursement headroom for hospital-administered antisense treatments.
- ASO-siRNA Convergence:Hybrid oligonucleotide platforms combining RNase H recruitment with RNAi machinery engagement are opening mechanistically distinct therapeutic categories.
- Direct-to-Hospital Distribution:Outpatient infusion centers in the United States are establishing captive pharmacy relationships that disintermediate wholesale distributors.
Industry Challenges
- Oligonucleotide Manufacturing Talent Scarcity:Synthetic chemistry and analytical method development expertise for large-scale ASO production concentrates among a narrow cohort of contract manufacturers.
- Multi-Regional Regulatory Synchronization:Divergent stability testing requirements between FDA, EMA, and PMDA force parallel development tracks that extend submission preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antisense Therapy Market |
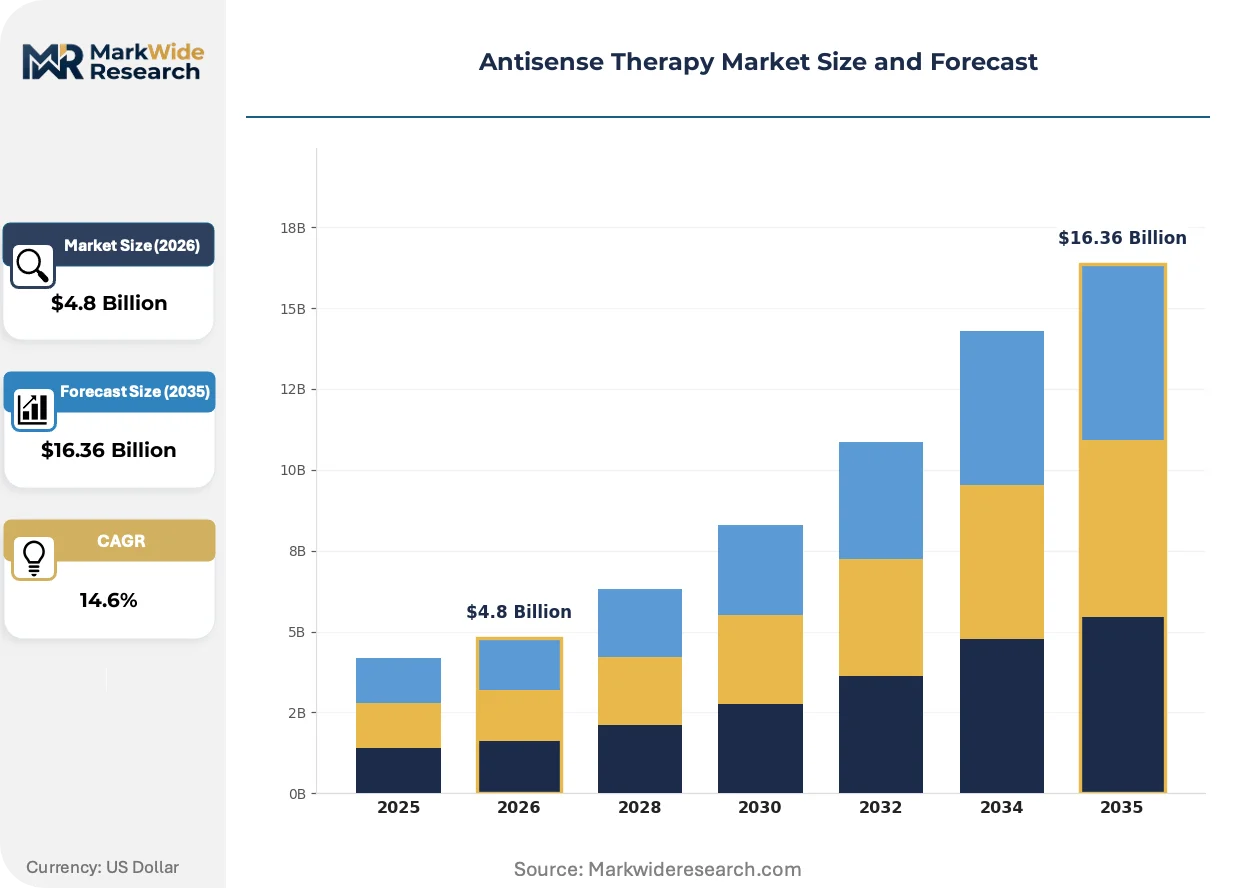
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASOs, Gene Silencing, Therapeutic Agents, RNA Modifiers End User: Hospitals, Research Institutions, Pharmaceutical Companies, Clinics Therapy Area: Cancer, Neurological Disorders, Genetic Disorders, Infectious Diseases Delivery Method: Intravenous, Subcutaneous, Oral, Local Administration |
| Companies Covered | Biogen, Benitec Biopharma, Ionis Pharmaceuticals, GSK, Arbutus Biopharma, Alnylam Pharmaceuticals, Silence Therapeutics, Sanofi, Sarepta Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antisense Therapy Market Trends and Innovations
Antisense modality boundaries are dissolving as molecular engineering converges with computational target prediction, while procurement relationships restructure around site-of-care administration economics.
Artificial intelligence-enabled target identification platforms are digitizing the earliest stages of oligonucleotide drug discovery. Biopharma sponsors are integrating machine learning models for RNA secondary structure prediction into target validation workflows. This capability is digitizing the traditional empirical screening process, compressing lead optimization timelines from years to months.
EMA's PRIME scheme eligibility criteria now explicitly reward biomarker-stratified trial designs for advanced therapy medicinal products. Sponsors are restructuring Phase I/II protocols to incorporate pharmacodynamic endpoints that satisfy conditional approval pathways. Neurological disorder programs targeting polyglutamine expansion diseases are most affected, with developers redesigning studies around cerebrospinal fluid target engagement measures.
Hospital pharmacy and therapeutics committees are asserting centralized control over antisense formulary placement, displacing physician-directed prescribing autonomy. Specialty pharmacy dispense-and-ship models are yielding to buy-and-bill arrangements where institutions capture margin on infused therapies. This concentration is most visible in United States academic medical centers managing spinal muscular atrophy patient populations.
Antisense Therapy Market Segmentation
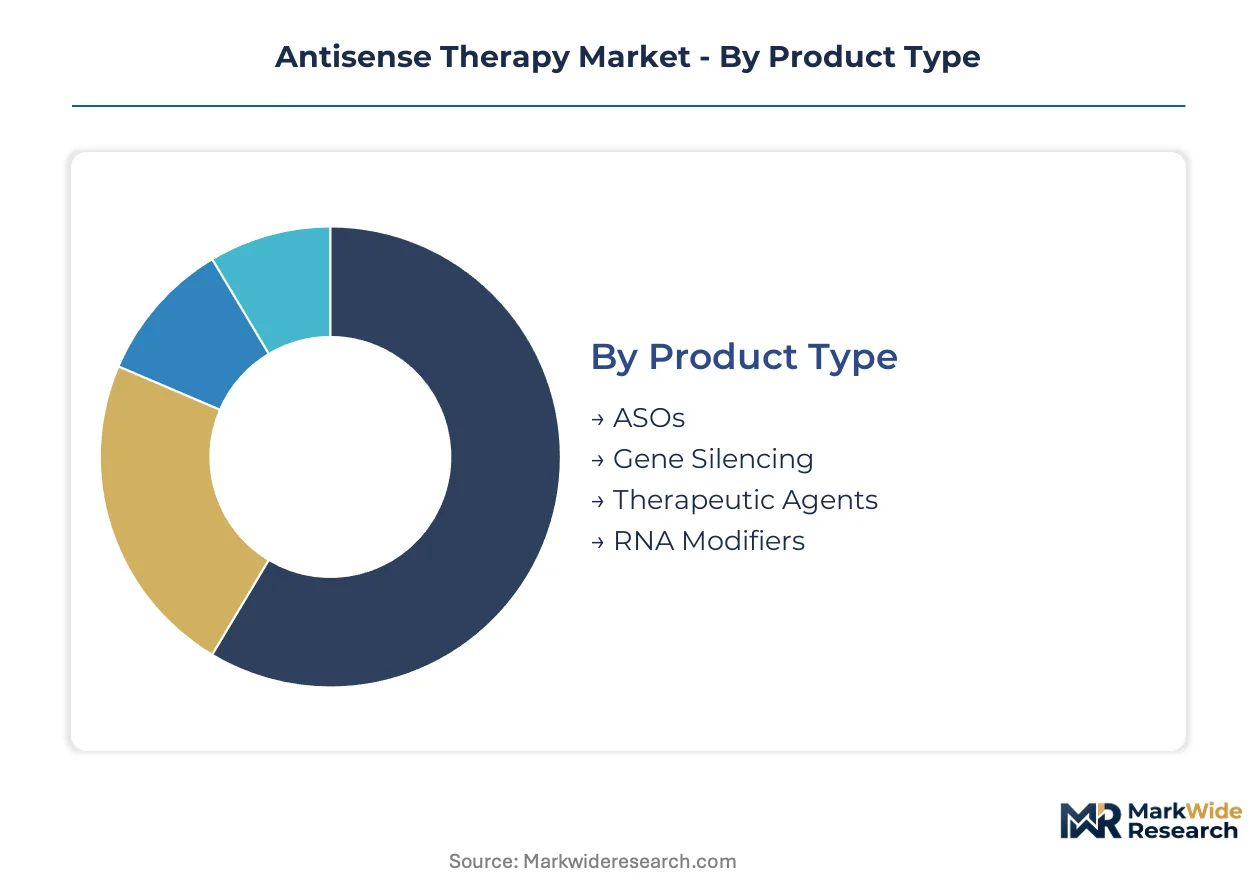
Antisense therapy segmentation reflects the interplay between molecular mechanism, clinical setting, and biological target. Each dimension shapes manufacturing requirements, regulatory pathways, and reimbursement negotiations differently.
Product Type:
Cost tier differentiation separates mature commercial platforms from emerging modalities still establishing manufacturing scale and payer acceptance.
- ASOs:Synthetic single-stranded oligonucleotides 15–25 nucleotides in length bind complementary mRNA sequences to trigger RNase H-mediated degradation or splice switching. Hospital procurement in the United States and Germany concentrates on established ASO platforms where infusion networks and reimbursement agreements have achieved critical density.
- Gene Silencing:RNA interference-based approaches engage the RISC complex to catalytically cleave target transcripts. Japanese PMDA Sakigake designations are accelerating development timelines for gene silencing candidates targeting hereditary transthyretin amyloidosis, pulling manufacturing investment toward neurological applications.
- Therapeutic Agents:Broader category encompassing conjugated oligonucleotides and hybrid architectures.
- RNA Modifiers:Emerging class targeting RNA editing and direct sequence modification without permanent transcript destruction.
ASOs command the established base. The steepest expansion runs through gene silencing.
End User:
Customer type determines distribution architecture, with direct-to-hospital procurement displacing traditional specialty pharmacy channels for infused therapies.
- Hospitals:Academic medical centers and specialized infusion centers administer intrathecal and intravenous antisense therapies for spinal muscular atrophy and Huntington's disease. United States hospital pharmacy and therapeutics committees are asserting centralized formulary control, capturing margin through buy-and-bill arrangements that disintermediate wholesale distributors.
- Pharmaceutical Companies:Sponsors internalize early-phase manufacturing and analytical development before transferring to contract manufacturers for commercial scale. Switzerland and Germany host concentrated phosphorothioate reagent supply, creating single-source vulnerability for sulfur-modified backbone chemistry.
- Research Institutions:Preclinical and translational programs supply target validation data.
- Clinics:Outpatient settings handle subcutaneous administration for select indications.
Hospitals capture the dominant volume share. Pharmaceutical companies drive the fastest capacity expansion.
Therapy Area:
Application focus determines target validation depth, biomarker strategy, and conditional approval pathway eligibility.
- Neurological Disorders:Polyglutamine expansion diseases and spinal muscular atrophy represent the most validated target space, with cerebrospinal fluid pharmacodynamic endpoints enabling accelerated approval. EMA's PRIME scheme explicitly rewards biomarker-stratified trial designs for neurological programs, restructuring Phase I/II protocols around target engagement measures.
- Cancer:Tumor-specific transcript targeting leverages synthetic lethality and immune modulation mechanisms. Discovery investment is expanding for oncogene-directed ASOs, though blood-brain barrier penetration constraints limit central nervous system oncology applications.
- Genetic Disorders:Orphan indications leverage FDA's seven-year exclusivity window.
- Infectious Diseases:Viral RNA targeting remains exploratory with limited commercial precedent.
Neurological disorders anchor current revenue. Cancer applications are climbing the fastest.
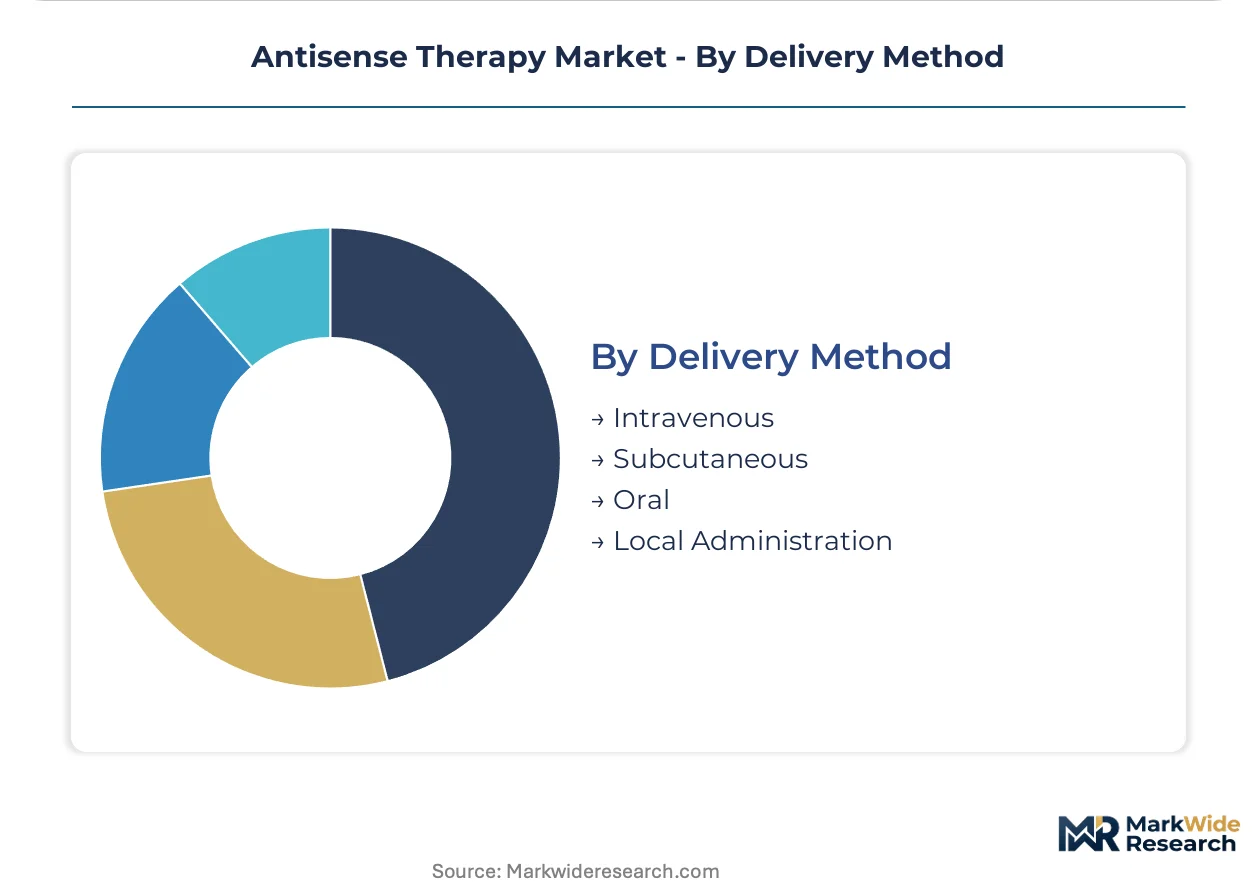
Delivery Method:
Route of administration shapes manufacturing formulation, cold chain requirements, and site-of-care economics.
- Intravenous:Systemic delivery enables liver and peripheral tissue targeting for metabolic and cardiovascular indications. Hospital-administered intravenous infusion requires specialized nursing protocols and extended observation periods, concentrating demand in United States and German academic medical centers with established rare disease programs.
- Subcutaneous:Self-administration potential reduces healthcare utilization costs and expands addressable geography beyond infusion center networks. Subcutaneous formulation development is accelerating for maintenance dosing regimens in hereditary transthyretin amyloidosis.
- Intrathecal:Cerebrospinal fluid delivery bypasses blood-brain barrier constraints for central nervous system targets.
- Oral:Bioavailability challenges limit current utility, though chemical modification programs aim to enable gastrointestinal absorption.
Intravenous infusion retains the installed base. Subcutaneous delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where specialist infusion networks command premium reimbursement rates, while Japanese and Swiss markets negotiate steeper discounts despite comparable clinical adoption.
United States
FDA breakthrough therapy designations accelerate spinal muscular atrophy and Huntington's disease programs through compressed review timelines. Medicare's National Coverage Determination process calibrates single-course gene-modifying therapy pricing against chronic maintenance paradigms. Boston and San Francisco anchor the deepest clinical trial site networks for intrathecal delivery development.
Germany
G-DRG system adjustments for innovative therapies create reimbursement headroom for hospital-administered antisense treatments in hereditary transthyretin amyloidosis. EMA's PRIME scheme eligibility rewards biomarker-stratified neurological trial designs with conditional approval pathways. Munich and Heidelberg concentrate phosphorothioate reagent supply chains for sulfur-modified backbone chemistry.
Japan
PMDA Sakigake designation accelerates priority review timelines for RNA-targeting modalities seeking earlier Asian market entry. The country's regenerative medicine and advanced therapy fast-track framework attracts trial site investment from global sponsors. Tokyo and Osaka host specialized infusion centers managing spinal muscular atrophy patient populations.
Switzerland
Swissmedic aligns with EMA accelerated pathways while maintaining distinct stability testing requirements for oligonucleotide therapeutics. The country's specialized reagent suppliers concentrate phosphorothioate raw material production for ASO manufacturing. Basel anchors contract manufacturing capacity for large-scale synthetic chemistry and analytical method development.
United Kingdom
NICE technology appraisals evaluate antisense therapies against quality-adjusted life year thresholds for rare disease indications. The MHRA's post-Brexit regulatory autonomy enables parallel submission strategies diverging from EMA timelines. London and Cambridge concentrate target validation research and preclinical translational programs for polyglutamine expansion diseases.
Antisense Therapy Market Competitive Landscape
Platform-scale developers and modality-specialist biotechs split the market between established commercial infrastructure and emerging mechanistic innovation. The competitive terrain tilts toward manufacturing capacity scarcity and regulatory pathway expertise rather than traditional marketing scale. Two dominant strategic archetypes occupy distinct positions: integrated pharmaceutical companies leveraging distribution depth, and focused biotechnology firms concentrating clinical pipeline density. Competitive moves center on direct-to-hospital distribution partnerships and hybrid oligonucleotide platform development combining RNase H recruitment with RNAi machinery engagement.
Among platform-scale developers, Biogen and Ionis Pharmaceuticals exemplify divergent strategic positions within the antisense modality. Biogen occupies a position representing integrated commercial infrastructure for neurological disorder administration. Ionis Pharmaceuticals sits within the focused biotechnology archetype, anchoring pipeline depth in hereditary transthyretin amyloidosis and Huntington's disease. Alnylam Pharmaceuticals represents the convergence strategy archetype, blurring traditional modality boundaries through RNAi platform development.
| Leading Market Players |
|---|
| Biogen |
| Benitec Biopharma |
| Ionis Pharmaceuticals |
| GSK |
| Arbutus Biopharma |
| Alnylam Pharmaceuticals |
| Silence Therapeutics |
| Sanofi |
| Sarepta Therapeutics |
| Others |
Pricing and Supply Chain Analysis
Basel and Munich anchor concentrated phosphorothioate reagent production for sulfur-modified oligonucleotide backbone chemistry, creating upstream scarcity that feeds into premium pricing for validated contract manufacturing slots. Hospital pharmacy and therapeutics committees in the United States and Germany exploit this concentration through buy-and-bill arrangements that capture margin on infused therapies.
Pricing Analysis
The customization-premium spread separates validated commercial ASO platforms from emerging gene silencing modalities still establishing manufacturing scale and payer acceptance. Three-tier pricing structure across premium, standard, and economy levels stratifies by regulatory approval status, biomarker stratification, and infusion center accreditation tier. Cost compression in the standard tier is intensifying because hospital systems consolidate formulary control and demand volume discounts for spinal muscular atrophy patient populations. Academic medical centers with established rare disease programs exhibit the least price sensitivity, while outpatient clinics managing subcutaneous maintenance regimens negotiate most aggressively on per-dose economics.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk planning for phosphorothioate raw material flows. Synthetic chemistry capacity concentrates in Switzerland, Germany, and the United States, drawing from specialized reagent suppliers and analytical method development expertise pools. Single-source vulnerability runs through sulfur-modified backbone chemistry precursors manufactured by a narrow cohort of European suppliers. Distribution runs through direct-to-hospital procurement relationships that disintermediate wholesale distributors for intrathecal and intravenous administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital pharmacy and therapeutics committees assert centralized formulary control over antisense therapy procurement, displacing physician-directed prescribing autonomy and fragmenting specialty pharmacy channels.
For Market Incumbents: Pre-empt emerging RNAi convergence platforms by deepening manufacturing capacity in Basel and Munich to secure phosphorothioate reagent supply chains against single-source vulnerability. Lock in exclusive direct-to-hospital distribution partnerships with United States academic medical centers before competitor ASO-siRNA hybrid platforms achieve commercial scale. FDA breakthrough therapy designation maintenance represents the critical regulatory lever for pricing power preservation. For New Entrants and Emerging Players: Subcutaneous delivery formulation development for hereditary transthyretin amyloidosis maintenance regimens represents the most penetrable entry point, as established players concentrate on intrathecal administration for neurological disorders. Japan's PMDA Sakigake fast-track pathway offers accelerated market access with lower clinical trial site density requirements than FDA or EMA routes. Target hospital outpatient infusion centers in secondary United States markets where formulary control remains less consolidated. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-scale developers with established intrathecal delivery infrastructure and validated biomarker-stratified trial endpoints. Long-term viability across the analysis window favors integrated manufacturers with captive phosphorothioate chemistry capabilities and direct hospital procurement relationships. Watch for EMA PRIME scheme conditional approval decisions in Huntington's disease programs as the signal for neurological disorder platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-stratified Phase I/II protocols satisfy EMA PRIME conditional approval pathways for neurological programs. |
| Manufacturing Scale-Up | Synthetic chemistry capacity expansion in Basel secures phosphorothioate reagent supply against single-source vulnerability. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for spinal muscular atrophy candidates. |
| Pipeline Diversification | ASO-siRNA hybrid platforms open mechanistically distinct therapeutic categories beyond traditional modality boundaries. |
| Hospital System Partnership | Direct-to-hospital distribution relationships capture buy-and-bill margin and disintermediate wholesale distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA PRIME eligibility determinations, ClinicalTrials.gov protocol registrations, and hospital formulary placement databases. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed demand-side assumptions. Secondary validation drew from SEC 10-K filings, CMS National Coverage Determination documents, and G-DRG system adjustment records. Bottom-up patient population sizing and top-down revenue triangulation cross-checked segmentation outputs.
Forecast inputs span treatment line, administration route, regional regulatory cluster, and therapy area across the modeling period. CAGRs were derived from segmented volume and value trajectories incorporating pipeline probability-weighted revenue recognition. Key inputs include conditional approval pathway success rates, hospital formulary placement velocity, and phosphorothioate manufacturing capacity expansion schedules. Neurological disorder and cancer application splits were modeled separately given divergent biomarker validation maturity.
Stress conditions across CMS reimbursement calibration, EMA stability testing requirement divergence, and phosphorothioate supplier concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and manufacturing scale-up feasibility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Anti-Cathepsin B Market