
 Blue Biotechnology Market | 2026-2036
Blue Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Biotechnology Market Analysis
The EU Green Deal is restructuring procurement criteria for marine-derived ingredients across European pharmaceutical and food manufacturers. Aker BioMarine leverages its Antarctic krill harvesting operations to secure consistent raw material flows for omega-3 and phospholipid production. BASF SE anchors its position through industrial-scale fermentation platforms that convert marine biomass into high-purity enzymes. Cyanotech Corporation specializes in microalgae cultivation systems at its Kona, Hawaii facility, producing astaxanthin for nutraceutical applications.
Blue biotechnology encompasses the application of molecular and cell biology tools to marine and freshwater organisms for the extraction, modification, or synthesis of biologically active compounds, typically operating at salinity levels of 30-35 PSU and temperatures adapted to cold-adapted enzyme kinetics. Marine-derived compounds dominate current revenue pools due to established demand from pharmaceutical formulators seeking novel bioactive scaffolds. Genetic engineering competes with traditional cultivation methods by shortening strain development cycles for high-value metabolites such as polyunsaturated fatty acids and carotenoids. Bioinformatics extends analytical capabilities through metagenomic screening of unculturable marine microbiota, accelerating target identification without exhaustive physical sampling.
The European Medicines Agency evaluates marine-sourced drug candidates under centralized marketing authorization procedures, while the U.S. Food and Drug Administration maintains specific guidance for aquaculture-derived therapeutics regarding contaminant profiling. REACH compliance in Europe imposes substance registration requirements on imported marine biochemicals, altering supplier qualification protocols for non-EU producers. Stakeholders must monitor how evolving ESG disclosure rules under the EU Corporate Sustainability Reporting Directive reshape buyer diligence requirements for ocean-sourced inputs.
Market Dynamics
Marine-derived active ingredients are displacing synthetic alternatives across pharmaceutical pipelines as cold-adapted enzyme kinetics unlock novel bioactive scaffolds inaccessible through terrestrial biotechnology. This structural shift concentrates procurement power among formulators with validated cold-chain logistics and Antarctic harvesting licenses.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants accelerates demand for enzymatic cold-processing technologies that operate at sub-zero temperatures without synthetic coolants.
- Pharmaceutical formulators:Major drug developers now mandate marine-sourced polyunsaturated fatty acids and phospholipids for neurodegenerative and cardiovascular therapeutic programs.
- Arctic research infrastructure:Norway's Svalbard marine stations and Tromsø biobanks provide authenticated strain libraries that shorten lead times for novel compound discovery.
Market Restraints
- Krill biomass volatility:Antarctic catch quotas fluctuate with Commission for the Conservation of Antarctic Marine Living Resources assessments, constraining omega-3 raw material predictability.
- REACH registration costs:European substance registration fees for imported marine biochemicals exceed €100,000 per compound, excluding smaller non-EU extractors from continental supply chains.
- Fermentation scale-up barriers:Industrial photobioreactor construction for microalgae cultivation demands specialized stainless-steel alloys resistant to saline corrosion at 30-35 PSU.
Strategic Opportunities
- CSRD disclosure mandates:The EU Corporate Sustainability Reporting Directive creates premium pricing tiers for marine ingredients with verified ecosystem impact documentation and traceable harvesting coordinates.
- Metagenomic screening platforms:Bioinformatics pipelines analyzing unculturable deep-sea microbiota bypass physical sampling costs while accelerating target identification for oncology applications.
- Aquaculture biotechnology clusters:Scotland's emerging marine innovation corridor offers underutilized cold-water cultivation capacity for high-value carotenoid production.
Industry Challenges
- Cryobiology expertise scarcity:Qualified technicians for maintaining viable marine cell lines at sub-zero temperatures command salary premiums that strain R&D budgets at mid-scale fermentation facilities.
- EMA centralized authorization timelines:Marine-sourced drug candidates face 18-24 month evaluation periods under European Medicines Agency procedures, compressing patent-protected revenue windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Biotechnology Market |
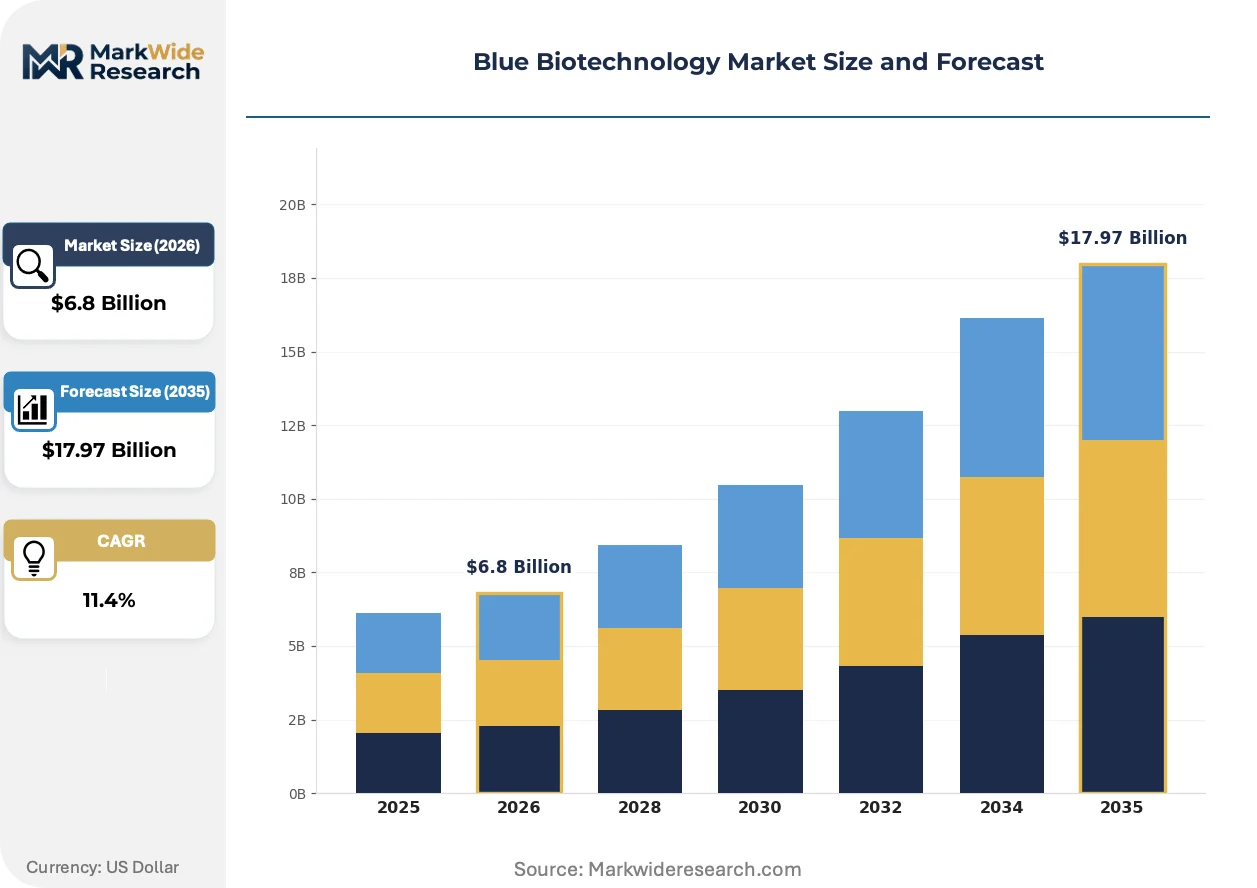
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Marine-Derived Compounds, Biofuels, Bioplastics Application: Aquaculture, Bioremediation, Pharmaceuticals, Food & Beverage Technology: Genetic Engineering, Fermentation, Cultivation, Bioinformatics End User: Agriculture, Healthcare, Environmental Services, Industrial Manufacturing |
| Companies Covered | Aker BioMarine, New England Biolabs, Cyanotech Corporation, BASF SE, CP Kelco U.S., Inc., Marinova Pty Ltd, GeoMarine Biotechnologies, Archer Daniels Midland Company, Sea Run Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Biotechnology Market Emerging Trajectories
Metagenomic sequencing platforms are collapsing the discovery timeline for novel marine bioactives, enabling pharmaceutical formulators to bypass exhaustive physical ocean sampling. This technological inflection is compressing competitive moats around established strain libraries.
Synthetic biology toolkits are unifying CRISPR-based strain engineering with automated bioreactor control systems, allowing real-time metabolite pathway optimization. Contract research organizations in Denmark and Singapore deploy these integrated platforms to shorten polyunsaturated fatty acid production cycles from 18 months to under 6 months. The convergence is compressing development economics for mid-tier nutraceutical entrants.
EMA guidance on aquaculture-derived therapeutics now mandates expanded contaminant profiling for heavy metals and persistent organic pollutants. European pharmaceutical manufacturers are responding by qualifying Antarctic and North Atlantic harvesting zones with lower industrial runoff exposure. This regulatory tightening is fragmenting supplier approval lists and concentrating procurement among vertically integrated harvesters with captive testing laboratories.
Formulators are consolidating vendor relationships around single-source contracts with guaranteed volume commitments and fixed-price clauses spanning 36-month horizons. This behavioral shift displaces spot-market purchasing that dominated omega-3 procurement through 2023. Norwegian and Peruvian extraction facilities report the most pronounced contract conversion rates as buyers seek insulation from krill biomass quota volatility.
Blue Biotechnology Market Segmentation
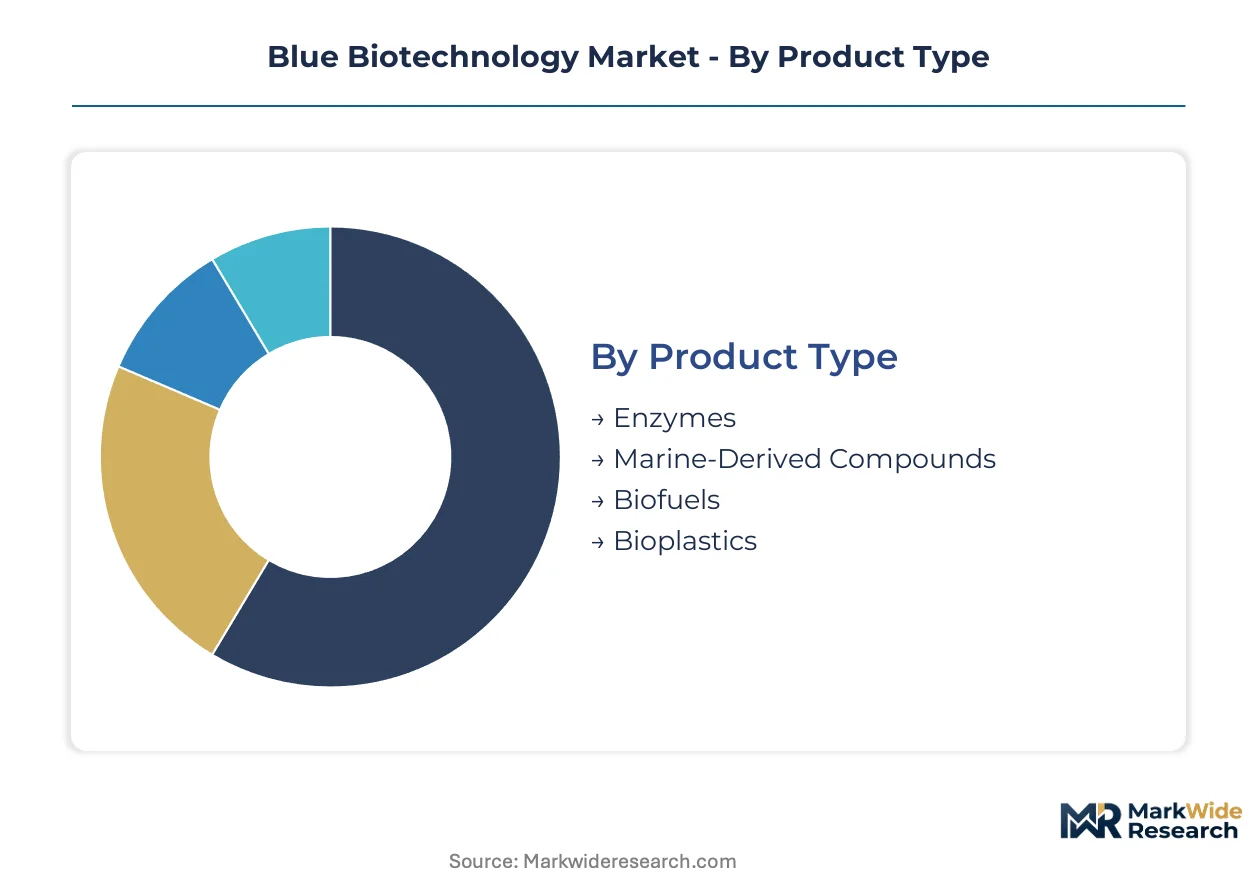
Segmentation in blue biotechnology reveals how value flows from raw biomass extraction through specialized processing technologies to distinct end-use specifications. Pharmaceutical formulators and aquaculture operators demand fundamentally different product purity grades and documentation standards.
Product Type:
Standalone enzyme products operate as discrete inputs with defined catalytic specifications, while marine-derived compounds and biofuels embed within broader formulation systems requiring compatibility testing.
- Enzymes:Cold-adapted hydrolases and oxidoreductases function at 4-15°C with 40-60% higher catalytic efficiency than terrestrial equivalents. Norwegian pharmaceutical manufacturers source these for lipid modification processes, though cryogenic logistics constrain supplier qualification to Arctic-adjacent facilities with validated cold-chain infrastructure.
- Marine-Derived Compounds:Omega-3 concentrates, phospholipid fractions, and carotenoid isolates constitute high-value nutraceutical and pharmaceutical inputs. Demand concentrates among EMA-authorized drug developers seeking novel bioactive scaffolds for neurodegenerative therapeutic programs, with REACH registration requirements filtering non-EU extractors from continental supply chains.
- Biofuels:Algal lipid-to-biodiesel conversion pathways remain pre-commercial at industrial scale.
- Bioplastics:Polyhydroxyalkanoate production from marine bacterial strains faces cost barriers against petrochemical alternatives.
Volume placements concentrate in marine-derived compounds; the faster expansion belongs to enzymes.
Application:
Cost tier differentiation separates commodity aquaculture feed additives from premium pharmaceutical actives with 10-20x unit value multiples.
- Pharmaceuticals:Marine-sourced drug candidates undergo EMA centralized authorization with 18-24 month evaluation timelines. Cold-adapted enzyme kinetics enable bioactive scaffolds inaccessible through terrestrial biotechnology, concentrating procurement among formulators with Antarctic harvesting licenses and captive contaminant testing laboratories.
- Aquaculture:Probiotic formulations and immunostimulant feeds dominate Norwegian salmon production systems. Scottish marine innovation corridors offer underutilized cold-water cultivation capacity for high-value carotenoid integration into premium feed tiers.
- Bioremediation:Marine microbial consortia degrade petroleum hydrocarbons in polar marine environments.
- Food & Beverage:Astaxanthin and omega-3 fortification targets functional food positioning in European markets.
Premium pricing tiers concentrate in pharmaceuticals; aquaculture represents the largest volume placement.
Technology:
Customer type splits between research-intensive pharmaceutical developers seeking metagenomic discovery platforms and industrial manufacturers prioritizing fermentation scale-up reliability.
- Fermentation:Industrial photobioreactor construction demands specialized stainless-steel alloys resistant to saline corrosion at 30-35 PSU. BASF SE anchors its position through industrial-scale platforms converting marine biomass into high-purity enzymes, with Danish contract research organizations deploying automated control systems for real-time metabolite pathway optimization.
- Bioinformatics:Metagenomic screening platforms analyze unculturable deep-sea microbiota without exhaustive physical sampling. Singapore-based CROs compress polyunsaturated fatty acid production cycles from 18 months to under 6 months through CRISPR-integrated automated systems.
- Genetic Engineering:CRISPR-based strain engineering shortens development cycles for high-value metabolites.
- Cultivation:Open-pond and closed photobioreactor systems compete on capital intensity versus contamination control.
Steepest expansion trajectory belongs to bioinformatics; fermentation retains dominant volume placement.
End User:
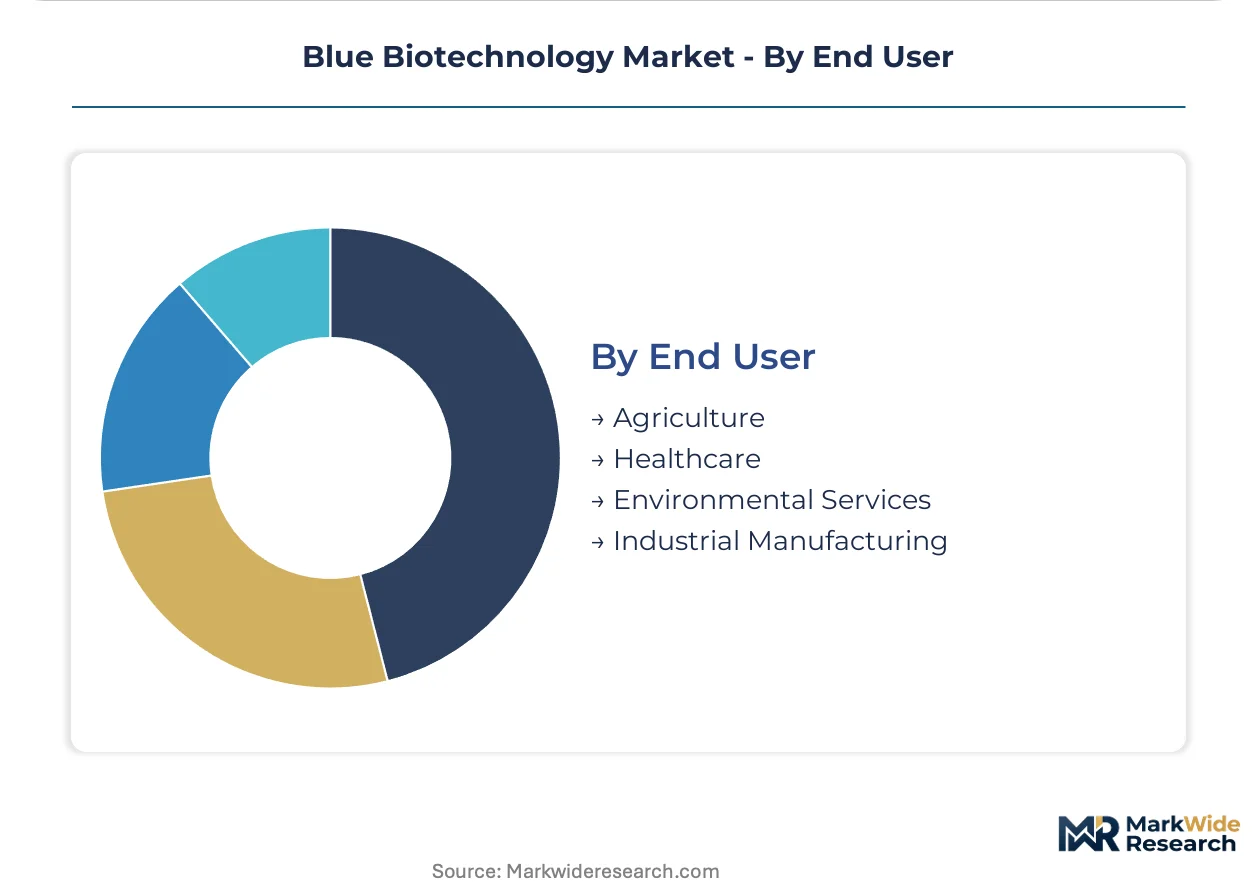
Geography clusters around North Atlantic and Antarctic harvesting zones with lower industrial runoff exposure, concentrating supply relationships among vertically integrated operators.
- Healthcare:Drug developers mandate marine-sourced polyunsaturated fatty acids and phospholipids for neurodegenerative and cardiovascular programs. EMA guidance on aquaculture-derived therapeutics mandates expanded heavy metal and persistent organic pollutant profiling, fragmenting supplier approval lists toward captive testing operations.
- Industrial Manufacturing:Enzymatic cold-processing technologies substitute for hydrofluorocarbon refrigerants under EU F-Gas Regulation phasedown schedules. Industrial manufacturers qualify sub-zero enzymatic systems for lipid modification and specialty chemical synthesis.
- Agriculture:Marine biostimulants target high-value horticultural crop segments.
- Environmental Services:Oil spill response and wastewater treatment applications drive bioremediation demand.
Healthcare commands premium unit economics; industrial manufacturing scales fastest on volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antarctic and North Atlantic harvesting zones supply raw biomass while pharmaceutical formulators in Germany, Norway, and the United States consume refined marine actives. This geographic split concentrates upstream extraction among licensed polar operators and downstream value capture among EMA-authorized drug developers.
Norway
Arctic marine research infrastructure and established aquaculture biotechnology clusters drive national specialization in cold-adapted enzyme production. The Norwegian Food Safety Authority enforces strict contaminant profiling for marine-derived ingredients entering pharmaceutical supply chains. Tromsø biobanks and Svalbard marine stations authenticate strain libraries that shorten lead times for novel compound discovery.
Germany
Industrial-scale fermentation platforms and REACH compliance expertise position German manufacturers as preferred suppliers to continental pharmaceutical formulators. ECHA substance registration requirements filter non-EU extractors from supply chains, elevating domestic biochemical producers. BASF SE anchors enzyme production through saline-resistant bioreactor systems operating at 30-35 PSU.
United States
FDA guidance on aquaculture-derived therapeutics mandates expanded heavy metal and persistent organic pollutant screening for imported marine biochemicals. Hawaiian microalgae cultivation facilities supply astaxanthin for nutraceutical applications under USDA organic certification protocols. West Coast contract research organizations deploy CRISPR-integrated automated systems for real-time metabolite pathway optimization.
Singapore
Contract research organizations compress polyunsaturated fatty acid production cycles through bioinformatics pipelines analyzing unculturable deep-sea microbiota. The Health Sciences Authority regulates marine-sourced drug candidates under ASEAN harmonized standards. Biotech parks in Tuas and one-north host fermentation scale-up facilities serving Asia-Pacific pharmaceutical formulators.
United Kingdom
Scotland's emerging marine innovation corridor offers underutilized cold-water cultivation capacity for high-value carotenoid production. The Medicines and Healthcare products Regulatory Agency evaluates marine-sourced therapeutics under post-Brexit recognition agreements with EMA. Aberdeen and Edinburgh research clusters specialize in metagenomic screening platforms that bypass exhaustive physical ocean sampling.
Blue Biotechnology Market Vendor Landscape
The competitive structure tilts toward vertically integrated harvesters with captive testing laboratories and Antarctic licensing. Tiered specialization separates industrial-scale fermentation operators from boutique metagenomic discovery platforms. Three archetypes dominate: polar biomass extractors with guaranteed catch quotas, enzyme manufacturers with saline-resistant bioreactor infrastructure, and bioinformatics specialists with automated strain engineering capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as formulators consolidate vendor relationships around single-source contracts.
Among polar biomass specialists, Aker BioMarine exemplifies the licensed extractor archetype through Antarctic krill harvesting operations. BASF SE represents industrial-scale fermentation dominance with marine biomass conversion capabilities. Cyanotech Corporation occupies a position within microalgae cultivation specialists, anchoring the high-value carotenoid production tier from its Hawaii-based facility.
| Leading Market Players |
|---|
| Aker BioMarine |
| New England Biolabs |
| Cyanotech Corporation |
| BASF SE |
| CP Kelco U.S., Inc. |
| Marinova Pty Ltd |
| GeoMarine Biotechnologies |
| Archer Daniels Midland Company |
| Sea Run Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EMA-authorized pharmaceutical inputs and commodity aquaculture feeds manifests in 10-20x unit value multiples and Antarctic licensing requirements for premium tiers. Buyers with REACH-registered supply chains command pricing power through contaminant-tested strain libraries, while spot-market purchasers of unverified krill biomass absorb quota volatility.
Pricing Analysis
Margin tightening in pharmaceutical-grade marine compounds reflects REACH registration fees exceeding €100,000 per compound that filter non-EU extractors from continental supply chains. Contract-based long-term offtake agreements with 36-month fixed-price clauses now dominate omega-3 procurement, displacing spot-market purchasing. Price differentiation rests on EMA authorization status and Antarctic harvesting licenses versus unverified North Atlantic sourcing. Industrial manufacturers face acute cost-down pressure as enzymatic cold-processing substitutes for phased-out hydrofluorocarbon refrigerants under EU F-Gas Regulation schedules.
Supply Chain Analysis
REACH compliance and EMA contaminant profiling requirements gate supplier qualification to Norwegian, German, and US operators with captive testing laboratories. Raw material flows draw from Antarctic krill quotas administered by CCAMLR and North Atlantic cold-water biomass harvested through Arctic-adjacent facilities. Single-source vulnerability concentrates around Commission for the Conservation of Antarctic Marine Living Resources assessments that constrain omega-3 raw material predictability. Distribution runs through vertically integrated harvesters with validated cold-chain logistics rather than fragmented spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blue biotechnology sector is consolidating around upstream control over Antarctic harvesting licenses and downstream captive testing infrastructure. Players securing both poles of this vertical-integration race will capture margin expansion as EMA authorization timelines lengthen and biomass quotas tighten.
For Market Incumbents: Lock in Antarctic catch quota security through multi-year CCAMLR licensing renewals and backward integration into Tromsø biobank strain authentication. Cryobiology technician scarcity threatens mid-scale fermentation expansion; anchor R&D budgets with Arctic-adjacent facilities where qualified cold-chain labor concentrates. Defend against metagenomic discovery platforms by accelerating CRISPR-integrated automated bioreactor deployments that compress polyunsaturated fatty acid production cycles. For New Entrants and Emerging Players: Mid-tier nutraceutical formulators with unmet demand for REACH-registered phospholipid fractions present the most penetrable buyer archetype. Scotland's emerging marine innovation corridor offers underutilized cold-water cultivation capacity without incumbent quota entanglements. A bioinformatics-led go-to-market angle analyzing unculturable deep-sea microbiota bypasses exhaustive physical sampling costs while accelerating target identification for oncology applications. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated harvesters possessing both Antarctic licensing and EMA-authorized contaminant testing laboratories given CSRD disclosure mandates creating premium pricing tiers for traceable marine ingredients. Long-term viability over the next decade hinges on securing authenticated strain libraries before metagenomic screening platforms collapse discovery timelines. The signal to watch is consolidation velocity among Norwegian and Peruvian extraction facilities reporting pronounced contract conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Antarctic Harvesting License Renewal | CCAMLR quota security guarantees raw material flows for omega-3 production cycles. |
| REACH Registration Completion | ECHA substance registration unlocks continental pharmaceutical supply chain access. |
| Metagenomic Screening Platform Deployment | Bioinformatics pipelines collapse novel compound discovery timelines without physical sampling. |
| Cryogenic Logistics Infrastructure Investment | Validated cold-chain systems qualify suppliers for cold-adapted enzyme pharmaceutical contracts. |
| CSRD-Compliant Ecosystem Documentation | Verified traceable harvesting coordinates command premium pricing tiers from European formulators. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fermentation facility managers, pharmaceutical procurement leads, regulatory affairs directors at EMA-authorized drug developers, and Antarctic harvesting operators provided qualitative validation. ECHA substance registration databases, FDA aquaculture-derived therapeutic guidance documents, CCAMLR catch quota assessments, and EU Green Deal procurement criteria furnished quantitative benchmarks. Bottom-up strain library valuations and top-down marine biomass extraction volume reconciliations triangulated market sizing.
Reconciling production capacity announcements from Norwegian and German fermentation operators against pharmaceutical formulator offtake commitments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, technology platform, and end-user industry vertical. CAGRs derived from historical extraction volume trajectories and anticipated EMA authorization pipeline flows. Industry-specific forecast inputs encompass Antarctic krill biomass quota volatility and REACH registration cost pass-through elasticity.
Revisions become necessary when CCAMLR assessments materially alter catch quotas, when EMA contaminant profiling guidance expands testing requirements, or when EU F-Gas Regulation phasedown schedules accelerate. Forecasts reflect assumptions regarding cryogenic logistics capacity expansion and metagenomic platform adoption curves. A model refresh is warranted upon material change in CSRD disclosure enforcement stringency or Antarctic licensing renewal patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Bioremediation Market