
 Multi-Touch Screen Market | 2026-2036
Multi-Touch Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Touch Screen Market Intelligence
Asset-light leasing models for touch sensor manufacturing equipment is reconfiguring capital barriers for mid-tier entrants. Samsung Electronics leverages captive OLED fabs to sustain vertical integration across projected capacitive stacks. TPK Holding anchors high-volume supply relationships with tier-one device OEMs. General Interface Solution Holding specializes in narrow-bezin designs for automotive displays, differentiating through precision patterning capabilities.
A multi-touch screen detects and processes simultaneous contact points through capacitive, resistive, infrared, or optical sensing layers bonded to glass or polymer substrates, with projected capacitive technology employing indium tin oxide (ITO) or metal mesh electrodes to achieve sub-millimeter positional accuracy for human-machine interface applications. Capacitive product types dominate consumer electronics volumes where finger-driven interaction defines usability standards, while infrared and optical variants capture industrial automation deployments requiring gloved-hand operability and environmental resilience. The technology dimension splits between projected capacitive leadership in premium smartphones and surface acoustic wave retention in legacy kiosks and point-of-sale terminals where cost amortization cycles run longer.
The EPA regulates electronic waste recovery rates affecting touch panel end-of-life obligations for US-bound products, while REACH compliance mandates substance disclosure across ITO and conductive adhesive supply chains serving European automotive and healthcare end users. China's GB standards for electromagnetic compatibility constrain sensor design parameters for domestically sold industrial equipment. Stakeholders must monitor evolving F-Gas Regulation thresholds for manufacturing process emissions as European production requirements tighten, and assess whether backward integration into sensor glass melting or controller IC sourcing alters cost structures ahead of next-generation automotive qualification cycles.
Market Dynamics
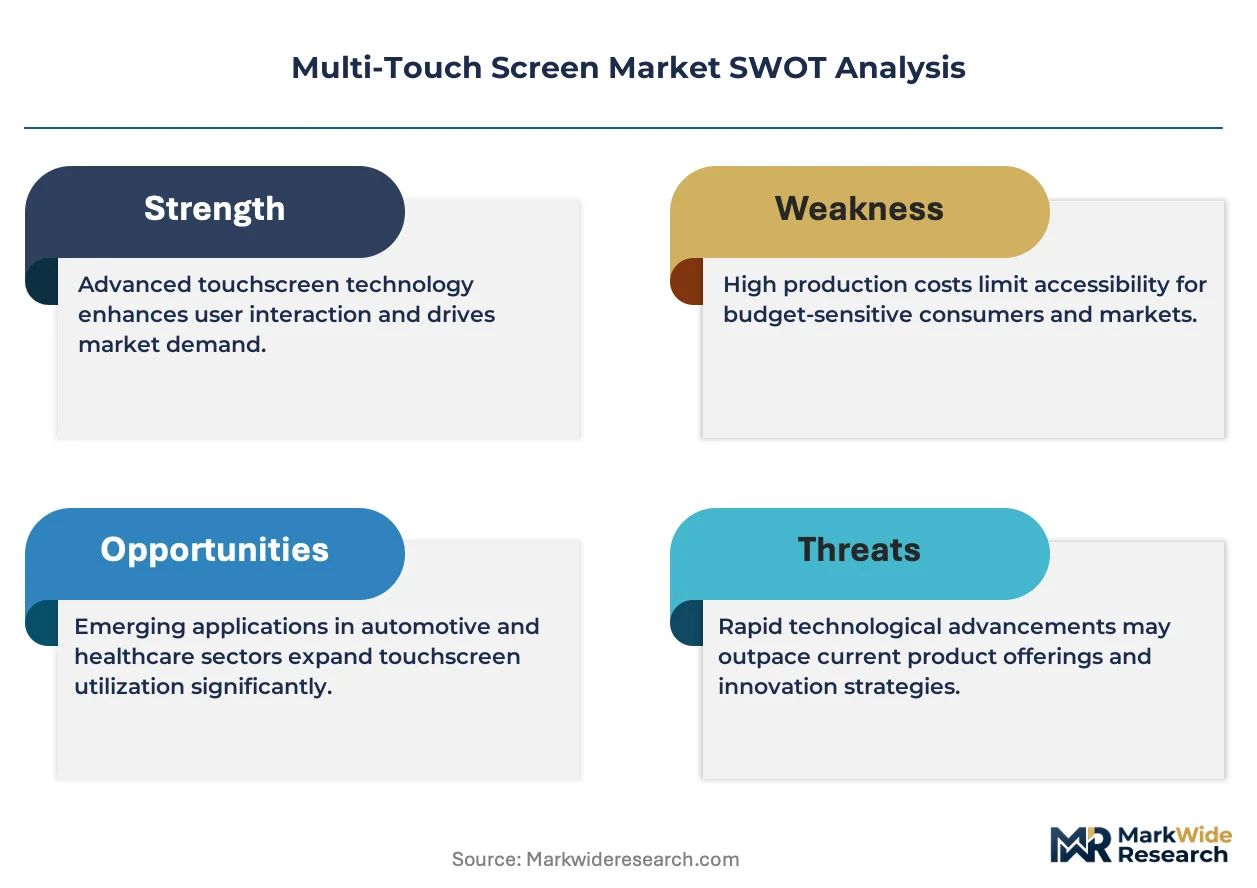
Automotive OEM qualification cycles are compressing development timelines for projected capacitive suppliers, forcing simultaneous compliance with REACH substance restrictions and electromagnetic compatibility mandates across multiple jurisdictions.
Growth Catalysts
- Automotive digitization:Center console and instrument cluster deployments in Germany and Japan are expanding addressable unit volumes for capacitive stack manufacturers serving tier-one integrators.
- REACH compliance:ECHA substance disclosure mandates for ITO and conductive adhesives are filtering supplier bases toward qualified European automotive and healthcare component vendors.
- Guangdong manufacturing concentration:Panel fabrication clusters in China's Guangdong province are achieving scale economies that downstream integrators leverage across consumer electronics and industrial automation.
Market Restraints
- Indium supply concentration:ITO electrode production depends on geographically concentrated indium refining, exposing touch sensor cost structures to raw material volatility and export restriction risks.
- Surface acoustic wave legacy retention:Extended amortization cycles in kiosks and point-of-sale terminals delay replacement demand for projected capacitive alternatives.
- F-Gas Regulation thresholds:EU manufacturing process emission limits are tightening compliance burdens for European-based touch panel production facilities.
Strategic Opportunities
- Industrial gloved-hand operability:Infrared and optical sensing variants are capturing automation deployments where environmental resilience and protective equipment compatibility exceed capacitive performance limits.
- Asset-light equipment leasing:Manufacturing equipment leasing models are lowering capital barriers for mid-tier entrants seeking qualified supplier status without fab ownership.
- GB standards compliance:China's electromagnetic compatibility requirements for domestically sold industrial equipment are creating certification-driven preference advantages for compliant sensor designers.
Industry Challenges
- Controller IC sourcing complexity:Backward integration decisions into semiconductor procurement are altering cost structures ahead of automotive qualification cycles.
- Patterning precision requirements:Narrow-bezel automotive display specifications demand sub-millimeter accuracy that strains legacy photolithography capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Touch Screen Market |
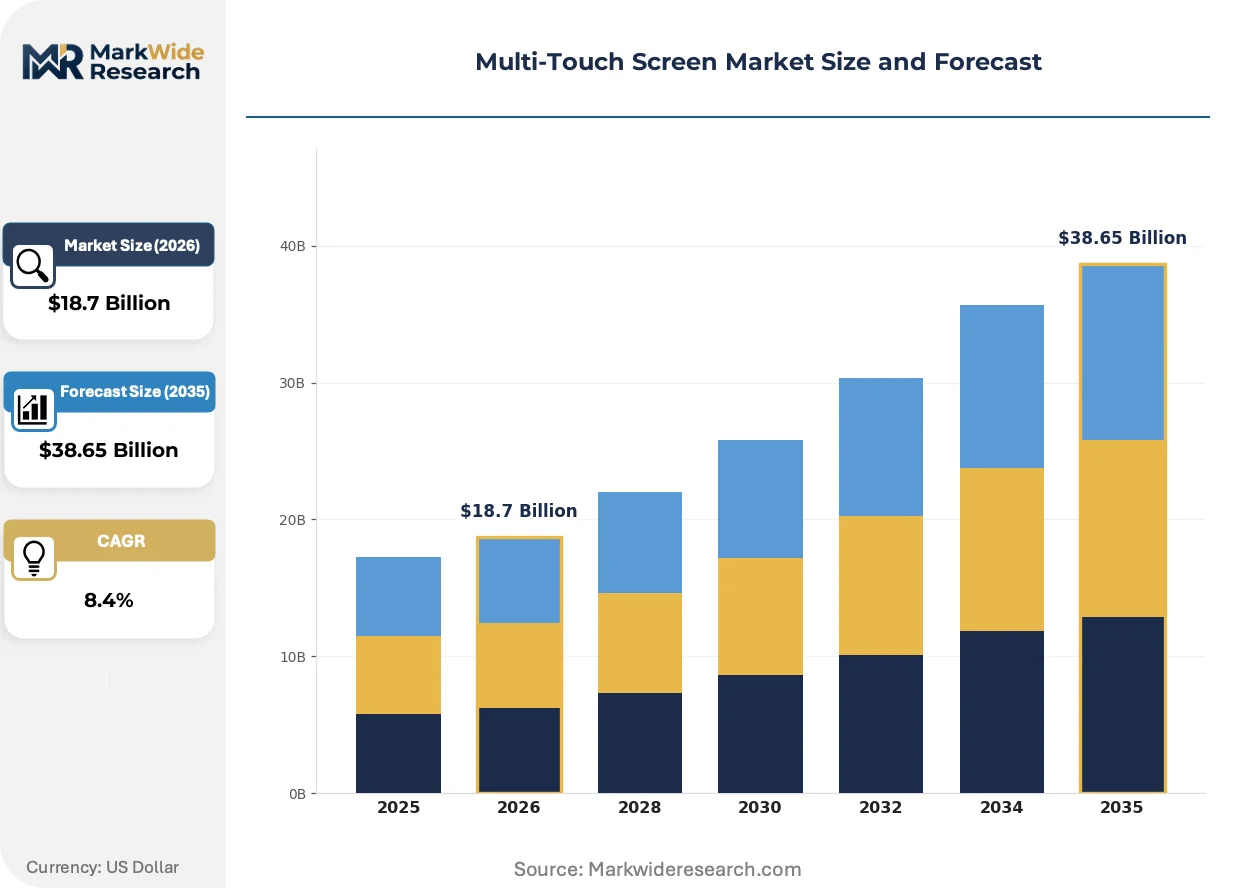
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Optical Application: Consumer Electronics, Industrial Automation, Gaming, Education Technology: Projected Capacitive, Surface Acoustic Wave, IR Touch, Optical Imaging End User: Retail, Healthcare, Automotive, Hospitality |
| Companies Covered | TPK Holding, Wintek Corporation, Samsung Electronics, 3M, LG Electronics, Synaptics Incorporated, General Interface Solution Holding, Apple, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Touch Screen Market Strategic Shifts & Innovations
Metal mesh electrode architectures are supplanting ITO in large-format and flexible applications, while regulatory pressure on hazardous substances and manufacturing emissions reshapes material selection and process design across supply chains.
Metal mesh conductive layers are replacing indium tin oxide in automotive and industrial displays requiring bend radius tolerance and lower sheet resistance. Tier-one automotive OEMs in Germany and Japan are qualifying these stacks for curved center console implementations. This transition is digitizing patterning equipment requirements and compressing qualification timelines for alternative electrode suppliers.
EU F-Gas Regulation thresholds are tightening manufacturing process emission limits for European touch panel production. Facilities serving automotive and healthcare end users must retrofit process gas handling or relocate fabrication to jurisdictions with looser environmental controls. Surface acoustic wave legacy producers with depreciated European assets face disproportionate compliance cost exposure relative to Asian competitors with newer fabs.
Buyers are consolidating supplier relationships around vertically integrated capacitive stack providers with captive controller IC and sensor glass capabilities. Device OEMs in consumer electronics are reducing qualified vendor lists from six to two suppliers per program. This concentration is most visible in South Korea, where Samsung Electronics leverages internal OLED fab integration to capture expanded share of high-volume smartphone touch module procurement.
Multi-Touch Screen Market Segmentation
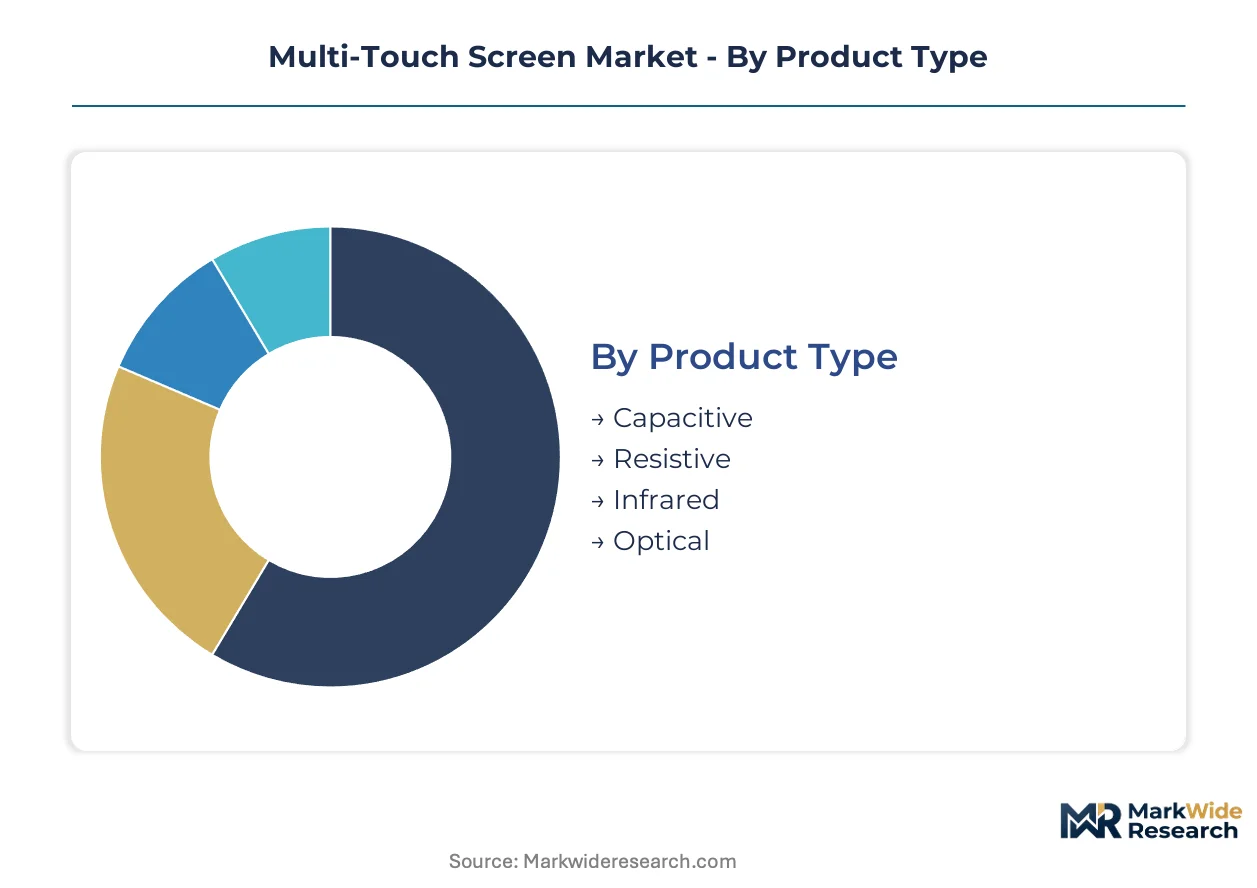
Multi-touch screen segmentation reveals how sensing technologies map to distinct operational environments and procurement priorities across automotive, industrial, and consumer domains. Product type and technology choices directly determine compatibility with glove-wearing operators, curved surface geometries, and electromagnetic interference constraints.
Product Type:
The use-case spectrum spans finger-driven precision interfaces to gloved-hand industrial deployments where environmental resilience overrides responsiveness.
- Capacitive:Projected capacitive layers using ITO or metal mesh electrodes achieve sub-millimeter positional accuracy for smartphone and automotive center console applications. German and Japanese OEMs are expanding deployments across instrument clusters and curved displays, though indium supply concentration exposes cost structures to raw material volatility.
- Infrared:IR frame arrays detect touch interruptions without surface conductivity, enabling gloved-hand operability in factory automation and outdoor kiosks. Demand is concentrating in China's Guangdong province manufacturing clusters where downstream integrators source ruggedized panels for industrial equipment.
- Resistive:Pressure-activated dual-layer construction survives harsh chemical exposure in legacy point-of-sale and medical device applications.
- Optical:Camera-based triangulation supports very large formats where bezel-free edge-to-edge activation matters.
The dominant share belongs to Capacitive, while Infrared is closing the gap fastest.
Application:
Volume distribution correlates with replacement cycles and digitization maturity across end-use sectors.
- Consumer Electronics:Smartphone and tablet deployments drive the highest unit volumes, with South Korean device OEMs consolidating qualified supplier lists around vertically integrated stack providers. REACH substance disclosure mandates for ITO and conductive adhesives are filtering European supplier bases toward qualified vendors.
- Industrial Automation:Factory floor HMIs and process control panels prioritize environmental sealing and electromagnetic compatibility. China's GB standards for electromagnetic compatibility constrain sensor design parameters for domestically sold equipment, creating certification-driven preference advantages.
- Gaming:Arcade and casino floor installations demand vandal-resistant surfaces with multi-user simultaneous tracking.
- Education:Interactive whiteboard deployments in institutional procurement cycles favor cost-optimized infrared and optical variants.
Consumer Electronics commands the largest revenue pool, yet Industrial Automation exhibits the steepest expansion trajectory as manufacturing digitization accelerates.
Technology:
Process compatibility and patterning precision requirements separate premium automotive qualifications from legacy infrastructure retention.
- Projected Capacitive:Mutual-capacitance electrode matrices enable multi-finger gesture recognition with minimal bezel intrusion. Metal mesh architectures are supplanting ITO in large-format and flexible automotive implementations, digitizing patterning equipment requirements for tier-one suppliers.
- Surface Acoustic Wave:Ultrasonic transducer arrays deliver optical clarity without conductive coatings, retaining installed base in kiosks and point-of-sale terminals where extended amortization cycles delay replacement demand.
- IR Touch:LED-photodetector frame configurations scale economically to very large diagonal measurements.
- Optical Imaging:Stereoscopic camera triangulation enables object recognition beyond simple touch detection.
Projected Capacitive holds established leadership, though Surface Acoustic Wave retention in legacy infrastructure moderates conversion velocity.
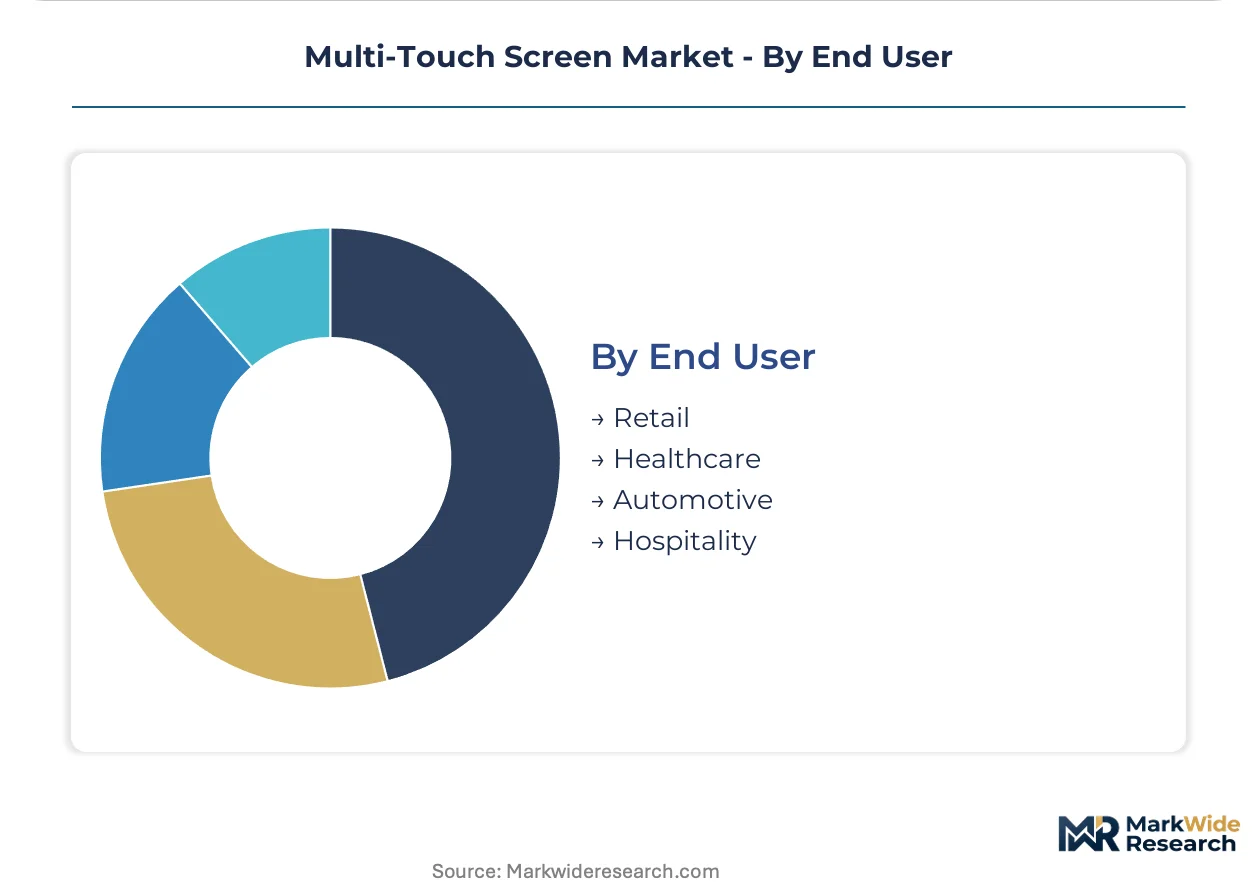
End User:
Procurement sophistication and compliance burden intensity vary sharply across sector-specific qualification regimes.
- Automotive:Center console and instrument cluster deployments impose simultaneous REACH substance restrictions and electromagnetic compatibility mandates across multiple jurisdictions. Narrow-bezel specifications demand sub-millimeter patterning accuracy that strains legacy photolithography capabilities.
- Healthcare:Medical device interfaces require ECHA substance disclosure compliance across ITO and conductive adhesive supply chains, favoring qualified European component vendors with documented material traceability.
- Retail:Self-service kiosks and point-of-sale terminals balance durability against total cost of ownership in high-traffic environments.
- Hospitality:Guest-facing interactive directories and in-room control panels prioritize aesthetic integration over technical performance extremes.
Automotive captures the highest value per unit, while Healthcare is gaining share fastest through regulatory-driven supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed industrial policy is redirecting touch sensor fabrication capacity across four major economies. Subsidy programs for advanced display manufacturing in Asia and emissions regulations in Europe are reshaping where projected capacitive stacks undergo final assembly.
China
Guangdong province panel fabrication clusters supply downstream integrators across consumer electronics and industrial automation. GB standards for electromagnetic compatibility constrain sensor design parameters for domestically sold equipment. Shenzhen and Dongguan manufacturing zones are absorbing capacity expansion from Korean and Taiwanese touch module suppliers seeking tariff-advantaged production bases.
Germany
Automotive OEM qualification cycles for center console and instrument cluster deployments are compressing development timelines for projected capacitive suppliers. REACH substance restrictions and ECHA disclosure mandates for ITO and conductive adhesives filter supplier bases toward qualified European component vendors. Bavaria and Baden-Württemberg host tier-one automotive electronics integrators qualifying metal mesh electrode stacks for curved display implementations.
Japan
METI-funded next-generation display initiatives support domestic touch sensor manufacturers serving precision industrial automation and automotive end users. JIS standards for electromagnetic compatibility align with stringent automotive OEM requirements. Chubu and Kansai manufacturing corridors concentrate surface acoustic wave legacy production alongside emerging projected capacitive qualification programs.
South Korea
Device OEMs are consolidating qualified supplier lists from six to two suppliers per program around vertically integrated stack providers. Domestic OLED fab integration enables captive supply chain control for high-volume smartphone touch module procurement. Seoul Capital Area and Gyeonggi province host the concentration of captive touch controller IC and sensor glass capabilities.
United States
EPA electronic waste recovery rates affect touch panel end-of-life obligations for domestically bound products. FDA electromagnetic compatibility requirements for medical device interfaces impose additional qualification burdens on healthcare-facing sensor vendors. Texas and Arizona semiconductor corridors attract touch controller IC design operations seeking proximity to systems integrators.
Multi-Touch Screen Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base organizes around three strategic archetypes: vertically integrated display conglomerates with captive touch module operations, independent touch sensor specialists serving multiple device OEMs, and component-focused suppliers concentrating on narrow-bezel or automotive-grade patterning capabilities. Dominant competitive moves include backward integration into controller IC sourcing and geographic relocation of final assembly to tariff-advantaged jurisdictions.
Among Asian fabricators, TPK Holding and General Interface Solution Holding occupy positions within the independent specialist tier. Samsung Electronics exemplifies the vertically integrated archetype through captive OLED fab operations. These three entities anchor distinct competitive vectors: high-volume supply relationships, precision patterning differentiation, and in-house production of complete capacitive stacks.
| Leading Market Players |
|---|
| TPK Holding |
| Wintek Corporation |
| Samsung Electronics |
| 3M |
| LG Electronics |
| Synaptics Incorporated |
| General Interface Solution Holding |
| Apple |
| Panasonic |
| Others |
Cost & Logistics Intelligence
Indium supply concentration in Chinese and Korean refining corridors determines both the premium commanded by metal mesh electrode alternatives and the geographic relocation patterns of touch sensor fabrication. REACH substance disclosure mandates for ITO and conductive adhesives compress pricing spreads between qualified European automotive suppliers and unqualified Asian volume producers, while tariff exposure on controller IC imports reshapes backward integration decisions across tier-one device OEMs.
Pricing Analysis
Certification level—REACH-compliant versus standard-grade—creates the primary spread between automotive-qualified and consumer-electronics touch stacks. Pricing stratifies across premium, standard, and economy tiers based on patterning precision and electromagnetic compatibility testing depth. Cost compression in the standard tier intensifies because Guangdong manufacturing clusters achieve scale economies that strain legacy photolithography-dependent suppliers. Automotive OEM procurement teams exhibit the lowest price sensitivity due to qualification cycle switching costs, while education-sector interactive whiteboard buyers drive the hardest volume discounts.
Supply Chain Analysis
Extended payment terms from tier-one automotive OEMs to projected capacitive suppliers have normalized 90-day cycles that strain working capital for mid-tier entrants lacking supply-chain finance facilities. Manufacturing concentrates in China, South Korea, and Japan, with sensor glass melting anchored in Japanese and Korean captive operations while final module assembly clusters in Guangdong. Controller IC sourcing rests on Taiwan and South Korean foundry capacity, exposing touch module cost structures to single-source vulnerability in advanced node availability. Distribution runs through tier-one automotive electronics integrators in Germany and Japan, direct procurement by South Korean device OEMs, and industrial automation distributors serving China's factory automation sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive digitization across center console and instrument cluster deployments represents an early-cycle expansion story, with metal mesh electrode qualification programs at German and Japanese OEMs driving penetration gains ahead of legacy surface acoustic wave replacement waves.
For Market Incumbents: Entrench qualified supplier status by accelerating metal mesh patterning equipment deployment ahead of compressed automotive qualification timelines. Secure captive controller IC sourcing through foundry partnerships or in-house design capabilities to defend margin position against Samsung Electronics' vertical integration. Monitor REACH substance restriction evolution as a regulatory chokepoint that filters competitor bases toward documented material traceability. For New Entrants and Emerging Players: India's underpenetrated industrial automation sector offers white-space access where GB standards compliance creates certification-driven preference advantages for qualified sensor designers. Target China's inland provinces beyond Guangdong for cost-optimized infrared touch deployments in factory floor HMI applications. Pursue asset-light equipment leasing models to bypass capital barriers and achieve qualified supplier status without fab ownership. For Investors and Strategic Acquirers: EU F-Gas Regulation threshold tightening reshapes the acquisition landscape by forcing European facility retrofit or relocation decisions that favor Asian-targeted roll-ups. Focus on mid-tier projected capacitive specialists with automotive qualification pipeline visibility and metal mesh electrode transition readiness. Watch indium price volatility and export restriction signals as inflection indicators for metal mesh substitution acceleration and ITO-dependent asset impairment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Metal Mesh Electrode Qualification | Enables curved automotive center console deployments at German and Japanese OEMs. |
| Controller IC Backward Integration | Captive semiconductor sourcing compresses cost structures ahead of automotive cycles. |
| REACH Compliance Investment | Substance disclosure documentation filters European supplier bases toward qualified vendors. |
| Guangdong Manufacturing Expansion | Tariff-advantaged production bases absorb Korean and Taiwanese capacity relocation. |
| Asset-Light Equipment Leasing | Manufacturing equipment leasing lowers capital barriers for mid-tier entrant qualification. |
Research Approach
Initial hypotheses were tested against primary input from touch sensor procurement managers at tier-one automotive electronics integrators, projected capacitive stack manufacturing executives, industrial automation HMI designers, and device OEM supply chain directors, then refined through secondary validation across SEC filings from Samsung Electronics and TPK Holding, ECHA substance disclosure databases, GB standards electromagnetic compatibility documentation, and customs trade data for indium and ITO electrode imports. Bottom-up segment sizing triangulated against top-down market consolidation estimates derived from panel fabrication capacity disclosures in Guangdong and South Korea.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value outputs through segmentation by product type (capacitive, infrared, resistive, optical), application (consumer electronics, industrial automation, automotive, healthcare), technology (projected capacitive, surface acoustic wave, IR touch), and end user procurement sophistication. CAGRs were derived from installed base replacement cycle analysis, automotive digitization penetration curves, and metal mesh electrode substitution elasticity. Forecast inputs incorporated REACH compliance cost pass-through assumptions and F-Gas Regulation retrofit expenditure timelines for European production facilities.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by South Korean display conglomerates or accelerated metal mesh qualification programs by Japanese automotive OEMs would shift outcomes. Macroeconomic deviation in indium commodity markets, regulatory expansion of substance disclosure mandates beyond ITO to metal mesh alloys, or technological breakthroughs in optical sensing for gloved-hand applications would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
IGZO Display Market
Display Technologies
3LCD Projector Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Global Embedded Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Global OLED Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Smart Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
North America Industrial Display Market