
 Middle East and Africa Industrial Display Market | 2026-2036
Middle East and Africa Industrial Display Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Industrial Display Market Foresight
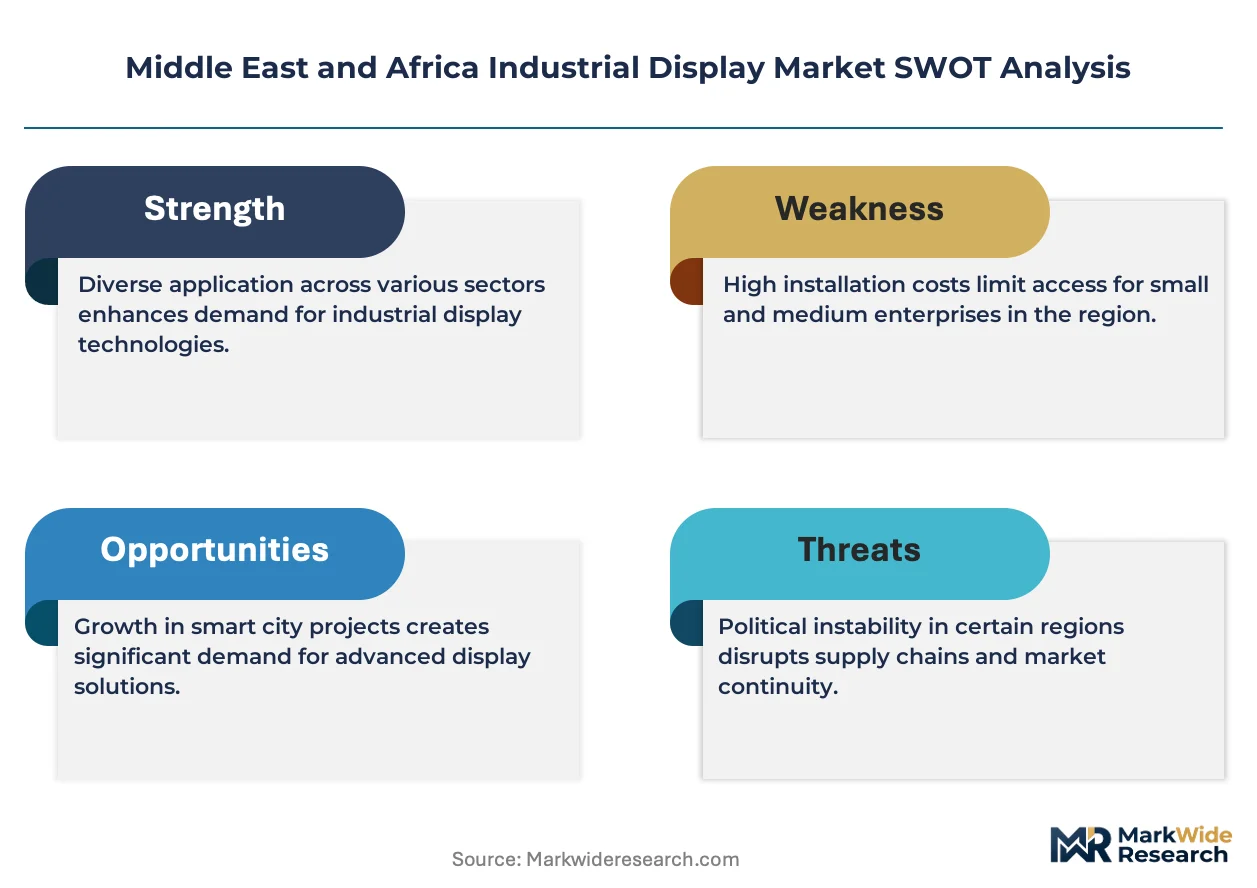
Energy sector procurement is shifting toward ruggedized displays for upstream monitoring and downstream process control. Siemens AG anchors its position through deep channel relationships with Middle Eastern petrochemical operators. Samsung Electronics Co., Ltd. competes aggressively on panel supply scale across African mining automation projects. Advantech Co., Ltd. specializes in embedded computing-integrated display platforms for harsh-environment deployments.
Middle East and Africa Industrial Display comprises hardened visual interface hardware engineered to operate across temperature extremes from -20°C to 70°C, with IP65 ingress protection and sustained luminance above 1000 cd/m² for outdoor readability in high-ambient desert conditions. LCD panels dominate installed manufacturing floors due to proven supply chain availability and cost structure, while OLED displays capture premium positioning in medical imaging and control room visualization where contrast ratio and color accuracy command technical priority. Touchscreen interfaces across transportation and retail applications represent the fastest-expanding interaction modality as operators eliminate mechanical input redundancy.
Saudi Arabia's SFDA and the UAE's MOHAP enforce electromagnetic compatibility and safety certifications that shape product qualification pathways for healthcare-industrial crossover displays. South Africa's central standards body and Egypt's industrial quality regulator mandate localized testing protocols that extend market access timelines for imported equipment. Stakeholders must weigh certification portfolio breadth against the concentration of demand in Gulf state megaprojects and East African logistics corridors.
Market Dynamics
The transition from mechanical control interfaces to fully integrated touchscreen HMI systems is compressing replacement cycles across Middle Eastern petrochemical facilities and African mining operations. This shift demands simultaneous hardware upgrades and cybersecurity certification compliance.
Growth Catalysts
- SFDA Electromagnetic Compatibility Mandates:Saudi Arabia's medical device safety standards are forcing healthcare-industrial crossover display upgrades in diagnostic equipment manufacturing.
- UAE Smart Manufacturing Zones:Abu Dhabi and Dubai industrial parks are specifying IP65-rated outdoor displays for logistics automation and port operations.
- Edge Computing Integration:Real-time data visualization requirements at remote oil wellheads are pulling ruggedized panel PCs with embedded processing into upstream energy deployments.
Market Restraints
- LCD Panel Supply Concentration:Display module sourcing remains concentrated among East Asian substrate manufacturers, exposing African integrators to extended lead times.
- Localized Testing Protocols:South Africa's central standards body mandates in-country electromagnetic testing that adds 8-14 weeks to product registration timelines.
- Project Finance Volatility:Large-scale Saudi giga-project payment cycles create working capital strain for display system integrators.
Strategic Opportunities
- East African Logistics Corridors:Kenya and Ethiopia freight rail modernization programs require rugged wayside displays for trackside monitoring infrastructure.
- MOHAP Certification Pathways:UAE healthcare regulator streamlined approval processes create faster market entry for medical-grade industrial displays.
- OLED-Convergence in Control Rooms:Command center visualization is absorbing broadcast-grade OLED panels for high-contrast process monitoring applications.
Industry Challenges
- IEC 62443 Cybersecurity Skill Gap:Industrial automation security certification expertise remains scarce across Gulf state system integrators.
- Legacy RS-232 Integration Friction:Brownfield manufacturing floors in Egypt and Nigeria require protocol bridging hardware that complicates touchscreen retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Industrial Display Market |
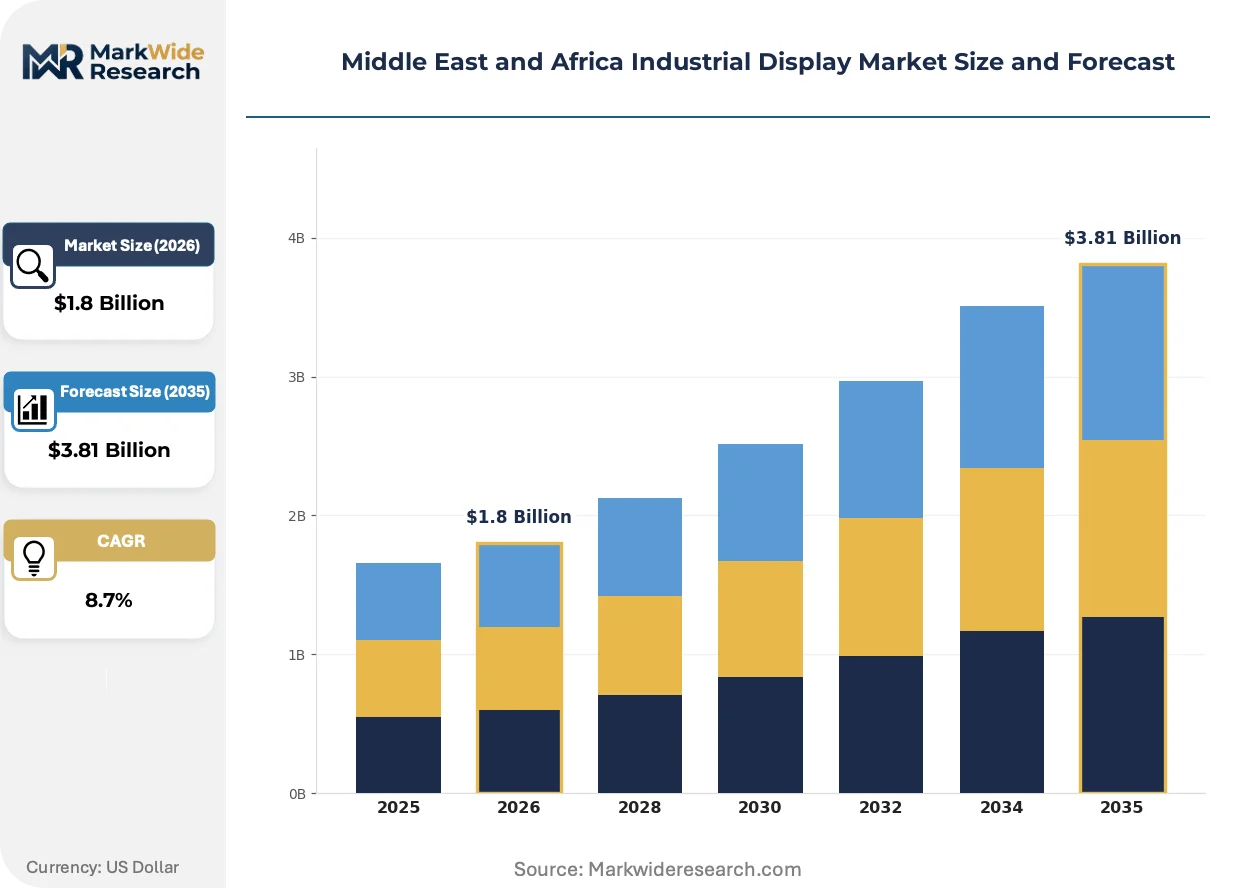
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Touchscreen Application: Manufacturing, Transportation, Healthcare, Retail End User: OEMs, System Integrators, Distributors, End Users Technology: Analog, Digital, Wireless, Embedded |
| Companies Covered | Sharp Corporation, Panasonic Holdings Corporation, Samsung Electronics Co., Ltd., Winmate Taiwan, Japan Display Inc., Siemens AG, LG Display Co., Ltd., Innolux Corporation, Advantech Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Industrial Display Market Shifts & Advancements
Display interface architecture is pivoting from passive visualization to active edge-computing nodes capable of local analytics processing. This transformation is reshaping supplier value propositions and buyer technical specifications simultaneously.
Optical bonding technology is electrifying outdoor display durability in desert environments. The process eliminates air gaps between cover glass and LCD cells, eliminating condensation failures in Saudi Aramco upstream monitoring stations. Petrochemical operators are specifying optically bonded panels for 70°C ambient tolerance, compressing field failure rates and extending replacement intervals.
South Africa's adoption of IEC 62443 cybersecurity standards is mandating secure boot capabilities and encrypted firmware updates for industrial displays. The regulation forces hardware architecture redesigns that add cost but enable insurance premium reductions for certified deployments. Mining automation projects in the Platinum Belt are prioritizing displays with built-in hardware security modules to accelerate compliance.
Energy sector buyers are consolidating procurement through framework agreements with single-source system integrators. This pattern displaces component-level purchasing that previously allowed display specification flexibility. Saudi giga-project developers are bundling display requirements into EPC contracts, concentrating volume with integrators holding SFDA and MOHAP certification portfolios.
Middle East and Africa Industrial Display Market Segmentation
Industrial display procurement across the Middle East and Africa stratifies sharply by environmental tolerance requirements and integration complexity. Buyers in Saudi petrochemical corridors and South African mining belts prioritize fundamentally different specification bundles than healthcare operators in Dubai or retail deployers in Nairobi.
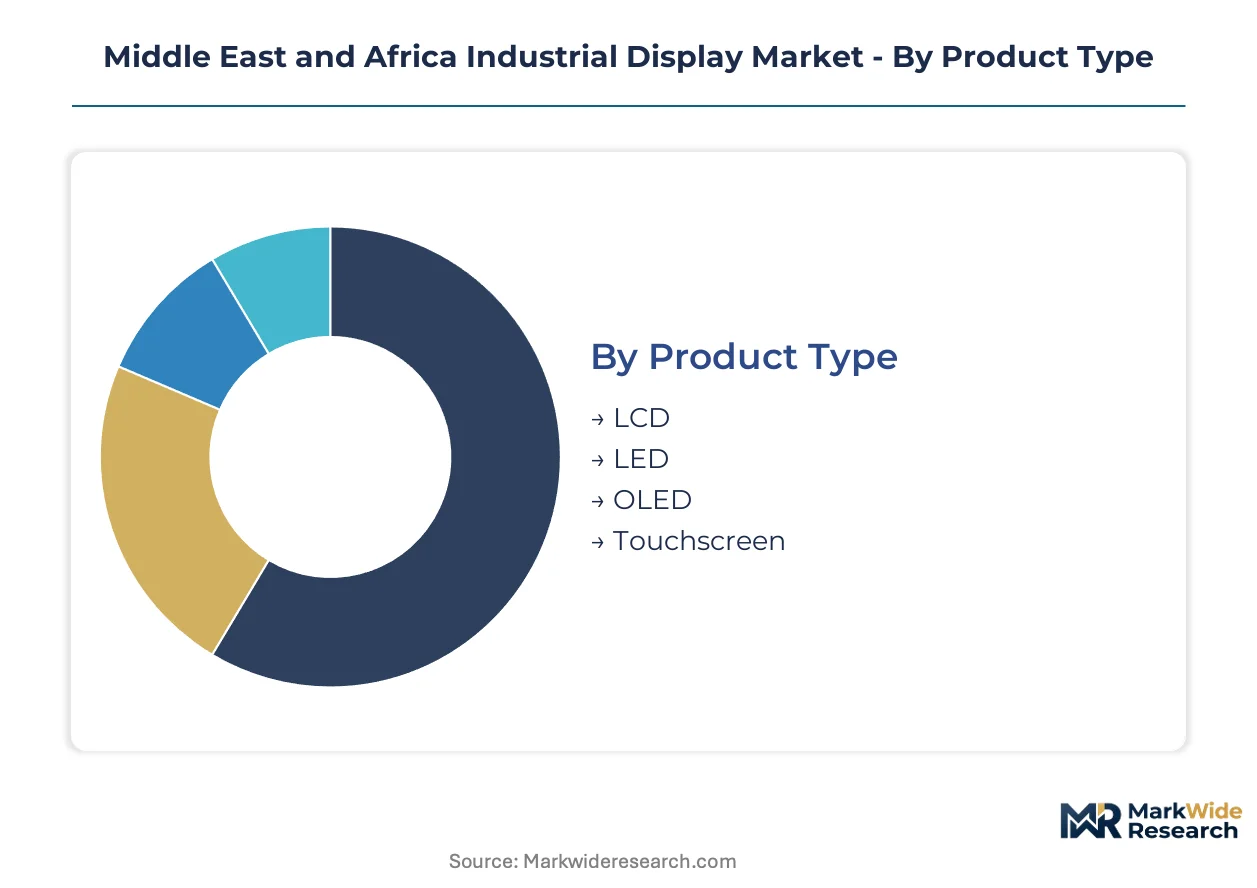
Product Type:
Capital expenditure tolerance and ambient operating conditions determine panel technology selection across GCC energy infrastructure and East African logistics networks.
- LCD:Dominates installed manufacturing floors due to proven supply chain availability and cost structure. Demand concentrates in Egypt's textile automation sector and Nigeria's food processing plants where replacement cycles favor proven reliability over performance premiums.
- Touchscreen:Interfaces across transportation and retail applications are climbing the fastest as operators eliminate mechanical input redundancy. Kenya's freight rail modernization and UAE port automation specify projected-capacitive touch for glove-compatible operation in dusty environments.
- LED:High-brightness direct-view configurations serve outdoor digital signage and wayside monitoring along Saudi giga-project construction corridors.
- OLED:Broadcast-grade panels capture premium positioning in medical imaging and control room visualization where contrast ratio and color accuracy command technical priority.
LCD leads on scale; Touchscreen leads on momentum.
Application:
Regulatory certification requirements fragment demand patterns across verticals, with healthcare and energy commanding divergent compliance portfolios.
- Manufacturing:Hardened visual interfaces engineered for temperature extremes from -20°C to 70°C serve Saudi Aramco upstream monitoring stations and South African Platinum Belt automation. SFDA electromagnetic compatibility mandates force hardware architecture redesigns in diagnostic equipment manufacturing.
- Transportation:Rugged wayside displays for trackside monitoring infrastructure are gaining share fastest along Kenya and Ethiopia freight rail corridors. Optical bonding technology eliminates condensation failures in high-ambient desert conditions.
- Healthcare:Crossover displays must satisfy both MOHAP streamlined approval processes and industrial durability specifications for UAE medical device manufacturing.
- Retail:IP65-rated outdoor displays serve logistics automation and port operations in Abu Dhabi and Dubai industrial parks.
Manufacturing commands volume concentration; Transportation shows steepest expansion trajectory.
End User:
Procurement consolidation through framework agreements is reshaping channel relationships across the value chain.
- System Integrators:Saudi giga-project developers bundle display requirements into EPC contracts, concentrating volume with integrators holding SFDA and MOHAP certification portfolios. IEC 62443 cybersecurity skill gaps remain scarce across Gulf state implementation teams.
- OEMs:Deep channel relationships with Middle Eastern petrochemical operators anchor panel supply commitments. Display module sourcing concentration among East Asian substrate manufacturers exposes African integrators to extended lead times.
- Distributors:Localized testing protocols in South Africa and Egypt extend market access timelines for imported equipment through central standards body mandates.
- End Users:Direct procurement patterns concentrate in UAE smart manufacturing zones specifying outdoor readability above 1000 cd/m² for desert conditions.
System Integrators capture contract consolidation; OEMs retain specification influence.
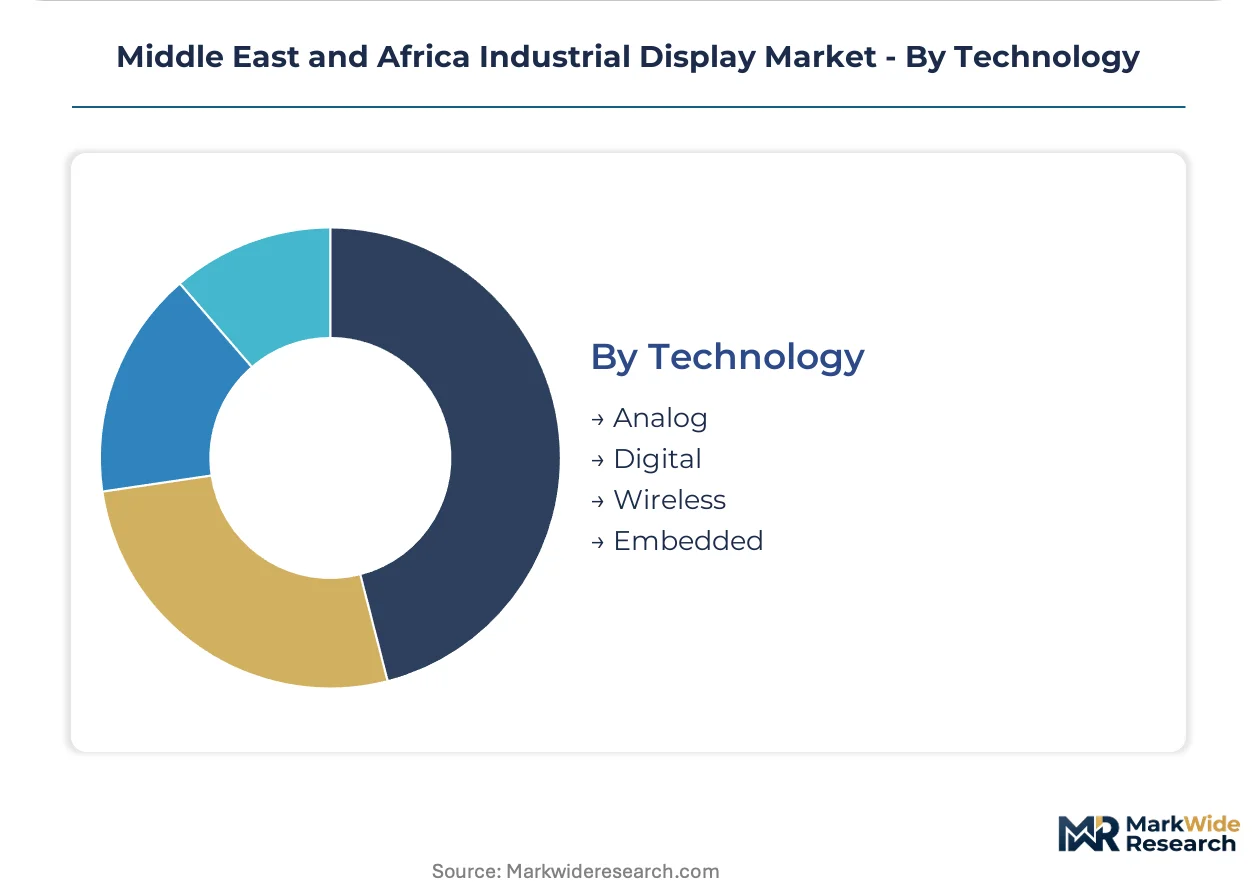
Technology:
Interface architecture pivots from passive visualization toward active edge-computing nodes capable of local analytics processing.
- Embedded:Ruggedized panel PCs with integrated processing serve real-time data visualization at remote oil wellheads. Edge computing requirements pull embedded platforms into upstream energy deployments across Kuwait and Qatar.
- Digital:Secure boot capabilities and encrypted firmware updates satisfy South Africa's IEC 62443 adoption, enabling insurance premium reductions for certified mining automation displays.
- Wireless:Protocol bridging hardware complicates touchscreen retrofits on brownfield manufacturing floors in Egypt and Nigeria with legacy RS-232 integration friction.
- Analog:Remaining installed base in aging industrial infrastructure requires replacement cycle management as digital transition accelerates.
Embedded leads technical specification; Digital leads compliance-driven replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling display procurement toward jurisdictions with streamlined certification pathways. SFDA and MOHAP compliance costs in the Gulf are lower than European equivalents, concentrating healthcare-industrial crossover manufacturing in Saudi Arabia and the UAE.
Saudi Arabia
Upstream oil monitoring and giga-project industrial automation drive ruggedized display demand. SFDA electromagnetic compatibility mandates force hardware redesigns in diagnostic equipment manufacturing. NEOM and the Eastern Province industrial cities specify IP65-rated outdoor panels for desert construction corridors.
United Arab Emirates
Smart manufacturing zones in Abu Dhabi and Dubai require logistics automation displays with 1000 cd/m² luminance for port operations. MOHAP streamlined approval processes accelerate market entry for medical-grade industrial displays. Jebel Ali industrial clusters concentrate procurement through framework agreements with certified system integrators.
South Africa
Platinum Belt mining automation prioritizes displays with hardware security modules for IEC 62443 compliance. The central standards body mandates in-country electromagnetic testing that extends product registration timelines. Johannesburg and Rustenburg industrial corridors absorb the bulk of cybersecurity-certified panel deployments.
Egypt
Brownfield textile and food processing automation drives LCD replacement cycles favoring proven reliability. The industrial quality regulator enforces localized testing protocols that delay imported equipment market access. Cairo and Alexandria manufacturing belts require protocol bridging hardware for legacy RS-232 integration.
Kenya
Freight rail modernization programs specify rugged wayside displays for trackside monitoring infrastructure. East African logistics corridors demand glove-compatible projected-capacitive touch interfaces in dusty environments. Nairobi and Mombasa transport hubs anchor regional procurement for transportation-grade panels.
Middle East and Africa Industrial Display Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: diversified electronics conglomerates with captive panel supply, industrial automation specialists with embedded computing integration, and regional system integrators holding certification portfolios. Competitive moves concentrate on EPC contract bundling and cybersecurity certification pre-positioning.
Among East Asian panel suppliers, Sharp Corporation and Samsung Electronics Co., Ltd. occupy positions defined by substrate manufacturing scale and supply chain reach. Siemens AG anchors the industrial automation tier through channel relationships with Middle Eastern petrochemical operators. Advantech Co., Ltd. exemplifies the embedded computing-integrated display archetype for harsh-environment deployments.
| Leading Market Players |
|---|
| Sharp Corporation |
| Panasonic Holdings Corporation |
| Samsung Electronics Co., Ltd. |
| Winmate Taiwan |
| Japan Display Inc. |
| Siemens AG |
| LG Display Co., Ltd. |
| Innolux Corporation |
| Advantech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Embedded firmware engineers concentrated in Shenzhen and Taipei command wage premiums that compress margins on entry-level industrial display tiers while widening spreads between economy and premium product lines. Labor-cost differentials between East Asian design centers and Gulf state integration facilities shape three-tier pricing architectures across certification grades.
Pricing Analysis
Distributor margins of 15-25% on standard LCD modules widen to 35-45% on IEC 62443-certified panels with embedded security modules. Pricing stratifies across SFDA medical-grade, IP65 industrial-rugged, and economy replacement tiers based on certification burden and optical bonding processing. Cost compression in economy LCD tiers intensifies as Egyptian and Nigerian buyers prioritize proven reliability over performance premiums. System integrators in Saudi giga-projects show least price sensitivity due to bundled EPC contracting, while African mining distributors exhibit highest sensitivity to panel module fluctuations.
Supply Chain Analysis
Refurbishment flows for failed outdoor displays in Saudi Aramco upstream stations and South African Platinum Belt operations create secondary supply channels that compete with new module sales. Display substrate manufacturing concentrates in South Korea, Taiwan, and Japan, with panel bonding and ruggedization finishing in Malaysia and Vietnam. Glass substrate and driver IC dependencies draw from concentrated East Asian chemical and semiconductor suppliers. Single-source vulnerability in polarizer film supply exposes African integrators to allocation risk during demand surges. Distribution runs through Dubai-based regional hubs serving Gulf state megaprojects and Johannesburg channels feeding sub-Saharan mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SFDA electromagnetic compatibility mandates and South Africa's IEC 62443 adoption force recurring hardware refresh cycles that sustain replacement demand independent of macro conditions.
For Market Incumbents: To counter margin compression from East Asian panel oversupply, Siemens AG and Advantech Co., Ltd. should deepen captive supply relationships with MOHAP-certified Gulf state system integrators while accelerating hardware security module integration to capture IEC 62443 premium pricing in South African mining automation. For New Entrants and Emerging Players: MOHAP streamlined approval processes in the UAE open a window for medical-grade industrial display specialists to establish beachheads in Dubai's Jebel Ali industrial clusters before SFDA compliance costs rise in Saudi Arabia. Target East African logistics corridors in Kenya and Ethiopia where freight rail modernization demands glove-compatible projected-capacitive touch interfaces with minimal incumbent saturation. For Investors and Strategic Acquirers: Industrial automation conglomerates with captive petrochemical channel relationships are the most active acquirer in this space, seeking embedded computing-integrated display platforms to round out edge-computing portfolios. Acquisition targets should display IEC 62443 certification pre-positioning and MOHAP/SFDA regulatory dossiers. Practitioners should monitor Saudi giga-project payment cycle stress and East Asian substrate allocation announcements as early inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Pre-Positioning | Enables insurance premium reductions for South African Platinum Belt mining automation deployments. |
| Optical Bonding Capacity Expansion | Eliminates condensation failures in Saudi Aramco upstream monitoring stations operating at 70°C ambient. |
| MOHAP Regulatory Dossier Investment | Accelerates market entry for medical-grade displays in Dubai smart manufacturing zones. |
| Embedded Panel PC Platform Integration | Satisfies real-time data visualization requirements at remote Kuwait and Qatar oil wellheads. |
| East African Distribution Channel Partnership | Captures Kenya and Ethiopia freight rail modernization procurement for rugged wayside displays. |
Research Methodology
Multiple input streams — technical specification audits of SFDA and MOHAP certification pathways, procurement pattern analysis from Saudi giga-project EPC contracts, and field validation with industrial automation system integrators — were reconciled against secondary trade data and regulatory filing repositories. Primary interviews with display module procurement leads at Middle Eastern petrochemical operators, cybersecurity compliance officers at South African mining automation firms, and channel managers at Dubai-based distribution hubs informed demand-side calibration. Secondary sources included customs records for LCD and OLED panel imports, IEC 62443 adoption tracking from South Africa's central standards body, and hospital procurement databases for healthcare-industrial crossover applications. Bottom-up unit shipment estimates and top-down value triangulation were cross-validated across the analysis window.
Historical shipment trajectories were cross-referenced against panel input from display substrate manufacturers and ruggedization finishers to anchor projection assumptions. Segmentation modeling spanned panel technology, application vertical, end-user procurement channel, and integration complexity tiers across the projection horizon. CAGRs were derived from regression analysis of replacement cycle compression rates and regulatory mandate phase-in schedules. Industry-specific forecast inputs included Saudi Aramco digital control room expansion timelines and Kenya Railways Authority freight modernization procurement phases.
Revisions become necessary when SFDA or MOHAP regulatory timelines shift, East Asian substrate allocation disruptions materialize, or Saudi giga-project payment cycles extend beyond contracted terms. Practitioners should monitor IEC 62443 certification backlog durations at South Africa's central standards body and polarizer film supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Video Wall Display Market
Display Technologies
8K Display Resolution Market
Display Technologies
Laptop Panels Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Field Emission Display Market
Display Technologies
3LCD Projector Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Foldable Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Smart Display Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
4K Technology Market
Display Technologies
Next Generation 3D Display Market