
 Electroluminescent Display Market | 2026-2036
Electroluminescent Display Market Size, Share, and Industry Trends Forecast 2026-2036
Electroluminescent Display Market Analysis
The gap between thin-film electroluminescent manufacturing and organic LED alternatives is narrowing as phosphor efficiency improves and deposition costs decline. Sharp Corporation leverages its legacy in LCD-to-EL process migration to sustain competitive manufacturing scale in Japanese production facilities. Panasonic Corporation anchors its position through specialized ruggedized displays for industrial and military applications where brightness stability under temperature extremes differentiates product performance.
Electroluminescent displays emit light through phosphor excitation by an electric field across a thin dielectric layer, typically operating at 100-200 volts alternating current with luminance ranging from 30 to 150 cd/m² depending on phosphor composition and drive frequency. These displays serve critical visibility functions in low-light environments where power efficiency and wide viewing angles outweigh color gamut requirements. Passive matrix configurations dominate current shipment volumes due to simpler driver electronics and lower unit costs, while transparent displays capture expanding interest from automotive HUD integrators seeking windshield-embedded information projection. Thin-film technology leads manufacturing throughput, though quantum-dot-enhanced phosphors represent the fastest-growing research frontier for color purity improvement.
FCC certification governs electromagnetic emissions from AC-driven EL panels in the United States, while REACH and RoHS frameworks in Europe restrict cadmium and lead content in phosphor formulations, directly shaping material substitution timelines for manufacturers. Japan's METI energy efficiency standards and China's GB display performance specifications create divergent compliance pathways that fragment product platform strategies. Stakeholders must monitor phosphor material supply concentration and evolving automotive safety display mandates to align capacity investments with qualification requirements.
Market Dynamics
Automotive electrification is compressing qualification timelines for instrument cluster displays as OEMs consolidate supplier bases around dual-source thin-film strategies. Phosphor deposition capacity concentration in East Asian manufacturing clusters is forcing Western integrators into longer-term offtake arrangements to secure supply continuity.
Growth Catalysts
- REACH RoHS material mandates:European restrictions on cadmium-based phosphors are accelerating substitution toward europium-doped alkaline earth thiogallate formulations with higher luminous efficiency.
- Head-up display integration:Automotive HUD systems are absorbing transparent electroluminescent panels for windshield-embedded speed and navigation projection in premium vehicle segments.
- Thin-film deposition scaling:China, Japan, and South Korea concentrate over seventy percent of active-matrix backplane capacity, enabling cost compression for high-brightness industrial panels.
Market Restraints
- AC drive electronics cost structure:High-voltage inverter components for 100-200V operation add fifteen to twenty percent BOM overhead versus DC-driven alternatives.
- Phosphor supply concentration:Rare-earth activator sourcing depends on Chinese separation and refining infrastructure, exposing non-domestic fabricators to export quota volatility.
- Color gamut limitation:Standard zinc sulfide phosphor systems achieve narrow spectral output that restricts application in full-color consumer displays.
Strategic Opportunities
- Quantum-dot phosphor enhancement:Colloidal quantum dot integration with traditional inorganic hosts is opening pathways to saturated red and green emission without rare-earth dependency.
- Ruggedized industrial retrofit:Mining, oil and gas, and defense sectors are replacing failing LCD installations with solid-state EL alternatives rated for minus forty to plus eighty-five degree Celsius operation.
- NHTSA safety display mandates:Proposed federal motor vehicle safety standards for backup camera and blind-spot visualization are expanding addressable automotive surface area for low-power illumination.
Industry Challenges
- Thin-film process engineering talent:Vacuum deposition and dielectric optimization expertise resides predominantly with legacy Japanese and Korean equipment vendors, constraining new entrant scale-up.
- FCC Part 15 certification timelines:Electromagnetic interference testing for AC-driven panels extends qualification cycles by four to six months versus DC alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroluminescent Display Market |
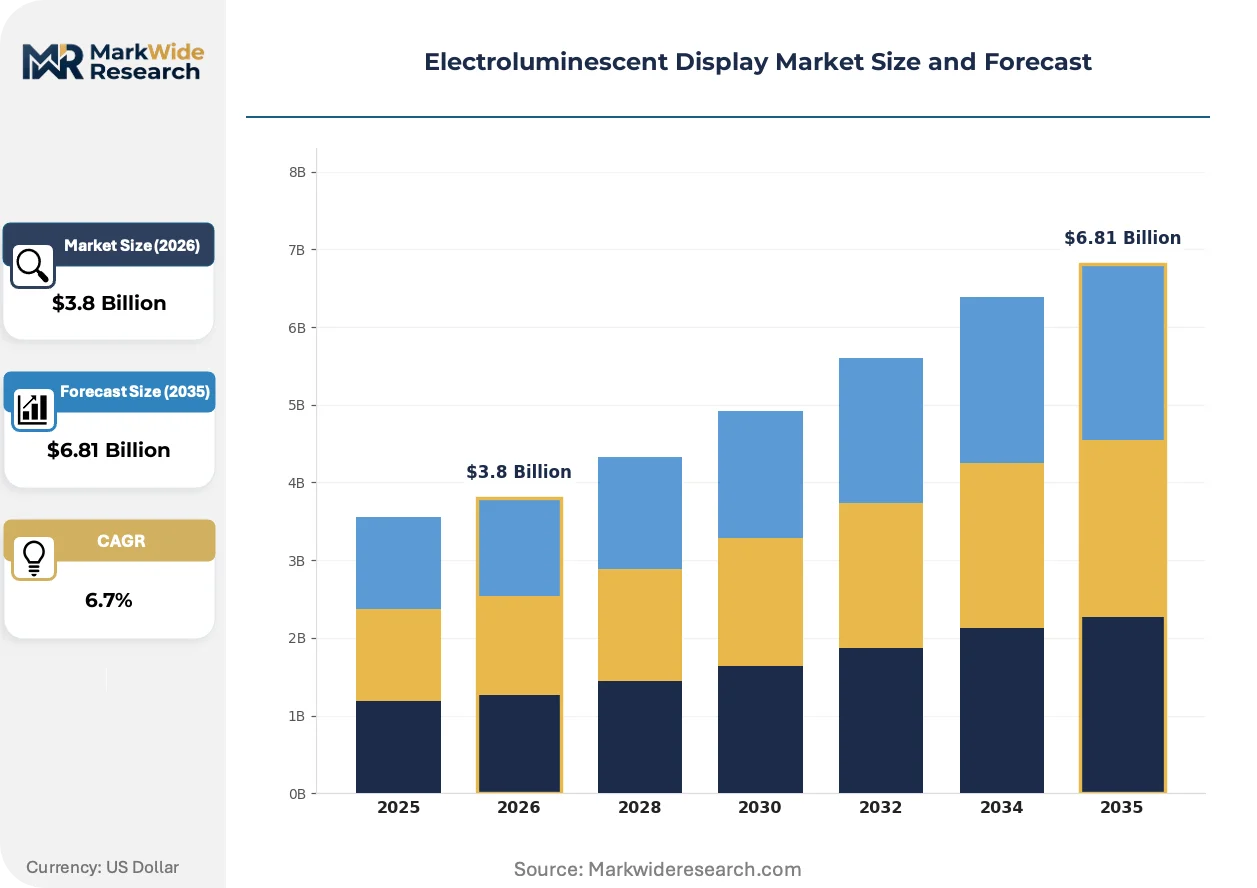
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Matrix, Active Matrix, Transparent Displays, Flexible Displays Technology: Thin Film, Inorganic, Organic, Quantum Dot Application: Consumer Electronics, Automotive, Industrial, Healthcare End User: OEMs, Retailers, Manufacturers, Distributors |
| Companies Covered | Lumineq, Planar Systems, Sharp Corporation, Japan Display Inc., Sony Corporation, Panasonic Corporation, Nejilock Technology Pte Ltd, Orbit Electronics Group, iFire Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroluminescent Display Market Emerging Trajectories
Phosphor efficiency breakthroughs and deposition automation are compressing the historical performance gap between electroluminescent systems and organic LED alternatives. Three developments are restructuring competitive positioning and procurement patterns.
Quantum-dot-enhanced phosphor systems are collapsing the luminance efficiency deficit that previously relegated EL technology to low-information-content applications. Automotive HUD integrators are piloting these formulations for daylight-readable windshield projection. The technology is collapsing price premiums for color-saturated transparent displays.
REACH Annex XVII restrictions on cadmium content are forcing reformulation of green-emitting phosphor systems across European supply chains. Manufacturers are qualifying copper-activated zinc sulfide alternatives with modified drive frequency compensation. Industrial and medical display segments in Germany, France, and the Netherlands are absorbing qualification costs fastest.
Fleet operators and defense procurement agencies are consolidating vendor relationships around performance-based specifications rather than component-level sourcing. System integrators are capturing margin previously held by discrete display suppliers. North American military and heavy equipment verticals are driving this consolidation through multi-year sustainment contracts.
Electroluminescent Display Market Segmentation
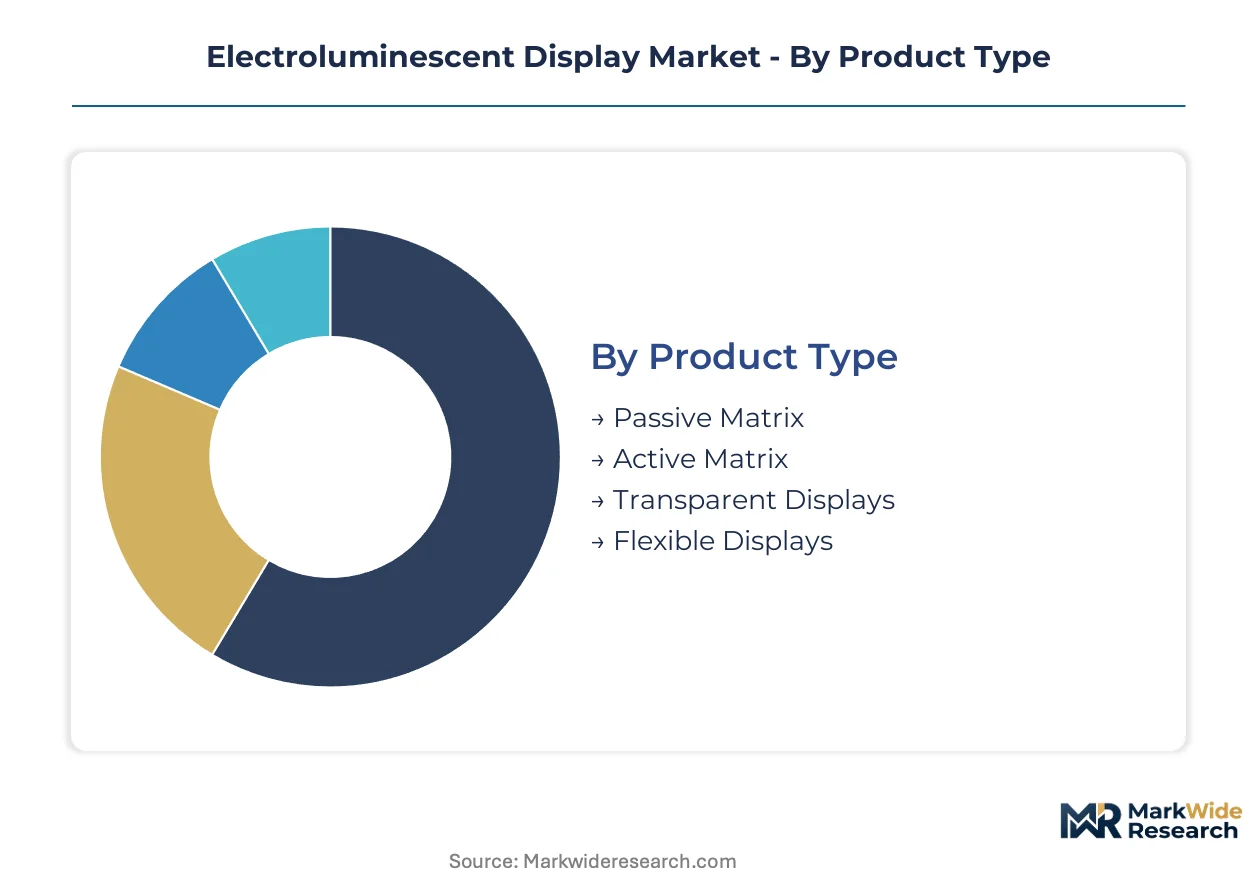
Segmentation in electroluminescent displays separates high-volume automotive instrument clusters from specialized industrial units with radically different qualification cycles. Procurement patterns diverge sharply between consumer electronics with 18-month refresh rates and defense applications demanding decade-long sustainment commitments.
Product Type:
Passive matrix panels turn inventory fastest with standardized driver electronics, while transparent displays face extended automotive qualification timelines stretching 24-36 months.
- Passive Matrix:Simpler row-column addressing with external driver ICs keeps unit costs lowest for basic alphanumeric and icon-based readouts. Automotive instrument clusters in Japan and Germany absorb the highest shipment volumes as OEMs consolidate around dual-source thin-film strategies.
- Active Matrix:Integrated thin-film transistor backplanes enable higher information density and faster refresh for complex graphics. Industrial human-machine interfaces in South Korean smart factories and German automation lines are where expansion concentrates as legacy LCD retrofits accelerate.
- Transparent Displays:Partial transparency suits head-up projection and architectural integration. Automotive HUD pilots in premium German and Japanese vehicle segments are absorbing qualification costs despite luminance challenges under direct sunlight.
- Flexible Displays:Polyimide or thin-glass substrates enable curved mounting surfaces. Wearable prototypes in Japanese consumer electronics labs and medical patch concepts in Swiss healthcare device development represent the primary demand concentration.
Passive matrix dominates installed base. Active matrix is where expansion concentrates.
Technology:
Cost tiers separate mature deposition methods from quantum-dot formulations commanding research premiums.
- Thin Film:Vacuum-deposited dielectric and phosphor layers on glass or ceramic substrates constitute the manufacturing mainstream. Chinese, Japanese, and South Korean fabrication clusters control over seventy percent of active capacity, forcing Western integrators into longer-term offtake arrangements.
- Inorganic:Traditional zinc sulfide and alkaline earth thiogallate phosphors with rare-earth activators deliver proven brightness stability. REACH Annex XVII cadmium restrictions are accelerating europium-doped green phosphor reformulation across European supply chains.
- Organic:Hybrid organic-inorganic approaches remain experimental with limited commercial traction. Japanese materials laboratories and Korean display research consortia hold the primary patent positions.
- Quantum Dot:Colloidal nanocrystal integration with inorganic hosts collapses the color gamut deficit versus organic LED alternatives. Automotive HUD integrators in Germany and Japan are piloting these formulations for daylight-readable windshield projection.
Thin film commands production volume. Quantum dot is climbing the fastest.
Application:
Customer type separates specification-driven automotive procurement from price-sensitive consumer electronics.
- Consumer Electronics:Clocks, toys, and novelty lighting with basic visibility requirements. Chinese manufacturing clusters dominate this segment with compressed margins and rapid product cycles.
- Automotive:Instrument clusters, climate controls, and emerging HUD systems where NHTSA safety display mandates are expanding addressable surface area. German and Japanese OEMs are consolidating supplier bases around performance-based specifications.
- Industrial:Mining, oil and gas, and manufacturing equipment rated for minus forty to plus eighty-five degree Celsius operation. North American military and heavy equipment verticals are driving vendor consolidation through multi-year sustainment contracts.
- Healthcare:Medical devices and diagnostic equipment where electromagnetic emissions must meet IEC 60601-1-2 standards. Swiss and German medical device manufacturers represent the most stringent qualification requirements.
Automotive commands revenue concentration. Industrial is gaining share fastest.
End User:
Supply chain position determines whether procurement emphasizes component specifications or system integration capabilities.
- OEMs:Vehicle manufacturers, medical device builders, and industrial equipment makers with direct display integration. German automotive OEMs and Japanese electronics manufacturers maintain the most sophisticated incoming inspection protocols.
- Retailers:Limited presence given the technical nature of EL display procurement. Specialty electronics distributors in the United States and Germany serve hobbyist and replacement markets.
- Manufacturers:Contract electronics manufacturers and display module builders purchasing phosphor and backplane components. Chinese and South Korean contract manufacturers are capturing margin through vertical integration into driver electronics.
- Distributors:Industrial and military supply channels with long-term sustainment obligations. North American defense procurement agencies are consolidating relationships around performance specifications rather than component-level sourcing.
OEMs dominate direct procurement. Distributors are where sustainment revenue concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese electronics manufacturers concentrate the most sophisticated procurement protocols for thin-film electroluminescent components. Military sustainment contracts in North America and industrial automation retrofits across East Asian manufacturing clusters shape divergent regional demand patterns.
United States
NHTSA safety display mandates for backup cameras and blind-spot visualization expand addressable automotive surface area for low-power EL illumination. FCC Part 15 certification governs electromagnetic emissions from AC-driven panels, extending qualification cycles versus DC alternatives. Detroit-area automotive clusters and Southwest defense contractors anchor the highest concentration of ruggedized industrial procurement.
Germany
Premium vehicle OEMs in Stuttgart and Munich consolidate supplier bases around performance-based specifications for head-up display integration. REACH Annex XVII restrictions on cadmium-based phosphors accelerate reformulation toward europium-doped alkaline earth thiogallate systems. The Eindhoven-to-Dresden corridor hosts the densest concentration of industrial HMI retrofit demand as legacy LCD replacements accelerate.
Japan
METI energy efficiency standards create compliance pathways that diverge from European and North American frameworks, fragmenting product platform strategies. Sharp Corporation and Panasonic Corporation anchor competitive manufacturing scale through legacy LCD-to-EL process migration and specialized ruggedized displays respectively. The Kanto and Kansai industrial belts concentrate over sixty percent of domestic thin-film deposition capacity.
China
GB display performance specifications govern domestic certification requirements for consumer electronics and automotive applications. Chinese separation and refining infrastructure controls rare-earth activator sourcing, exposing non-domestic fabricators to export quota volatility. Yangtze River Delta manufacturing clusters concentrate the majority of active-matrix backplane capacity, enabling cost compression for high-brightness industrial panels.
South Korea
Smart factory automation lines in Gyeonggi Province drive active matrix expansion as legacy LCD retrofits accelerate. MFDS medical device standards and industrial safety regulations shape qualification requirements for healthcare and mining equipment applications. Seoul Capital Area fabrication clusters control significant phosphor deposition capacity, forcing Western integrators into longer-term offtake arrangements.
Electroluminescent Display Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base separates into scale-driven thin-film fabricators, technology-agnostic system integrators, and phosphor-material specialists with captive deposition assets. Dominant competitive moves include strategic partnerships between automotive Tier-1 suppliers and display module builders, plus geographic expansion through qualified supplier status in multiple regulatory jurisdictions.
Among Japanese electronics conglomerates, Sharp Corporation and Panasonic Corporation exemplify divergent strategic archetypes—Sharp occupying the LCD-to-EL process migration position, Panasonic anchoring the ruggedized industrial and military specialization tier. Lumineq represents the transparent display technology specialist archetype, with Finland-based credentials signaling European automotive HUD integration focus. These three companies illustrate how geographic origin and historical manufacturing heritage shape competitive positioning without requiring scale parity.
| Leading Market Players |
|---|
| Lumineq |
| Planar Systems |
| Sharp Corporation |
| Japan Display Inc. |
| Sony Corporation |
| Panasonic Corporation |
| Nejilock Technology Pte Ltd |
| Orbit Electronics Group |
| iFire Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Rare-earth activator sourcing from Chinese separation and refining infrastructure concentrates upstream margin capture with domestic fabricators, forcing Western display integrators into longer-term offtake arrangements that transfer pricing power downstream to automotive OEMs and defense procurement agencies with consolidated vendor relationships.
Pricing Analysis
Long-term offtake contracts with rare-earth indexation dominate procurement between phosphor material suppliers and display fabricators. Price differentiation separates REACH-compliant europium-doped formulations from legacy cadmium-activated systems in European supply chains. Cost compression in passive matrix panels is intensifying as Chinese contract manufacturers expand thin-film deposition capacity. Consumer electronics buyers exhibit highest price sensitivity, while military sustainment contracts show lowest sensitivity due to decade-long qualification requirements.
Supply Chain Analysis
Chinese, Japanese, and South Korean electronics manufacturing services hold over seventy percent of active-matrix backplane fabrication capacity. Phosphor deposition draws from zinc sulfide raw material feedstock and rare-earth activator supplies concentrated in Chinese refining infrastructure. Single-source vulnerability in europium and terbium separation exposes non-domestic fabricators to export quota volatility. Distribution runs through direct OEM procurement for automotive and industrial segments, with specialty distributors serving replacement and defense sustainment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroluminescent display manufacturing represents a defensive-moat market where regulatory entrenchment through multi-year automotive qualification cycles creates substantial switching costs that protect incumbent positions from displacement.
For Market Incumbents: Insulate market position by deepening backward integration into phosphor material supply through captive rare-earth offtake arrangements in Chinese and South Korean refining zones. Accelerate quantum-dot phosphor R&D investment to preempt organic LED substitution in head-up display applications. Secure dual-source qualification status with German and Japanese automotive OEMs before NHTSA safety display mandates expand addressable surface area.
For New Entrants and Emerging Players: North American industrial retrofit markets present underpenetration opportunities where legacy LCD replacement demand concentrates in mining and oil and gas verticals with extreme temperature specifications. Target defense sustainment contracts through performance-based specifications rather than component-level bidding. Enter through specialized transparent display integration for automotive HUD pilots where qualification timelines deter established players.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed Japanese display component specialists holding legacy thin-film deposition equipment and METI-certified production lines. Five-to-ten year viability hinges on successful quantum-dot formulation commercialization and automotive HUD adoption velocity. Monitor europium export quota announcements from Chinese regulators as inflection indicator for supply-side margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Dot Phosphor Integration | Automotive HUD integrators in Germany and Japan pilot daylight-readable transparent formulations. |
| Long-term Rare Earth Offtake Agreement | Western fabricators secure europium supply continuity against Chinese export quota volatility. |
| REACH-Compliant Formulation Certification | European automotive OEMs mandate copper-activated zinc sulfide alternatives to cadmium systems. |
| Ruggedized Industrial Retrofit Partnership | North American defense agencies consolidate vendor relationships around minus forty to plus eighty-five Celsius specifications. |
| Dual-Source Automotive Qualification | German and Japanese OEMs thin supplier bases around performance-based thin-film strategies. |
Methodological Framework
Initial hypotheses were tested against primary input from thin-film deposition engineers, automotive Tier 1 procurement managers, phosphor material R&D directors, and defense sustainment contract officers and refined through secondary validation against SEC 10-K filings, METI energy efficiency standard disclosures, REACH Annex XVII regulatory updates, and customs trade data for rare-earth compound flows. Bottom-up phosphor consumption estimates and top-down display shipment projections were triangulated to converge on market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value outputs through segmentation by product type, technology tier, application vertical, and end-user supply chain position. CAGRs were derived from regression analysis of historical automotive instrument cluster adoption and forward projection of NHTSA safety display mandate implementation. Industry-specific forecast inputs included thin-film deposition capacity expansion announcements and quantum-dot phosphor patent filing velocity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese contract manufacturers or breakthrough organic LED cost parity would shift outcomes materially. Quarterly review of europium export quota announcements, automotive HUD pilot program conversions, and FCC Part 15 certification timeline extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Collaboration Display Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Flexible Display Market
Display Technologies
Smart Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
DLP Projector Market
Display Technologies
Global Display Controllers Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Screenless Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Global Embedded Display Market
Display Technologies
Smartphone Display Market
Display Technologies
Display Port Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market