
 Computer Monitor Market | 2026-2036
Computer Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Monitor Market Analysis
Equipment leasing and subscription-based refresh programs is fragmenting procurement power across mid-sized enterprises and educational institutions. Dell Technologies leverages direct-channel financing to sustain institutional account stickiness. Samsung Electronics anchors high-volume panel supply through captive semiconductor and display fabrication. LG Electronics differentiates OLED monitor lines through color-accuracy certification for creative professionals.
A computer monitor is an electronic visual display comprising an LCD, LED, or OLED panel with a dedicated driver board, backlight assembly or self-emissive pixel matrix, and input interface hardware, engineered to render digital video signals for human interaction. Panel type determines luminance uniformity, response time, and power draw, with OLED eliminating backlight layers through per-pixel illumination. Resolution segments reveal 4K as the margin pool for professional and gaming applications, while 1080p occupies volume-driven education and corporate deployments. Screen size stratification shows 27-inch and 32-inch formats gaining share among designers and gamers seeking workspace density without 40-inch spatial requirements.
EPA Energy Star specifications and EU Ecodesign requirements shape minimum efficiency thresholds for backlight and standby power, directly influencing OEM design priorities and market access. FCC electromagnetic emissions standards in the United States and CE marking obligations under EU RoHS and REACH restrict hazardous substance use and recyclability design. Stakeholders must monitor evolving EPEAT criteria and emerging right-to-repair mandates that could alter panel modularity requirements and aftermarket service economics.
Market Dynamics
The computer monitor market pivots on panel technology substitution cycles, where OLED self-emissive architectures are compressing legacy LCD-LED backlight supply chains and reallocating manufacturing investment toward South Korean and Chinese display clusters.
Growth Catalysts
- EU Ecodesign efficiency mandates:Minimum standby power thresholds and luminance uniformity standards are forcing OEM redesigns that favor premium panel tiers, accelerating replacement demand across institutional buyers in Germany and France.
- Enterprise IT refresh normalization:Post-pandemic remote-work infrastructure buildouts have institutionalized hybrid workforce display requirements, sustaining volume procurement across mid-sized enterprises and educational institutions in the United States.
- Per-pixel illumination architectures:OLED technology eliminates backlight assembly layers entirely, reducing power draw and enabling thinner form factors that command margin premiums in professional design and gaming segments.
Market Restraints
- Display driver IC supply concentration:Taiwanese and South Korean foundry capacity constraints for high-resolution timing controllers create input bottlenecks during demand surges, compressing OEM delivery schedules.
- Indium gallium zinc oxide substrate costs:IGZO backplane material volatility for high-refresh-rate panels elevates bill-of-materials exposure for premium-tier manufacturers targeting 240Hz+ gaming specifications.
- EU right-to-repair legislative friction:Emerging mandates for panel modularity and standardized component access threaten aftermarket service economics and current sealed-unit industrial designs.
Strategic Opportunities
- India BIS certification pathway expansion:Domestic manufacturing incentives under the PLI scheme create localized assembly opportunities for entry-level 1080p education and government procurement segments.
- Cloud-gaming endpoint proliferation:Low-latency display requirements for streaming-based gameplay are creating specification pull-through for 144Hz+ panels in markets where discrete GPU ownership lags.
- Subscription-based refresh programs:Equipment-as-a-service financing models fragment capital expenditure into operational budgets, opening mid-market enterprise accounts previously captured by direct purchase cycles.
Industry Challenges
- Color-calibration technician scarcity:Factory-level uniformity tuning for professional-grade OLED lines requires specialized labor pools concentrated in South Korea and Japan, constraining capacity scaling.
- EPEAT criteria evolution tracking:Shifting environmental performance standards across multiple jurisdictions demand continuous compliance monitoring that strains smaller OEM regulatory affairs functions.
- Legacy VGA/HDMI interface support:Maintaining backward compatibility with aging institutional infrastructure extends SKU complexity and inventory carrying costs for commercial-focused product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Monitor Market |
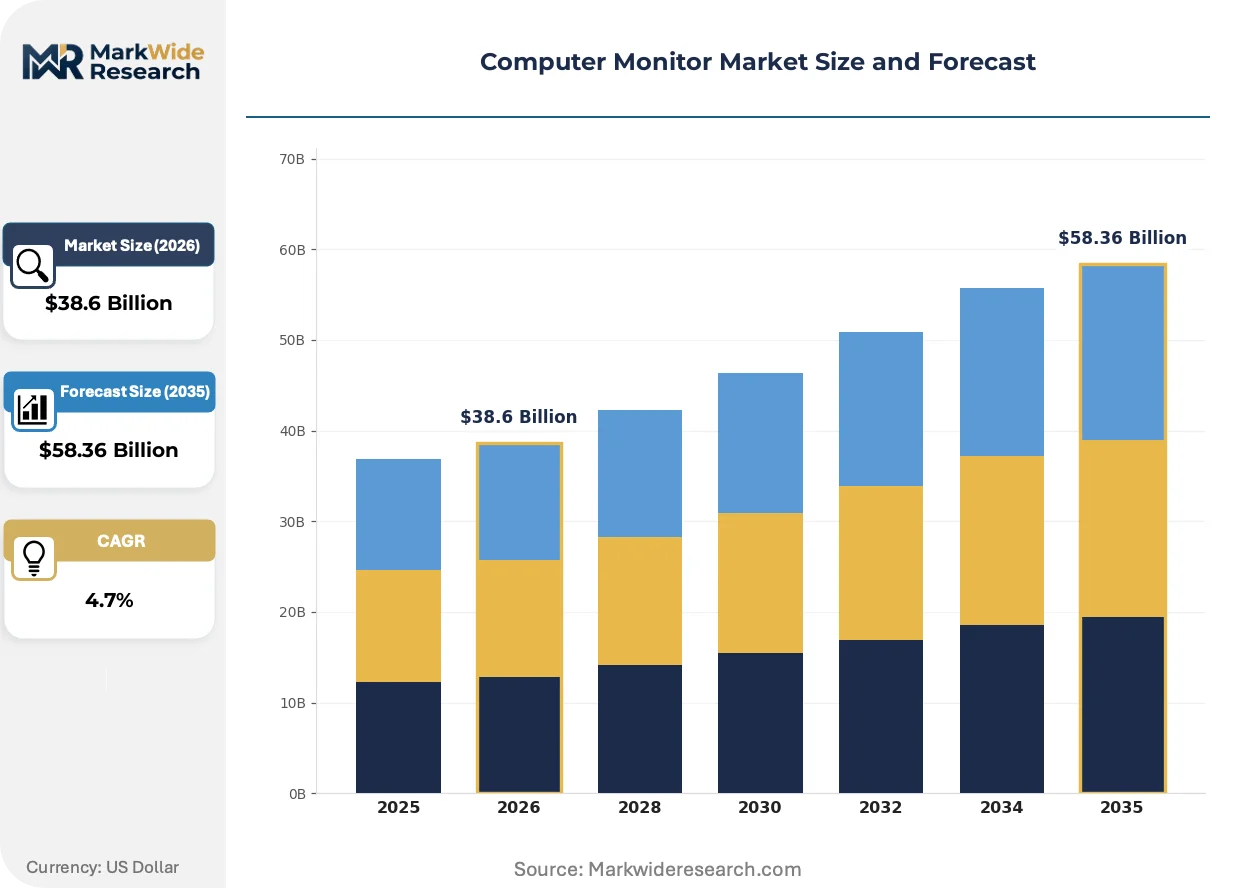
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, LCD, DLP Screen Size: 24 inch, 27 inch, 32 inch, 40 inch Resolution: 1080p, 1440p, 4K, 8K End User: Students, Professionals, Gamers, Designers |
| Companies Covered | Dell Technologies, BenQ, Samsung Electronics, ViewSonic, AOC, LG Electronics, Acer, Gigabyte, ASUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Monitor Market Emerging Trajectories
Panel architecture convergence with semiconductor fabrication methods is dissolving traditional display industry boundaries, while regulatory efficiency mandates and procurement model fragmentation are rewriting competitive rules across price tiers.
Mini-LED local dimming zones are collapsing the luminance control advantage previously exclusive to OLED, enabling LCD-based monitors to approach contrast ratios of 1,000,000:1 through thousands of individually controlled backlight segments. Gaming monitor buyers in China and the United States are adopting these hybrid panels at accelerating rates. The technology is collapsing the price-performance gap that justified OLED premiums for HDR content creators.
EPA Energy Star 8.0 specifications impose stricter active-mode power limits and mandatory on-mode testing protocols that disqualify older backlight designs from federal procurement eligibility. OEMs serving the United States government and education verticals must redesign power management firmware and source more efficient LED drivers. The specification most heavily impacts 27-inch and larger formats where luminance requirements scale nonlinearly with panel area.
Leasing arrangements and refresh-as-a-service contracts are displacing capital purchase cycles among North American and European mid-market enterprises, unbundling hardware ownership from IT infrastructure management. Dell Technologies and channel partners have built captive financing arms to capture recurring revenue streams. This shift concentrates most visibly in healthcare and financial services verticals where compliance-driven replacement schedules align with subscription billing periods.
Computer Monitor Market Segmentation
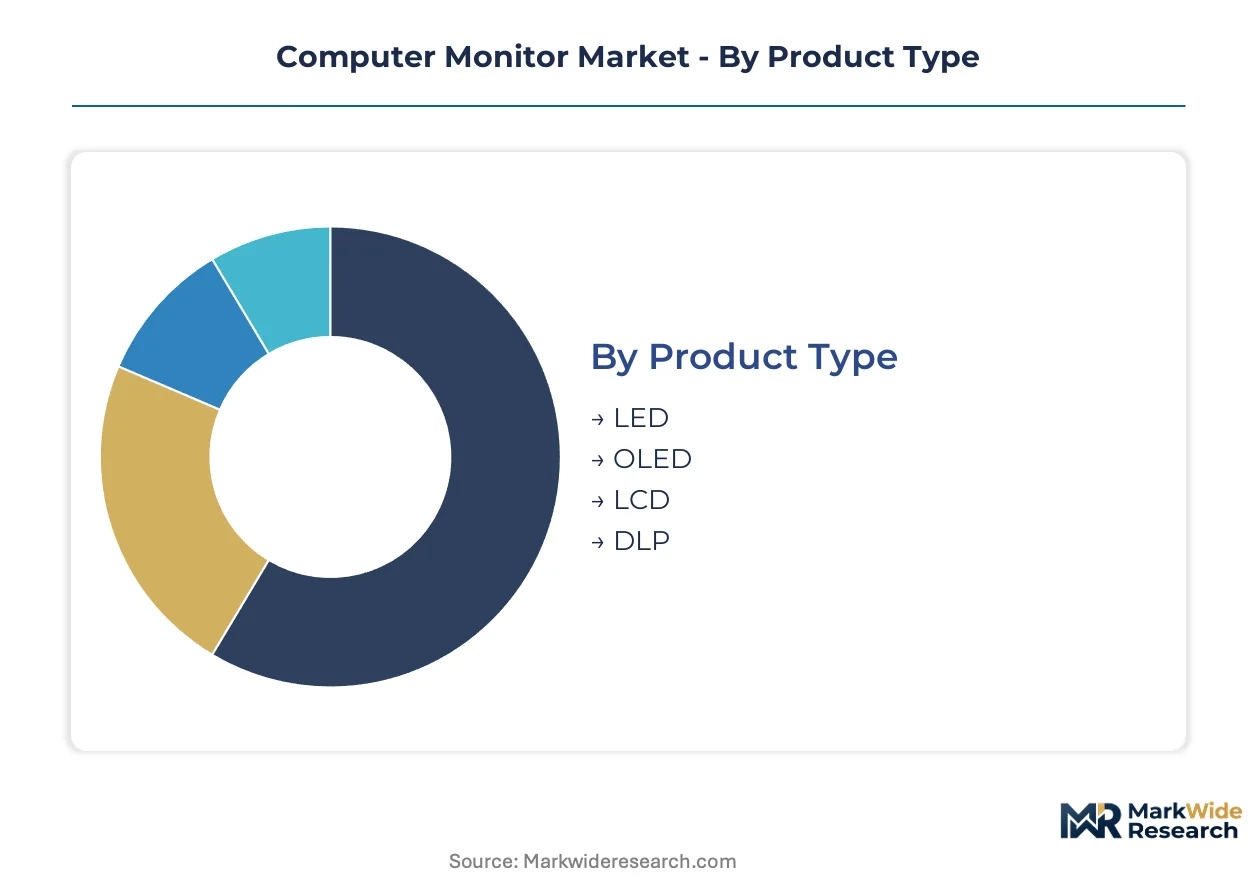
Panel technology and display specifications determine service lifecycle, warranty exposure, and refurbishment economics across the computer monitor market. Segmentation reveals how OLED self-emissive architectures command premium service contracts while LCD volume deployments sustain aftermarket parts networks.
Product Type:
After-sales-service intensity varies sharply by panel architecture, with OLED requiring specialized calibration labor and LCD demanding backlight module replacement programs.
- OLED:Self-emissive pixel matrices eliminate backlight layers entirely, reducing power draw and enabling sub-3mm form factors. Demand concentrates among creative professionals in South Korea and gaming enthusiasts in the United States, where color accuracy and response time justify premium pricing and extended warranty uptake.
- LED:Edge-lit and direct-lit backlight configurations dominate volume manufacturing, with modular driver boards enabling field-replaceable unit strategies. Corporate refresh cycles in Germany and France sustain bulk procurement through leasing programs that bundle preventive maintenance.
- LCD:Twisted nematic and in-plane switching variants anchor education and government segments, with standardized panel interfaces reducing technician training costs for institutional service providers.
- DLP:Digital micromirror device projection monitors serve specialized simulation and command-center applications requiring ultra-large formats beyond flat-panel manufacturing limits.
OLED holds the largest share; momentum sits with LED as Mini-LED local dimming narrows the performance gap.
Screen Size:
Physical dimensions dictate logistics costs, packaging engineering, and installation service requirements across commercial and consumer channels.
- 27 inch:The workspace density sweet spot for hybrid professionals balancing document viewing with video conferencing, with VESA mount standardization reducing deployment labor across United States enterprise rollouts.
- 32 inch:Expanding fastest among designers and financial analysts in China seeking single-display productivity without multi-monitor cable management complexity.
- 24 inch:Compact footprint suits standardized cubicle dimensions and educational computer labs, with high volume enabling aggressive unit economics for budget-constrained institutional buyers.
- 40 inch:Ultrawide and large-format panels target trading floors and content review suites, requiring specialized freight handling and on-site calibration services that elevate total cost of ownership.
27 inch holds the largest share; 32 inch is climbing the fastest as workspace density preferences shift.
Resolution:
Pixel density determines GPU pairing requirements, cable specification, and upgrade pathway complexity for IT administrators managing heterogeneous fleets.
- 4K:UHD panels at 3840×2160 anchor professional video editing and CAD visualization, with DisplayPort 1.4 and HDMI 2.1 interface requirements complicating legacy infrastructure integration for United States media production houses.
- 1080p:Full HD remains the volume workhorse for call centers, administrative offices, and K-12 education, with minimal graphics card demands extending hardware refresh intervals and reducing total cost of ownership.
- 1440p:QHD resolution gains traction among competitive gamers in China seeking frame rate performance compromises between 1080p and 4K rendering loads.
- 8K:7680×4320 panels serve medical imaging and broadcast monitoring applications where pixel-level scrutiny justifies extreme bandwidth and processing investments.
1080p holds the largest share; 4K shows the steepest expansion trajectory as content creation workflows proliferate.
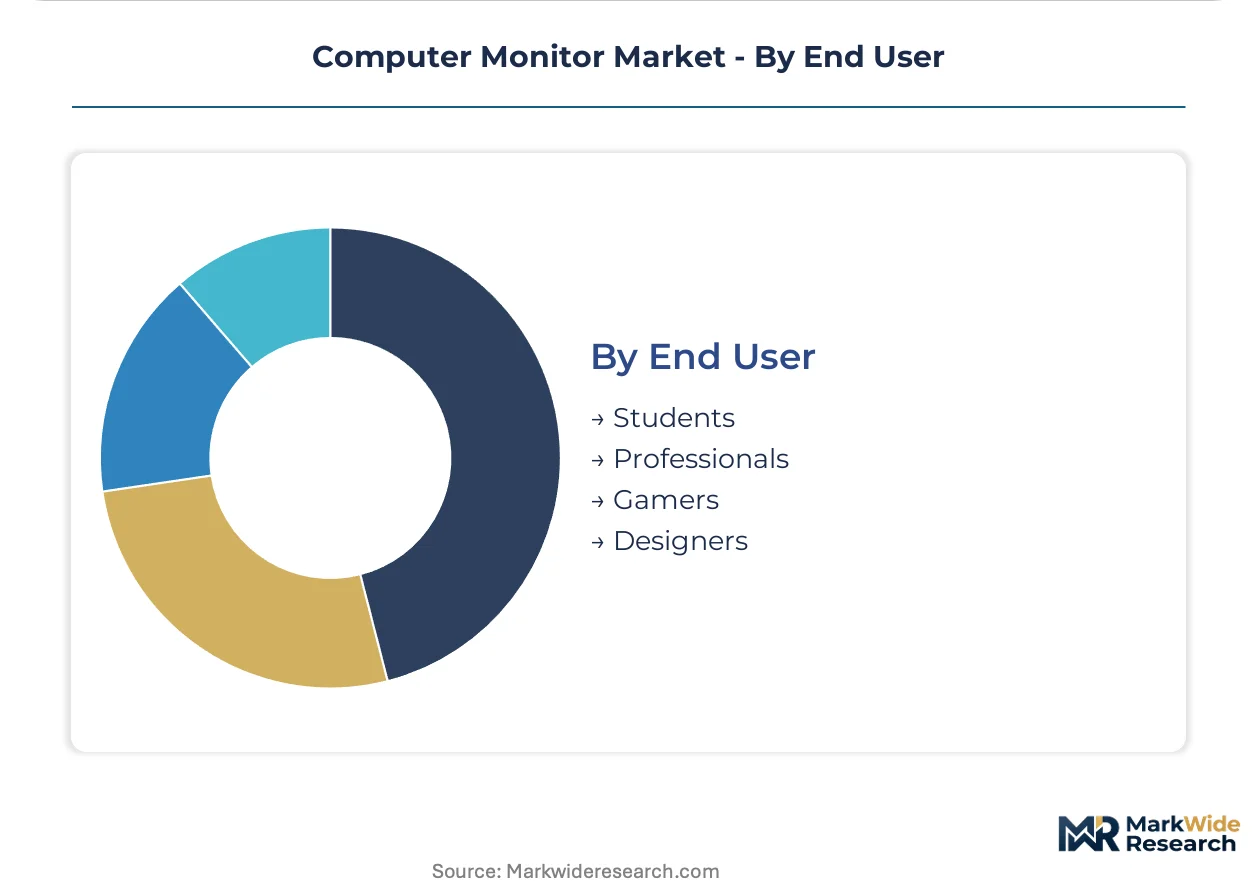
End User:
Usage patterns and performance expectations segment warranty terms, support tiering, and accessory bundling strategies across distribution channels.
- Professionals:Knowledge workers prioritize ergonomic adjustability and eye comfort certifications, with United States enterprises specifying EPEAT-registered models for sustainability compliance and federal procurement eligibility.
- Gamers:Refresh rate and adaptive sync specifications dominate purchase criteria, with 144Hz minimums becoming standard in China and the United States as cloud gaming reduces discrete GPU dependency.
- Students:Price sensitivity and dormitory space constraints drive compact 24-inch 1080p preferences, with educational discounts and institutional bulk purchasing aggregating demand for entry-tier SKUs.
- Designers:Color-critical workflows demand factory-calibrated Delta E<2 guarantees and hardware calibration probe compatibility, with Adobe RGB and DCI-P3 coverage percentages determining panel selection for South Korean and Japanese creative studios.
Professionals hold the largest share; gamers are gaining share fastest as esports infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in display panel fabrication concentrate value capture in South Korea and China, while import-dependent markets in Germany and India drive procurement innovation through regulatory compliance and localized assembly incentives.
United States
Enterprise IT refresh cycles and cloud-gaming infrastructure sustain demand for high-refresh-rate panels. EPA Energy Star 8.0 specifications disqualify older backlight designs from federal procurement eligibility. Austin and Seattle tech corridors anchor specification-setting for professional and gaming segments.
Germany
Industrial automation and precision engineering workflows drive premium-tier monitor adoption among Mittelstand manufacturers. EU Ecodesign efficiency mandates force OEM redesigns favoring advanced panel tiers. Bavaria's automotive design clusters concentrate color-critical display procurement for CAD visualization.
South Korea
OLED self-emissive technology leadership and captive semiconductor fabrication create export surplus in high-value display components. MFDS-equivalent display quality standards shape domestic certification requirements. Gyeonggi Province's display industrial complex anchors global OLED panel supply.
China
Domestic gaming market scale and esports infrastructure investment pull through 144Hz+ panel volumes. MIIT display efficiency standards align with national dual carbon goals. Yangtze River Delta manufacturing clusters integrate panel assembly with downstream system integration.
India
Education sector digitization and government procurement programs aggregate entry-level 1080p demand. BIS certification pathways and PLI scheme incentives enable localized assembly cost structures. Tamil Nadu and Karnataka electronics manufacturing zones concentrate import-substitution investments.
Computer Monitor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in panel fabrication and driver IC supply. Market structure consolidates around display technology leaders with captive semiconductor capabilities, while mid-tier assemblers compete on logistics and channel financing. Three archetypes dominate: vertically integrated electronics conglomerates, specialized gaming monitor brands, and contract manufacturing platforms serving institutional procurement. Capacity expansion in OLED fabrication and strategic partnerships for cloud-gaming endpoint certification represent the dominant competitive vectors.
Among vertically integrated conglomerates, Samsung Electronics and LG Electronics exemplify the technology-leader archetype through captive display fabrication. Dell Technologies occupies a position as the enterprise platform integrator, leveraging direct-channel financing to capture institutional account stickiness. Specialized gaming-focused manufacturers including ASUS and Gigabyte sit within the enthusiast-tier segment, competing on refresh-rate specifications and adaptive sync certification.
| Leading Market Players |
|---|
| Dell Technologies |
| BenQ |
| Samsung Electronics |
| ViewSonic |
| AOC |
| LG Electronics |
| Acer |
| Gigabyte |
| ASUS |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese LCD fabrication is compressing panel spot prices and forcing Korean manufacturers toward OLED premiumization strategies that preserve margin pools. This utilization imbalance creates divergent supplier behaviors: Chinese foundries absorb volume losses to maintain employment, while Korean operations throttle legacy capacity to sustain pricing power in professional tiers.
Pricing Analysis
Enterprise IT buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on panel certification grade and volume procurement scale, with EPEAT-registered and factory-calibrated SKUs commanding substantial premiums over uncertified alternatives. Cost compression in entry-level 1080p segments is intensifying because Chinese domestic brands are absorbing margin losses to secure education and government contracts. Educational institutions exhibit highest price sensitivity, while professional design studios prioritize color-accuracy guarantees over unit economics.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment are constraining Chinese OLED capacity expansion and reinforcing Korean near-monopoly in self-emissive panel supply. Geographic concentration centers on South Korea, China, and Taiwan for display driver ICs and timing controllers. Raw material dependencies include indium tin oxide substrates, liquid crystal compounds, and gallium-based semiconductor materials. Single-source vulnerability in IGZO backplane supply creates procurement risk for high-refresh-rate gaming panels. Distribution runs through direct-channel enterprise integrators and specialized gaming retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED penetration in professional workflows sits below 15% across major economies, creating substantial runway as color-critical applications displace legacy LCD installations. Cloud-gaming infrastructure buildouts are accelerating refresh-rate specification pull-through in markets where discrete GPU ownership remains limited.
For Market Incumbents: Insulate premium-tier positioning through captive OLED fabrication capacity and factory-calibration service bundling. Samsung Electronics and LG Electronics should expand Gyeonggi Province OLED lines before Chinese competitors achieve process parity. Defend against Mini-LED substitution by emphasizing per-pixel illumination advantages in HDR content workflows.
For New Entrants and Emerging Players: Mid-market commercial buildings in India and Southeast Asia represent the most penetrable entry point for localized assembly operations. Target 24-inch 1080p education procurement under BIS certification pathways and PLI scheme incentives. Pursue equipment-as-a-service financing partnerships to displace Dell Technologies' direct-channel stickiness in healthcare verticals.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise platform integrators with captive financing arms and refresh-subscription contracts. Long-term viability favors vertically integrated display conglomerates with semiconductor fabrication capabilities. Monitor OLED yield-rate improvements at Chinese panel makers as inflection indicator for pricing power erosion in premium tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| OLED Capacity Expansion | Korean manufacturers are scaling Gyeonggi Province fabrication to meet professional design demand. |
| Backward Integration into Driver ICs | Captive semiconductor production reduces Taiwanese foundry dependency for timing controllers. |
| Subscription Refresh Programs | Equipment-as-a-service models fragment capital expenditure into operational budgets for mid-market enterprises. |
| Cloud-Gaming Endpoint Certification | Low-latency display partnerships with streaming platforms pull through 144Hz+ panel specifications. |
| Localized Assembly in India | PLI scheme incentives enable cost-competitive 1080p production for education and government procurement. |
Methodological Framework
A standing panel of display procurement directors, OEM product managers, panel fabrication engineers, and channel financing executives provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, customs trade data, EPA Energy Star certification databases, and EU Ecodesign regulatory filings. Bottom-up shipment modeling and top-down value-chain triangulation reconciled volume estimates across the analysis window.
Scenario-bracketing framed demand projections under varying OLED penetration assumptions and regulatory efficiency mandate timelines. Segmentation dimensions modeled include panel technology, screen size, resolution tier, end-user vertical, and regional procurement cluster. CAGRs were derived from fitted growth curves anchored to historical shipment data and forward-looking replacement cycle analysis. Forecast inputs incorporated enterprise IT refresh normalization patterns and cloud-gaming infrastructure deployment schedules.
Practitioners should monitor panel utilization rates at Chinese LCD foundries and Korean OLED yield improvements for early signals of pricing inflection. Forecasts reflect documented assumptions regarding regulatory compliance timelines and substitution elasticity between display technologies. Material shifts in EU right-to-repair enforcement or IGZO substrate supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Paper-Thin Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Global OLED Market
Display Technologies
Electrochromic Window Market
Display Technologies
Laptop Panels Market
Display Technologies
Global Wearable Display Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Global Medical Display Market
Display Technologies
Wireless Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Collaboration Display Market
Display Technologies
Smart Screen Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Display Port Market