
 Global Haptic Touchscreen Market | 2026-2036
Global Haptic Touchscreen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Haptic Touchscreen Market Foresight
A shortage of piezoelectric material specialists is unwinding production timelines across actuator foundries. Texas Instruments Incorporated leverages its analog semiconductor portfolio to dominate driver IC supply for ultrasonic haptic modules. Immersion Corporation sustains its intellectual property position through extensive patent licensing to mobile device manufacturers. Samsung Electronics anchors captive demand through vertical integration across display and haptic actuator production.
Haptic touchscreens incorporate electromechanical transducers that generate localized vibrotactile feedback through piezoelectric ceramics or electrostatic friction modulation, typically operating at resonance frequencies between 100-300 Hz to simulate texture and button press confirmation. Capacitive touch panels with integrated force sensors currently occupy the largest revenue share due to smartphone penetration, while piezoelectric technology leads growth trajectories in automotive control systems where precise tactile response improves driver safety. Gaming applications compete for engineering attention as force feedback implementations require higher displacement actuators and dedicated signal processing architectures.
FDA scrutiny of haptic interfaces in medical device touch panels shapes validation protocols for surgical equipment and diagnostic systems in the United States. CE marking under the EU's Medical Device Regulation and REACH chemical compliance for piezoelectric lead zirconate titanate compositions constrain material sourcing and product design cycles. Stakeholders must monitor evolving automotive functional safety standards from NHTSA and ECHA restrictions on piezoelectric material content to anticipate certification bottlenecks and supply chain requalification requirements.
Market Dynamics
Piezoelectric actuator supply concentration in East Asian foundries is forcing automotive OEMs to requalify alternative ceramic formulations and redesign driver IC architectures to reduce single-source dependency risks.
Growth Catalysts
- Automotive HMI mandates:NHTSA guidelines for reduced driver distraction push vehicle manufacturers toward tactile feedback interfaces in center-stack controls.
- EU AI Act compliance:CE marking requirements for human-machine interaction safety create procurement pull for certified haptic modules in medical and industrial equipment.
- Lead zirconate titanate ceramic advances:Improved sintering processes enable thinner actuator layers with equivalent displacement output, expanding design flexibility for smartphone integrators.
Market Restraints
- Piezoelectric material concentration:Over 70% of high-purity PZT ceramic supply originates from Chinese smelters, exposing downstream module assemblers to export quota volatility.
- REACH chemical restrictions:ECHA scrutiny of lead content in piezoelectric compositions forces reformulation cycles that extend product development timelines by 8-14 months.
- Electrostatic friction modulation:Lower-cost ultrasonic alternatives from display-integrated suppliers threaten standalone piezoelectric module attach rates in mid-tier consumer electronics.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronic component production attract actuator module assembly investments serving domestic smartphone brands.
- Surgical robotics integration:FDA 510(k) pathways for haptic feedback in minimally invasive instruments open premium pricing tiers for force-sensitive touch panels.
- Ultrasonic surface haptics convergence:Combination of time-of-flight sensing with localized friction modulation enables texture rendering without mechanical actuators, reducing assembly thickness.
Industry Challenges
- Piezoelectric ceramics expertise gap:Foundry engineers with deep knowledge of poling voltage optimization and resonance tuning remain scarce relative to expansion plans.
- Automotive functional safety certification:ISO 26262 ASIL-B compliance for haptic feedback systems in steering wheel controls demands fault-tolerant driver architectures that inflate BOM costs.
- Legacy capacitive retrofit complexity:Industrial equipment OEMs face mechanical redesign burdens when upgrading existing touch panels to force-sensing haptic variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Haptic Touchscreen Market |
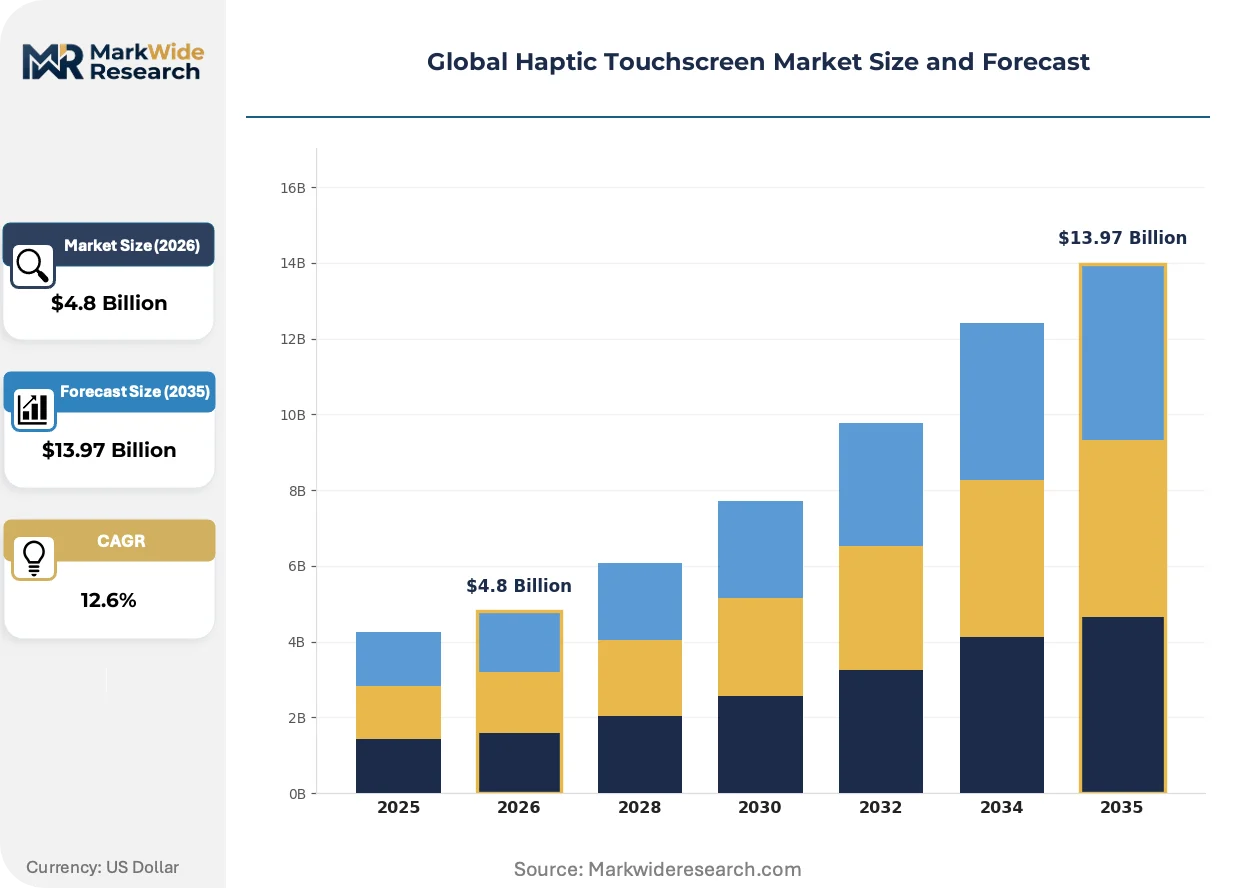
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistive, Capacitive, Surface Acoustic Wave, Infrared, Optical, Electromagnetic Technology: Tactile, Force Feedback, Electrostatic, Piezoelectric, Vibrational, Ultrasonic Application: Smartphones, Automotive Control Systems, Wearable Devices, Industrial Equipment, Consumer Electronics, Gaming End User: Mobile Device Manufacturers, Vehicle OEMs, Medical Device Companies, Industrial Automation Firms, Electronics Retailers, Entertainment Providers |
| Companies Covered | Immersion Corporation, Texas Instruments Incorporated, Apple Inc., Qualcomm Technologies, Inc., Microchip Technology Inc., Samsung Electronics, LG Display Co., TDK Corporation, Synaptics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Haptic Touchscreen Market Shifts & Advancements
Ultrasonic surface haptics is compressing the addressable market for electromechanical actuators while regulatory chemical restrictions are accelerating material substitution programs across European supply chains.
Surface-guided haptic wave generation through phased-array ultrasonic transducers is displacing traditional piezoelectric bender actuators in premium smartphone displays. Samsung Display and BOE Technology are shipping millions of panels with integrated ultrasonic haptics, eliminating separate actuator modules and compressing stack thickness by 0.4-0.6 millimeters. This displacement is forcing standalone haptic component suppliers to pivot toward automotive and industrial applications where force magnitude requirements exceed ultrasonic output limits.
REACH authorization requirements for lead compounds are tightening ECHA oversight of piezoelectric material formulations used in consumer electronics. Manufacturers must submit substitution plans or secure time-limited exemptions for PZT-based actuators, driving R&D investment into potassium sodium niobate and bismuth-based alternatives with inferior electromechanical coupling coefficients. Medical device touch panels face the most severe compliance timeline pressure due to MDR Annex I biocompatibility requirements叠加 on chemical restrictions.
Automotive Tier 1 suppliers are consolidating haptic module procurement through direct partnerships with actuator foundries, bypassing traditional distribution channels. Continental and Bosch are negotiating multi-year supply agreements with ceramic manufacturers for customized piezoelectric stacks, locking in volume commitments in exchange for dedicated production lines. This channel compression is most advanced in Germany and Japan, where just-in-time assembly requirements favor captive supply relationships over spot-market purchasing.
Global Haptic Touchscreen Market Segmentation
Technology substitution pressures and regulatory chemical restrictions are fragmenting competitive positioning across haptic touchscreen architectures. Understanding segment-level exposure to ultrasonic displacement and REACH compliance timelines enables procurement teams to anticipate qualification bottlenecks and sourcing reallocation needs.
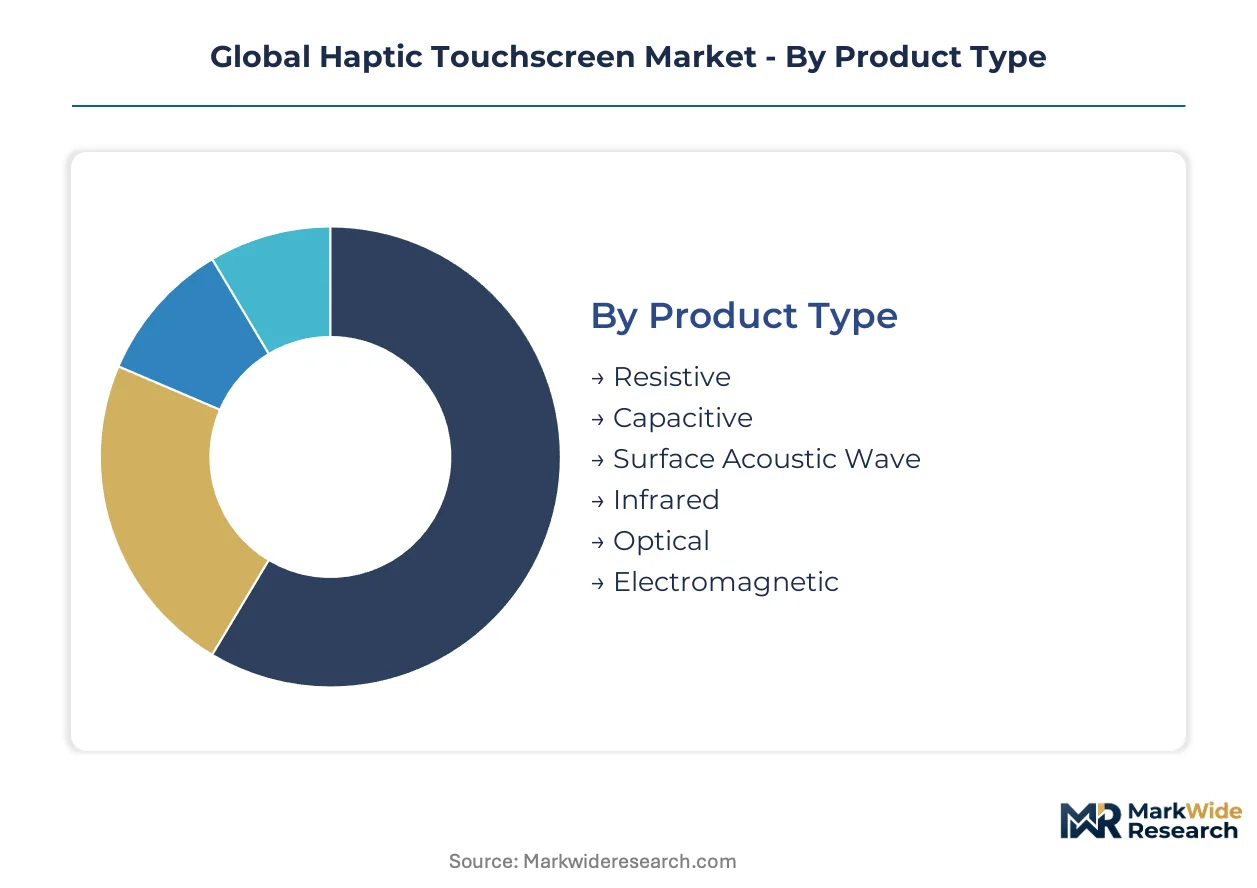
Product Type:
Capacitive and resistive technologies face divergent substitution threats from ultrasonic surface haptics, with stack-thinning requirements determining survival timelines in consumer electronics.
- Capacitive:Multi-layer construction integrating force sensors and transparent conductive electrodes dominates smartphone bill-of-materials. Samsung Display and BOE Technology are shipping integrated ultrasonic alternatives that eliminate separate capacitive sensor stacks, compressing attach rates for standalone modules in premium handsets.
- Resistive:Pressure-activated membrane switches with indium tin oxide coatings persist in industrial equipment where glove compatibility and liquid ingress tolerance outweigh precision requirements. Automotive center-stack retrofits and legacy manufacturing HMI systems in Germany and Japan sustain procurement volumes despite displacement in consumer applications.
- Surface Acoustic Wave:Piezoelectric transducer arrays generating Rayleigh waves for touch detection maintain niche deployment in kiosks and casino gaming terminals where vandal resistance is paramount.
- Infrared:LED-photodetector grid arrays without surface overlay suit medical imaging workstations requiring sterile field compatibility.
- Optical:Camera-based touch detection through frustrated total internal reflection finds limited adoption in large-format interactive displays.
- Electromagnetic:Resonant inductive coupling for stylus input anchors specialized drawing tablet applications from Wacom and Huion.
Capacitive anchors the volume base while surface acoustic wave gains share at the steepest rate in ruggedized industrial deployments.
Technology:
Cost tier stratification separates electromechanical actuator families from solid-state ultrasonic implementations, with force magnitude requirements determining automotive versus consumer viability.
- Piezoelectric:Lead zirconate titanate ceramic stacks operating at resonance frequencies between 100-300 Hz deliver precise displacement control for texture simulation. ECHA REACH authorization timelines are forcing reformulation into potassium sodium niobate alternatives, extending product development cycles for European medical device suppliers.
- Ultrasonic:Phased-array transducers modulating surface friction through acoustic radiation pressure eliminate mechanical actuators entirely. Samsung Electronics and Tanvas are commercializing display-integrated implementations that threaten standalone module suppliers in smartphone and tablet applications.
- Tactile:Eccentric rotating mass motors and linear resonant actuators provide basic vibrotactile feedback in mid-tier consumer electronics where cost minimization dominates specification sheets.
- Force Feedback:Higher-displacement actuators with dedicated signal processing architectures serve surgical robotics and flight simulation training systems requiring kinesthetic resistance rendering.
- Electrostatic:Variable capacitance between finger and insulated electrode creates programmable friction modulation without moving parts.
- Vibrational:Broad-spectrum mechanical oscillation for alert notification in wearable devices with severe power and space constraints.
Piezoelectric commands premium pricing in automotive safety systems while ultrasonic climbs the fastest in smartphone display integration.
Application:
Automotive functional safety mandates and medical device FDA pathways are concentrating engineering investment in force-sensitive implementations, diverting resources from gaming peripheral development.
- Automotive Control Systems:Center-stack and steering wheel interfaces requiring ISO 26262 ASIL-B fault tolerance. NHTSA distraction reduction guidelines are mandating tactile feedback for eyes-off operation, locking in multi-year procurement commitments from Continental and Bosch.
- Smartphones:Ultrasonic surface haptics from Samsung Display is displacing electromechanical actuators in flagship handsets, compressing revenue pools for standalone module suppliers serving Chinese domestic brands.
- Wearable Devices:Ultra-thin linear resonant actuators in smartwatches and fitness bands prioritize battery endurance over texture rendering fidelity.
- Industrial Equipment:Glove-compatible resistive overlays with IP65 sealing persist in factory floor HMI panels where chemical exposure and impact damage are routine.
- Consumer Electronics:Remote controls and kitchen appliances adopt basic tactile feedback for button press confirmation at minimal cost increment.
- Gaming:Force feedback steering wheels and haptic VR controllers demand higher-displacement actuators with dedicated DSP architectures, competing for engineering talent against automotive safety projects.
Smartphones anchor the volume base while automotive control systems expand most quickly on regulatory mandate pull-through.
End User:
Vertical integration strategies and captive supply chain control are reshaping procurement relationships, with direct foundry partnerships displacing traditional distribution channels.
- Vehicle OEMs:Volkswagen, Toyota, and Ford are negotiating multi-year supply agreements with ceramic manufacturers for customized piezoelectric stacks, bypassing Tier 1 module assemblers to secure dedicated production capacity.
- Mobile Device Manufacturers:Xiaomi, OPPO, and vivo in China drive volume procurement of actuator modules, though Samsung Electronics' captive display-haptics integration threatens attach rates for external suppliers.
- Medical Device Companies:Intuitive Surgical and Medtronic face FDA 510(k) validation requirements for haptic feedback in minimally invasive instruments, with MDR Annex I biocompatibility叠加 on REACH chemical restrictions.
- Industrial Automation Firms:Siemens and Rockwell Automation retrofit legacy capacitive panels with force-sensing variants, absorbing mechanical redesign burdens for HMI upgrade cycles.
- Electronics Retailers:Private label sourcing of white-good touch panels with basic tactile feedback from contract manufacturers in Vietnam and Indonesia.
- Entertainment Providers:Arcade operators and VR venue chains procurement haptic-enhanced interfaces for immersive experience differentiation.
Mobile device manufacturers anchor the volume base while vehicle OEMs gain procurement leverage at the steepest rate through direct foundry engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification requirements in China shape procurement standards that cascade through East Asian supply chains. The EU AI Act and CE marking frameworks in Europe are redefining human-machine interface safety protocols. FDA 510(k) pathways in the United States govern medical device integration timelines.
China
Domestic smartphone brands and EV manufacturers drive volume procurement of piezoelectric actuator modules. MIIT standards for automotive HMI safety accelerate qualification requirements for center-stack suppliers. Shenzhen and Dongguan host concentrated module assembly operations serving Xiaomi, OPPO, and vivo procurement networks.
United States
NHTSA distraction reduction guidelines mandate tactile feedback for eyes-off vehicle operation. FDA 510(k) validation protocols shape haptic interface deployment in surgical robotics and diagnostic equipment. Michigan and California anchor automotive OEM engineering centers where Continental and Bosch maintain haptic system integration facilities.
Germany
Volkswagen, BMW, and Mercedes-Benz negotiate direct foundry partnerships for customized piezoelectric stacks. KBA type-approval requirements for automotive electronics intersect with REACH chemical restrictions on lead zirconate titanate formulations. Bavaria and Baden-Württemberg concentrate Tier 1 supplier engineering operations for ISO 26262 ASIL-B compliance development.
South Korea
Samsung Electronics leverages captive display-haptics integration to compress standalone module attach rates. MFDS medical device regulations overlay REACH compliance timelines for piezoelectric material sourcing. Gyeonggi Province hosts concentrated display panel manufacturing where ultrasonic surface haptics displace electromechanical alternatives.
Japan
Automotive functional safety investments from Toyota and Honda sustain demand for high-reliability actuator modules. METI technology roadmaps prioritize advanced HMI development for aging-population mobility solutions. Aichi and Kanagawa prefectures concentrate precision ceramics foundries with deep expertise in poling voltage optimization.
Global Haptic Touchscreen Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the haptic touchscreen value chain. The market structures around three tiers: integrated display manufacturers with captive haptics capabilities, specialized actuator module suppliers, and semiconductor firms dominating driver IC supply. Two strategic archetypes predominate: IP licensors extracting royalties across multiple device categories, and vertically integrated electronics conglomerates controlling stack-level integration. Competitive moves concentrate on backward integration into ceramic foundry capacity and strategic patent portfolio expansion.
Within the intellectual property licensing tier, Immersion Corporation exemplifies royalty-based revenue extraction across mobile device ecosystems. Texas Instruments Incorporated anchors the analog semiconductor segment supplying driver architectures for ultrasonic and piezoelectric implementations. Samsung Electronics occupies a position representing full-stack integration from display panel through haptics module production.
| Leading Market Players |
|---|
| Immersion Corporation |
| Texas Instruments Incorporated |
| Apple Inc. |
| Qualcomm Technologies, Inc. |
| Microchip Technology Inc. |
| Samsung Electronics |
| LG Display Co. |
| TDK Corporation |
| Synaptics Incorporated |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in East Asian ceramic manufacturing compress unit costs for piezoelectric actuators while simultaneously concentrating pricing power among a handful of high-volume suppliers. This scale-driven consolidation locks in price floors for automotive and medical device OEMs that lack alternative sourcing pathways, particularly as REACH compliance costs layer onto European procurement budgets.
Pricing Analysis
Geographic price spreads of 15-25% separate German automotive procurement from Chinese domestic brand sourcing for equivalent piezoelectric actuator specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with ISO 26262 ASIL-B qualified modules commanding substantial premiums over consumer-grade alternatives. Cost compression in mid-tier smartphone haptics is intensifying because Samsung Display's captive ultrasonic integration eliminates attach opportunities for standalone module suppliers. Chinese EV manufacturers exhibit highest price sensitivity, while surgical robotics OEMs prioritize force fidelity over unit economics.
Supply Chain Analysis
Just-in-time assembly preferences among German and Japanese automotive Tier 1 suppliers clash with strategic stockpile imperatives driven by Chinese export quota volatility for high-purity PZT ceramics. Supply concentrates in China, Japan, and South Korea for ceramic foundry capacity, with driver IC sourcing anchored in Texas and Taiwan. Raw material dependencies rest on lead zirconate titanate powders, indium tin oxide coatings, and analog semiconductor wafers. Single-source vulnerability pervades high-purity PZT supply from Chinese smelters. Distribution runs through direct foundry partnerships that bypass traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of engineers skilled in poling voltage optimization and resonance tuning constrains expansion timelines across actuator foundries, amplifying returns for incumbents that lock in technical talent pipelines.
For Market Incumbents: Fortify captive ceramic foundry relationships through multi-year volume commitments that secure dedicated production lines, particularly as automotive OEMs bypass Tier 1 assemblers. Deepen backward integration into potassium sodium niobate R&D to preempt REACH substitution mandates. Prioritize certification investment in FDA 510(k) pathways for surgical robotics applications where force-sensitive touch panels command premium positioning. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized electronic component manufacturing zones to serve Xiaomi, OPPO, and vivo procurement networks with cost-competitive actuator module assembly. Target industrial equipment retrofit segments where legacy resistive panel upgrades absorb mechanical redesign burdens that deter incumbent resource allocation. Pursue white-label partnerships with Vietnamese and Indonesian contract manufacturers for white-good touch panel integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized actuator module suppliers with established automotive safety certifications over display-integrated ultrasonic players facing smartphone attach rate compression. Long-term viability hinges on regulatory compliance capabilities spanning FDA, CE marking, and REACH authorization timelines. Monitor ECHA substitution exemption decisions as the critical inflection signal for material technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Foundry Capacity | Volkswagen and Toyota direct partnerships eliminate Tier 1 margin extraction. |
| REACH-Compliant Material Substitution Program | Potassium sodium niobate R&D investments preempt ECHA authorization deadlines. |
| Automotive Safety Certification Acceleration | ISO 26262 ASIL-B compliance unlocks NHTSA-mandated center-stack procurement. |
| Ultrasonic Surface Haptics Platform Integration | Samsung Display's captive production compresses standalone module attach rates. |
| Surgical Robotics FDA 510(k) Pathway | Intuitive Surgical and Medtronic validation requirements open premium pricing tiers. |
Research Methodology
A standing panel of ceramic foundry operations directors, automotive Tier 1 procurement leads, medical device regulatory affairs specialists, and smartphone platform engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT automotive HMI standards filings, ECHA REACH authorization submissions, FDA 510(k) clearance databases, and SEC 10-K disclosures from analog semiconductor suppliers. Bottom-up unit shipment modeling across piezoelectric and ultrasonic technology categories triangulated against top-down OEM procurement budget analysis.
Consistency checks against IHS Markit vehicle production databases and display panel shipment trackers from Gyeonggi Province manufacturing clusters validated volume outputs across the projection horizon. Segmentation dimensions modeled include technology type, application sector, end-user vertical, and regional regulatory cluster. CAGRs were derived from polynomial trend fitting to historical price-volume trajectories, with automotive functional safety mandate timelines and REACH substitution schedules as key haptic touchscreen demand inputs.
Material uncertainties — ECHA lead compound exemption decisions, Chinese PZT export quota adjustments, and ultrasonic surface haptics yield improvements — sit outside the modeled envelope. Forecasts reflect assumptions regarding ceramic formulation stability and automotive OEM direct sourcing momentum. Practitioners should keep alternative scenarios live as EU AI Act implementation guidance and NHTSA distraction reduction rulemaking evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Graphic LCD Modules Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Rental Outdoor LED Display Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Visual Computing Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Mono LCD Displays Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Video Wall Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Rugged Display Market
Display Technologies
4K Drawing Tablet with Screen Market