
 Cathode Ray Tube Display Market | 2026-2036
Cathode Ray Tube Display Market Size, Share, and Industry Trends Forecast 2026-2036
Cathode Ray Tube Display Market Analysis
REACH compliance is recalibrating the cost-of-entry calculus for European CRT refurbishment operations. LG Display Co., Ltd. leverages its residual manufacturing infrastructure to sustain limited specialty production. Samsung SDI anchors supply for legacy industrial monitor replacements across Asian maintenance networks. Toshiba Corporation specializes in high-reliability tube variants for oscilloscope OEMs.
A cathode ray tube display is an evacuated glass envelope containing an electron gun and phosphorescent screen, operating through electrostatic or electromagnetic beam deflection to render images at refresh rates typically between 60 and 85 Hz. Its primary commercial purpose remains displaying waveform data in precision test equipment and sustaining legacy video systems where flat-panel alternatives fail to replicate motion clarity or color accuracy. Color CRT dominates replacement revenue in broadcast monitoring and arcade gaming restoration, while monochrome CRT retains superior margin pools in medical imaging and military avionics due to certification barriers. Portable CRT occupies a shrinking niche in field-deployable oscilloscope units where power efficiency and shock resistance outweigh display bulk.
The EPA regulates cathode-ray tube disposal under universal waste rules that elevate end-of-life handling costs for US operators. ECHA enforces REACH substance restrictions on leaded glass and phosphor coatings, constraining European refurbishment economics. Japan's METI maintains JIS standards for electron gun emissions that shape export eligibility for Asian manufacturers. Stakeholders must weigh inventory depletion timelines against regulatory compliance investments as original equipment manufacturing ceases entirely.
Market Dynamics
Inventory depletion timelines now dominate strategic planning as original equipment manufacturing ceases entirely across all major production bases. Stakeholders must calibrate compliance investments against residual demand concentration in defense and industrial maintenance channels where replacement cycles extend decades.
Growth Catalysts
- Military-grade oscilloscope demand:Equipment longevity requirements in defense procurement specifications sustain replacement orders where flat-panel alternatives fail to replicate waveform fidelity.
- REACH substance thresholds:European refurbishment operations achieving compliance certification capture margin premiums on certified leaded-glass inventory.
- Phosphor coating advances:Enhanced rare-earth formulations extend tube operational lifespan in medical imaging equipment requiring color stability certification.
Market Restraints
- Leaded glass supply concentration:Primary funnel glass production now concentrates in Asian specialist foundries with limited Western alternative sourcing.
- EPA universal waste rules:End-of-life handling cost elevation compresses refurbishment economics for US-based operators.
- LCD substitution in broadcast monitoring:Flat-panel motion interpolation advances erode residual CRT advantages in studio equipment refresh cycles.
Strategic Opportunities
- Japanese JIS standard electron gun exports:METI-certified manufacturers access niche Asian maintenance networks requiring emission-specified replacements.
- Arcade gaming restoration segment:Authentic display procurement for vintage cabinet refurbishment commands premium pricing in collector markets.
- Avionics monochrome certification pathways:FAA and EASA legacy equipment waivers sustain demand for high-reliability tube variants in cockpit instrumentation.
Industry Challenges
- Electron gun assembly technician scarcity:Specialized vacuum tube manufacturing skills retire without pipeline replacement across all production regions.
- Phosphor coating facility capex requirements:Environmental containment investments for rare-earth handling deter new market entry.
- Cross-border hazardous material logistics:Leaded glass transport regulations fragment supply chain coordination between refurbishment centers and end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathode Ray Tube Display Market |
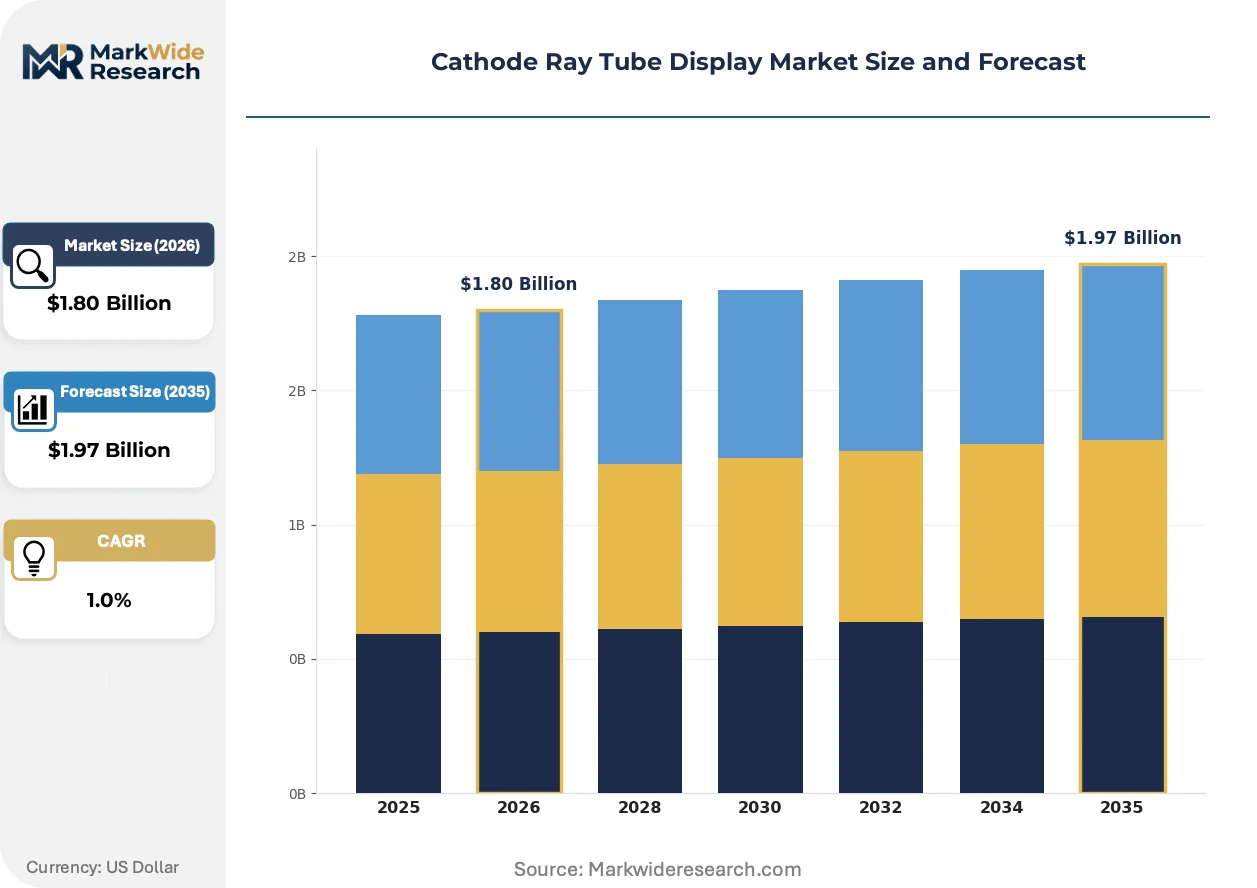
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color CRT, Monochrome CRT, High-Resolution CRT, Portable CRT Application: Television, Computer Monitor, Oscilloscope, Gaming Console Technology: Analog, Digital, Direct View, Projection End User: Consumer Electronics, Education, Healthcare, Military |
| Companies Covered | LG Display Co., Ltd., Samsung SDI, Toshiba Corporation, Panasonic Corporation, Koninklijke Philips N.V., Sony Corporation, Chunghwa Picture Tubes, LTD., Richardson Electronics, Video Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathode Ray Tube Display Market Emerging Trajectories
Active beam deflection calibration systems are compressing the performance gap between legacy CRT architectures and precision display requirements. Three developments are reshaping how specialty manufacturers sustain technical relevance.
Automated phosphor deposition equipment is automating coating uniformity in small-batch tube production. Oscilloscope OEMs in Germany and Japan adopt these systems to sustain sub-micron pitch consistency for high-bandwidth waveform visualization. The technology is automating quality control labor costs that previously constrained low-volume manufacturing economics.
RoHS exemption renewal negotiations are recalibrating European refurbishment investment horizons. The European Commission's periodic review of leaded-glass exclusions determines whether specialized coating facilities retain operational licenses. Medical imaging equipment manufacturers in Italy and France accelerate inventory stockpiling ahead of potential 2026 directive revisions.
Direct procurement relationships between defense maintenance depots and Asian tube specialists are displacing traditional distributor intermediaries. Long-term availability agreements now span fifteen-year horizons for avionics and naval applications. This pattern is most visible in US Navy and Royal Navy submarine systems where supply chain traceability requirements override cost optimization.
Cathode Ray Tube Display Market Segmentation
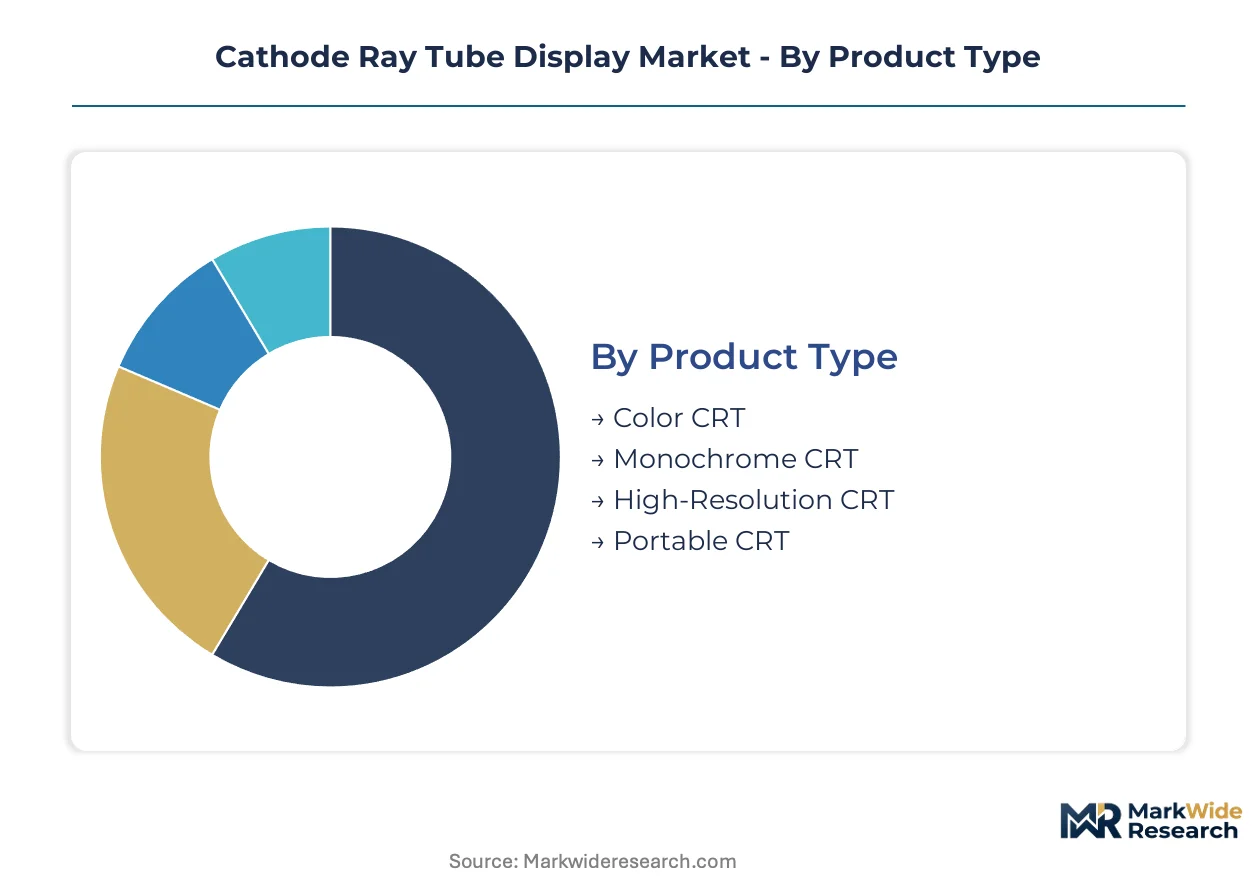
CRT display procurement patterns diverge sharply by technical specification and regulatory certification requirements. End-users in defense and medical imaging pay substantial premiums for monochrome and high-resolution variants that flat-panel technologies cannot replicate. Understanding these segment boundaries clarifies where refurbishment economics sustain viable operations versus where substitution has already concluded.
Product Type:
Buyers in this category separate by image fidelity requirements and environmental operating conditions rather than unit price sensitivity.
- Color CRT:RGB phosphor triad architecture renders broadcast-grade color gamut for studio monitoring and arcade cabinet restoration. Demand concentrates in North American collector markets and Japanese broadcast maintenance depots where motion clarity specifications exclude LCD alternatives.
- Monochrome CRT:Single-phosphor formulation eliminates convergence drift and delivers superior edge definition for waveform analysis. Military avionics and medical imaging equipment in Germany and France sustain procurement through FAA and EASA certification pathways that flat-panel displays have not penetrated.
- High-Resolution CRT:Sub-0.25mm dot pitch enables precision CAD/CAM visualization in legacy industrial workstations.
- Portable CRT:Ruggedized envelope construction withstands field deployment shock loads for oscilloscope manufacturers serving utility maintenance crews.
Volume sits with Color CRT; growth tilts toward Monochrome CRT as defense procurement specifications harden against display technology migration.
Application:
Replacement cycle duration varies from months in consumer segments to decades in embedded industrial systems.
- Oscilloscope:Phosphor persistence characteristics and infinite contrast ratio enable nanosecond-scale waveform capture that semiconductor-based displays cannot replicate. Tektronix and Keysight service depots in the United States and Japan maintain multi-year tube inventories against manufacturer discontinuation.
- Gaming Console:Authentic scanline rendering and input lag absence drive restoration demand for vintage arcade and home console collectors. Premium pricing in this segment often exceeds original manufacturing cost due to scarcity-driven auction dynamics.
- Television:Consumer replacement has effectively concluded outside developing-market repair ecosystems.
- Computer Monitor:Legacy industrial control systems in manufacturing plants sustain residual demand for direct replacement.
Revenue concentrates in Oscilloscope; the steepest expansion trajectory belongs to Gaming Console as collector market liquidity deepens.
Technology:
Architecture selection determines compatibility with legacy signal formats and electromagnetic interference tolerance.
- Analog:Continuous beam deflection preserves signal integrity for RF measurement equipment where digital sampling introduces aliasing artifacts. Oscilloscope OEMs in Germany and Japan specify analog reception for bandwidth specifications exceeding 500 MHz.
- Direct View:Evacuated envelope construction positions the phosphor surface at the viewing plane without intermediate optics, eliminating distortion in precision measurement applications. Medical imaging equipment manufacturers in Italy require direct view architecture for diagnostic consistency certification.
- Digital:On-board signal processing enables compatibility with modern source equipment in limited retrofit applications.
- Projection:Cathode ray projection systems persist in specialized simulation environments requiring large-format display.
Procurement volume clusters in Analog; certification momentum favors Direct View for replacement cycles in safety-critical equipment.
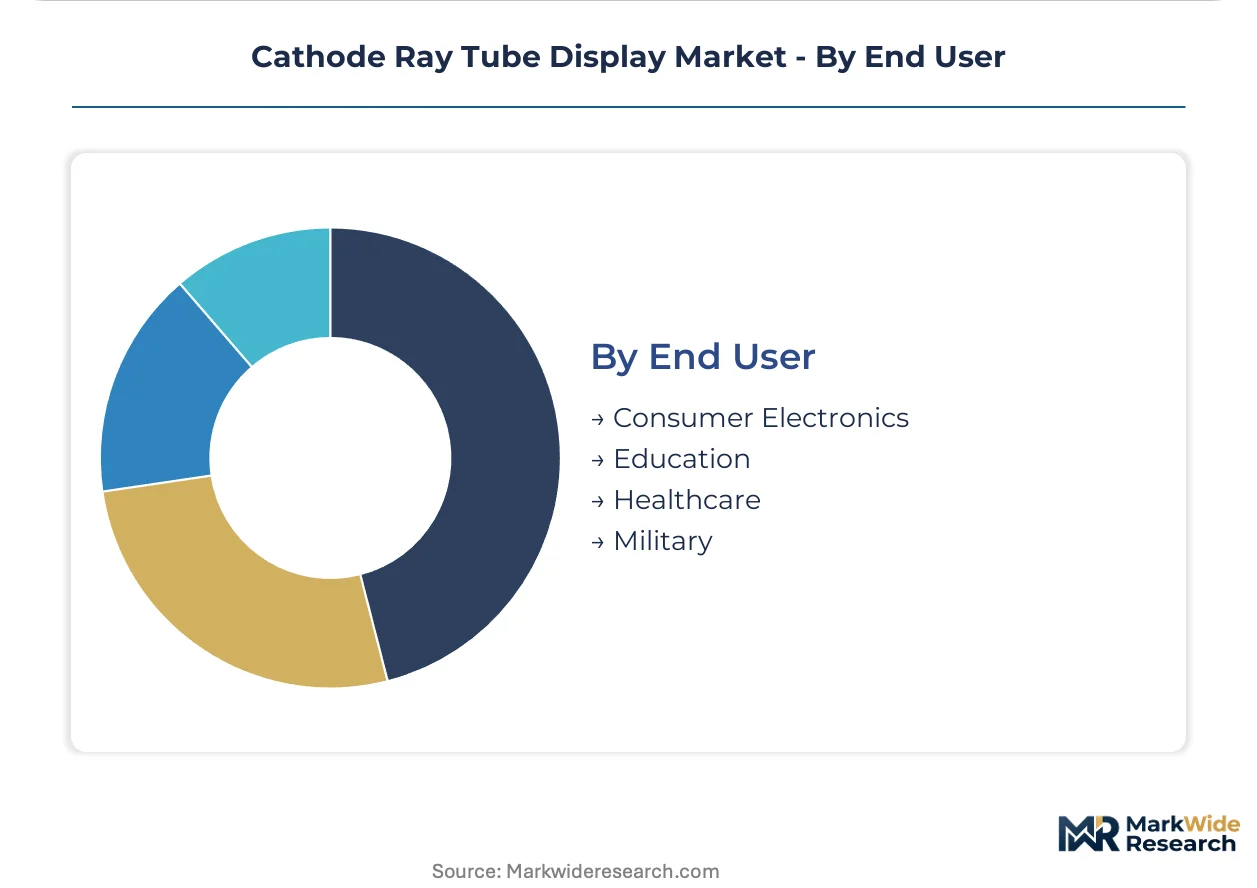
End User:
Budget authority and compliance obligation intensity shape purchasing behavior more than technical specification alone.
- Military:Defense procurement specifications mandate equipment longevity horizons exceeding thirty years, with waiver processes for cockpit and submarine systems blocking flat-panel substitution. US Navy and Royal Navy maintenance depots negotiate direct availability agreements with Asian tube specialists spanning fifteen-year supply horizons.
- Healthcare:Diagnostic imaging equipment requires color stability certification that legacy CRT formulations have demonstrated over decades of operational history. French and Italian medical device manufacturers stockpile certified inventory ahead of potential RoHS exemption revisions.
- Consumer Electronics:Replacement demand has collapsed outside emerging-market repair channels.
- Education:Physics laboratory demonstration equipment sustures minimal volume for electron beam visualization experiments.
Contract value concentrates in Military; replacement urgency is climbing the fastest in Healthcare as equipment obsolescence timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones in Southeast Asia host the remaining CRT glass foundry capacity serving global refurbishment demand. Defense procurement specifications and medical imaging certification requirements sustain residual manufacturing footprints across multiple jurisdictions.
United States
Navy submarine maintenance depots and oscilloscope service networks drive replacement orders for high-reliability tubes. EPA universal waste rules elevate end-of-life handling costs for domestic refurbishment operators. Richardson Electronics anchors supply chain coordination from its Illinois base for industrial and defense maintenance channels.
Japan
Oscilloscope OEMs in Nagoya and Yokohama sustain precision tube procurement for bandwidth specifications exceeding 500 MHz. METI enforces JIS standards for electron gun emissions that shape export eligibility for Asian manufacturers. Chubu region specialists maintain automated phosphor deposition equipment for small-batch production.
Germany
Medical imaging equipment manufacturers in Munich and Stuttgart stockpile certified inventory ahead of potential RoHS exemption revisions. ECHA REACH substance restrictions on leaded glass constrain European refurbishment economics. Bavarian industrial clusters sustain legacy CAD/CAM workstation replacement demand.
South Korea
Residual manufacturing infrastructure supports limited specialty production for Asian maintenance networks. Domestic regulations align with international hazardous material transport protocols for cross-border tube shipments. Seoul-based specialists coordinate direct procurement relationships with defense maintenance depots.
Taiwan
Specialist foundries concentrate primary funnel glass production with limited Western alternative sourcing. Regional logistics hubs facilitate cross-border hazardous material transport to refurbishment centers. Taoyuan industrial zones host coating facilities serving collector and restoration market segments.
Cathode Ray Tube Display Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across shrinking but high-margin replacement segments. Market structure tilts toward consolidation as original equipment manufacturing ceases and inventory depletion timelines compress viable participant counts. Three archetypes dominate: residual manufacturing conglomerates leveraging legacy infrastructure, specialized refurbishment operators capturing compliance premiums, and distributor intermediaries displaced by direct defense procurement relationships. Competitive moves center on long-term availability agreements spanning fifteen-year horizons and automated quality control investments sustaining sub-micron pitch consistency.
Among diversified Korean and Japanese conglomerates, LG Display Co., Ltd. and Samsung SDI occupy positions reflecting residual manufacturing infrastructure strategies, while Toshiba Corporation exemplifies the high-reliability specialization archetype for oscilloscope OEM certification pathways. These entities represent contrasting responses to market contraction: conglomerate diversification versus focused technical preservation.
| Leading Market Players |
|---|
| LG Display Co., Ltd. |
| Samsung SDI |
| Toshiba Corporation |
| Panasonic Corporation |
| Koninklijke Philips N.V. |
| Sony Corporation |
| Chunghwa Picture Tubes, LTD. |
| Richardson Electronics |
| Video Display Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA/EASA-certified monochrome tubes and unverified refurbished color units manifests in both unit economics and sourcing complexity. Premium-certified inventory commands substantial markups through defense procurement channels, while spot-market color CRT trades at compressed margins through distributor networks constrained by EPA universal waste handling costs.
Pricing Analysis
Short-lead-time premiums for certified military-grade tubes sustain elevated pricing through direct defense depot procurement, while spot inventory of unverified consumer-grade units discounts sharply through auction channels. Three-tier pricing structure across certified, refurbished, and as-is tiers separates defense contractors from industrial maintenance buyers from collector-market hobbyists. Cost compression in the refurbished tier intensifies because electron gun assembly technician scarcity elevates labor costs without quality improvement. Defense procurement specifications render military buyers least price-sensitive; arcade restoration collectors exhibit highest elasticity to scarcity-driven auction dynamics.
Supply Chain Analysis
Cross-border hazardous material freight costs fragment supply chain coordination between Asian coating facilities and Western refurbishment centers. Primary funnel glass production concentrates in Taiwan, South Korea, and mainland China specialist foundries with limited alternative sourcing. Rare-earth phosphor formulations and leaded glass envelopes draw from concentrated mining and metallurgical processing nodes. Single-source vulnerability runs through Taiwanese foundry capacity for high-reliability tube variants. Distribution runs through defense maintenance depot direct procurement relationships displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where flat-panel LCD and OLED architectures progressively displace legacy CRT applications outside certification-barriered defense and medical segments.
For Market Incumbents: Lock in long-term availability agreements with defense maintenance depots spanning fifteen-year supply horizons before electron gun assembly technician retirement accelerates. Capture margin premiums through REACH compliance certification investment for European medical imaging equipment manufacturers stockpiling ahead of RoHS exemption revisions. Vertical integration into automated phosphor deposition equipment sustains sub-micron pitch consistency for oscilloscope OEM certification pathways. For New Entrants and Emerging Players: Digital-channel auction platforms for vintage arcade cabinet restoration represent the most penetrable white-space target, authentic scanline rendering commands premium pricing from collector markets inaccessible through traditional industrial distribution. Specialty refurbishment operations serving US Navy and Royal Navy submarine systems offer second entry angle through supply chain traceability compliance rather than cost competition. Direct procurement relationship cultivation with defense depot technical staff bypasses established distributor lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-focused specialty manufacturers with established FAA/EASA certification pathways and captive Asian tube supply agreements. Long-term viability framing favors five-to-ten year windows for residual demand capture in oscilloscope and avionics segments before flat-panel substitution penetrates certification barriers. The signal to watch is RoHS exemption renewal negotiations determining European refurbishment operational license continuity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Availability Agreements | Defense depot direct procurement secures fifteen-year supply visibility against inventory depletion. |
| REACH Compliance Certification | European medical imaging manufacturers pay premiums for certified leaded-glass inventory stockpiles. |
| Automated Phosphor Deposition Investment | German and Japanese oscilloscope OEMs demand sub-micron pitch consistency for bandwidth specifications. |
| Electron Gun Assembly Technician Training | Pipeline replacement addresses specialized vacuum tube manufacturing skill retirement across production regions. |
| Direct Defense Procurement Relationships | US Navy and Royal Navy maintenance depots displace distributor intermediaries for supply chain traceability. |
Methodological Framework
Multi-period observation of inventory depletion timelines, RoHS exemption negotiation status, and defense procurement specification revisions anchored the trend analysis, supplemented by interviews with oscilloscope OEM procurement directors, defense maintenance depot supply officers, medical imaging equipment regulatory affairs leads, and CRT refurbishment facility operations managers. Secondary validation drew from EPA universal waste rule filings, ECHA REACH substance restriction updates, METI JIS standard electron gun emission documentation, and customs records of leaded glass tube shipments. Bottom-up demand aggregation across end-use segments triangulated against top-down supply capacity assessments from Asian foundry disclosures.
Segment-weighting across product type, application, technology, and end-user dimensions shaped the analytical framework, with additional modeling of certification-grade stratification for defense and medical imaging procurement channels. CAGRs were derived from replacement cycle duration analysis and inventory depletion trajectory modeling. Forecast inputs incorporated electron gun assembly technician retirement curves, phosphor coating facility environmental containment investment viability, and flat-panel substitution penetration rates in broadcast monitoring applications.
The model holds under stable regulatory exemption status for leaded glass in medical and defense applications; deviation in RoHS directive revision outcomes or REACH substance threshold tightening would shift refurbishment economics and inventory valuation assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Port Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Light Field Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Screenless Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Backlit Displays Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Global Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Global LED Digital Signage Market