
 Coated Silicon Wafer Market | 2026-2036
Coated Silicon Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Silicon Wafer Market Insights
Gallium nitride is expanding its addressable footprint in power electronics, displacing conventional silicon substrates in high-frequency, high-temperature applications. Shin-Etsu Handotai leverages captive polysilicon supply to anchor margin stability across coated wafer grades. SUMCO Corporation sustains technology leadership through epitaxial process refinement for automotive-grade substrates. SK Siltron Co., Ltd. dominates Korean semiconductor supply chains with vertically integrated crystal growth through final polish operations.
Coated silicon wafers are monocrystalline silicon discs with engineered surface layers—oxides, nitrides, or metals—deposited via chemical vapor deposition or atomic layer deposition to achieve precise thickness control within angstrom tolerances. These substrates enable pattern transfer fidelity in photolithography and electrical isolation in finished devices. Epitaxial-coated wafers command premium positioning due to defect density requirements in RF device fabrication, while SOI substrates lead growth trajectories driven by power electronics leakage reduction needs. Double-sided coatings retain mature volume positions in sensor applications where cost sensitivity constrains process migration.
Japan's METI enforces JIS standards for wafer surface metal contamination that dictate coating chemistry selection and qualification timelines. South Korea's MFDS coordinates with METI on cross-border material certification reciprocity, smoothing supply chain access for coated substrate imports. China's SAMR and GB standards mandate domestic traceability for silicon used in strategic semiconductor applications, reshaping supplier qualification protocols. Stakeholders must monitor evolving dual-use export control alignments between East Asian regulators to anticipate coating equipment and precursor material access constraints.
Market Dynamics
Advanced node lithography below 7nm is compressing defect tolerance thresholds, forcing fabs to migrate from thermal oxide coatings to atomic layer deposition for angstrom-scale uniformity control.
Growth Catalysts
- Epitaxial wafer demand:RF device manufacturers are scaling procurement of defect-controlled substrates for 5G base station amplifiers and radar modules.
- China's material purity mandates:NMPA and MIIT standards for domestic chip self-sufficiency are accelerating qualification of locally produced coated wafers for strategic semiconductor applications.
- Power electronics leakage reduction:Silicon-on-insulator substrates are capturing design wins in electric vehicle inverters where thermal management constraints dominate system architecture.
Market Restraints
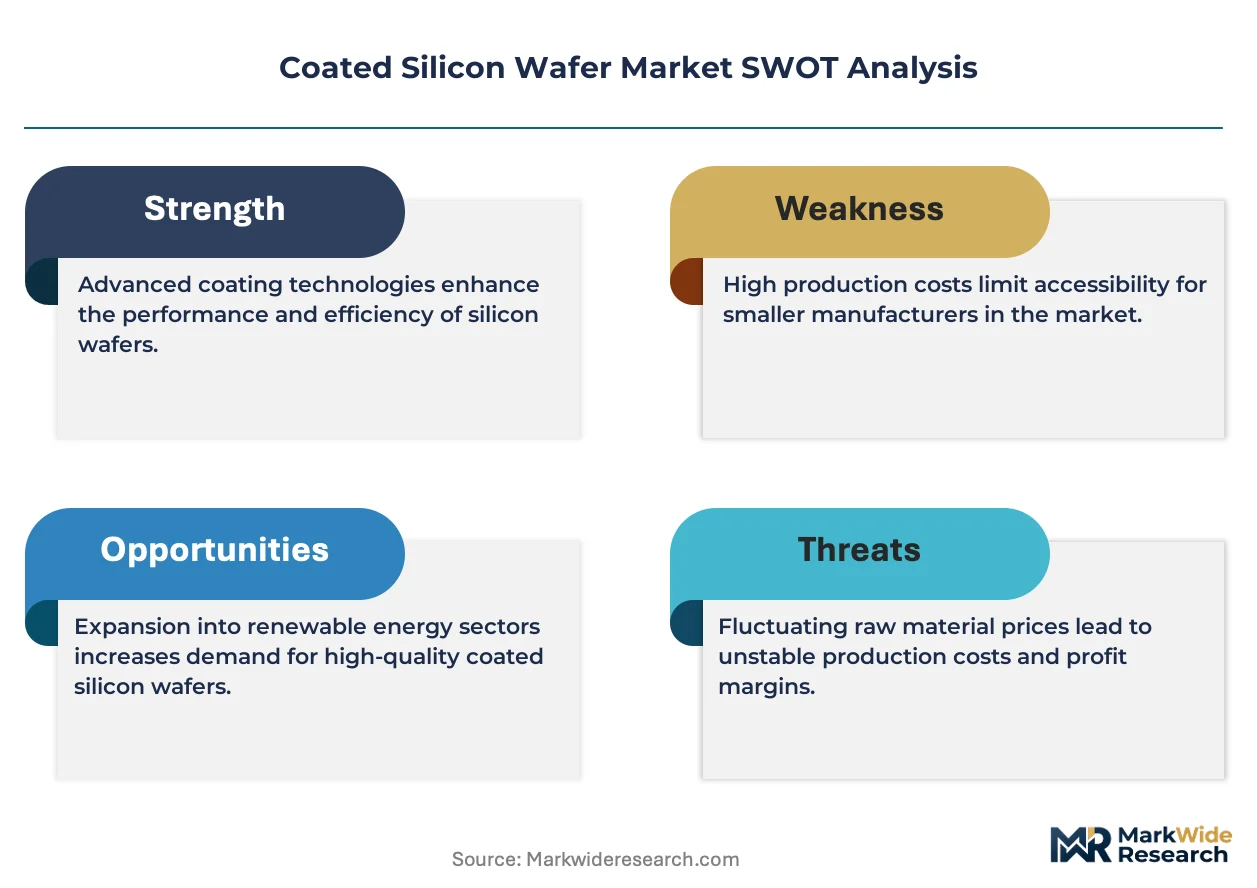
- Polysilicon feedstock volatility:Energy-intensive Siemens process economics tie coating cost structures to regional electricity pricing and carbon border adjustments.
- Equipment import dependencies:East Asian fabrication clusters concentrate critical chemical vapor deposition tool supply, creating single-source vulnerability for new market entrants.
- Gallium nitride substitution:Wide-bandgap semiconductors are capturing frequency and thermal performance requirements that previously mandated premium epitaxial silicon substrates.
Strategic Opportunities
- Automotive-grade substrate certification:AEC-Q100 qualification protocols are opening volume procurement channels for coated wafers in autonomous sensor and powertrain modules.
- India's semiconductor PLI scheme:Domestic fabrication incentives are creating first-mover advantage for coating technology transfer and localized epitaxial production partnerships.
- Double-sided coating sensor applications:Cost-sensitive industrial IoT and medical imaging markets present volume expansion paths for mature process technologies.
Industry Challenges
- Atomic layer deposition technician scarcity:Angstrom-level process control expertise resides in a limited pool of specialists concentrated in Japanese and Korean equipment vendor ecosystems.
- Cross-border precursor material certification:Divergent metal contamination standards between Japan's METI JIS requirements and China's SAMR traceability mandates are elongating qualification timelines for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Silicon Wafer Market |
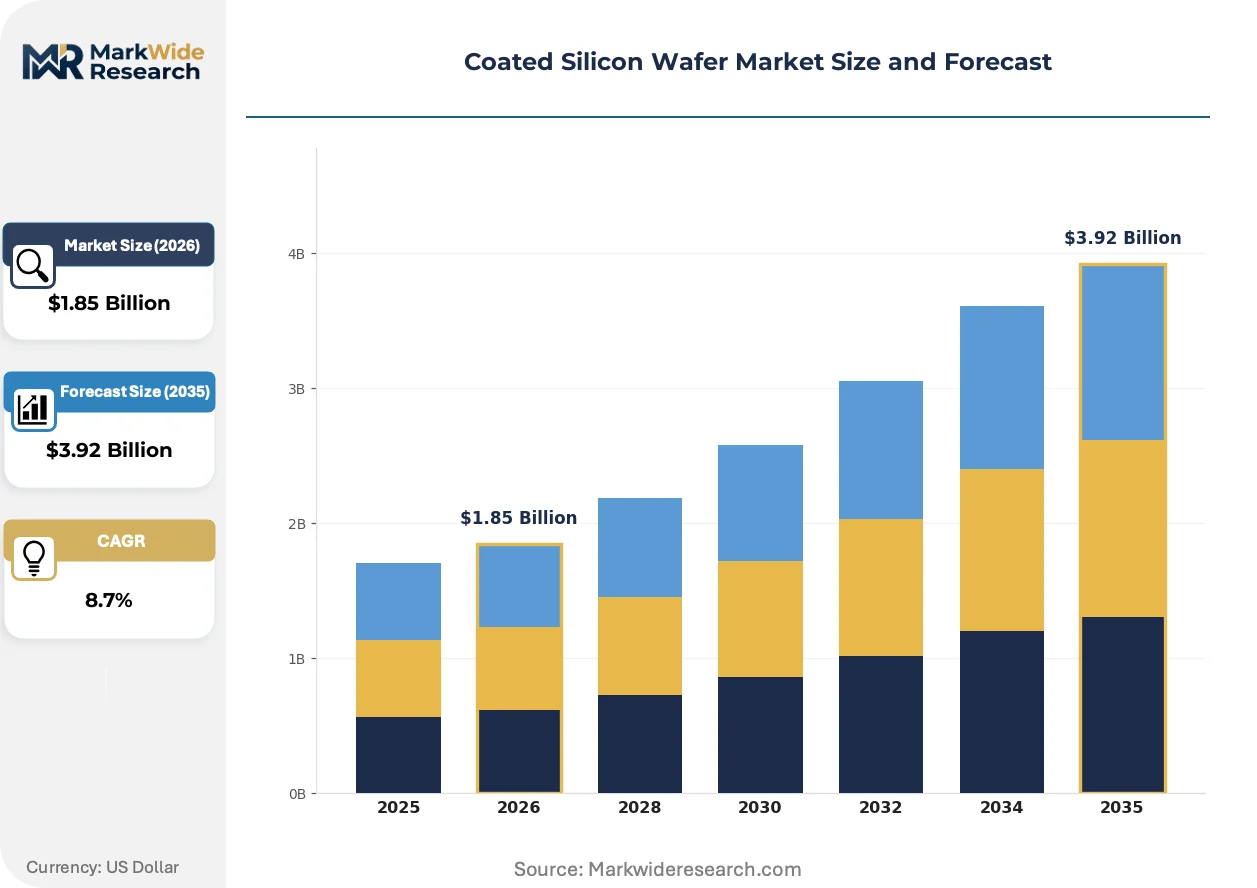
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Epitaxial, SOI End User: Semiconductors, Electronics, Solar Cells, LEDs Application: Power Electronics, RF Devices, Optoelectronics, Sensors Technology: Photolithography, Etching, CVD, ALD |
| Companies Covered | Shin-Etsu Handotai, SUMCO Corporation, GlobalWafers Co., Ltd., Siltronic AG, SK Siltron Co., Ltd., Wafer Works Corporation, Okmetic Oy, LG Siltron Inc., REC Silicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Silicon Wafer Market Trends and Innovations
Process control automation and regulatory fragmentation are reshaping competitive advantage in coated wafer manufacturing, with differentiation shifting from material purity to deposition precision and certification agility.
Atomic layer deposition is automating thickness uniformity control across 300mm wafer surfaces, enabling single-digit angstrom repeatability that thermal oxidation cannot achieve. Memory and logic fabs at 5nm and below are mandating ALD for gate oxide and high-k dielectric stacks. This precision is compressing yield loss from coating non-uniformity, reducing scrap rates in high-volume production environments.
REACH substance restrictions are forcing reformulation of coating precursors containing heavy metal contaminants, particularly for organometallic compounds used in barrier layer deposition. European equipment vendors are accelerating qualification of alternative chemistries to maintain market access. Automotive and medical device segments are responding fastest, as these verticals face concurrent MDR and EU Green Deal compliance pressures.
Long-term supply agreements with fixed pricing mechanisms are displacing spot market purchasing for epitaxial-grade substrates, as fabs seek insulation from polysilicon cost swings. Tier-one foundries in Taiwan and Korea are locking multi-year coating capacity through direct equipment co-investment models. This consolidation is most visible in RF and power device supply chains where substrate performance directly determines end-product specifications.
Coated Silicon Wafer Market Segmentation
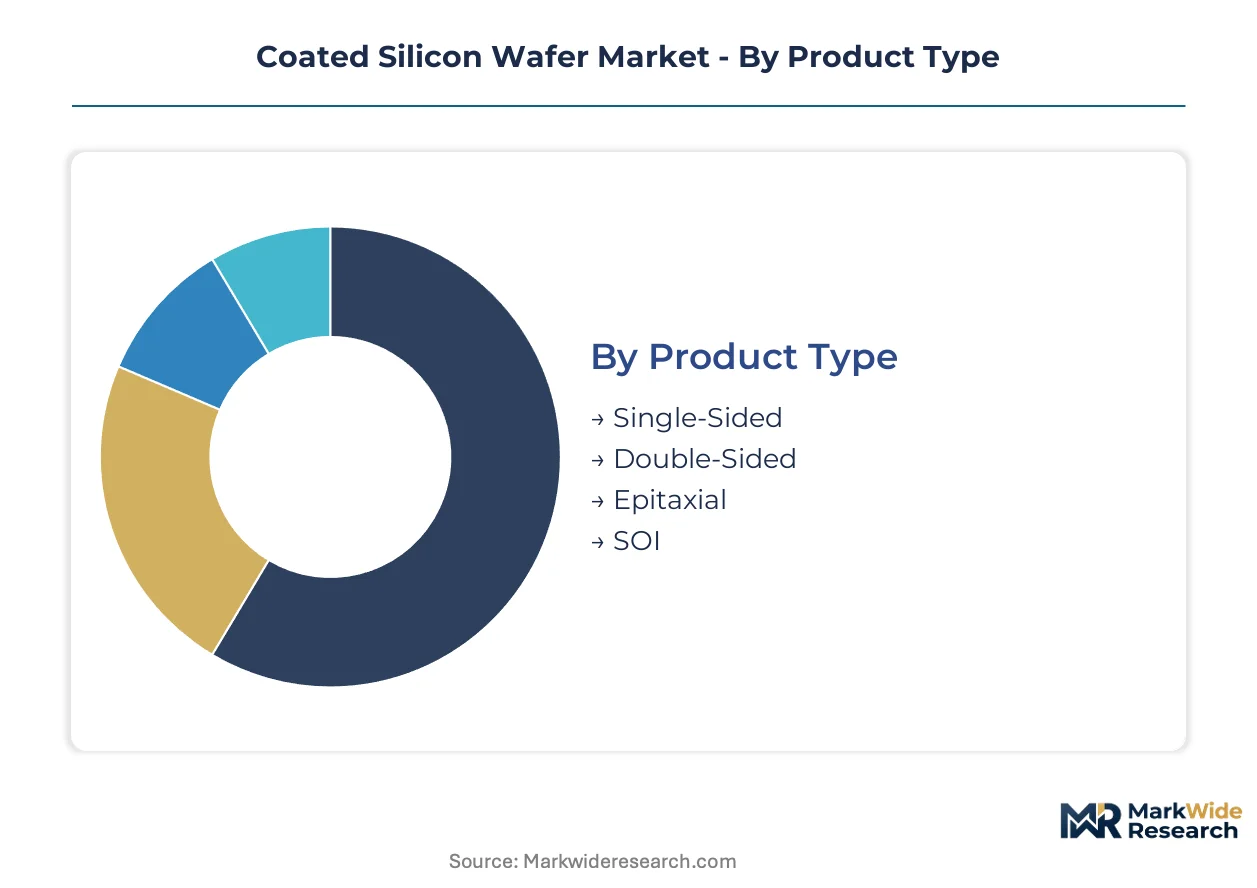
Process migration from thermal oxidation to atomic layer deposition is fragmenting procurement patterns across wafer grades. fabs now segment suppliers by deposition precision capability rather than bulk silicon quality alone.
Product Type:
Equipment upgrade cycles favor substrates compatible with existing thermal oxidation tools while next-generation fabs demand ALD-ready specifications.
- Epitaxial:Defect-controlled monocrystalline layers deposited via vapor-phase epitaxy achieve sub-1/cm² dislocation densities mandatory for RF power amplifiers. 5G base station manufacturers in Taiwan and Korea are locking multi-year supply agreements for 150mm and 200mm diameters.
- SOI:Buried oxide layers eliminate latch-up in high-voltage power electronics while reducing parasitic capacitance. Electric vehicle inverter designers specify SOI for thermal management performance that silicon substrates cannot match.
- Single-Sided:One-face coatings dominate legacy CMOS logic production where cost sensitivity constrains process migration.
- Double-Sided:Symmetrical surface engineering serves pressure sensor and MEMS applications requiring matched thermal expansion coefficients.
Volume placements concentrate in Single-Sided wafers; the faster expansion belongs to Epitaxial grades.
End User:
Customer procurement sophistication separates volume buyers with captive metrology capabilities from price-sensitive assemblers dependent on supplier certificates.
- Semiconductors:Foundries and IDMs specify coating thickness uniformity within ±3% across 300mm surfaces for sub-7nm lithography. Japan's METI JIS standards and China's SAMR traceability mandates are elongating qualification timelines for multi-region suppliers.
- Electronics:Consumer device assemblers prioritize lot-to-lot consistency over absolute precision, accepting ±10% uniformity tolerances for display driver IC substrates.
- Solar Cells:Photovoltaic manufacturers utilize lower-grade coatings for anti-reflection layers where spectral performance outweighs defect density metrics.
- LEDs:Sapphire substrate alternatives dominate solid-state lighting, constraining silicon wafer penetration to specialized UV-C applications.
Procurement scale favors Semiconductor buyers; Electronics assemblers are gaining share fastest in cost-optimized regional supply chains.
Application:
End-use thermal and frequency specifications dictate coating chemistry selection more than wafer diameter or crystal orientation.
- Power Electronics:Silicon carbide and gallium nitride are displacing silicon in 650V+ applications, compressing addressable market for coated silicon substrates in electric vehicle traction inverters.
- RF Devices:Base station amplifiers and radar modules demand epitaxial layers with precise doping profiles for impedance matching. Korea's MFDS coordinates with Japan's METI on cross-border material certification reciprocity for defense-adjacent applications.
- Optoelectronics:Photodetector arrays utilize anti-reflection coatings with controlled refractive index gradients.
- Sensors:Industrial IoT deployments favor double-sided coatings for pressure transducers where hermetic sealing requirements dominate specification sheets.
RF Devices command premium positioning; Sensor applications are climbing the fastest as automotive qualification protocols mature.
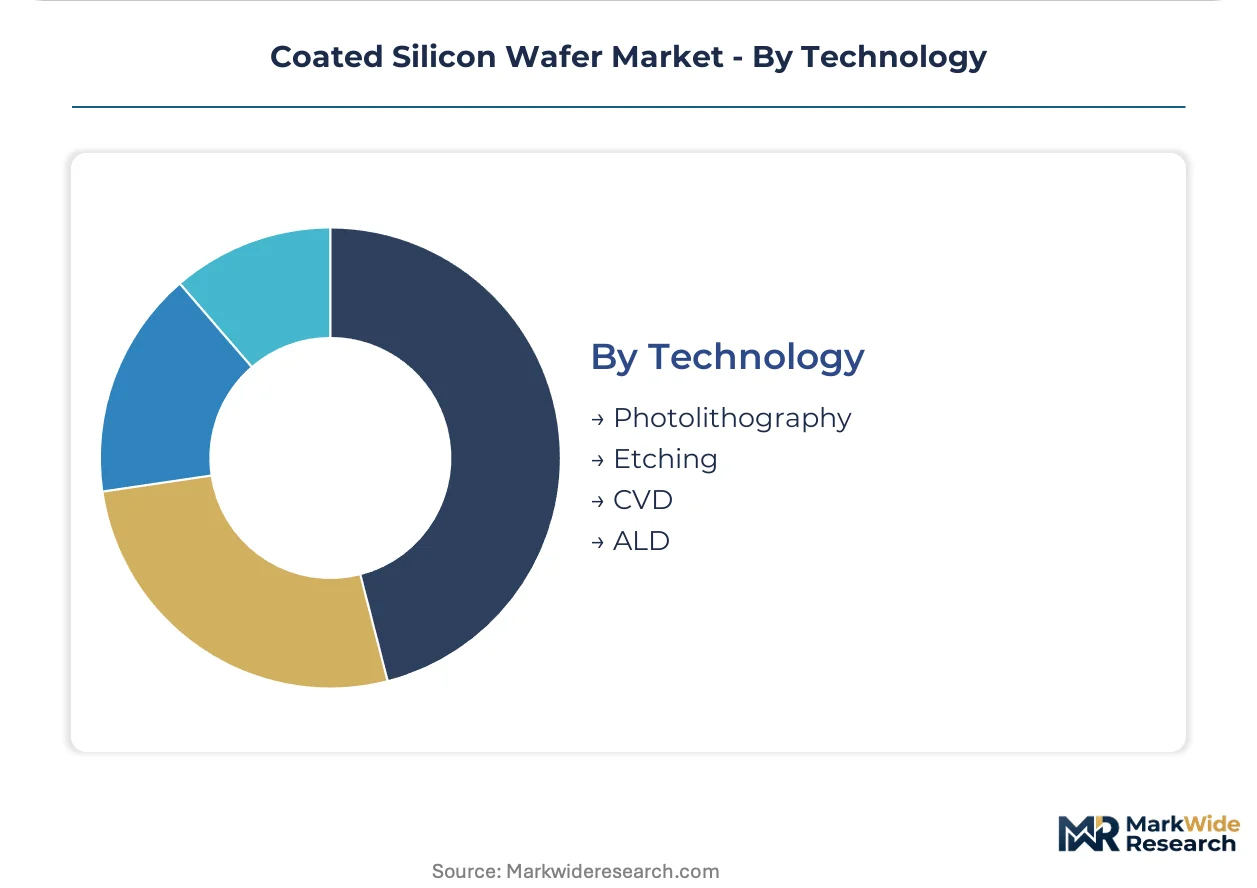
Technology:
Deposition tool availability constrains coating technology adoption more than substrate demand or precursor chemistry maturity.
- ALD:Self-limiting surface reactions achieve angstrom-scale thickness control across 300mm wafers. Memory fabs at 5nm and below mandate ALD for high-k dielectric stacks.
- CVD:Plasma-enhanced and low-pressure variants retain volume positions in mature node production where throughput economics outweigh uniformity precision.
- Photolithography:Pattern transfer processes utilize coated wafers as mechanical carriers rather than active coating beneficiaries.
- Etching:Plasma and wet chemical removal processes expose coating-substrate interface integrity to thermal cycling stress.
Capital deployment concentrates in ALD; CVD retains installed base protection in cost-optimized fabrication lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters concentrate coated wafer production within special economic zones offering tax holidays for semiconductor capital equipment. China's Hengqin and South Korea's Yongin semiconductor valleys anchor multi-billion-dollar substrate supply chains serving advanced node foundries.
China
Domestic foundries in Yangtze River Delta clusters are scaling epitaxial wafer procurement for 14nm node production. NMPA and MIIT purity mandates for strategic semiconductor applications are accelerating local supplier qualification timelines. Shanghai's Zhangjiang Hi-Tech Park hosts coating equipment co-investment partnerships between state-backed funds and Japanese tool vendors.
Japan
Silicon carbide power device manufacturers in Kyushu are sourcing defect-controlled substrates for automotive inverter modules. METI enforces JIS surface metal contamination standards that dictate coating chemistry selection for export-qualified wafers. Hiroshima's semiconductor corridor maintains captive polysilicon-to-coating vertical integration through integrated chemical suppliers.
South Korea
Memory fabs in Yongin and Pyeongtaek are mandating ALD-ready specifications for high-k dielectric stacks at sub-5nm nodes. MFDS coordinates cross-border material certification reciprocity with Japan's METI for defense-adjacent RF applications. Busan-Ulsan industrial complexes house vertically integrated crystal growth through final polish operations serving Samsung and SK Hynix supply chains.
Taiwan
Foundries in Hsinchu Science Park are locking multi-year coating capacity agreements through direct equipment co-investment models. The National Science and Technology Council subsidizes domestic precursor material development to reduce import dependencies. Tainan's Southern Taiwan Science Park clusters epitaxial wafer production for 5G base station amplifier supply chains.
United States
Power electronics designers in Texas and Arizona are specifying SOI substrates for electric vehicle inverter thermal management. CHIPS Act funding flows to domestic wafer fabrication facilities seeking coating technology transfer partnerships. Phoenix's semiconductor corridor attracts epitaxial equipment vendors establishing North American service hubs.
Coated Silicon Wafer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive foundry suppliers commanding premium-tier positioning and independent merchants serving cost-optimized regional markets. The vendor base concentrates around three strategic archetypes: polysilicon-integrated upstream controllers, deposition-technology specialists, and foundry-captive fabricators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players seek ALD process expertise.
Among Japanese upstream controllers, Shin-Etsu Handotai and SUMCO Corporation exemplify polysilicon-integrated archetypes that anchor margin stability through captive feedstock supply. SK Siltron Co., Ltd. occupies a position within the Korean foundry-captive tier, serving vertically integrated demand from domestic memory and logic manufacturers. These three entities represent distinct geographic and structural approaches to coated wafer supply security.
| Leading Market Players |
|---|
| Shin-Etsu Handotai |
| SUMCO Corporation |
| GlobalWafers Co., Ltd. |
| Siltronic AG |
| SK Siltron Co., Ltd. |
| Wafer Works Corporation |
| Okmetic Oy |
| LG Siltron Inc. |
| REC Silicon |
| Others |
Pricing and Supply Chain Analysis
Polysilicon spot price volatility on the Shanghai Metals Market cascades through coating cost structures into three-tier pricing stratification across premium epitaxial, standard SOI, and economy-grade single-sided wafer tiers. Foundries with captive polysilicon supply command margin insulation unavailable to merchant coaters exposed to Siemens process energy cost swings.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines reward suppliers with unallocated ALD capacity serving RF device manufacturers facing sudden 5G base station amplifier demand spikes. Contract-based long-term offtake agreements dominate procurement for sub-7nm logic fabs, while spot purchasing persists in cost-optimized sensor applications. Price differentiation hinges on AEC-Q100 automotive certification tier and volume scale commitments. Cost compression in economy-grade single-sided wafers is intensifying because Chinese domestic suppliers are qualifying under NMPA purity mandates. Display driver assemblers in consumer electronics show highest price sensitivity; automotive power module designers accept premium positioning for defect-controlled epitaxial grades.
Supply Chain Analysis
Dual-sourcing requirements from Taiwan foundries and Korean memory manufacturers mandate multi-supplier qualification for ALD precursors and polysilicon feedstock, elongating vendor onboarding to eighteen-month cycles. Geographic supply concentration centers on Japan, South Korea, and Taiwan for coating equipment and precursor synthesis. Raw material dependencies draw from high-purity polysilicon, organometallic precursors, and specialized quartzware. Single-source vulnerability concentrates in Tokyo Electron and ASM International ALD tool architectures. Distribution runs through foundry-direct contracts with equipment co-investment clauses, bypassing traditional merchant wafer distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coated silicon wafer market reads as a cost-of-compliance story where Japan's METI JIS surface metal contamination standards and China's SAMR traceability mandates erect barrier-to-entry moats favoring incumbents with established multi-regulator qualification dossiers.
For Market Incumbents: Deploy equipment co-investment partnerships as the primary lever to lock multi-year capacity commitments from Taiwan and Korea foundries. Capture backward integration into organometallic precursor synthesis to insulate margin structures from REACH-driven chemistry reformulation costs. Gallium nitride substitution in 650V+ power electronics represents the core technology threat requiring epitaxial performance differentiation. For New Entrants and Emerging Players: Direct-to-foundry digital qualification portals bypass incumbent distributor networks and accelerate SAMR traceability documentation for Chinese domestic fab procurement. Target India's semiconductor PLI scheme subsidy window for first-mover coating technology transfer partnerships. Automotive-grade sensor applications present the most penetrable white-space segment given AEC-Q100 protocol maturation. For Investors and Strategic Acquirers: Distressed-cycle entries favor polysilicon-integrated mid-cap specialists in Kyushu and Hiroshima corridors with dormant ALD capacity expansion permits. Long-term viability over the coming decade hinges on atomic layer deposition technician pipeline depth and cross-border precursor certification agility. Watch for MFDS-METI reciprocity agreement expansions as the signal indicating regional supply chain access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Capacity Expansion | Enables angstrom-scale uniformity for sub-5nm memory and logic node production. |
| Backward Integration into Precursor Synthesis | Insulates margin structures from ECHA REACH substance restriction-driven chemistry reformulation. |
| Automotive-Grade Substrate Certification | Opens AEC-Q100 volume procurement channels for electric vehicle inverter and sensor modules. |
| Long-Term Foundry Co-Investment Partnership | Locks multi-year coating capacity through direct equipment placement at Taiwan and Korea fabs. |
| Cross-Border Regulatory Reciprocity Engagement | Accelerates MFDS-METI material certification alignment for defense-adjacent RF applications. |
Research Methodology
Document review covered SEC 10-K filings from listed wafer manufacturers, METI JIS standard documentation, and customs trade data for polysilicon and coated wafer movements, complemented by interviews with epitaxial process engineers, foundry procurement directors, ALD equipment vendor application specialists, and automotive Tier 1 substrate qualification managers. Secondary validation drew from SEMI industry statistics, China SAMR regulatory bulletins, and Korea MFDS certification registries. Bottom-up wafer shipment data triangulated against top-down fabrication capacity expansion announcements.
Cross-referencing historical pricing elasticity against panel input from equipment vendors and foundry planners anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include coating technology tier, wafer diameter specification, end-use industry vertical, and regional regulatory cluster. CAGRs derived from shipment volume trajectories weighted by foundry capex cycle phasing and polysilicon feedstock contract renegotiation patterns.
The model holds under sustained East Asian fabrication cluster concentration and stable dual-use export control alignments; deviation in METI-SAMR regulatory divergence or gallium nitride penetration acceleration beyond power electronics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Data Processing Unit Market