
 Electronics Control Management Market | 2026-2036
Electronics Control Management Market Size, Share, and Industry Trends Forecast 2026-2036
Electronics Control Management Market Analysis
Automotive-grade ASIL-D certification is redrawing competitive boundaries in electronics control management. Robert Bosch GmbH leverages captive semiconductor fabrication and systems integration to dominate safety-critical chassis control. Continental AG differentiates through embedded software stacks that span powertrain, braking, and body electronics. Denso Corporation anchors its position in thermal management and electrification control with manufacturing scale across Japan, China, and North America.
Electronics Control Management comprises the hardware, firmware, and communication architectures that govern real-time sensing, decision-making, and actuation in electromechanical systems, typically operating with sub-millisecond latency and ISO 26262 functional-safety compliance. Its primary purpose is to ensure deterministic performance across automotive, aerospace, and industrial automation environments where failure carries catastrophic cost. Embedded Systems and IoT technology segments command the deepest engineering investment, as edge-computing requirements and over-the-air update capabilities expand firmware complexity. Controllers and Sensors product categories occupy the largest volume positions, though Actuators generate disproportionate margin pools in precision-motion applications such as electric steering and brake-by-wire systems.
FDA, NHTSA, and ISO standards collectively shape validation protocols, cybersecurity mandates, and traceability requirements that determine market access for control-system suppliers. REACH and RoHS constraints in Europe plus China's GB standards for electromagnetic compatibility add compliance layers that favor vertically integrated manufacturers with in-house testing laboratories. Stakeholders must monitor how functional-safety tiering and regional certification divergence affect platform economics and sourcing geography.
Market Dynamics
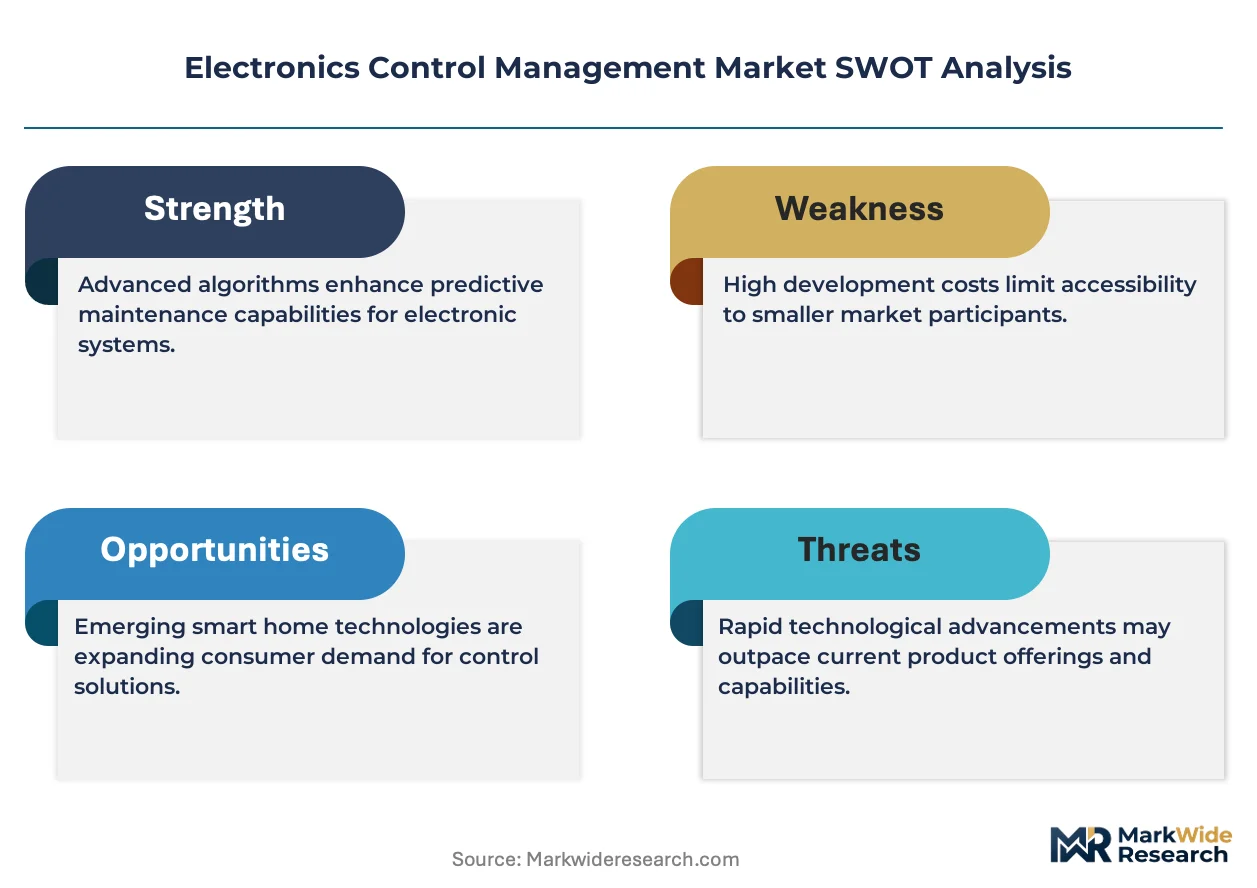
Electrification mandates and ASIL-D functional-safety certification are compressing development cycles and redrawing supplier hierarchies across automotive control systems. Tier-one manufacturers now demand captive semiconductor capacity and firmware traceability that smaller vendors cannot replicate.
Growth Catalysts
- EU AI Act compliance deadlines:Automotive OEMs in Germany and France are accelerating procurement of verified AI-enabled chassis controllers to meet algorithmic transparency requirements before enforcement phases begin.
- Electric powertrain sensor fusion:Battery management systems require synchronized thermal and voltage monitoring, expanding addressable controller content per vehicle by 40-60 discrete sensing nodes.
- South Korean foundry capacity expansion:Samsung and SK Hynix are dedicating 8-inch automotive-grade wafer starts to control module suppliers, easing prior procurement bottlenecks for silicon carbide gate drivers.
Market Restraints
- Neon gas supply concentration:Ukrainian and Russian noble gas purification facilities supply 90% of semiconductor-grade neon for deep-UV lithography, exposing controller chip production to geopolitical supply shocks.
- ASIL-D certification timeline:ISO 26262 functional-safety validation requires 18-24 months of fault-injection testing, freezing out new entrants from safety-critical braking and steering contracts.
- Legacy 12V architecture persistence:Internal combustion vehicle platforms in emerging markets delay 48V mild-hybrid adoption, constraining advanced power electronics controller volumes.
Strategic Opportunities
- India PLI scheme for automotive electronics:Tier-two cities including Pune and Chennai are attracting control module assembly investments with 25% capex-linked incentives and reduced import duties on semiconductor testing equipment.
- Over-the-air firmware monetization:Subscription-based feature activation for ADAS calibration and powertrain optimization creates recurring revenue streams detached from hardware shipment cycles.
- Digital twin convergence with edge AI:Real-time physics simulation paired with onboard neural inference enables predictive thermal management in electric commercial vehicles.
Industry Challenges
- Embedded cybersecurity engineering scarcity:NHTSA and UNECE R155 mandates require hardware security module integration, but qualified firmware architects command 40% salary premiums over general automotive software roles.
- Multi-domain controller integration complexity:Consolidating powertrain, chassis, and body electronics onto zonal architectures forces suppliers to reconcile conflicting real-time operating system requirements and supplier IP boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronics Control Management Market |
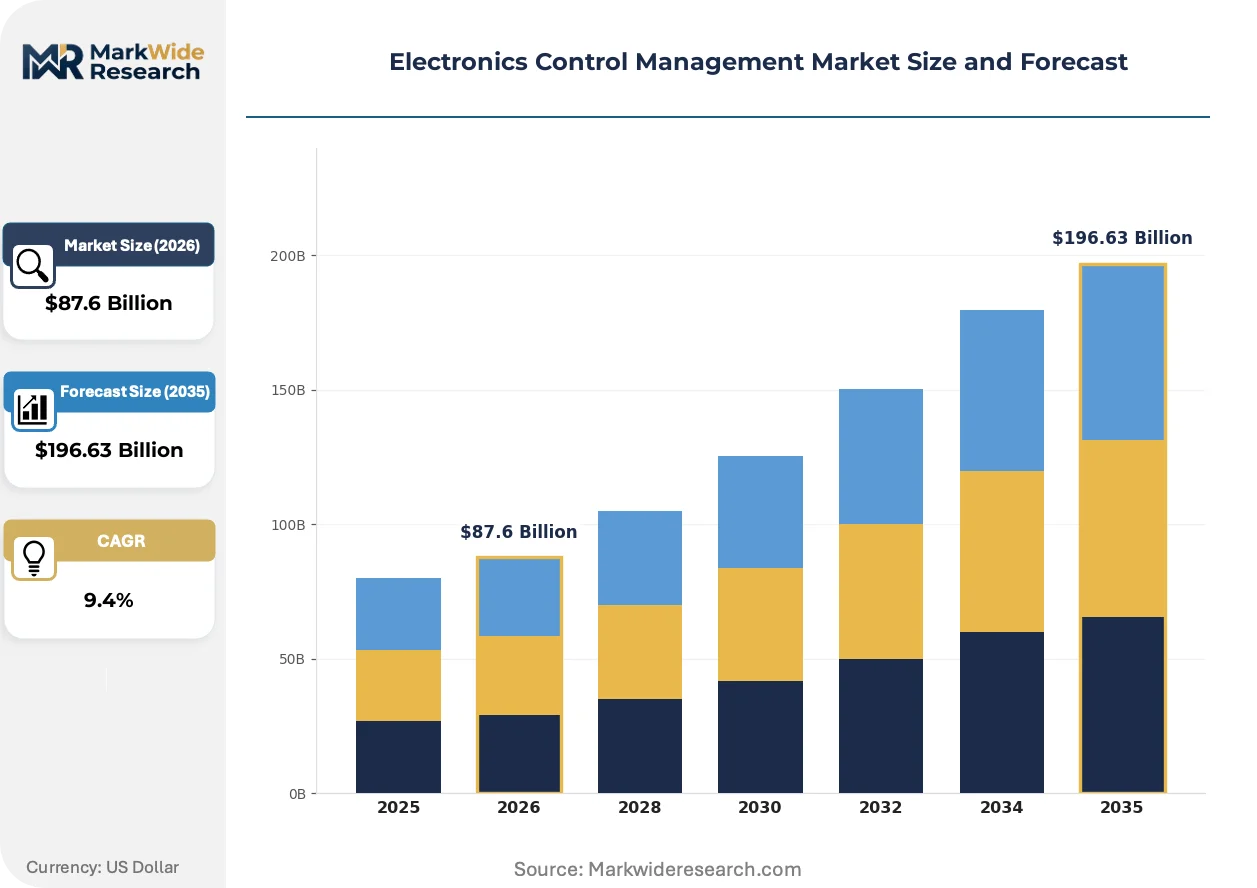
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Actuators, Interfaces Technology: Embedded Systems, Wireless Communications, IoT, Robotics End User: Automotive, Aerospace, Manufacturing, Consumer Electronics Application: Process Automation, Vehicle Control, Home Automation, Smart Grid |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, ZF Friedrichshafen AG, Aptiv PLC, Autoliv Inc., Hyundai Mobis Co., Ltd., Hitachi Astemo, Ltd., Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronics Control Management Market Emerging Trajectories
Deterministic edge computing and zonal electrical architectures are collapsing the traditional distributed ECU model into fewer, more powerful domain controllers. This compression demands new semiconductor packaging approaches and software isolation techniques.
Silicon carbide MOSFET gate drivers are fragmenting the power electronics controller landscape. These devices enable 800V battery architectures with switching losses below silicon IGBT thresholds. German and Japanese OEMs are qualifying SiC-based inverter modules for 2026 platform launches. The technology is fragmenting procurement patterns as vertically integrated suppliers capture inverter-controller integration contracts previously split across tier-two vendors.
REACH substance restrictions on PFAS and halogenated flame retardants are forcing substrate material substitutions in printed circuit board laminates. European control module suppliers must validate alternative dielectric materials by 2026 to maintain CE marking eligibility. Automotive-grade PCB fabricators in Germany and Austria are investing in ceramic-filled hydrocarbon resin qualification to preserve supply continuity.
Buyer concentration among battery-electric vehicle platforms is compressing controller supplier negotiation leverage. Volkswagen, Tesla, and BYD collectively specify 60% of global BMS controller volumes, extracting multi-year price-down commitments and open-source firmware requirements. This concentration is most visible in China, where domestic OEMs now mandate controller hardware designs with full software stack visibility for cybersecurity audit compliance.
Electronics Control Management Market Segmentation
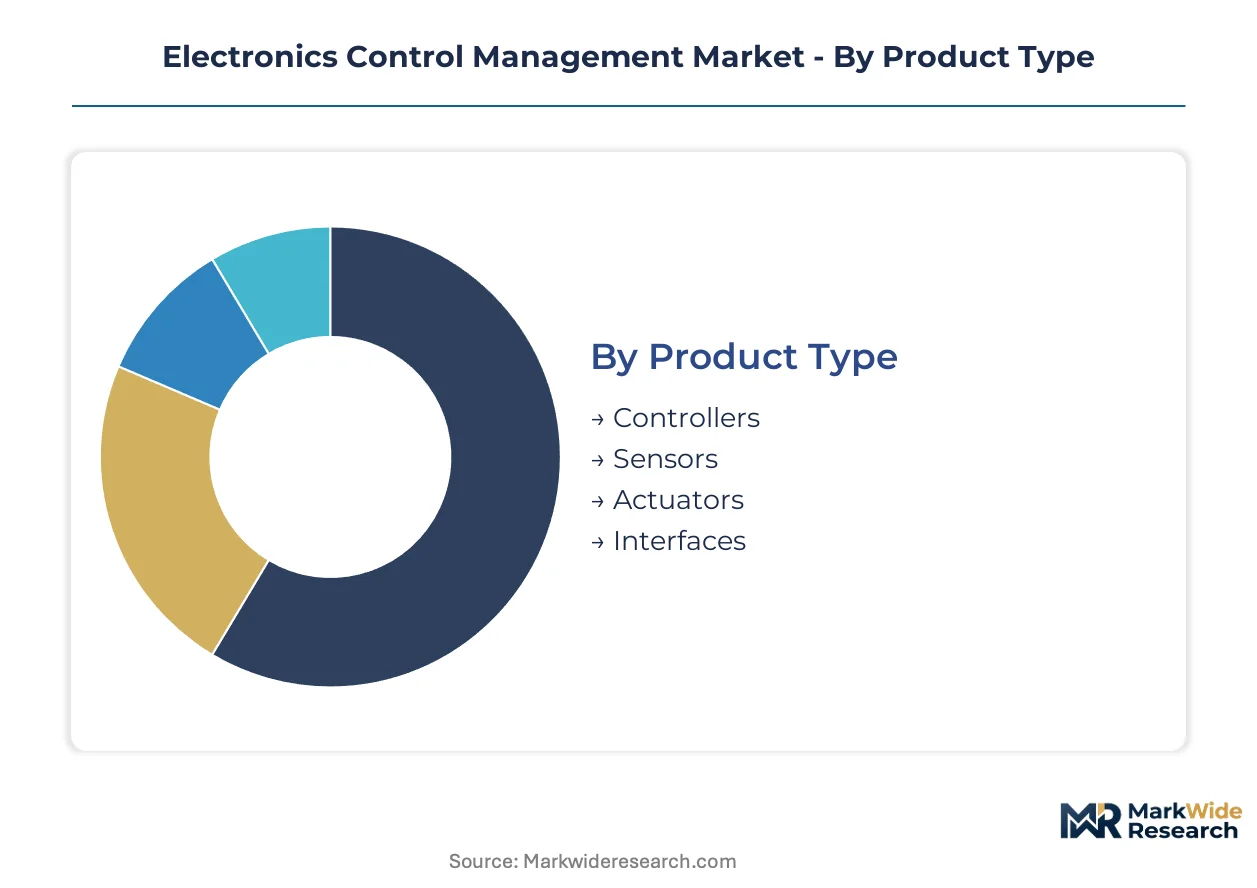
Electronics Control Management segmentation reveals divergent margin economics across hardware, software, and integration layers. Product architecture choices determine certification burden, semiconductor content, and aftermarket serviceability. Technology and end-use splits expose which application clusters absorb premium pricing for deterministic performance.
Product Type:
Controllers capture the deepest margin pools through firmware licensing and ASIL-D certification premiums. Sensors and actuators compete on manufacturing scale and precision tolerances.
- Controllers:Domain controllers consolidate powertrain, chassis, and body electronics onto zonal architectures with sub-millisecond latency. Automotive OEMs in Germany and Japan prioritize captive controller development for electric powertrain integration, compressing tier-one supplier margins.
- Sensors:Synchronized thermal, voltage, and current sensing nodes expand 40-60 discrete units per battery-electric vehicle. South Korean foundries dedicate 8-inch automotive-grade capacity to silicon carbide gate driver integration, easing prior procurement bottlenecks.
- Actuators:Precision-motion components in electric steering and brake-by-wire systems.
- Interfaces:Human-machine interaction modules bridging physical and digital control planes.
Controllers hold installed capacity. Sensors are rotating up the share rankings.
Technology:
Embedded Systems and IoT concentrate engineering investment and edge-computing complexity. Wireless Communications and Robotics address narrower application sets with distinct connectivity or kinematic requirements.
- Embedded Systems:Real-time operating systems with ISO 26262 functional-safety compliance govern deterministic sensing and actuation. EU AI Act algorithmic transparency mandates are accelerating procurement of verified AI-enabled chassis controllers before enforcement phases begin.
- IoT:Over-the-air firmware update capabilities expand software complexity and enable subscription-based feature activation. NHTSA cybersecurity guidelines require hardware security module integration, but qualified firmware architects command salary premiums that constrain vendor scaling.
- Wireless Communications:Low-latency protocols for distributed control architectures.
- Robotics:Kinematic control systems for precision manufacturing and autonomous mobility.
Embedded Systems anchors current deployment volumes. IoT is climbing the fastest on connected feature monetization.
End User:
Automotive absorbs the dominant share of ASIL-D certified controller volumes. Aerospace, Manufacturing, and Consumer Electronics operate under less stringent functional-safety tiers with different procurement cycles.
- Automotive:Electric powertrain and ADAS platforms drive 800V battery architectures with silicon carbide MOSFET gate drivers. Volkswagen, Tesla, and BYD collectively specify the majority of global battery management system controller volumes, extracting multi-year price-down commitments.
- Manufacturing:Process automation controllers for industrial robotics and precision assembly lines.
- Aerospace:Flight-critical control systems with DO-178C software assurance requirements.
- Consumer Electronics:Cost-optimized control modules for home appliances and personal devices.
Automotive dominates current procurement. Manufacturing is gaining share fastest on industrial automation refresh cycles.
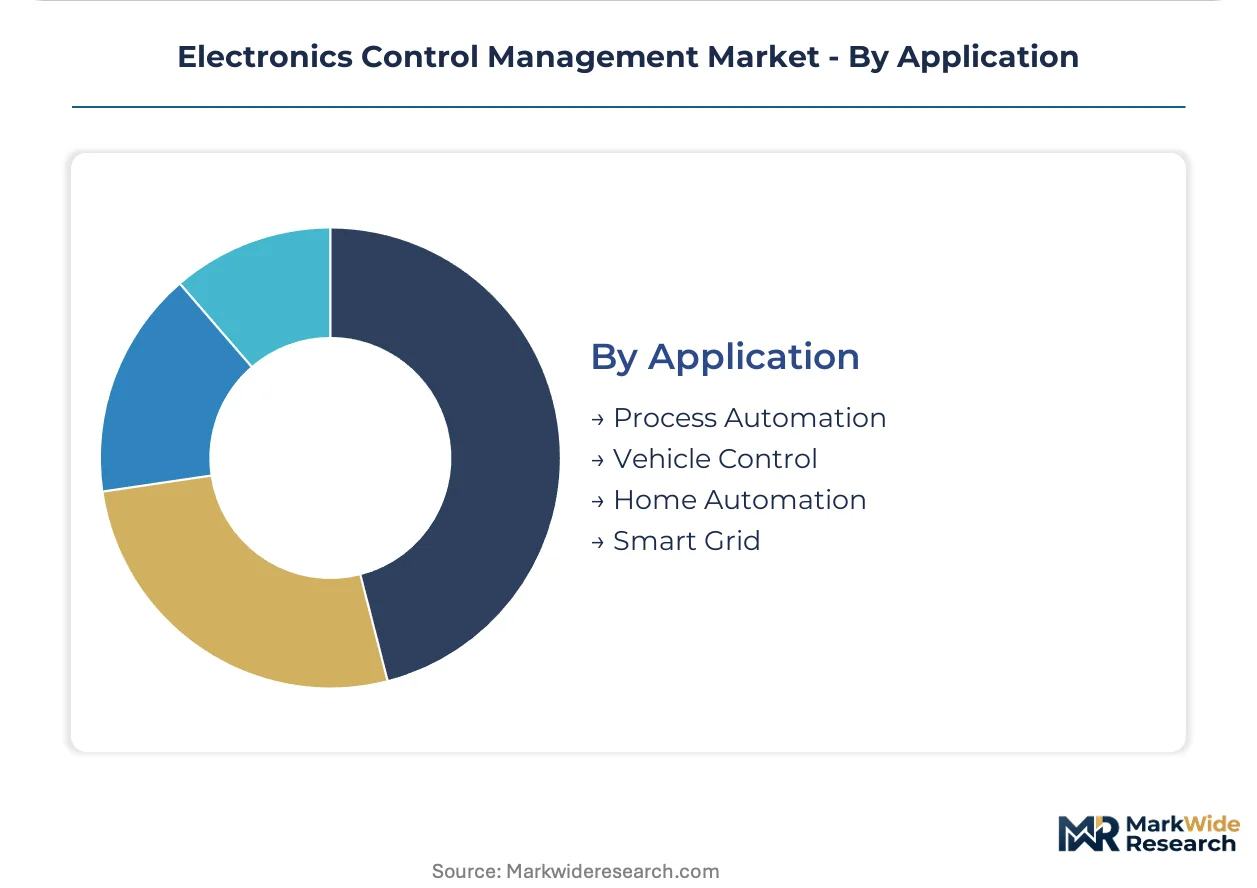
Application:
Vehicle Control and Process Automation concentrate premium pricing for deterministic performance. Home Automation and Smart Grid operate under lighter real-time constraints with volume-oriented economics.
- Vehicle Control:Domain controllers for electric powertrain, braking, and steering systems with failure-tolerant architectures. REACH and RoHS constraints in Europe force substrate material substitutions in printed circuit board laminates, requiring validation of alternative dielectric materials.
- Process Automation:Programmable logic controllers and distributed control systems for continuous manufacturing operations.
- Smart Grid:Grid-tied inverters and energy storage management controllers.
- Home Automation:Residential climate, lighting, and security control modules.
Vehicle Control holds the premium tier. Process Automation is expanding most quickly on factory digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller fabrication capacity clusters in Germany, Japan, and the United States, with tier-one suppliers demanding captive semiconductor capacity and firmware traceability that smaller vendors cannot replicate. This supply-side concentration shapes procurement geography across automotive electrification platforms.
United States
NHTSA cybersecurity guidelines and the Inflation Reduction Act's domestic content incentives are accelerating localized controller production for electric powertrains. Detroit-based OEMs are consolidating supplier bases around ASIL-D certified domain controllers. The Southeast manufacturing corridor spanning Tennessee and South Carolina is attracting battery management system assembly investments from tier-one electronics suppliers.
Germany
The EU AI Act's algorithmic transparency deadlines are compressing procurement timelines for AI-enabled chassis controllers. KBA type-approval requirements for functional safety are tightening validation protocols. The Stuttgart-Munich automotive belt remains the densest concentration of embedded control engineering, with suppliers qualifying silicon carbide inverter modules for 2026 platform launches.
China
GB standards for electromagnetic compatibility and MIIT mandates for automotive semiconductor self-sufficiency are reshaping procurement patterns. Domestic OEMs now require full software stack visibility for cybersecurity audit compliance. The Yangtze River Delta and Pearl River Delta clusters dominate battery management system controller volumes, with BYD and CATL extracting multi-year price-down commitments from suppliers.
Japan
METI's carbon neutrality roadmap and JIS functional-safety standards are driving thermal management controller demand for electrification platforms. Denso and Hitachi Astemo anchor manufacturing scale across Aichi Prefecture and Ibaraki. The Nagoya-Tokyo corridor concentrates precision actuator production for brake-by-wire and electric steering systems.
South Korea
Samsung and SK Hynix are dedicating 8-inch automotive-grade wafer starts to control module suppliers, easing prior procurement bottlenecks for silicon carbide gate drivers. MFDS-equivalent automotive reliability standards are aligning with global ASIL-D certification. The Seoul Capital Area and Busan-Ulsan corridor host the densest concentration of battery-electric vehicle controller demand from Hyundai and Kia platforms.
Electronics Control Management Market Vendor Landscape
Concentration sits with diversified tier-one automotive suppliers possessing captive semiconductor fabrication and systems integration capabilities. The market structure exhibits tiered consolidation: a top stratum of vertically integrated German and Japanese conglomerates, a middle tier of Korean and American suppliers scaling through foundry partnerships, and fragmented specialty actuator manufacturers. Three archetypes dominate—full-stack integrators controlling silicon through software, domain specialists in thermal and motion control, and contract manufacturers serving cost-optimized emerging market platforms. Competitive moves center on backward integration into semiconductor packaging and strategic licensing of over-the-air firmware update capabilities.
Within the full-stack integrator tier, Robert Bosch GmbH exemplifies the archetype combining captive semiconductor fabrication with chassis control systems integration. Denso Corporation occupies a position representing thermal management and electrification control specialists with manufacturing scale across multiple continents. Continental AG anchors the embedded software differentiation vector, spanning powertrain, braking, and body electronics stacks. These three entities sit within the premium certification tier where ASIL-D validation and firmware traceability create defensible positioning.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Autoliv Inc. |
| Hyundai Mobis Co., Ltd. |
| Hitachi Astemo, Ltd. |
| Valeo SA |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month ASIL-D certification lead times concentrate procurement leverage among captive semiconductor fabricators in Germany and Japan, compressing tier-two supplier margins while amplifying pricing power for vertically integrated domain controller specialists.
Pricing Analysis
ISO 26262 functional-safety tiering dictates the pricing tier structure across automotive electronics control management. Premium-mid-economy pricing differentiation separates ASIL-D certified chassis controllers from ASIL-B body electronics and uncertified aftermarket modules. Cost compression in standard-tier powertrain controllers is intensifying because Volkswagen, Tesla, and BYD extract multi-year price-down commitments through concentrated battery-electric vehicle procurement. Tier-two actuator manufacturers exhibit highest price sensitivity due to foundry dependency, while full-stack integrators with captive silicon fabrication maintain lowest sensitivity.
Supply Chain Analysis
Inventory buffers for automotive-grade silicon carbide gate drivers remain thin across tier-one controller suppliers, exposing procurement timelines to South Korean foundry allocation decisions. Semiconductor-grade neon purification concentrates in Ukrainian and Russian facilities, while 8-inch automotive wafer fabrication clusters in South Korea, Taiwan, and Japan. Controller chip production rests on noble gas supply continuity, ceramic-filled hydrocarbon PCB substrates, and rare-earth magnetic materials for precision actuators. Single-source vulnerability in deep-UV lithography gas supply generates structural risk. Distribution runs through OEM direct procurement with tier-one systems integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronics Control Management Market is recovering from semiconductor allocation constraints as South Korean foundry capacity expansion and zonal architecture standardization release pent-up controller demand across automotive electrification platforms.
For Market Incumbents: Fortify captive semiconductor packaging capabilities and firmware traceability systems to defend against emerging Chinese controller suppliers leveraging GB standard compliance and domestic OEM software visibility mandates. Prioritize backward integration into silicon carbide gate driver assembly and hardware security module integration to meet NHTSA cybersecurity guidelines and UNECE R155 mandates. For New Entrants and Emerging Players: Differentiate on over-the-air firmware subscription architectures and predictive thermal management algorithms for electric commercial vehicles. White-space opportunities concentrate in India's PLI scheme corridors around Pune and Chennai, where 25% capex-linked incentives and reduced semiconductor testing equipment duties lower entry barriers. Target tier-two actuator manufacturing for emerging market 12V legacy platforms with cost-optimized motion control modules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across domain controller development as zonal architecture consolidation forces multi-million-dollar firmware stack investments and ISO 26262 validation laboratory buildouts. Long-term viability favors vertically integrated suppliers with captive foundry partnerships and ASIL-D certification track records. Watch for inflection when Chinese OEMs relax software stack visibility requirements or when EU AI Act enforcement phases accelerate algorithmic transparency procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Module Qualification | German and Japanese OEMs are qualifying SiC-based designs for platform launches, fragmenting procurement patterns. |
| Over-the-Air Firmware Monetization | Subscription-based ADAS calibration creates recurring revenue streams detached from hardware shipment cycles. |
| Domain Controller Consolidation | Zonal architecture compression collapses distributed ECU models into fewer, more powerful controllers with software isolation. |
| Automotive-Grade PCB Material Substitution | REACH PFAS restrictions force European suppliers to validate ceramic-filled hydrocarbon resins for CE marking continuity. |
| India PLI Scheme Manufacturing Footprint | Tier-two cities attract control module assembly with capex incentives and reduced semiconductor testing duties. |
Methodological Framework
Desk research of SEC automotive supplier filings, vehicle production databases, and IHS Markit registration data preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and semiconductor foundry account managers. Primary fieldwork combined with secondary validation from regulatory filings including NHTSA cybersecurity guidelines, EU AI Act algorithmic transparency mandates, and MIIT automotive semiconductor directives. Bottom-up controller volume modeling triangulated against top-down electrification platform forecasts.
Variance decomposition across technology segments, product architectures, and regional regulatory clusters shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include vehicle propulsion architecture, functional-safety certification tier, content per vehicle, OEM procurement tier, and regional production cluster. CAGRs derived from fitted growth curves applied to electrification penetration assumptions and controller node expansion per battery-electric vehicle platform.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment, stable noble gas supply chains, or continued ASIL-D certification tiering would require recalibration. Forecasts reflect documented assumptions regarding foundry capacity expansion, regulatory enforcement timelines, and zonal architecture adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Monitor Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Latin America Gas Sensors Market