
 Dot-Matrix LCD Modules Market | 2026-2036
Dot-Matrix LCD Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Dot-Matrix LCD Modules Market Analytics
Passive-to-active matrix migration is tilting module architectures toward lower-power, higher-contrast designs for battery-backed applications. BOE Technology Group leverages captive glass and driver IC capacity to anchor cost positions in character LCD supply for white goods. Sharp Corporation sustains technology leadership in monochrome graphic formats through dedicated fab lines in Japan. Newhaven Display International specializes in small-batch, quick-turn customization for North American industrial OEMs.
Dot-matrix LCD modules are electro-optical display assemblies built from liquid crystal cells arranged in row-column addressable grids, typically operating at 5V logic levels with duty ratios between 1/8 and 1/64 depending on multiplex complexity. These modules render alphanumeric characters or bitmap graphics through segment or pixel activation, serving as human-machine interfaces where readability under ambient light and multi-decade operational life outweigh color fidelity requirements. Character LCD retains the largest shipment volume across smart meter and appliance segments, though graphic LCD commands wider unit margins due to custom controller firmware and broader addressable pixel arrays. Active matrix technology is displacing passive matrix in wearable and portable information displays where response time and viewing angle consistency matter, while resistive touch integration dominates industrial equipment for glove-compatible operation.
RoHS and REACH in Europe restrict hazardous substance thresholds in display module assemblies, compelling reformulation of solder joints and backlight phosphors. China's GB standards and MIIT directives mandate energy efficiency labeling for home appliances, indirectly specifying display module power budgets. The US FCC governs electromagnetic emissions from embedded display controllers in medical and automotive applications. Stakeholders must monitor divergence between regional substance restrictions and efficiency mandates when configuring platform display strategies across manufacturing footprints.
Market Dynamics
Passive-to-active matrix migration is compressing duty cycle requirements while EU substance restrictions and China's domestic fab consolidation reshape supplier hierarchies and procurement patterns across industrial display value chains.
Growth Catalysts
- REACH substance restrictions:European frameworks banning mercury and cadmium in backlight phosphors accelerate LED-based module redesigns, creating refresh demand across appliance OEM installed bases.
- Industrial HMI panels:Equipment manufacturers in automation and process control are specifying graphic LCD variants for operator interfaces requiring glove-compatible resistive touch layers.
- China's domestic fab consolidation:Vertically integrated glass and driver IC capacity in Chinese manufacturing clusters compresses lead times for character LCD procurement by white goods producers.
Market Restraints
- Indium tin oxide cost volatility:Transparent electrode material price swings constrain margin stability for mid-volume module assemblers dependent on spot market sourcing.
- Passive matrix technical ceiling:Duty ratio limitations above 1/64 multiplex complexity restrict addressable pixel density for high-information-density wearable applications.
- OLED substitution in consumer segments:Flexible organic display alternatives capture portable device sockets previously served by monochrome graphic modules.
Strategic Opportunities
- Medical device certification gap:FDA 510(k) pathway expertise among LCD module suppliers remains scarce, creating white space for qualified entrants in diagnostic equipment displays.
- ISO 13485 quality convergence:Medical-grade quality management integration with industrial module platforms enables cross-vertical scale without duplicate facility investment.
- Aftermarket service unbundling:Industrial OEMs are separating display module replacement from full system service contracts, opening direct spare parts channels bypassing original equipment integrators.
Industry Challenges
- Driver IC firmware customization:Graphic LCD controller programming expertise scarcity extends qualification timelines for specialized industrial applications requiring custom character sets or bitmap handling.
- Legacy 5V logic integration:Modern microcontroller 3.3V I/O architectures create level-shifting complexity when interfacing with established module designs, demanding additional BOM components and board space.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dot-Matrix LCD Modules Market |
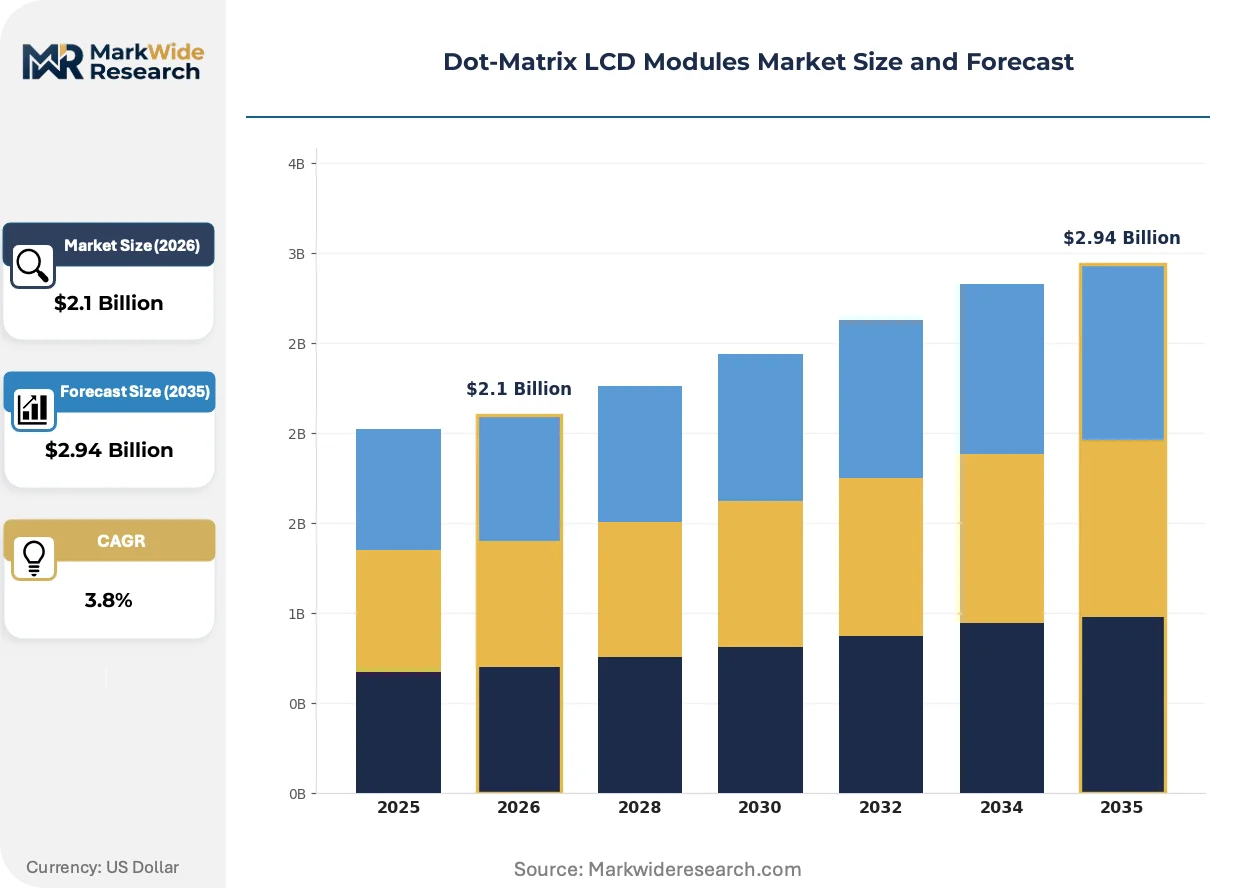
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Character LCD, Graphic LCD, Thin Film Transistor LCD, OLED End User: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices Technology: Passive Matrix, Active Matrix, Capacitive Touch, Resistive Touch Application: Smart Meters, Home Appliances, Wearable Devices, Information Displays |
| Companies Covered | AU Optronics, LG Display, Innolux Corporation, BOE Technology Group, Sharp Corporation, Newhaven Display International, Kingbright, Raystar Optronics, AuroraLCD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dot-Matrix LCD Modules Market Evolving Landscape
Display module architectures are bifurcating between ultra-low-power wearable implementations and ruggedized industrial platforms, with regulatory substance mandates and procurement model fragmentation accelerating technology refresh cycles.
Chip-on-glass bonding technology is migrating from passive matrix character displays to active matrix graphic modules, reducing bezel width and improving shock resistance. Automotive instrument cluster suppliers are adopting COG for space-constrained dashboard implementations. This transition is compressing demand for traditional tape-automated bonding processes in mid-size panel categories.
China's MIIT energy efficiency labeling mandates for home appliances are indirectly specifying display module power budgets, compelling controller IC redesigns with deeper sleep states. Manufacturers serving domestic Chinese appliance OEMs must validate standby consumption below thresholds tied to product efficiency ratings. White goods segments with always-on clock displays face the most stringent compliance timelines.
Industrial buyers are consolidating supplier relationships around module vendors offering in-house resistive touch integration and custom bezel finishing. Single-source procurement for complete HMI subassemblies is displacing multi-vendor display-plus-touch-plus-enclosure sourcing. North American factory automation OEMs exhibit the most concentrated preference for integrated supplier models.
Dot-Matrix LCD Modules Market Segmentation
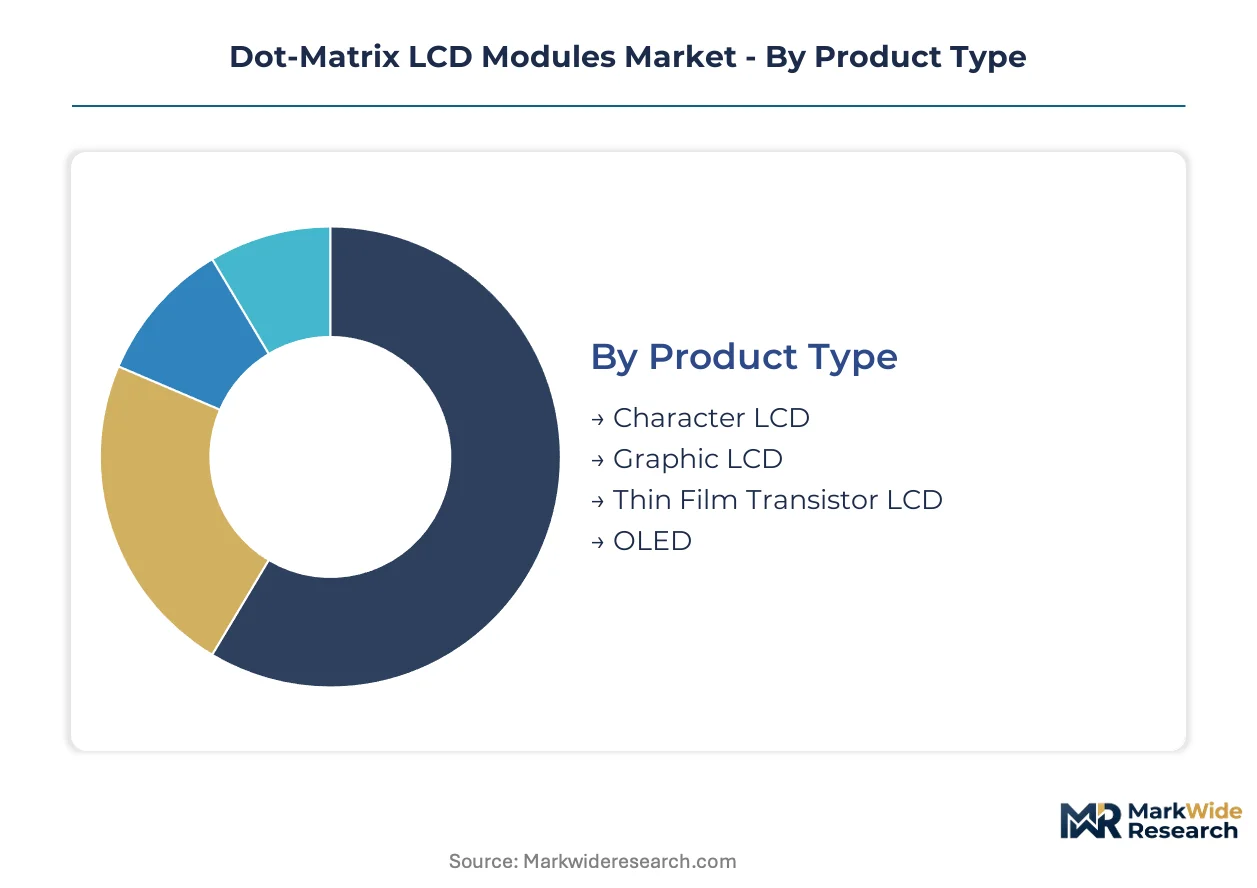
Dot-matrix LCD module segmentation reveals distinct procurement patterns across product architectures and end-use verticals. Technology choices and application requirements drive divergent specification priorities, from industrial HMI durability to wearable power efficiency.
Product Type:
Mature formats dominate shipment volumes while emerging display technologies capture premium sockets in next-generation equipment.
- Character LCD:Fixed-segment alphanumeric displays operate at 5V logic with 1/8 to 1/16 duty ratios, rendering standard font sets through controller IC firmware. Demand concentrates in China's domestic appliance sector, where MIIT energy efficiency labeling mandates compress standby power budgets for always-on clock displays.
- Graphic LCD:Bitmap-addressable pixel arrays enable custom iconography and multi-language interfaces through flexible controller programming. Industrial equipment manufacturers in North American factory automation specify these variants with integrated resistive touch layers for glove-compatible HMI panels.
- Thin Film Transistor LCD:Active matrix architectures deliver faster response times and wider viewing angles through dedicated thin-film transistors at each pixel site.
- OLED:Self-emitting organic diode structures eliminate backlight assemblies, enabling thinner form factors and deeper contrast ratios in portable information displays.
Character LCD retains volume leadership; OLED holds the steepest expansion curve.
End User:
Cost tier differentiation separates commodity procurement from certified medical-grade supply chains with divergent margin structures.
- Consumer Electronics:High-volume, short-lifecycle applications prioritize unit cost minimization over operational longevity, with OEMs sourcing through consolidated Asian module integrators.
- Automotive Displays:Instrument cluster and center console implementations demand extended temperature ranges and vibration resistance validated to OEM-specific qualification protocols.
- Industrial Equipment:Process control and automation interfaces require decade-plus operational life with readable performance under direct ambient light exposure.
- Medical Devices:Diagnostic equipment displays must satisfy FDA 510(k) pathways and ISO 13485 quality management systems, creating qualification barriers that sustain premium pricing tiers.
Industrial equipment commands the most fragmented supplier base; medical devices sustain the highest certification premiums.
Technology:
Application requirements determine matrix architecture selection, with duty ratio limitations constraining pixel density in passive implementations.
- Passive Matrix:Row-column addressing without active switching elements suits low-information-density applications where cost sensitivity outweighs response time requirements.
- Active Matrix:Dedicated TFT switching at each pixel enables higher multiplex complexity and superior viewing angle consistency for wearable and portable information displays.
- Capacitive Touch:Projected capacitance layers support multi-point gesture recognition in consumer electronics where bare-finger operation predominates.
- Resistive Touch:Pressure-sensitive membrane structures maintain operability through industrial gloves, dominating factory floor and medical sterile field applications.
Passive matrix maintains cost advantage in character formats; active matrix is displacing legacy architectures in graphic applications.
Application:
Customer type fragmentation separates utility-specified meter deployments from appliance OEM integrated supply chains.
- Smart Meters:Utility-grade displays require decade-plus readability under outdoor exposure with minimal power draw from battery-backed metering systems.
- Home Appliances:White goods manufacturers specify character LCD modules with custom bezel finishing and controller firmware supporting multi-language user interfaces.
- Wearable Devices:Ultra-low-power active matrix implementations prioritize response time and viewing angle consistency for wrist-worn health monitoring platforms.
- Information Displays:Public signage and portable data terminals balance readability with battery autonomy in variable ambient lighting conditions.
Home appliances generate the highest unit volumes; wearable devices exhibit the most rapid technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial equipment manufacturers and white goods OEMs concentrate procurement decisions in manufacturing clusters with captive glass and driver IC capacity. China's vertically integrated fabs anchor volume supply, while European REACH enforcement and US medical certification requirements sustain premium-tier demand in regulated end-uses.
China
Domestic appliance OEMs in the Yangtze River Delta and Pearl River Delta drive character LCD procurement for always-on clock displays in refrigerators and washing machines. MIIT energy efficiency labeling mandates compress standby power budgets, forcing controller IC redesigns with deeper sleep states. BOE Technology Group and Innolux Corporation operate vertically integrated fabs in Beijing and Taipei-serving facilities, shortening lead times for white goods producers.
United States
Factory automation OEMs in the Midwest and Southeast specify graphic LCD modules with integrated resistive touch for glove-compatible HMI panels. FCC electromagnetic emissions regulations govern embedded display controllers in medical and automotive applications. Newhaven Display International maintains quick-turn customization operations serving North American industrial customers from Illinois-based facilities.
Germany
Industrial machinery builders in Bavaria and North Rhine-Westphalia procure decade-life displays for process control interfaces requiring ambient light readability. ECHA REACH substance restrictions ban mercury and cadmium in backlight phosphors, accelerating LED-based module redesigns across appliance OEM installed bases. Siemens and Bosch-connected suppliers in Stuttgart and Munich industrial clusters validate extended temperature range implementations.
Japan
Automotive instrument cluster suppliers in the Chubu region around Nagoya adopt chip-on-glass bonding for space-constrained dashboard implementations. METI industrial standards shape qualification protocols for vibration-resistant modules. Sharp Corporation sustains dedicated fab lines in Mie Prefecture for monochrome graphic formats serving domestic automotive Tier 1s.
South Korea
Wearable device OEMs in the Seoul Capital Area source ultra-low-power active matrix implementations for wrist-worn health monitoring platforms. MFDS medical device regulations create parallel certification tracks for diagnostic equipment displays. Samsung-affiliated module operations in Suwon and Yongin anchor supply for domestic consumer electronics brands.
Dot-Matrix LCD Modules Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply structures. The vendor base clusters around three strategic archetypes: vertically integrated Asian panel houses with captive glass capacity, regional customization specialists serving quick-turn industrial demand, and component-aggregating distributors bridging specification gaps. Dominant competitive moves include backward integration into driver IC design and geographic expansion through distributor partnerships in underpenetrated medical device segments.
Among Taiwan and China-based panel fabricators, AU Optronics, Innolux Corporation, and BOE Technology Group exemplify the scale-driven archetype with integrated manufacturing footprints. Sharp Corporation occupies a position representing Japanese technology leadership in monochrome graphic formats. Newhaven Display International sits within the North American customization specialist tier. Kingbright and Raystar Optronics anchor the component supplier segment serving mid-volume industrial module assemblers.
| Leading Market Players |
|---|
| AU Optronics |
| LG Display |
| Innolux Corporation |
| BOE Technology Group |
| Sharp Corporation |
| Newhaven Display International |
| Kingbright |
| Raystar Optronics |
| AuroraLCD |
| Others |
Value Network & Pricing Analysis
China's captive glass and driver IC capacity anchors cost positions for character LCD modules, compressing margin pools for mid-volume assemblers dependent on spot market sourcing while concentrating pricing power among vertically integrated panel houses.
Pricing Analysis
Long-term supply contracts with indium tin oxide indexation dominate procurement between module assemblers and downstream OEMs. Three-tier pricing structure across medical-grade, industrial-certified, and consumer-economy levels separates FDA 510(k) qualified supply from standard industrial implementations. Cost compression in consumer-tier character LCDs is intensifying because BOE Technology Group and Innolux Corporation leverage in-house controller IC production. White goods manufacturers in China exhibit the highest price sensitivity, while medical device OEMs in the United States and Germany accept premium positioning for ISO 13485 validated supply.
Supply Chain Analysis
Indium tin oxide feedstock draws from Chinese refining operations and South Korean sputtering target manufacturers, with glass substrate production concentrated in Japan, Taiwan, and China. Driver IC fabrication rests on 8-inch wafer capacity at foundries in Taiwan and China, while LED backlight components source from epitaxial wafer growers in South Korea and Japan. Single-source vulnerability in specialized controller firmware expertise extends qualification timelines for custom graphic implementations. Distribution runs through direct OEM partnerships for high-volume appliance segments and regional distributors serving quick-turn industrial replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where FDA 510(k) and ISO 13485 certification barriers create switching costs that protect qualified suppliers from commoditization pressures.
For Market Incumbents: Entrench certification moats by deepening medical-grade quality management integration with industrial module platforms, eliminating duplicate facility investment. Accelerate backward integration into driver IC design to compress lead times for custom firmware implementations. OLED substitution in portable devices and emerging quick-turn customization specialists in North America threaten margin stability in graphic LCD segments. For New Entrants and Emerging Players: North American medical device display procurement exhibits structural underpenetration by qualified module suppliers, creating white space for ISO 13485 certified entrants. Target FDA 510(k) pathway expertise gaps among industrial module vendors serving diagnostic equipment OEMs. Establish partnerships with Illinois-based quick-turn customization operations to bypass entrenched Asian supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated panel houses with captive glass capacity and established medical certification portfolios. Long-term viability hinges on regulatory entrenchment rather than technology differentiation, favoring assets with proven FDA and EMA submission track records. Watch for MIIT energy efficiency mandate acceleration in China as an inflection indicator for controller IC redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | BOE Technology Group's captive controller capacity compresses lead times for appliance OEMs. |
| Medical Device Certification Investment | FDA 510(k) pathway expertise scarcity sustains premium pricing tiers in diagnostic equipment. |
| Resistive Touch Integration Expansion | Single-source HMI subassembly procurement displaces multi-vendor display-plus-touch sourcing. |
| Chip-on-Glass Bonding Migration | Automotive instrument cluster suppliers in Japan adopt COG for space-constrained dashboards. |
| Energy Efficiency Controller Redesign | MIIT labeling mandates force deeper sleep states in modules serving Chinese white goods. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with display module procurement managers, controller IC design engineers, and medical device quality assurance leads, and secondary validation through customs trade records, SEC 10-K filings of listed panel manufacturers, ECHA REACH substance restriction databases, and MIIT energy efficiency labeling disclosures. Bottom-up shipment estimates by product type and end-use vertical were triangulated against top-down value assessments derived from fab capacity announcements and OEM procurement patterns.
Forecast inputs considered passive-to-active matrix technology migration rates, REACH and RoHS regulatory enforcement timelines, and China's domestic fab consolidation trajectory across the projection horizon. Segmentation modeling incorporated product architecture, end-use vertical certification requirements, technology matrix type, and geographic procurement cluster. CAGRs were derived from regression analysis of historical shipment-value relationships adjusted for technology substitution effects and regulatory refresh demand.
The forecast holds incumbent behavior within observed patterns; aggressive moves by OLED display manufacturers into industrial HMI segments or rapid REACH substance restriction expansion would shift outcomes. Material shifts in indium tin oxide supply concentration or MIIT energy efficiency mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Foldable Screens Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Industrial Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Global Display Panel Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
4K Technology Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Visual Computing Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Rugged Display Market
Display Technologies
Global Projector Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Touch Screen Module Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Backlit Displays Market