
 LCD Panel Market | 2026-2036
LCD Panel Market Size, Share, and Industry Trends Forecast 2026-2036
LCD Panel Market Analytics
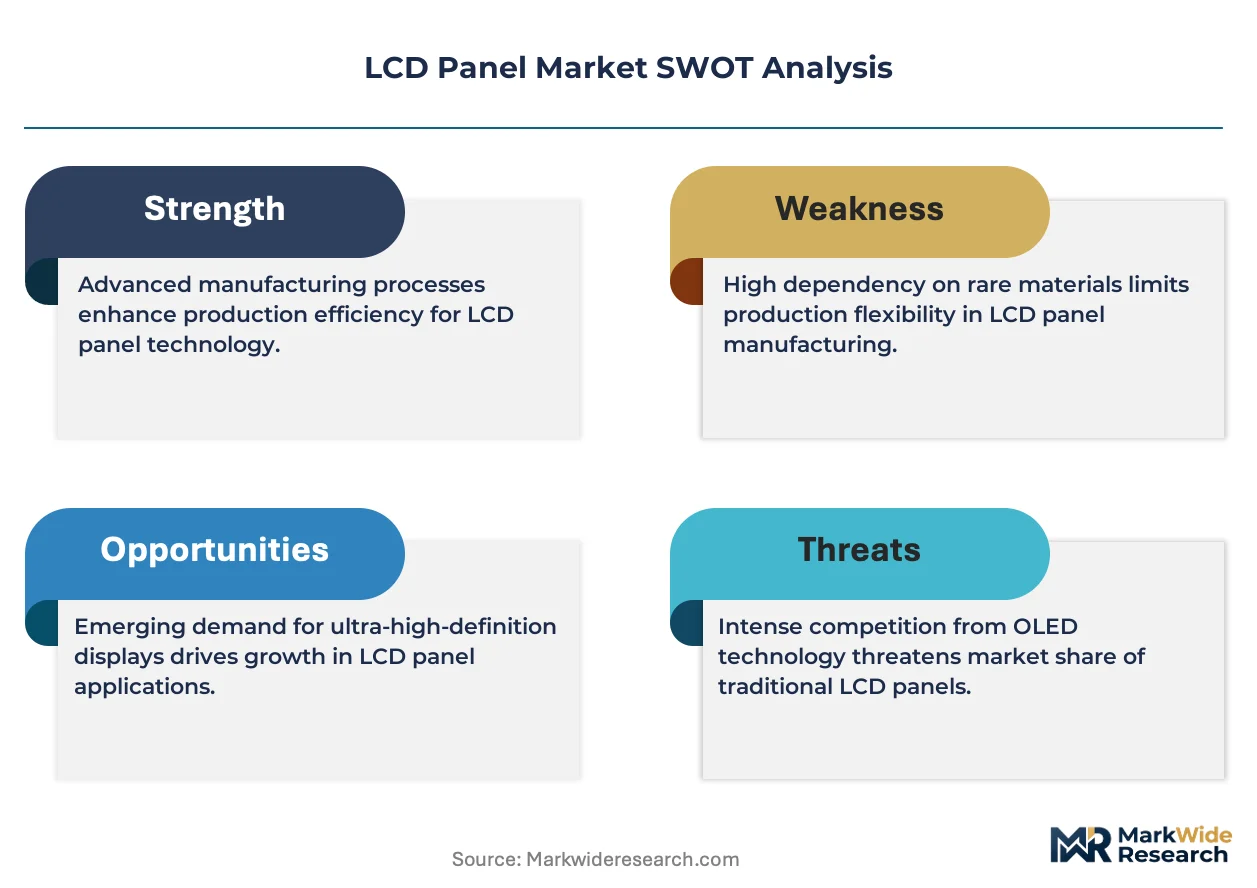
Asset-light leasing models for Gen 8.5 and Gen 10.5 fabrication lines is rewriting capital deployment across the LCD panel industry, allowing mid-tier competitors to access advanced capacity without balance-sheet strain. BOE Technology Group leverages its captive Gen 10.5 mother-glass output to dominate large-area TV panel supply. LG Display sustains premium positioning through IPS technology leadership in professional monitor segments. Samsung Display anchors its competitive stance by specializing in high-refresh-rate gaming panels where technical differentiation commands sustained margin pools.
An LCD panel is a flat-panel display device composed of liquid crystals sandwiched between two polarized glass substrates with thin-film transistor (TFT) backplanes, modulating light transmission from a backlight unit to produce images with typical response times below 5 milliseconds. Its primary commercial purpose spans television, computing, mobile, and specialized industrial visualization systems requiring scalable, cost-effective display surfaces. TV panels represent the most mature volume segment with thinning margin pools, while automotive displays emerge as the fastest-growing application dimension driven by cockpit digitization and head-up display integration. Mobile device panels concentrate value in OLED technology transitions, though LCD retains dominant share in cost-sensitive smartphone tiers and emerging market handsets.
China's MIIT enforces GB standards for display energy consumption and electromagnetic compatibility, directly shaping product design cycles and factory certification requirements for domestic and export-bound panels. South Korea's METI-equivalent industrial policy frameworks and REACH-aligned substance restrictions from European ECHA regulate material composition and end-of-life treatment protocols across supply chains. The EU F-Gas Regulation constrains fluorinated greenhouse gas use in etching processes, elevating compliance costs for manufacturers serving European automotive and commercial display customers. Stakeholders must monitor divergence between Chinese GB efficiency mandates and European chemical substance rules when configuring multi-region product platforms.
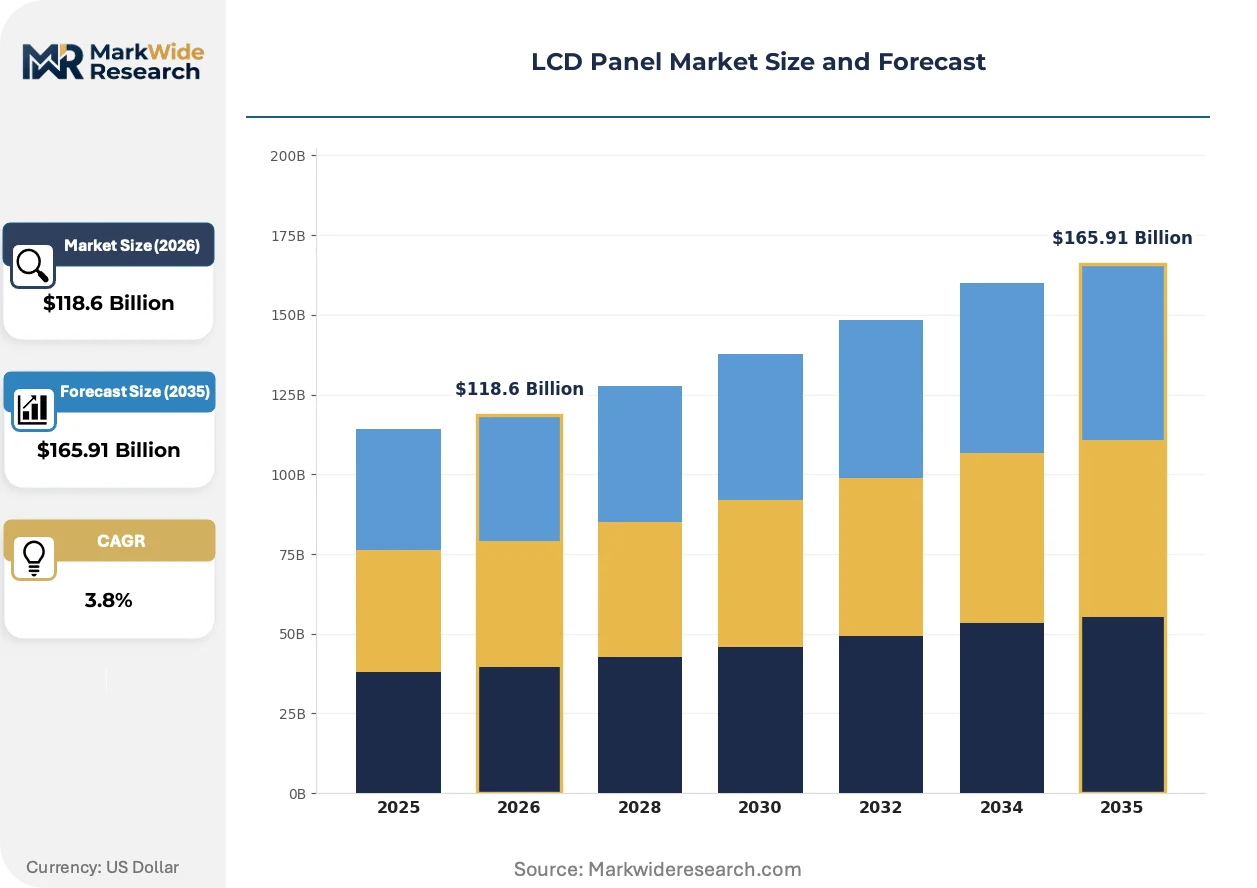
Market Dynamics
Asset-light leasing models for Gen 8.5 and Gen 10.5 fabrication lines are rewriting capital deployment across the LCD panel industry, allowing mid-tier competitors to access advanced capacity without balance-sheet strain. China's GB standards for display energy efficiency are tightening product requirements and compressing design cycles simultaneously.
Growth Catalysts
- Automotive cockpit digitization:Electric vehicle manufacturers integrate larger dashboard screens and head-up displays, creating sustained pull for high-brightness, wide-temperature-range panels.
- MIIT GB efficiency mandates:China's Ministry of Industry and Information Technology enforces tightening energy consumption standards, forcing technology upgrades that improve panel performance metrics.
- Gumi-Tangjeong manufacturing cluster:South Korea's concentrated display ecosystem enables rapid knowledge spillover and specialized supplier density for advanced TFT backplane processes.
Market Restraints
- Fluorinated gas constraints:The EU F-Gas Regulation limits etching process chemistries, elevating compliance costs for manufacturers serving European automotive and commercial display customers.
- OLED substitution in mobile:Organic light-emitting diode technology captures premium smartphone tiers, compressing LCD to cost-sensitive market segments with thinning margins.
- Mother-glass concentration:Captive Gen 10.5 output from dominant Chinese fabricators creates supply-side dependency for large-area TV panel procurement.
Strategic Opportunities
- Industrial visualization systems:Factory automation and medical imaging equipment demand ruggedized panels with extended operating lifecycles, opening specialized margin pools.
- India BIS certification pathway:Bureau of Indian Standards implementation for electronic displays creates first-mover advantage for compliant suppliers in an underpenetrated geography.
- Mini-LED backlight convergence:Hybrid architectures combining liquid crystal modulation with localized dimming arrays enable premium positioning against OLED in large-format applications.
Industry Challenges
- TFT backplane engineering scarcity:Advanced thin-film transistor design expertise concentrates at established Korean and Taiwanese engineering centers, constraining new entrant capability building.
- Multi-region certification complexity:Divergence between Chinese GB efficiency mandates, European REACH substance restrictions, and Indian BIS testing protocols extends product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LCD Panel Market |
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $165.91 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitors, TVs, Mobile Devices, Laptops Technology: IPS, TN, VA, OLED Application: Consumer Electronics, Automotive Displays, Gaming, Advertising End User: Retail, Hospitality, Education, Healthcare |
| Companies Covered | BOE Technology Group, LG Display, Samsung Display, AU Optronics, Innolux Corporation, Sharp Corporation, TCL China Star Optoelectronics Technology, Tianma Microelectronics, Japan Display Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LCD Panel Market Evolving Landscape
Active matrix liquid crystal technology faces simultaneous pressure from above and below. OLED alternatives attack premium segments while new backlight architectures and substrate materials extend LCD relevance in specialized applications.
Mini-LED backlighting is virtualizing traditional edge-lit and full-array LED configurations in high-end television and professional monitor segments. Automotive display integrators and gaming monitor manufacturers adopt the technology fastest, seeking localized dimming zones that approach OLED contrast without burn-in vulnerability. This architecture is virtualizing the competitive boundary between liquid crystal and emissive display technologies, compressing OLED's addressable premium market.
China's MIIT enforces progressively stricter GB standards for display energy consumption and electromagnetic compatibility. Domestic and export-bound panels must recertify against tightening thresholds, accelerating design refresh cycles. Professional monitor and automotive display segments face the steepest compliance burden as their duty cycles and operating environments trigger the most stringent test protocols.
Equipment leasing for Gen 8.5 and Gen 10.5 mother-glass lines is displacing traditional ownership models among mid-tier panel brands. Korean and Taiwanese equipment lessors now structure operating leases with technology refresh clauses, transferring obsolescence risk from balance sheets to lessor portfolios. This financing innovation is most visible among Chinese panel brands seeking rapid capacity scaling without equity market dependency.
LCD Panel Market Segmentation
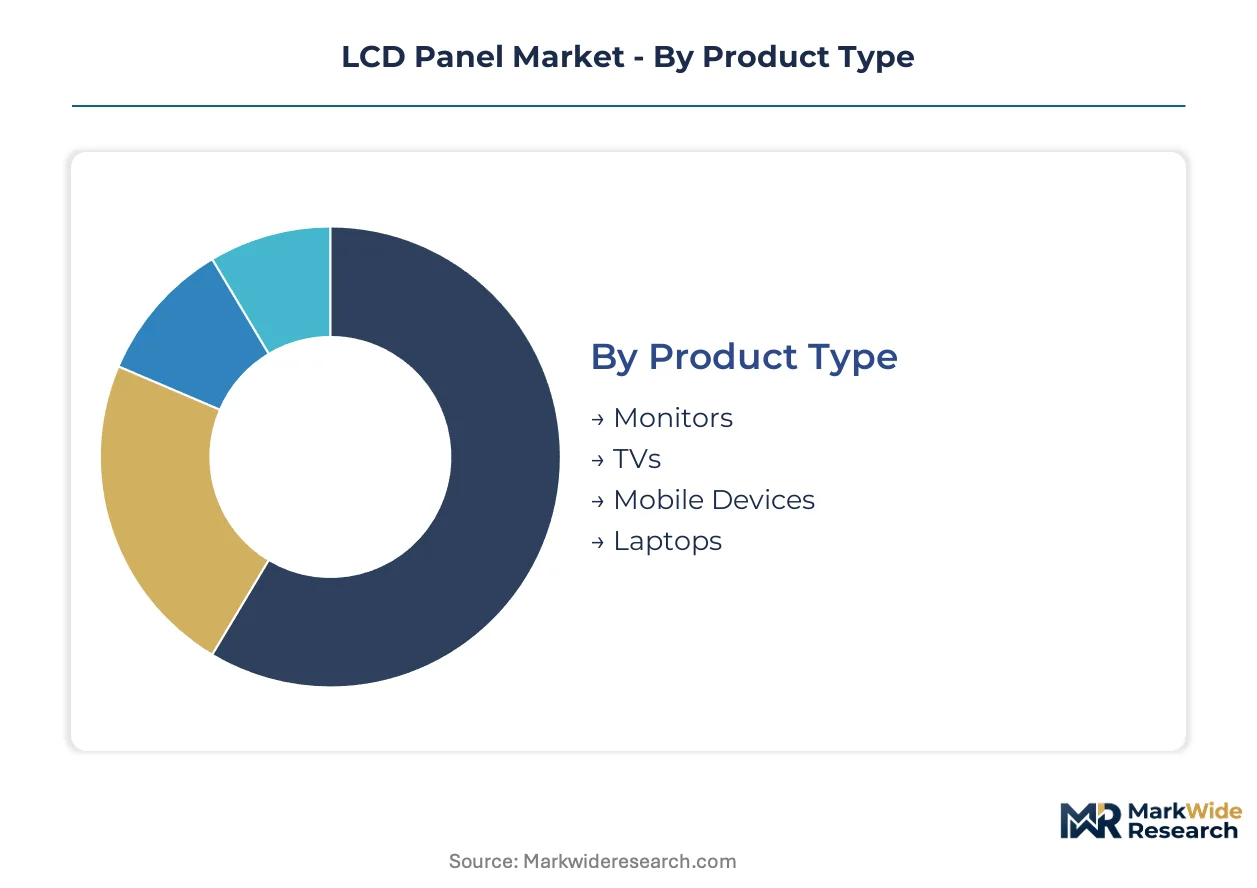
LCD panel segmentation reveals divergent replacement cycles across product categories, with mobile and gaming displays turning over fastest while industrial and automotive applications extend lifecycles through ruggedization requirements. Understanding these velocity differentials shapes inventory planning and technology roadmapping for fabricators serving multiple end-use tiers.
Product Type:
TV panels operate on the slowest refresh cycle among major categories, with replacement intervals stretching across multiple years, while mobile device panels turn over fastest as handset upgrade cycles compress design-to-obsolescence windows.
- Monitors:Professional-grade IPS configurations dominate enterprise procurement, with South Korean fabricators supplying high-refresh-rate units for financial trading floors and medical imaging suites where color accuracy commands premium positioning. Corporate IT refresh cycles and hybrid work infrastructure investments sustain demand stability in this segment.
- TVs:Large-area panels utilizing Gen 10.5 mother-glass substrates concentrate production in Chinese fabs, with 65-inch and larger formats driving average selling price recovery despite thinning margin pools at mainstream sizes. Energy efficiency mandates from China's MIIT accelerate backlight architecture transitions.
- Mobile Devices:Compact panels face OLED substitution pressure in premium tiers, though LCD retains cost-sensitive smartphone dominance through a-Si and LTPS backplane cost optimization for emerging market handsets.
- Laptops:Narrow-bezel designs and 16:10 aspect ratio transitions characterize current procurement patterns, with enterprise fleet refreshes and education sector bulk purchases sustaining volume against tablet substitution headwinds.
TV panels anchor the volume base while mobile device panels gain share at the steepest rate through emerging market handset expansion.
Technology:
Cost structures separate these architectures, with IPS commanding fabrication complexity premiums and TN retaining entry-level positioning through simplified cell processing.
- IPS:In-plane switching technology delivers superior color reproduction and viewing angle stability through horizontal liquid crystal alignment, commanding professional monitor and premium laptop applications where LG Display maintains technology leadership. Automotive integrators specify IPS for dashboard displays requiring wide temperature operation.
- TN:Twisted nematic cells offer fastest response times at lowest manufacturing cost, sustaining esports monitor and entry-level laptop segments despite limited viewing angles and color shift vulnerability.
- VA:Vertical alignment technology balances contrast performance with production economics, occupying mid-tier TV and curved gaming monitor segments where localized dimming compatibility matters.
- OLED:Organic emissive technology captures premium smartphone and television tiers through self-emissive pixel control, though LCD-Mini-LED hybrids compress its addressable premium in large-format applications.
TN technology anchors the volume base through cost-sensitive applications while OLED gains share at the steepest rate in premium television and mobile segments.
Application:
Commercial deployment models create margin stratification, with advertising and gaming applications prioritizing performance specifications over unit economics.
- Consumer Electronics:Television and personal computing displays constitute the mature volume core, with procurement consolidating around Chinese fabricators leveraging Gen 10.5 capacity for cost leadership at mainstream sizes.
- Automotive Displays:Cockpit digitization and head-up display integration drive specification escalation toward high-brightness, wide-temperature-range panels with automotive-grade reliability certification. Electric vehicle manufacturers specify larger dashboard formats.
- Gaming:High-refresh-rate panels with sub-5ms response times command specialized margin pools, with Samsung Display anchoring supply for competitive esports monitor segments.
- Advertising:Digital signage and public display applications prioritize luminance and durability over color accuracy, with outdoor installations requiring extended operating temperature ranges and ingress protection.
Consumer electronics anchors the volume base while automotive displays expand most quickly through electric vehicle cockpit digitization.
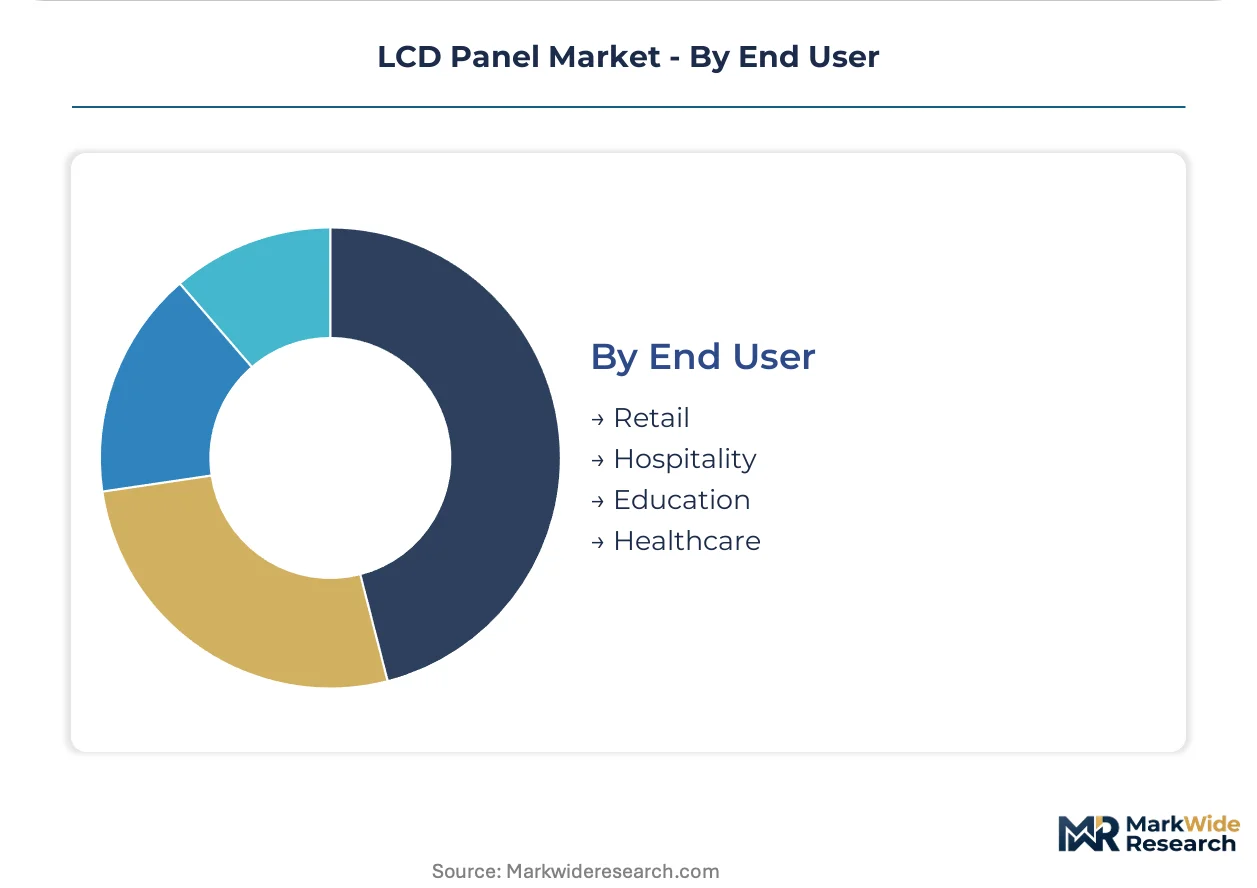
End User:
Procurement sophistication varies sharply across these verticals, with healthcare and education segments imposing certification burdens that filter supplier participation.
- Retail:Point-of-sale terminals and digital signage networks prioritize total cost of ownership over upfront panel expense, with 24/7 operation requirements favoring commercial-grade durability specifications.
- Hospitality:In-room entertainment and lobby display applications balance aesthetic integration with content management system compatibility, with procurement consolidating through AV integrators.
- Education:Interactive whiteboard and classroom display deployments accelerate through government technology infrastructure programs, with touch overlay integration and anti-glare treatments standardizing at district-level procurement.
- Healthcare:Diagnostic imaging and patient monitoring applications impose stringent color calibration and electromagnetic compatibility requirements, with FDA and equivalent national regulator clearances filtering supplier qualification.
Retail anchors the volume base through broad installation footprints while healthcare climbs the fastest through diagnostic imaging specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT GB efficiency mandates and South Korea's industrial policy frameworks are accelerating regional specialization, while India's BIS certification pathway and EU F-Gas Regulation create divergent compliance environments that reshape cross-border procurement strategies.
China
Domestic electric vehicle manufacturers are specifying larger dashboard formats, pulling high-brightness panel demand from local fabricators. MIIT enforces progressively stricter GB standards for display energy consumption and electromagnetic compatibility. The Yangtze River Delta and Pearl River Delta clusters concentrate Gen 10.5 mother-glass capacity where BOE and TCL China Star anchor large-area TV panel supply.
South Korea
Automotive cockpit digitization and gaming monitor procurement sustain premium-tier demand for high-refresh-rate IPS configurations. METI-aligned industrial policy frameworks support advanced TFT backplane process development. The Gumi-Tangjeong manufacturing cluster enables rapid knowledge spillover between Samsung Display and specialized equipment suppliers.
Japan
Medical imaging and diagnostic equipment manufacturers impose stringent color calibration requirements on professional monitor panels. JIS standards and PMDA regulatory clearances filter supplier qualification for healthcare applications. The Chubu-Nagoya region maintains precision manufacturing infrastructure for industrial visualization systems.
India
Government technology infrastructure programs are accelerating interactive whiteboard deployments across education sector procurement. BIS certification implementation for electronic displays creates compliance barriers for non-compliant imports. Maharashtra and Karnataka are emerging as assembly locations for cost-sensitive smartphone panels serving domestic handset brands.
Germany
Automotive OEMs specify wide-temperature-range panels for head-up display integration in premium electric vehicle platforms. ECHA REACH substance restrictions and EU F-Gas Regulation constrain etching process chemistries for export-bound production. Bavaria and Baden-Württemberg host automotive display engineering centers coordinating Tier 1 supplier qualification.
LCD Panel Market Competitive Landscape
On the supply side, the industry is consolidating around three scale tiers: Chinese fabricators leveraging Gen 10.5 capacity, Korean specialists defending premium positioning through technology leadership, and Taiwanese mid-tier players accessing advanced lines via asset-light leasing structures. Strategic archetypes include captive mother-glass operators, IPS technology licensors, and high-refresh-rate gaming panel specialists. Competitive moves concentrate on equipment leasing partnerships and multi-region certification platform development.
Among Chinese fabricators, BOE Technology Group and TCL China Star Optoelectronics Technology occupy positions as scale-driven operators with captive Gen 10.5 output. LG Display exemplifies the premium-tier archetype through IPS technology positioning. Samsung Display anchors the high-refresh-rate specialization vector for gaming and automotive applications.
| Leading Market Players |
|---|
| BOE Technology Group |
| LG Display |
| Samsung Display |
| AU Optronics |
| Innolux Corporation |
| Sharp Corporation |
| TCL China Star Optoelectronics Technology |
| Tianma Microelectronics |
| Japan Display Inc. |
| Others |
Value Network & Pricing Analysis
Gen 10.5 mother-glass concentration in China's Yangtze River Delta anchors cost leadership for large-area TV panels while compressing margin pools for mid-tier fabricators lacking captive substrate supply. This upstream consolidation funnels pricing power toward BOE and TCL China Star, forcing competitors toward specialized automotive and gaming segments where certification premiums sustain healthier economics.
Pricing Analysis
Certification grade creates the primary spread between automotive-grade panels and commodity TV configurations, with AEC-Q100 compliance adding substantial cost premiums over consumer-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects backplane technology differentiation, with a-Si commanding lowest price points and LTPS/Oxide backplanes anchoring premium mobile and automotive tiers. Cost compression in mainstream TV sizes intensifies as Chinese fabricators leverage Gen 10.5 scale advantages, eroding margins for non-captive producers. Enterprise procurement for professional monitors exhibits lowest price sensitivity due to color accuracy requirements, while education sector bulk purchases drive hardest bargain-seeking behavior.
Supply Chain Analysis
Export control regimes restricting advanced lithography and TFT deposition equipment limit capacity expansion outside established Korean and Chinese manufacturing bases. Geographic supply concentration centers on China, South Korea, and Taiwan, with Japanese equipment vendors providing critical deposition and etching tools. Raw material dependencies include photoresist chemicals from Japanese suppliers, polarizer films from Nitto Denko and Sumitomo, and driver ICs from Taiwanese semiconductor foundries. Single-source vulnerability concentrates in advanced photoresist formulations where Tokyo Ohka Kogyo and JSR dominate high-purity grades. Distribution runs through direct OEM contracts for automotive and TV panel procurement, with spot-market intermediaries handling excess inventory and secondary sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED substitution in premium smartphone and television tiers threatens LCD's addressable market, forcing incumbents to defend position through specialized applications where liquid crystal architectures retain technical or cost advantages.
For Market Incumbents: Harden automotive certification portfolios against emerging Mini-LED hybrid competition by accelerating AEC-Q100 qualification timelines for wide-temperature-range IPS configurations. Deepen backward integration into driver IC design to reduce exposure to Taiwanese foundry capacity constraints. Prioritize gaming monitor segments where Samsung Display's high-refresh-rate specialization demonstrates sustainable margin defense against OLED encroachment. For New Entrants and Emerging Players: Establish a beachhead in India's education technology procurement by securing BIS certification ahead of competitors and partnering with local system integrators for interactive whiteboard deployments. Target industrial visualization systems where ruggedization requirements and extended lifecycle specifications filter out commodity competitors. Pursue asset-light leasing structures for Gen 8.5 capacity to access advanced fabrication without balance-sheet strain. For Investors and Strategic Acquirers: Capital is best deployed toward equipment lessors with technology refresh clauses and captive mother-glass operators with Gen 10.5 scale positions. Long-term viability hinges on defensible automotive and gaming niches rather than commodity TV exposure. Watch for inflection signals in Mini-LED backlight adoption rates as the critical indicator of LCD's premium-market resilience against OLED substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Mini-LED Backlight Convergence | Hybrid architectures enable premium positioning against OLED in large-format television and automotive dashboard applications. |
| Automotive Certification Investment | AEC-Q100 qualification opens high-margin supply relationships with electric vehicle manufacturers specifying larger cockpit displays. |
| Asset-Light Leasing Expansion | Operating lease structures transfer obsolescence risk while enabling mid-tier competitors to access Gen 10.5 fabrication capacity. |
| India BIS Compliance Pathway | First-mover certification advantage captures education sector procurement through government technology infrastructure programs. |
| Driver IC Backward Integration | In-house semiconductor design reduces exposure to Taiwanese foundry capacity constraints and improves supply security. |
Research Methodology
Operator-level perspectives from TFT backplane engineers, automotive display procurement managers, panel fabrication equipment specialists, and education technology integrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs records, MIIT GB standard filings, SEC 10-K disclosures from listed fabricators, and equipment vendor order backlogs. Bottom-up unit economics modeling triangulated against top-down market size estimates derived from mother-glass input tracking and regional production cluster surveys.
Scenario-bracketing around OLED substitution velocity and automotive electrification penetration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, backplane technology, application vertical, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of input-output ratios and capacity utilization rates, cross-referenced against electric vehicle production forecasts and gaming monitor shipment data as industry-specific demand indicators.
Sensitivities concentrate around MIIT efficiency mandate enforcement intensity, EU F-Gas Regulation compliance cost escalation, and Mini-LED cost-down trajectories relative to OLED. Forecasts reflect documented assumptions regarding substrate generation transitions and regional manufacturing share shifts. Cross-checking against Display Supply Chain Consultants and Omdia panel shipment databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Privacy Screens Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Display Material Market
Display Technologies
PMOLED Display Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Interactive Display Market
Display Technologies
Plasma Display Module Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Display Glass Substrate Market