
 Textile Flame Retardants Market | 2026-2036
Textile Flame Retardants Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Flame Retardants Market Intelligence
Buyer concentration in the protective clothing segment is consolidating as defense contractors and industrial safety purchasers centralize procurement around certified suppliers. Clariant AG leverages its phosphorus-based portfolio to serve European aerospace buyers with REACH-compliant formulations. Albemarle Corporation anchors North American supply through its bromine and phosphorus specialties for military textile programs. BASF SE competes on polymer modification technology that integrates flame retardancy directly into fiber structures rather than relying on surface treatments.
Textile flame retardants are chemical additives or functional coatings engineered to inhibit ignition, suppress combustion, or reduce smoke density in woven and nonwoven materials, typically achieving LOI values above 26 percent for commercial certification. Their primary purpose is to ensure compliance with fire safety standards in environments where human exposure to ignition sources presents catastrophic risk. Phosphorus-based compounds now lead product type demand as manufacturers phase out chlorinated alternatives under regulatory pressure. Bio-based solutions represent the fastest-growing technology segment, though additive technology still occupies the largest installed base due to lower retrofit costs for existing textile finishing lines. Protective clothing applications command premium pricing compared to home textiles, where margin pools remain thinner and specification requirements less stringent.
REACH in Europe, the US FAA's flame resistance standards for aircraft interiors, and China's GB national standards for public building textiles collectively determine which chemistries gain market access and which face substitution mandates. The EU's F-Gas Regulation and evolving MEE enforcement in China are both narrowing the window for halogenated compound deployment in textile applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
REACH restrictions on halogenated compounds are forcing European formulators to rebuild supply chains around phosphorus-based and bio-based alternatives, compressing the window for legacy chemistry deployment while creating first-mover advantage for compliant producers.
Growth Catalysts
- Defense procurement modernization:Military textile programs in the United States are expanding flame-resistant uniform specifications, driving volume commitments for aramid and modacrylic fiber treatments that meet FAA and NHTSA durability standards.
- China's GB standard enforcement:Public building textile mandates under China's national standards are compelling domestic mills to upgrade finishing capabilities, creating captive demand for phosphorus-based formulations.
- Bio-based polymer advancement:Chitosan and phytic acid derivatives are achieving commercial LOI thresholds, attracting sustainability-focused buyers in Scandinavian contract textiles who face EU Green Deal procurement rules.
Market Restraints
- Phosphorus feedstock concentration:Elemental phosphorus supply clusters in China, Kazakhstan, and Morocco expose European and North American formulators to export quota volatility and freight cost spikes.
- Halogenated chemistry substitution friction:REACH authorization requirements for decabromodiphenyl ether and related compounds strand existing finishing equipment calibrated for brominated systems, forcing premature capital retirement.
- Technical performance gaps:Bio-based alternatives currently fail ultraviolet stability tests required for outdoor military and aerospace applications, limiting addressable market penetration.
Strategic Opportunities
- India's technical textiles corridor:The PLI scheme and BIS certification expansion for protective workwear create entry points for phosphorus-based suppliers establishing local compounding operations.
- Polymer-inherent flame retardancy:Copolymerization during PET and nylon spinning eliminates finishing steps, appealing to Japanese automotive seating producers under METI recycling mandates.
- Direct mill partnerships:Bypassing traditional chemical distributors, formulators are embedding technical service teams inside Chinese textile clusters to capture specification authority early in product development.
Industry Challenges
- Formulation toxicology expertise scarcity:REACH-compliant product development requires rare combinations of polymer chemistry and regulatory science skills, constraining R&D throughput at mid-size suppliers.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of FAA aircraft interior approval, EU CE marking, and China GB compliance extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Flame Retardants Market |
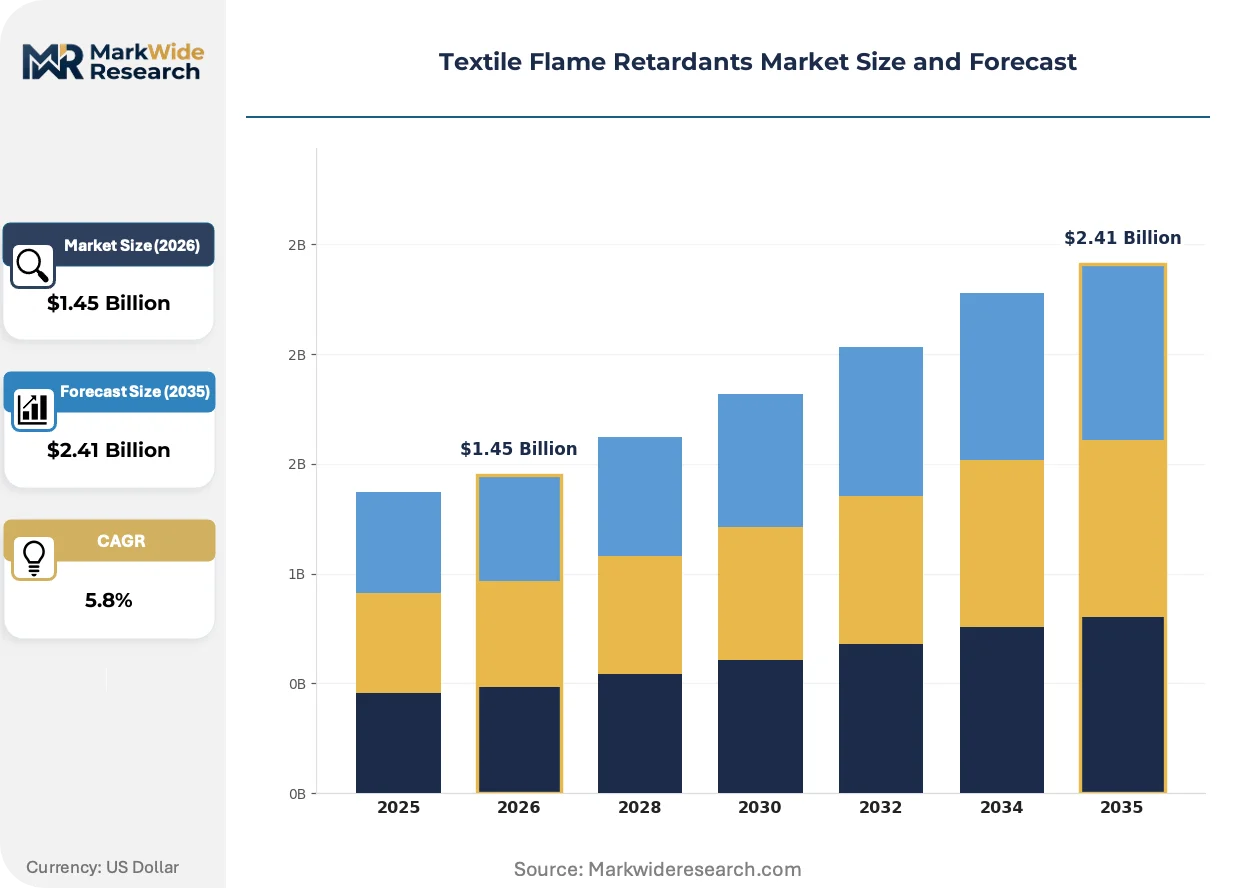
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Amine, Phosphorus-Based, Chlorinated Compounds, Inorganic Flame Retardants Application: Home Textiles, Industrial Fabrics, Protective Clothing, Upholstery Technology: Coating Technology, Polymer Modification, Additive Technology, Bio-Based Solutions End User: Aerospace, Automotive, Construction, Healthcare |
| Companies Covered | Clariant AG, Albemarle Corporation, BASF SE, Milliken & Company, Solvay S.A. (Syensqo), DuPont de Nemours, Inc., ICL Group Ltd., Huntsman Corporation, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Flame Retardants Market Strategic Shifts & Innovations
Reactive flame retardant chemistries are displacing additive approaches as textile mills face pressure to eliminate surface treatment wastewater and meet closed-loop manufacturing commitments in European and East Asian production hubs.
Nano-engineered layered double hydroxides are expanding into high-performance protective clothing applications. These inorganic platelets intercalate into fiber matrices during melt spinning, achieving LOI values above 30 percent without compromising tensile strength. German industrial safety buyers are qualifying the technology for arc-flash protective garments ahead of 2027 EU PPE regulation updates.
EU F-Gas Regulation amendments are accelerating the phase-out of fluorinated back-coatings historically used alongside flame retardants in contract upholstery. The industrial consequence is a search for silicone and phosphorus-hybrid barriers that maintain stain resistance without perfluorinated chemistry. Italian furniture textile producers are most affected, restructuring supply agreements to secure compliant barrier technologies before 2026 enforcement deadlines.
Specification authority is migrating from chemical suppliers to end-user safety departments at major defense contractors and airline maintenance operators. Centralized technical teams now dictate finishing protocols directly to textile mills, compressing the traditional distributor-mediated channel. This pattern is most visible in the United States, where Boeing and Lockheed Martin procurement organizations have established approved chemical lists that bypass regional finishing house preferences.
Textile Flame Retardants Market Segmentation
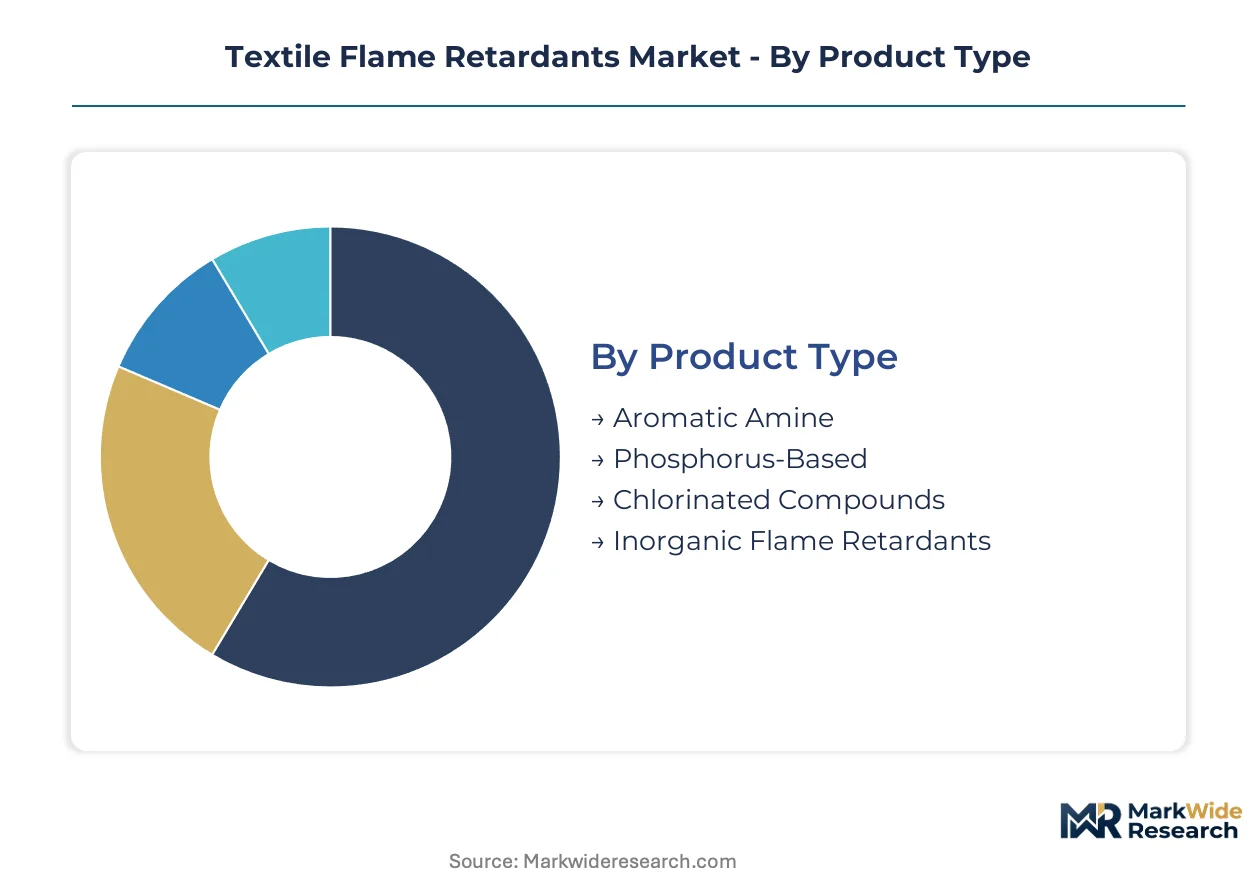
Segmentation in textile flame retardants reveals how specification authority migrates between chemistry types, application durability requirements, and end-user certification regimes. Buyers in defense and aerospace segments command premium formulations, while home textile procurement prioritizes cost-efficient additive systems.
Product Type:
Volume concentration clusters in phosphorus-based systems, while premium pricing attaches to aromatic amine formulations for high-heat applications.
- Phosphorus-Based:Organophosphorus compounds achieve LOI values above 28 percent through condensed-phase char formation. Demand concentrates in Chinese textile mills upgrading to GB-compliant finishing lines under MEE enforcement tightening.
- Aromatic Amine:Melamine derivatives and guanidine compounds deliver thermal stability for aramid fiber treatments. European aerospace buyers under REACH authorization requirements specify these for aircraft interior laminates.
- Chlorinated Compounds:Dechlorane Plus and related chemistries face substitution mandates in EU markets.
- Inorganic Flame Retardants:Aluminum hydroxide and magnesium hydroxide function as smoke suppressants in carpet backing applications.
Mature deployment sits with chlorinated compounds. Newer deployment is concentrated in phosphorus-based systems.
Application:
Margin pools diverge sharply between specification-heavy protective segments and commoditized residential markets.
- Protective Clothing:Arc-rated and flash-fire resistant garments require durability through industrial laundering cycles. US defense contractors centralize procurement around certified suppliers meeting FAA and NHTSA standards.
- Home Textiles:Curtains, bedding, and mattresses face flammability codes in public buildings. China's GB standard enforcement compels domestic mill upgrades, creating volume demand for phosphorus-based finishes.
- Industrial Fabrics:Conveyor belts and filtration media need chemical resistance alongside flame retardancy.
- Upholstery:Contract furniture textiles balance stain resistance with fire safety under evolving EU F-Gas Regulation constraints.
Specification authority concentrates in protective clothing. Volume expansion is fastest in home textiles.
Technology:
Retrofit economics favor additive approaches, while greenfield investments increasingly specify polymer-integrated solutions.
- Additive Technology:Surface-applied finishes using padding or exhaustion methods dominate installed textile finishing capacity. Lower capital requirements attract Indian technical textile producers under PLI scheme incentives.
- Bio-Based Solutions:Chitosan, phytic acid, and DNA-derived macromolecules achieve commercial LOI thresholds without petrochemical feedstocks. Scandinavian contract textile buyers facing EU Green Deal procurement rules drive qualification programs.
- Coating Technology:Back-coating with acrylic or polyurethane binders carries flame retardant payloads.
- Polymer Modification:Copolymerization during PET or nylon spinning embeds flame resistance intrinsically.
Installed base concentration remains with additive technology. Steepest expansion trajectory belongs to bio-based solutions.
End User:
Certification burden varies dramatically between regulated transportation sectors and building materials markets.
- Aerospace:Aircraft interior textiles face FAA flame resistance standards for cabin materials, combined with smoke density and toxicity requirements. Boeing and Lockheed Martin procurement organizations maintain approved chemical lists that bypass regional finishing preferences.
- Automotive:Seating and interior trim specifications integrate flame retardancy with METI recycling mandates in Japan. Polymer-inherent solutions eliminate separate finishing steps for Tier 1 suppliers.
- Construction:Tarpaulins, scaffolding nets, and architectural membranes face national building code variations.
- Healthcare:Hospital textiles and patient bedding require antimicrobial compatibility alongside fire safety.
Regulatory complexity peaks in aerospace. Standardization is advancing fastest in automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for textile flame retardants concentrates in manufacturing clusters where fire safety enforcement intersects with large-scale textile production. Procurement authority is migrating toward end-user safety departments at major defense contractors and industrial buyers.
United States
Military textile programs drive volume commitments for aramid and modacrylic fiber treatments meeting FAA and NHTSA durability standards. The FAA maintains strict flame resistance requirements for aircraft interior materials. Defense contractors in the Southeast and Texas centralize procurement around certified chemical suppliers, bypassing traditional regional finishing houses.
Germany
Industrial safety buyers qualify nano-engineered layered double hydroxides for arc-flash protective garments ahead of EU PPE regulation updates. ECHA administers REACH authorization requirements that phase out halogenated compounds. The Ruhr industrial corridor hosts technical textile producers restructuring supply agreements for compliant barrier technologies.
China
Domestic textile mills upgrade finishing capabilities under MEE enforcement of GB national standards for public building textiles. SAMR oversees market access rules that favor phosphorus-based formulations. The Yangtze River Delta textile clusters generate captive demand as fire safety code enforcement intensifies across Jiangsu and Zhejiang provinces.
India
The PLI scheme and BIS certification expansion for protective workwear create entry points for phosphorus-based suppliers establishing local compounding operations. CDSCO and BIS jointly regulate technical textile safety specifications. Technical textile corridors in Gujarat and Tamil Nadu attract foreign formulators embedding technical service teams inside production clusters.
Japan
Automotive seating producers under METI recycling mandates specify polymer-inherent flame retardancy solutions that eliminate separate finishing steps. The country's national chemical safety regulator enforces alignment with international automotive standards. Chubu region automotive textile suppliers integrate flame resistance directly into PET and nylon spinning processes.
Textile Flame Retardants Market Key Industry Players
European producers anchor one tier with REACH-compliant phosphorus-based portfolios; North American specialists hold military and aerospace certification authority through bromine and phosphorus specialties. The vendor base splits between consolidated multinational chemical conglomerates and focused technical textile additive suppliers. Three archetypes dominate: integrated polymer science conglomerates, phosphorus chemistry specialists, and technical service-oriented formulators. Competitive moves center on polymer-inherent technology licensing and direct mill partnerships that bypass traditional distribution channels.
Among the integrated tier, Clariant AG represents the European REACH-compliant archetype with phosphorus-based positioning, while Albemarle Corporation anchors North American supply through elemental bromine and phosphorus specialties. BASF SE occupies a position emphasizing polymer modification technology that embeds flame retardancy into fiber structures rather than surface treatments. These three exemplify how geographic regulatory divergence shapes competitive specialization.
| Leading Market Players |
|---|
| Clariant AG |
| Albemarle Corporation |
| BASF SE |
| Milliken & Company |
| Solvay S.A. (Syensqo) |
| DuPont de Nemours, Inc. |
| ICL Group Ltd. |
| Huntsman Corporation |
| Lanxess AG |
| Others |
Cost & Logistics Intelligence
Defense procurement centralization around certified suppliers is compressing margins for non-compliant formulators while elevating premiums for REACH-authorised phosphorus-based portfolios. This buyer-side consolidation forces supply chain restructuring toward dual-qualified manufacturing hubs, raising qualification costs but securing pricing power for integrated compounders.
Pricing Analysis
Volume-margin splits separate commodity additive finishes from polymer-inherent formulations. Pricing stratifies across aerospace-certified premium tiers, industrial-standard mid-tiers, and economy additive grades for home textiles. Cost compression in standard-tier phosphorus compounds is intensifying because elemental phosphorus feedstock volatility from Chinese export quotas feeds through to formulator margins. Home textile procurement teams exhibit highest price sensitivity; defense aerospace buyers show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Boeing and Lockheed Martin procurement organizations require textile mills to qualify multiple flame retardant suppliers simultaneously. Elemental phosphorus concentrates in China, Kazakhstan, and Morocco; specialty phosphorus derivatives concentrate in Germany and the United States. Raw material dependencies rest on phosphate rock mining, chlor-alkali chlorine supply, and organophosphorus intermediate synthesis. Single-source vulnerability sits with Chinese elemental phosphorus export quotas. Distribution runs through technical service teams embedded directly in textile manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and phosphorus feedstock volatility are forcing mid-size additive suppliers toward exit or acquisition, consolidating competitive control among integrated compounders with captive raw material positions.
For Market Incumbents: Deepen backward integration into elemental phosphorus or phosphate rock positions to insulate margins from Chinese export quota volatility. Expand technical service teams inside Chinese Yangtze River Delta textile clusters to capture specification authority before product development finalizes. Defend against bio-based entrants by accelerating polymer-inherent technology licensing to Japanese automotive seating producers. For New Entrants and Emerging Players: Capture India's technical textiles corridor under PLI scheme incentives by establishing local compounding operations for phosphorus-based protective workwear formulations. Target Scandinavian contract textile buyers facing EU Green Deal procurement rules with chitosan and phytic acid bio-based portfolios. Lead with sustainability certification narratives rather than cost parity against petrochemical alternatives. For Investors and Strategic Acquirers: The window for entry favors mid-size phosphorus chemistry specialists with REACH-compliant product libraries and established aerospace certification. Long-term viability hinges on polymer-inherent technology transition away from surface-finishing commoditization. Watch for MEE enforcement intensity in China as inflection signal for captive domestic demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Feedstock | Secures margin insulation against Chinese elemental phosphorus export quota volatility. |
| Polymer-Inherent Technology Licensing | Eliminates separate finishing steps for Japanese automotive seating producers under METI mandates. |
| Technical Service Team Embedding | Captures specification authority inside Chinese Yangtze River Delta textile clusters. |
| REACH-Compliant Portfolio Expansion | Maintains European aerospace market access as ECHA phases out halogenated alternatives. |
| Bio-Based Formulation Qualification | Opens Scandinavian contract textile procurement governed by EU Green Deal sustainability rules. |
Research Approach
Trade databases, ECHA authorization registries, and SEC chemical company filings formed the secondary backbone, cross-referenced with primary interviews across technical textile R&D directors, defense procurement officers, plant managers at phosphorus compounders, and distribution channel partners. Bottom-up volume modeling triangulated against top-down macroeconomic projections validated segment-level demand estimates.
Historical trendline analysis of phosphorus-based formulation adoption rates, halogenated chemistry substitution trajectories, and regional regulatory enforcement patterns established baseline growth assumptions across the projection horizon. Segmentation modeling incorporated chemistry type, application durability requirements, technology integration depth, and end-user certification burden. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points and feedstock supply disruptions.
The model holds under stable REACH enforcement intensity and continued Chinese GB standard implementation; deviation in MEE enforcement rigor or elemental phosphorus export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Pegylated Lipids Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
US Post Laser Recovery Products Market