
 Alkali Metal Hydroxides Market | 2026-2036
Alkali Metal Hydroxides Market Size, Share, and Industry Trends Forecast 2026-2036
Alkali Metal Hydroxides Market Analytics
Water treatment and battery cathode manufacturing is expanding as the fastest-growing end-use vertical mix for alkali metal hydroxides. Albemarle Corporation leverages its Nevada lithium extraction assets to anchor battery-grade lithium hydroxide supply chains. Solvay sustains its European chlor-alkali network through membrane technology specialization. BASF competes on integrated chemical synthesis platforms that consume sodium hydroxide at scale.
Alkali metal hydroxides comprise strongly basic compounds of Group 1 metals—primarily sodium hydroxide (NaOH, caustic soda), potassium hydroxide (KOH), and lithium hydroxide (LiOH)—typically produced via chlor-alkali electrolysis of brine with membrane cell technology achieving 32-50% concentration grades. Their primary industrial purpose spans pH neutralization, saponification, chemical intermediate synthesis, and increasingly lithium salt production for energy storage. Sodium hydroxide retains the largest volume share across pulp bleaching and petroleum refining applications, while lithium hydroxide claims the fastest value growth trajectory tied to nickel-rich cathode chemistries. Industrial grade material dominates total tonnage, though battery-grade lithium hydroxide commands premium pricing through stricter impurity thresholds.
China's MEE enforces dual carbon emission intensity caps on chlor-alkali operations, while the EU Green Deal and REACH restrict mercury cell technology and classify sodium hydroxide handling standards. India's BIS certification mandates product purity labeling for imported caustic soda. Stakeholders must monitor regulatory divergence between Asian production cost advantages and European carbon border adjustment mechanisms when siting new electrolysis capacity.
Market Dynamics
Membrane cell technology diffusion is compressing energy intensity differentials between chlor-alkali producers while China's MEE dual carbon enforcement accelerates capacity consolidation around integrated chemical clusters.
Growth Catalysts
- Battery cathode chemistry pivot:Nickel-rich NMC formulations require battery-grade lithium hydroxide with sub-20ppm impurity thresholds. EV manufacturers in East China chemical clusters are securing dedicated supply lines.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive caustic soda are incentivizing European chlor-alkali restarts with renewable power purchase agreements.
- Membrane cell retrofits:Diaphragm and mercury cell conversions to ion-exchange membrane technology cut electricity consumption by 15-20% per ton of NaOH equivalent.
Market Restraints
- Brine supply concentration:High-purity lithium brine extraction depends on Chilean Atacama and Argentine salar concessions controlled by three integrated producers.
- Power cost volatility:Electrolysis operations consume 2,100-2,400 kWh per ton of caustic soda; European natural gas price spikes render marginal capacity uneconomic.
- Caustic potash substitution:Sodium hydroxide displaces potassium hydroxide in detergent formulations where mildness requirements permit the switch.
Strategic Opportunities
- Direct shipping ore-to-hydroxide conversion:Australian spodumene concentrate processors are integrating calcination and acid roasting to capture margin upstream of Chinese refiners.
- US Inflation Reduction Act domestic content credits:Battery cell and pack assembly incentives are pulling lithium hydroxide refining capacity toward North American free trade agreement zones.
- Industrial symbiosis clusters:Chlor-alkali plants co-located with pulp mills and alumina refineries monetize hydrogen byproduct and share brine preprocessing infrastructure.
Industry Challenges
- Battery-grade purification bottlenecks:Boron and magnesium removal to sub-10ppm levels requires solvent extraction trains with 18-24 month commissioning timelines.
- Electrolyzer membrane supply constraints:Perfluorinated ionomer sheet production is concentrated with two specialty chemical suppliers, extending order backlogs to 14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkali Metal Hydroxides Market |
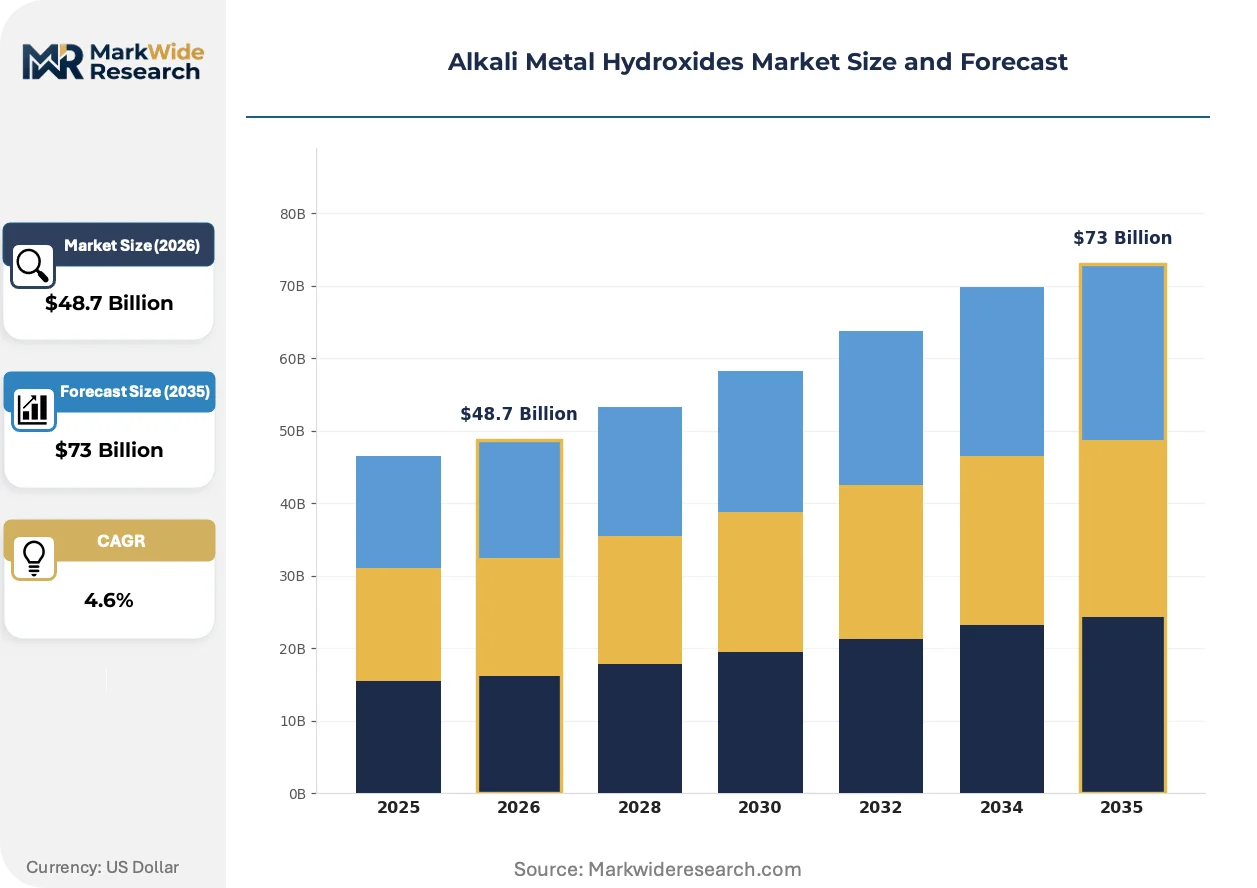
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Hydroxide, Potassium Hydroxide, Lithium Hydroxide, Calcium Hydroxide End Use Industry: Pulp & Paper, Pharmaceuticals, Water Treatment, Textile Grade: Industrial Grade, Food Grade, Laboratory Grade, Technical Grade Application: pH Regulation, Chemical Synthesis, Soap Making, Batteries |
| Companies Covered | Albemarle Corporation, Solvay, BASF, Dow, Olin Corporation, Occidental Petroleum Corporation, Tata Chemicals, Gujarat Alkalies and Chemicals Limited, Westlake Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkali Metal Hydroxides Market Evolving Landscape
Electrification of transport chemistry is rewriting specification sheets for alkali metal hydroxides while process intensification and regulatory carbon accounting reshape production economics.
Modular skid-mounted chlor-alkali units rated below 10,000 tons annual capacity are decentralizing supply for remote mining operations and islanded industrial zones. Copper-nickel alloy cathode designs from European engineering firms cut installation footprints by 60%. Off-grid solar-hybrid power integration is enabling African and Middle Eastern entrants to bypass transmission infrastructure gaps.
China's GB 31573-2015 emission standard revisions are tightening particulate and chlorine release limits for existing membrane cell installations. Provincial environmental bureaus in Jiangsu and Shandong are denying capacity expansions without demonstrated renewable power offtake. Incumbent producers are responding with chlorine derivative integration into PVC and isocyanate chains to absorb captive output.
Long-term offtake contracting with cathode active material plants is displacing spot market liquidity for battery-grade lithium hydroxide. Korean and Japanese battery makers are inserting origin traceability clauses requiring exclusion of certain brine sources. Contract structures now index to London Metal Exchange lithium carbonate futures with quality-adjusted premia rather than historical fixed-price frameworks.
Alkali Metal Hydroxides Market Segmentation
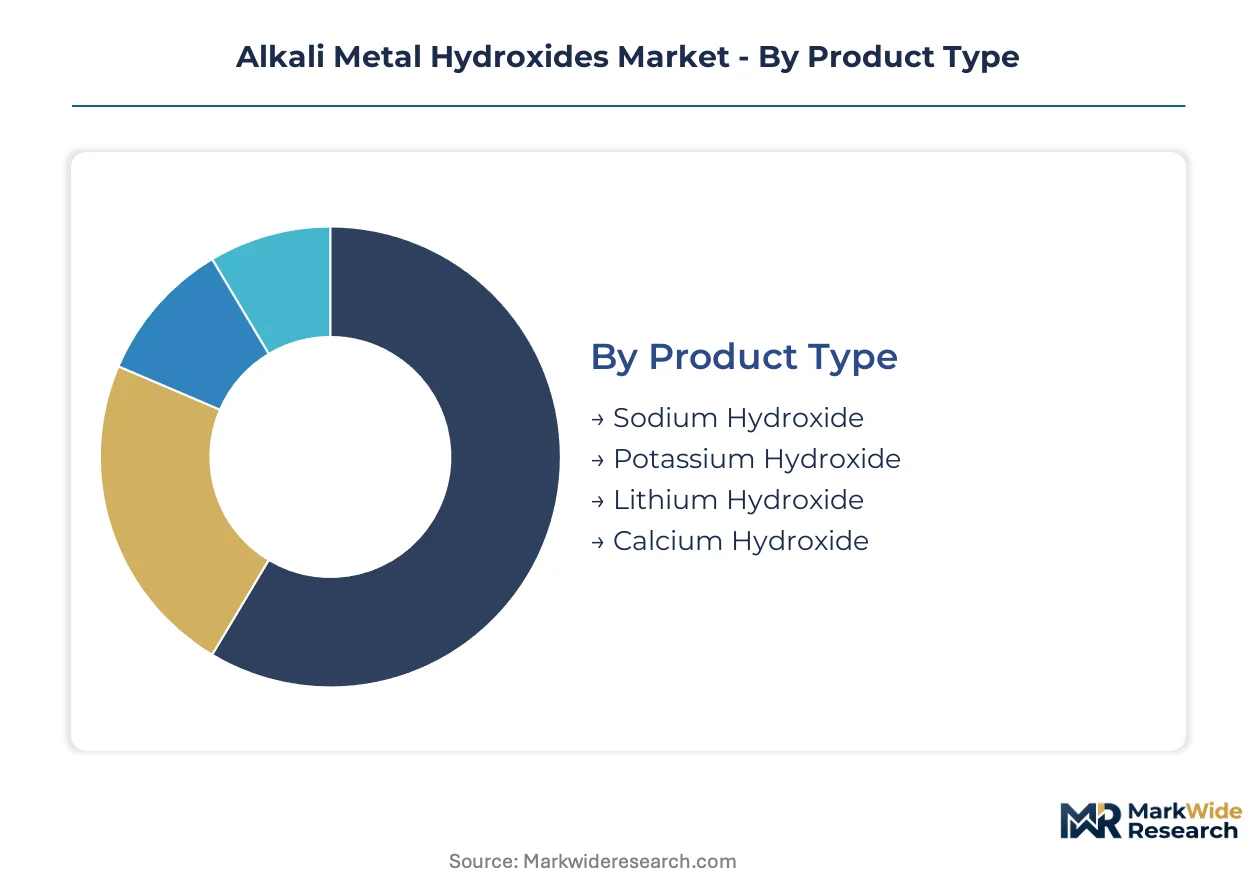
Alkali metal hydroxides serve divergent industrial specifications that dictate electrolyzer configuration, purification train investment, and offtake contracting structures. Segmentation reveals where capital deployment concentrates and which purity thresholds command premium pricing.
Product Type:
Capital intensity varies sharply across electrolysis chemistries, with lithium extraction and conversion requiring the heaviest upstream investment.
- Sodium Hydroxide:Membrane cell electrolysis of saturated brine yields 32-50% NaOH solution with chlorine and hydrogen co-products. Pulp mills in the US Southeast and alumina refineries in Western Australia absorb the largest merchant volumes.
- Lithium Hydroxide:Battery-grade material demands spodumene calcination, acid roasting, and solvent extraction trains to achieve sub-20ppm impurity thresholds. East China chemical clusters around Ningbo are securing dedicated supply lines from Australian concentrate processors.
- Potassium Hydroxide:Electrolysis of potassium chloride brine generates caustic potash for liquid soap and potassium carbonate synthesis.
- Calcium Hydroxide:Slaked lime production via hydration of quicklime serves flue gas desulfurization and water softening at lower unit capital cost.
Most installed capacity flows through sodium hydroxide. Expansion is steepest in lithium hydroxide.
End Use Industry:
Customer concentration patterns determine contract duration and pricing indexation structures across verticals.
- Pulp & Paper:Chlorine dioxide generation and pulp bleaching consume industrial-grade caustic soda in continuous digesters. Scandinavian integrated mills and Brazilian pulp exporters operate the largest single-site offtake agreements.
- Water Treatment:pH adjustment and heavy metal precipitation drive municipal and industrial demand. German municipal utilities and Saudi desalination complexes specify membrane-grade material to avoid mercury cell contamination.
- Pharmaceuticals:GMP-compliant potassium hydroxide serves active pharmaceutical ingredient synthesis and excipient neutralization.
- Textile:Mercerization of cotton fibers and dye bath pH control absorb standard-grade sodium hydroxide in South Asian spinning operations.
Pulp and paper anchors contract volumes. Water treatment is gaining share fastest on desalination buildouts.
Grade:
Purification intensity separates pricing tiers, with battery and food applications demanding contaminant controls that multiply processing costs.
- Industrial Grade:Standard membrane cell output with 97-99% purity serves bulk neutralization and chemical synthesis without further refinement. Chinese chlor-alkali producers in Shandong province dominate merchant supply.
- Food Grade:Heavy metal limits per FDA and EFSA specifications require additional filtration and packaging controls for food processing and beverage applications.
- Laboratory Grade:ACS reagent specifications with documented impurity certificates support analytical chemistry and quality control laboratories.
- Technical Grade:Intermediate purity for soap manufacturing and petroleum refining where color stability matters less than cost.
Industrial grade carries the tonnage base. Food grade commands the steepest purity premia.
Application:
Functional requirements dictate specification sheets, with battery cathode chemistry imposing the most stringent impurity ceilings.
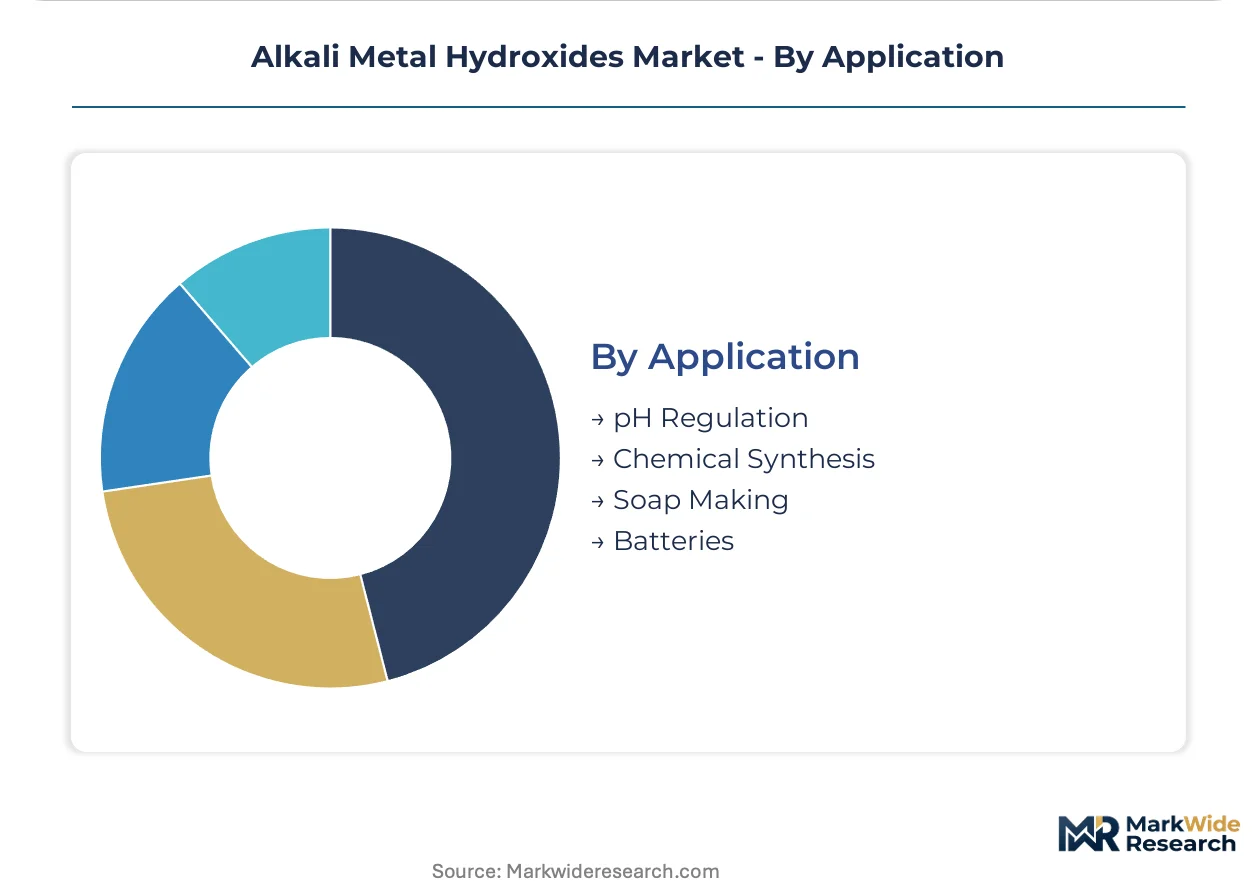
- Batteries:Nickel-rich NMC cathode production requires battery-grade lithium hydroxide with sub-10ppm boron and magnesium levels. Korean cathode active material plants are inserting origin traceability clauses into long-term offtake contracts.
- pH Regulation:Continuous neutralization in wastewater treatment and chemical process streams consumes the largest absolute volumes of standard-grade material.
- Chemical Synthesis:Sodium methoxide, epoxides, and various organic intermediates rely on anhydrous or aqueous caustic soda as nucleophilic reagents.
- Soap Making:Saponification of fats and oils with sodium or potassium hydroxide produces bar and liquid detergents for household and industrial cleaning.
pH regulation handles the volume throughput. Batteries show the sharpest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China chemical clusters around Shanghai and Ningbo concentrate the world's largest chlor-alkali capacity and battery-grade lithium hydroxide refining operations.
China
East China chemical clusters absorb the majority of domestic chlor-alkali output for PVC and isocyanate derivative chains. MEE dual carbon enforcement tightens emission intensity caps on existing membrane cell installations. Provincial environmental bureaus in Jiangsu and Shandong deny capacity expansions without demonstrated renewable power offtake agreements.
United States
Gulf Coast petrochemical corridors and Southeast pulp mills drive merchant caustic soda offtake for bleaching and petroleum refining applications. IRA domestic content credits pull lithium hydroxide refining capacity toward North American free trade agreement zones. Albemarle Corporation leverages Nevada lithium extraction assets to anchor regional battery-grade supply chains.
Germany
Ruhr industrial basin chlor-alkali plants serve integrated chemical synthesis platforms consuming sodium hydroxide at scale. EU Green Deal carbon border adjustments incentivize facility restarts with renewable power purchase agreements. BASF operates membrane technology networks that supply captive demand across Ludwigshafen and Antwerp corridors.
India
Gujarat chemical complexes and Maharashtra industrial zones absorb caustic soda for textile mercerization and detergent manufacturing. BIS certification mandates product purity labeling for imported sodium hydroxide shipments. Tata Chemicals and Gujarat Alkalies and Chemicals Limited anchor domestic membrane cell capacity around Mundra and Dahej port infrastructure.
Australia
Western Australian spodumene concentrate processors integrate calcination and acid roasting to capture margin upstream of Chinese refiners. Direct shipping ore-to-hydroxide conversion investments concentrate around Greenbushes and Pilbara mining districts. Korean and Japanese battery makers insert origin traceability clauses requiring Australian concentrate provenance for cathode active material supply.
Alkali Metal Hydroxides Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit diaphragm and mercury cell installations to ion-exchange membrane technology. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive chlor-alkali consumption, specialty lithium extractors serving battery cathode specifications, and regional membrane cell operators supplying merchant caustic markets. M&A consolidation and geographic repositioning toward IRA-compliant zones represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, BASF and Solvay exemplify European membrane technology specialization with captive demand absorption across diversified product portfolios. Albemarle Corporation anchors the specialty lithium extraction archetype through Nevada brine assets and Australian spodumene offtake relationships. Dow and Olin Corporation occupy positions among North American scale-driven operators with Gulf Coast logistics advantages and pulp mill integration networks.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Solvay |
| BASF |
| Dow |
| Olin Corporation |
| Occidental Petroleum Corporation |
| Tata Chemicals |
| Gujarat Alkalies and Chemicals Limited |
| Westlake Corporation |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers in China's East China chemical clusters anchor supply discipline through state-directed capacity consolidation, translating MEE dual carbon enforcement into tighter pricing control across battery-grade lithium hydroxide and industrial caustic soda tiers.
Pricing Analysis
Distributor margins on battery-grade lithium hydroxide compress as cathode active material plants negotiate direct-to-OEM offtake contracts indexed to London Metal Exchange futures. Three-tier pricing structure across battery-grade, food-grade, and industrial-grade material separates sub-20ppm purity thresholds from standard membrane cell output. Cost compression in industrial-grade caustic soda intensifies because Shandong province membrane cell operators compete on volume scale. Pulp mills and alumina refineries exhibit highest price sensitivity; Korean cathode makers show lowest sensitivity due to origin traceability requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from East China chemical clusters, while merchant distributors serve fragmented textile and water treatment accounts. Supply concentrates in China, Chile, and Australia—Chinese membrane cell capacity absorbs half of global chlor-alkali output, Chilean Atacama brine concessions feed lithium extraction, and Australian spodumene processors integrate calcination stages. Raw material dependencies rest on high-purity lithium brine, saturated sodium chloride brine, and perfluorinated ionomer membrane sheets. Single-source vulnerability in electrolyzer membrane supply extends order backlogs to fourteen months. Distribution runs through integrated chemical conglomerates with captive demand absorption and regional membrane cell operators supplying merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon border adjustments and China's MEE dual carbon enforcement accelerate demand for membrane cell retrofits and battery-grade purification capacity.
For Market Incumbents: Cement membrane technology specialization through ion-exchange retrofits of diaphragm and mercury cell installations, cutting electricity consumption by fifteen to twenty percent per ton. Absorb captive chlorine output into PVC and isocyanate derivative chains to defend margin position against Shandong province volume competitors. Prioritize renewable power purchase agreements to secure provincial environmental bureau approval for capacity expansions in Jiangsu and Shandong. For New Entrants and Emerging Players: Remote mining operations and islanded industrial zones present underserved buyer archetypes for modular skid-mounted chlor-alkali units rated below ten thousand tons annual capacity. African and Middle Eastern markets with off-grid solar-hybrid power integration offer lowest competitive density. Pursue direct shipping ore-to-hydroxide conversion partnerships with Australian spodumene concentrate processors to bypass Chinese refiner margins. For Investors and Strategic Acquirers: Valuations sit cheapest among regional membrane cell operators lacking chlorine derivative integration. Long-term viability centers on electrolyzer membrane supply security and renewable power offtake positioning across the analysis window. Target acquisition archetype: Australian spodumene processors with calcination and acid roasting assets. Watch commissioning timelines for solvent extraction trains achieving sub-10ppm boron and magnesium removal as inflection indicator for battery-grade supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | Converting diaphragm and mercury installations to ion-exchange technology cuts electricity consumption fifteen to twenty percent per ton. |
| Backward Integration into Spodumene | Australian concentrate processors capture margin upstream of Chinese refiners through calcination and acid roasting integration. |
| Renewable Power Purchase Agreement | European restarts and Chinese expansions require demonstrated renewable offtake to satisfy EU carbon border adjustments and MEE dual carbon enforcement. |
| Long-term Supply Agreement | Korean and Japanese battery makers insert origin traceability clauses requiring Australian concentrate provenance for cathode active material supply. |
| Joint Venture for Lithium Refining | IRA domestic content credits pull lithium hydroxide capacity toward North American free trade agreement zones through partnership structures. |
Research Methodology
Multiple input streams — technical discussions with chlor-alkali plant managers and lithium extraction operators, procurement lead interviews at cathode active material plants, and validation with membrane technology engineering firms — were reconciled against customs data, ACC and Cefic industry reports, and SEC filings from integrated chemical conglomerates. Bottom-up capacity modeling across electrolyzer configurations was triangulated with top-down demand aggregation from end-use industries including pulp mills, alumina refineries, and battery cell manufacturers.
Data-stream reconciliation applied analytical frameworks across the projection horizon, modeling segmentation dimensions including grade tier, end-use industry, and regional production hub. CAGRs were derived from electrolyzer capacity expansion pipelines, EV cathode chemistry adoption curves, and chlor-alkali operating rate assumptions. Forecast inputs incorporated MEE dual carbon enforcement timelines, EU carbon border adjustment implementation, and perfluorinated ionomer membrane supply constraints.
Underlying measurement precision varies by segment; battery-grade lithium hydroxide carries tighter precision than industrial-grade caustic soda due to concentrated producer base and transparent offtake contracting. Forecasts reflect assumptions around membrane technology diffusion rates, renewable power cost trajectories, and cathode chemistry specifications that could revise with regulatory acceleration or technology substitution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Cesium Hydroxide Market