
 Polyphosphate Market | 2026-2036
Polyphosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphosphate Market Insights
Technical service contracts for dosing-system calibration and performance monitoring is rebalancing how polyphosphate suppliers capture lifetime value from municipal and industrial accounts. ICL Group leverages its integrated phosphate rock position to sustain cost-advantaged supply across linear and condensed grades. Prayon anchors European water-treatment demand through specialized technical-service teams embedded with utility operators. Clariant differentiates via flame-retardant polyphosphate formulations for textile and polymer applications, competing on specification breadth rather than commodity volume.
Polyphosphate denotes a chain or ring of condensed phosphate units, typically synthesized via thermal dehydration of orthophosphate salts to yield glassy, linear, or cyclic structures with variable chain lengths from two to several hundred units; manufacturers control solubility and sequestration capacity through calcination temperature and sodium-to-calcium ratio adjustment. Its primary commercial purpose centers on chelating calcium and magnesium ions to inhibit scale formation, disperse colloids, and stabilize pH across water treatment, detergent, and metal-finishing processes. Glassy polyphosphate dominates current volume owing to lowest unit production cost and broad compatibility with legacy dosing equipment, while cyclic polyphosphate claims expanding share in precision metal treatment where controlled hydrolysis rates justify premium positioning. Water treatment remains the largest application pool by tonnage, though food preservation represents a concentrated margin segment where NSF and FDA compliance creates supplier stickiness and pricing power.
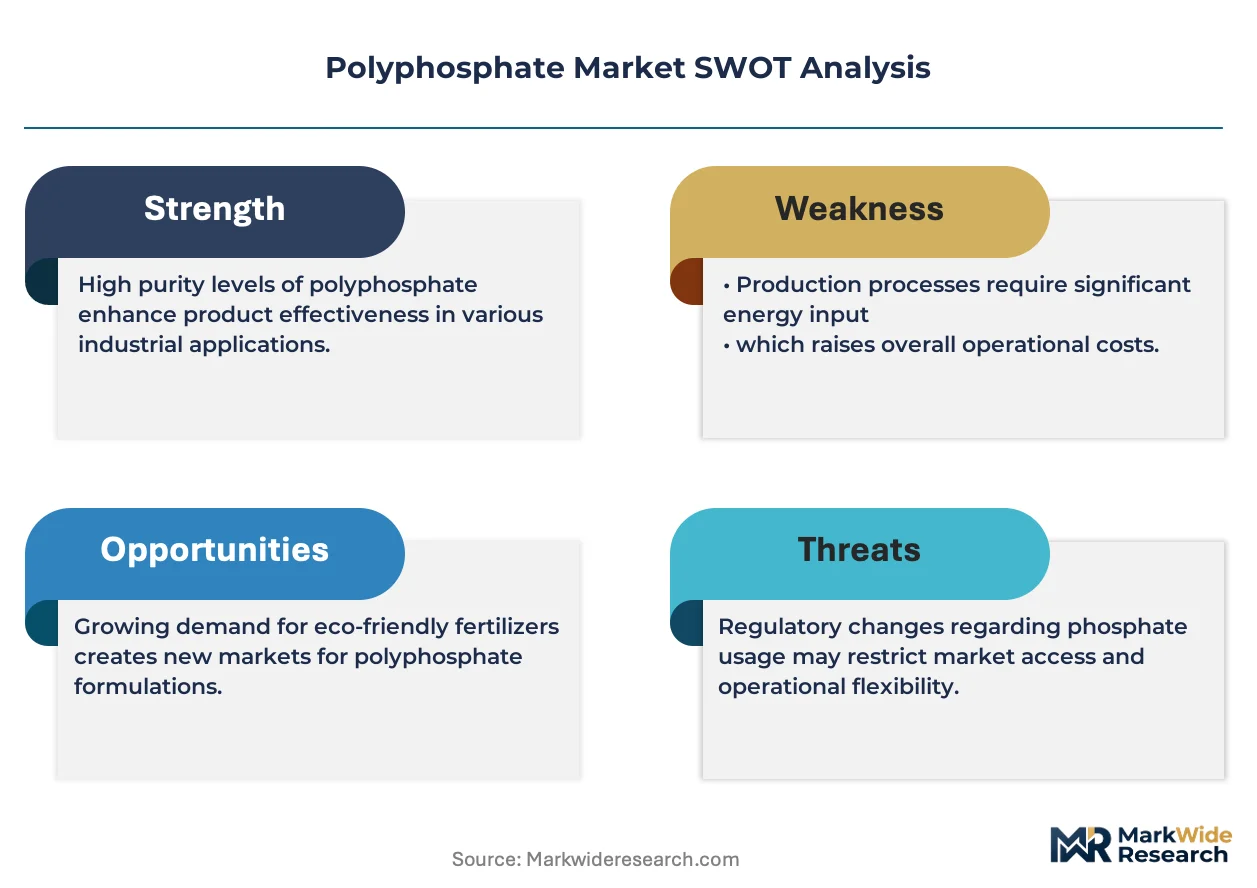
EPA discharge limits under the Clean Water Act and REACH Annex XVII restrictions on phosphate content in consumer detergents are reshaping product specifications and regional manufacturing footprints simultaneously. China's MEE enforces stricter total phosphorus caps for industrial wastewater, redirecting domestic polyphosphate capacity toward higher-purity grades for compliance-driven replacement cycles. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized multi-grade production or region-specialized asset configuration delivers superior returns through the forecast horizon.
Market Dynamics
Water treatment utilities are consolidating procurement around integrated dosing-system contracts, compressing supplier margins on commodity polyphosphate while expanding lifetime revenue capture through calibration and monitoring services.
Growth Catalysts
- EPA discharge limits under the Clean Water Act:Municipal utilities across the United States face tightening total phosphorus caps, forcing accelerated replacement of legacy scale inhibitors with higher-purity polyphosphate formulations.
- China's ceramic surface treatment expansion:Glassy polyphosphate demand concentrates in Foshan and Zibo industrial clusters where porcelain enamel and metal finishing output scales rapidly.
- Condensed phosphate chain-length engineering:Manufacturers now control hydrolysis rates through calcination temperature adjustment, unlocking precision applications in electronics metal finishing previously served by organic chelants.
Market Restraints
- Phosphate rock supply concentration:Morocco and Western Sahara hold roughly three-quarters of proven reserves, exposing linear polyphosphate producers to geopolitical disruption and export quota volatility.
- REACH Annex XVII detergent restrictions:The European framework caps phosphate content in consumer laundry and dishwasher products, eliminating volume outlets that once absorbed commodity-grade output.
- Organic polymer substitute advancement:Polyacrylate and phosphonate alternatives achieve comparable scale inhibition at lower environmental discharge risk in sensitive watersheds.
Strategic Opportunities
- India's municipal water infrastructure buildout:The Jal Jeevan Mission and AMRUT 2.0 schemes deploy centralized treatment across tier-2 and tier-3 cities, creating first-mover advantage for technical service-anchored suppliers.
- Food-grade polyphosphate certification:NSF/ANSI 60 and FDA 21 CFR compliance for direct food contact applications commands pricing premiums three to four times above technical grades.
- Smart dosing system integration:IoT-enabled flow-proportional feed controllers converge with predictive analytics platforms, enabling subscription-based chemical management contracts.
Industry Challenges
- Analytical chemist scarcity for orthophosphate-polyphosphate speciation:Accurate chain-length distribution testing requires ion chromatography expertise that remains concentrated in legacy phosphate mining regions.
- Legacy dosing equipment incompatibility:Municipal utilities operate dry-feed and solution-feed systems installed decades prior, complicating transition to engineered condensed grades with different dissolution kinetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphosphate Market |
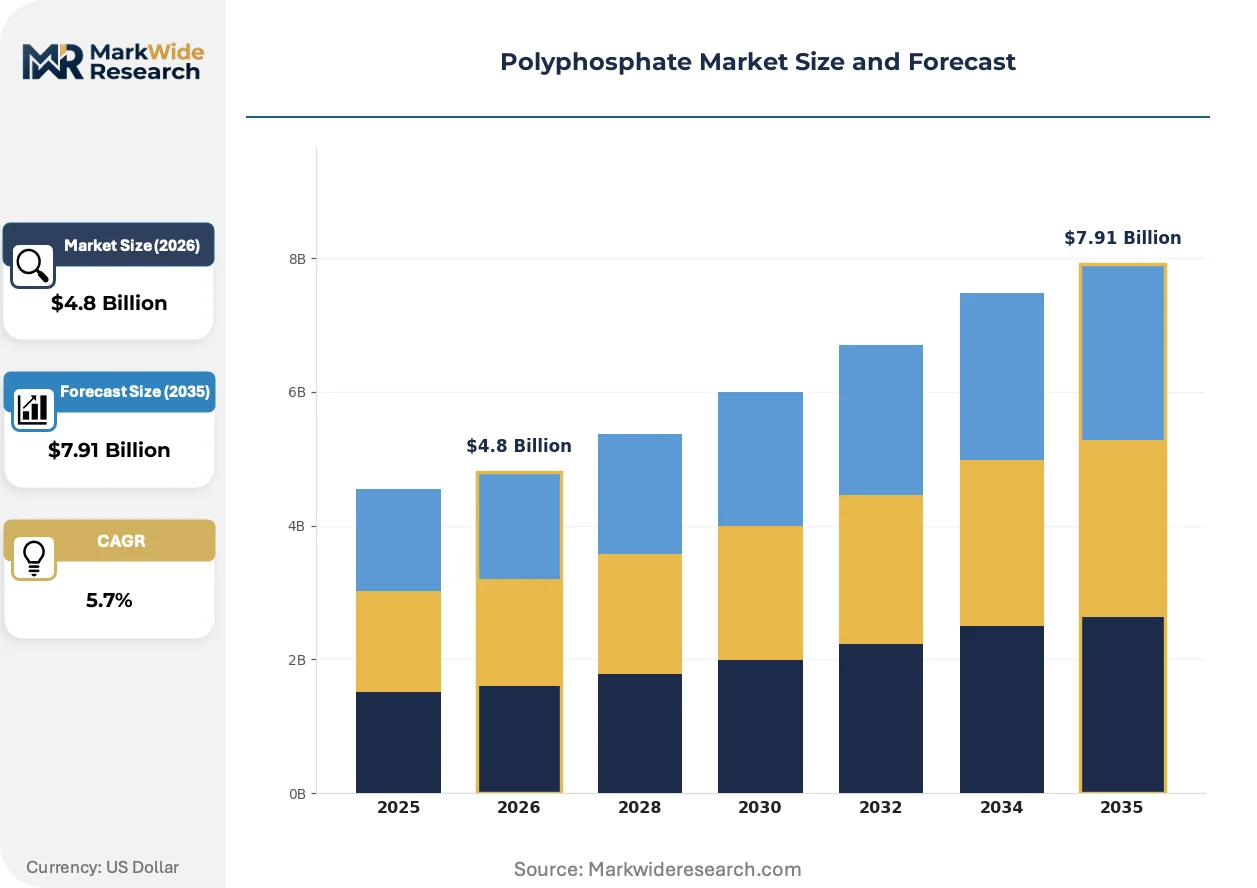
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Polyphosphate, Cyclic Polyphosphate, Condensed Polyphosphate, Glassy Polyphosphate Application: Water Treatment, Detergent Formulation, Food Preservation, Metal Treatment End Use Industry: Agriculture, Paper & Pulp, Textile Processing, Ceramics Manufacturing Packaging Type: Bulk Bags, Paper Bags, Plastic Containers, Drums |
| Companies Covered | ICL Group, Clariant, Nutrien, Budenheim, Prayon, Yara International, CF Industries, OCP Group, The Mosaic Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphosphate Market Trends and Innovations
Precision control over polyphosphate chain-length distribution is fragmenting the commodity market into specification-tightened segments, while regulatory pressure on phosphorus discharge accelerates substitution of legacy chemistries.
Cyclic polyphosphate is overtaking linear glassy grades in precision metal treatment applications where controlled hydrolysis rates prevent over-chelation and substrate etching. Aerospace and electronics finishers in Germany and Japan specify ring-structured phosphates for aluminum anodizing and printed circuit board metallization. This displacement is compressing margins on standard-grade output while rewarding manufacturers with calcination flexibility.
REACH authorization requirements for sodium tripolyphosphate in consumer detergents have triggered wholesale reformulation across European formulators. Industrial laundries and institutional cleaning operations now absorb displaced technical-grade volume, though at lower per-ton pricing. The regulation is forcing integrated phosphate producers to reallocate furnace capacity toward water-treatment and food-grade specifications.
Technical service contracts now bundle chemical supply with remote monitoring and predictive maintenance, displacing traditional spot-purchase arrangements. Water treatment operators in the Netherlands and Singapore increasingly specify outcome-based agreements where suppliers guarantee scale-free operation rather than merely delivering product. This compression of the traditional distributor channel is visible most acutely in desalination and power generation verticals.
Polyphosphate Market Segmentation
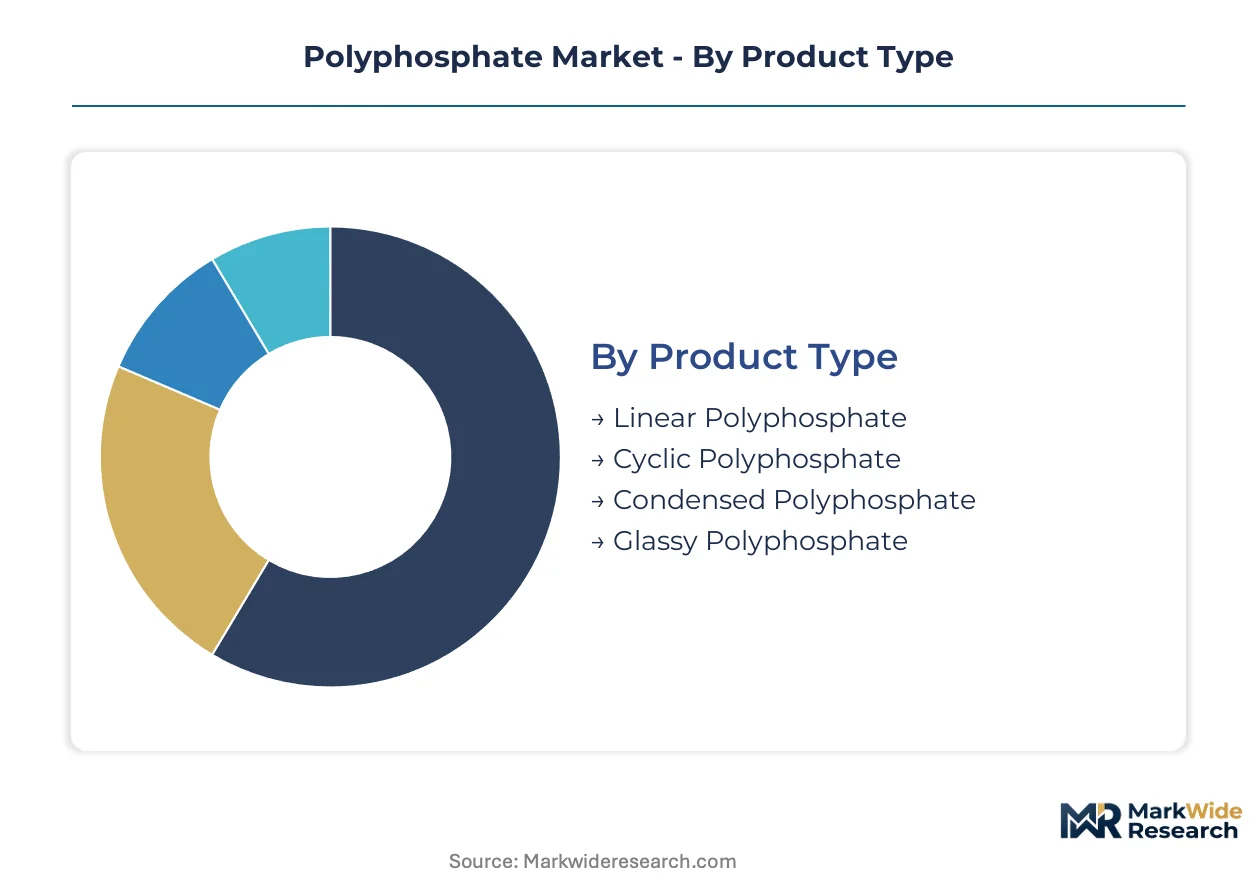
Polyphosphate manufacturers engineer distinct molecular architectures and delivery formats to match precise performance requirements across water chemistry, food safety, and industrial surface treatment protocols. Specification differentiation determines pricing power and supplier stickiness in this technically fragmented market.
Product Type:
Customization intensity varies sharply across this category, from commodity glassy grades produced at scale to precision-engineered cyclic structures commanding formulation premiums.
- Linear Polyphosphate:Chain-structured phosphates with two to several hundred condensed units, synthesized via controlled thermal dehydration of orthophosphate salts. Municipal water utilities in the United States specify linear grades for calcium sequestration under EPA discharge compliance timelines.
- Cyclic Polyphosphate:Ring-structured condensed phosphates exhibiting slower, more predictable hydrolysis kinetics. German and Japanese aerospace finishers specify cyclic grades for aluminum anodizing where controlled chelation prevents substrate etching.
- Condensed Polyphosphate:Intermediate chain-length products bridging linear and highly condensed structures. Found in industrial boiler water treatment where moderate sequestration rates balance performance against cost.
- Glassy Polyphosphate:Amorphous, randomized chain distributions produced through rapid melt quenching. Dominates volume in China's Foshan and Zibo ceramic clusters for porcelain enamel and metal finishing applications.
Leading the category by volume: Glassy Polyphosphate. Expanding most quickly: Cyclic Polyphosphate.
Application:
End-use chemistry requirements split this category between high-volume treatment processes and concentrated-margin specialty certifications.
- Water Treatment:Scale inhibition and corrosion control across municipal distribution systems, industrial cooling towers, and reverse osmosis pretreatment. India's Jal Jeevan Mission deployment creates procurement acceleration for technical service-integrated suppliers.
- Detergent Formulation:Builder and dispersant functions in laundry and dishwashing products. REACH Annex XVII restrictions have eliminated consumer-grade volume in Europe, redirecting capacity toward industrial and institutional cleaning.
- Food Preservation:Moisture retention and shelf-life extension in processed meats and seafood. NSF/ANSI 60 and FDA 21 CFR compliance requirements create supplier stickiness and pricing premiums three to four times above technical grades.
- Metal Treatment:Surface preparation, conversion coating, and electroplating bath stabilization. Electronics manufacturers in Japan specify precision grades for printed circuit board metallization.
Highest margin capture: Food Preservation. Greatest tonnage: Water Treatment.
End Use Industry:
Customer technical sophistication and specification stringency divide this category between commodity procurement and engineered solution partnerships.
- Agriculture:Fertilizer coating and micronutrient chelation applications. Regional demand concentrates where phosphate rock integration supports cost-advantaged supply.
- Paper & Pulp:Pitch control and brightness stabilization during pulping and bleaching sequences. Mills specify polyphosphate grades compatible with closed-loop water systems.
- Textile Processing:Water softening and dye bath stabilization. Clariant and specialty chemical houses compete on flame-retardant polyphosphate formulations for technical textiles.
- Ceramics Manufacturing:Porcelain enamel adhesion and glaze suspension. China's expanding Foshan and Zibo industrial clusters absorb expanding glassy polyphosphate output.
Steepest expansion trajectory: Ceramics Manufacturing. Most specification-locked: Textile Processing.
Packaging Type:
Logistics economics and handling infrastructure at customer sites determine format selection across this category.
- Bulk Bags:One-ton flexible intermediate bulk containers for high-volume municipal and industrial accounts with pneumatic unloading systems.
- Paper Bags:Multi-wall kraft constructions for mid-scale water treatment and food processing facilities with conventional material handling.
- Plastic Containers:Rigid pails and totes for liquid polyphosphate solutions and moisture-sensitive condensed grades.
- Drums:Steel and fiber drums for specialty grades requiring lot traceability and controlled atmosphere storage.
Dominant by shipment weight: Bulk Bags. Growing fastest: Plastic Containers for solution delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the majority of glassy polyphosphate production capacity, while consumption concentrates in industrial water treatment clusters across Germany, the United States, and Japan. This production-consumption divide shapes trade flows and regional pricing differentials throughout the forecast period.
United States
Municipal utilities under EPA Clean Water Act discharge limits are accelerating replacement of legacy scale inhibitors with higher-purity formulations. The EPA's tightening total phosphorus caps force procurement shifts across Great Lakes and Chesapeake Bay watershed states. Industrial demand clusters in Texas and Louisiana where petrochemical cooling towers require continuous polyphosphate dosing.
Germany
REACH Annex XVII detergent restrictions have eliminated consumer-grade phosphate volume, redirecting domestic capacity toward water-treatment and food-grade specifications. ECHA authorization timelines pressure formulators to complete reformulation by regulatory deadlines. Aerospace finishers in Bavaria specify cyclic polyphosphate grades for precision aluminum anodizing applications.
China
MEE enforcement of stricter total phosphorus caps for industrial wastewater redirects domestic capacity toward higher-purity grades. Glassy polyphosphate output concentrates in Foshan and Zibo ceramic clusters where porcelain enamel production scales rapidly. Yangtze River Delta water treatment plants absorb expanding technical-grade volume for municipal distribution systems.
Japan
Electronics manufacturers in Osaka and Nagoya specify precision-engineered polyphosphate grades for printed circuit board metallization. METI industrial standards drive specification tightening across metal finishing supply chains. Kanto region semiconductor fabricators require controlled-hydrolysis formulations for wafer processing applications.
India
Jal Jeevan Mission and AMRUT 2.0 infrastructure schemes deploy centralized water treatment across tier-2 and tier-3 cities, creating procurement acceleration. BIS certification requirements for drinking water chemicals filter supplier eligibility. Gujarat and Maharashtra industrial corridors absorb technical-grade volume for textile processing and boiler water treatment.
Polyphosphate Market Competitive Landscape
Capital-heavy producers with captive phosphate rock positions compete with asset-light formulators focused on specification engineering and technical service delivery. The market structure tiers between integrated mining-chemical conglomerates and specialized downstream compounders. Three archetypes dominate: upstream-integrated phosphate miners, regional water-treatment specialists with embedded service teams, and application-focused formulation houses targeting food-grade or flame-retardant niches. Competitive moves center on furnace capacity reallocation toward higher-margin grades and technical service contract bundling to displace spot purchasing.
Within the integrated-mining tier, ICL Group and OCP Group represent archetypes of backward-controlled supply chains securing cost-advantaged feedstock access. Among European formulation specialists, Prayon and Budenheim occupy positions anchored by technical service capabilities embedded with utility operators. At the specialty-chemical end, Clariant exemplifies differentiation through specification breadth rather than commodity volume, competing on flame-retardant and precision-grade formulations for textile and polymer applications.
| Leading Market Players |
|---|
| ICL Group |
| Clariant |
| Nutrien |
| Budenheim |
| Prayon |
| Yara International |
| CF Industries |
| OCP Group |
| The Mosaic Company |
| Others |
Pricing and Supply Chain Analysis
Calcination temperature control for chain-length engineering is simultaneously lowering unit production costs for glassy grades and concentrating technical expertise among furnace operators with advanced thermal process capabilities. This production-method transition rewards manufacturers with flexible calcination assets while compressing margins on standardized output.
Pricing Analysis
Margin tightening in commodity glassy grades traces to REACH-driven detergent reformulation redirecting surplus technical-grade volume toward lower-priced industrial outlets. Three-tier pricing structure across food-grade, water-treatment, and technical grades separates NSF-certified output commanding fourfold premiums from ungraded bulk supply. Municipal utilities exhibit highest price sensitivity through consolidated procurement tenders, while aerospace finishers in Germany and Japan absorb premium cyclic grades with minimal elasticity.
Supply Chain Analysis
Freight cost differentials between phosphate rock extraction zones and calcination facilities favor integrated producers with captive Moroccan or Western Saharan feedstock access. Manufacturing concentrates in China, Morocco, and the United States, with downstream compounding anchored in Germany and Japan. Supply chain risk centers on single-source phosphate rock vulnerability, as downstream polyphosphate production draws from concentrated mining jurisdictions. Distribution runs through regional chemical distributors with technical service capabilities for municipal utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate rock supply concentration constrains furnace capacity expansion, propping pricing power for integrated producers with captive mining assets against formulators exposed to raw material volatility.
For Market Incumbents: Anticipate organic polymer substitute advancement by deepening technical service bundling to lock municipal accounts into performance-based contracts rather than commodity spot purchasing. Prioritize calcination flexibility investments enabling rapid grade switching between glassy and cyclic output as aerospace and electronics specifications tighten.
For New Entrants and Emerging Players: Begin with India's Jal Jeevan Mission deployment corridors, where technical service-anchored distribution remains underdeveloped relative to procurement acceleration. Target food-grade certification as the most penetrable premium tier, leveraging NSF/ANSI 60 compliance gaps among regional Indian and Southeast Asian compounders.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty-chemical conglomerates seeking phosphate rock integration to secure cost-advantaged flame-retardant and food-grade formulation inputs. Long-term viability favors assets with calcination flexibility and existing technical service infrastructure over pure-play mining positions. Watch EPA discharge limit enforcement consistency across Great Lakes and Chesapeake Bay watersheds as inflection indicator for North American water-treatment grade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Secures feedstock cost advantage against OCP Group and ICL Group positions. |
| Calcination Flexibility Investment | Enables rapid furnace reconfiguration between glassy and cyclic grade output. |
| Food-Grade Certification Program | Unlocks NSF/ANSI 60 and FDA 21 CFR premiums in processed meat applications. |
| Technical Service Team Embedding | Displaces distributor channel through direct utility operator partnerships. |
| Smart Dosing System Integration | Converges IoT-enabled controllers with subscription chemical management contracts. |
Research Methodology
Document review covered customs trade databases, SEC 10-K filings, and ECHA authorization timelines, complemented by interviews with phosphate plant managers, municipal water utility procurement leads, and specialty chemical distribution channel partners. Secondary validation drew from ACC and Cefic industry reports, MEE discharge enforcement bulletins, and EPA Clean Water Act implementation guidance. Bottom-up volume modeling triangulated against top-down phosphate rock consumption estimates.
Output projections span grade tier, end-use industry, packaging format, and regional production hub dimensions across the modeling period. CAGRs derived from regression analysis against historical phosphate rock price elasticity and regulatory enforcement intensity. Forecast inputs incorporated calcination capacity utilization rates and REACH Annex XVII reformulation completion timelines.
Underlying measurement precision varies by segment; food-grade and cyclic polyphosphate carry tighter precision than commodity glassy grades given certification traceability requirements. Forecasts reflect assumptions about MEE enforcement consistency and EPA discharge limit implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Global Mandelic Acid Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market