
 US Post Laser Recovery Products Market | 2026-2036
US Post Laser Recovery Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Post Laser Recovery Products Market Intelligence
Peptide-infused serums is restructuring cost structures across post-laser recovery portfolios as synthetic growth factors replace traditional botanical extracts. NeoGenesis leverages stem-cell signaling proteins to anchor its premium positioning in clinical channels. Elixir Cosmeceuticals differentiates through Scandinavian-origin ingredient sourcing, while OxygenCeuticals controls oxygen-delivery technology for post-ablative repair protocols.
Post laser recovery products comprise topical and transdermal formulations engineered with epidermal growth factors, ceramides, and anti-inflammatory agents to accelerate re-epithelialization and barrier restoration following ablative and non-ablative laser procedures. Creams and gels dominate current volume due to established reimbursement pathways in clinic settings, while sprays represent the fastest-expanding delivery mode as ambulatory surgical centers prioritize non-contact application for infected or highly sensitized treatment zones. Dermatology centers command the largest margin pool among end users, though homecare channels are capturing incremental value through direct-to-consumer peptide mask subscriptions.
FDA oversight of cosmetic wound-healing claims under 21 CFR requirements shapes product labeling and clinical substantiation thresholds, while state medical boards in California, New York, and Florida enforce post-procedure care protocols that mandate specific recovery timelines. OSHA guidelines for clinic-grade skincare handling further constrain formulation choices in hospital-affiliated dermatology departments. Stakeholders must monitor evolving FDA guidance on regenerative medicine products and state-level scope-of-practice expansions that could redefine who administers and dispenses post-laser recovery systems.
Market Dynamics
Biocompatible peptide formulations are redirecting procurement decisions across dermatology centers, compressing timelines for botanical-based alternatives while elevating clinical validation thresholds for new market entrants.
Growth Catalysts
- FDA 21 CFR Oversight:Post-procedure skincare guidance from the FDA is mandating standardized recovery timelines, forcing clinics to stock clinically validated topical delivery systems.
- Stem-Cell Signaling Proteins:Synthetic growth factors are replacing traditional extracts in premium recovery portfolios, restructuring cost structures across Northeast corridor dermatology networks.
- California and Texas Expansion:Dermatology centers in these states are accelerating procurement of recovery creams and gels following updated state medical board post-procedure care protocols.
Market Restraints
- Peptide Raw Material Concentration:Supply of synthetic growth factors concentrates among specialized biotech suppliers, creating vulnerability for mid-tier formulators.
- OSHA Clinic Handling Requirements:Hospital-affiliated dermatology departments face constrained formulation choices due to workplace safety guidelines for clinic-grade skincare.
- Homecare Substitution Threat:Direct-to-consumer peptide mask subscriptions are capturing incremental value, pressuring clinic-dispensed product margins.
Strategic Opportunities
- Non-Contact Delivery Innovation:Ambulatory surgical centers are prioritizing spray formats for infected or sensitized treatment zones, opening fastest-expanding delivery mode.
- Regenerative Medicine Pathway:Evolving FDA guidance on regenerative medicine products could redefine dispensing authority, creating white space for scope-of-practice expansion.
- Oxygen-Delivery Convergence:Integration of oxygen-delivery technology with post-ablative repair protocols is enabling premium positioning in clinical channels.
Industry Challenges
- Formulation Scientist Shortage:Specialized expertise in transdermal peptide stability and epidermal growth factor preservation is scarce among contract manufacturers.
- Clinical Substantiation Timelines:Barrier restoration claims require extensive re-epithelialization studies, extending product development cycles.
- Legacy System Integration:Clinic inventory management systems struggle to accommodate subscription-based homecare fulfillment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Post Laser Recovery Products Market |
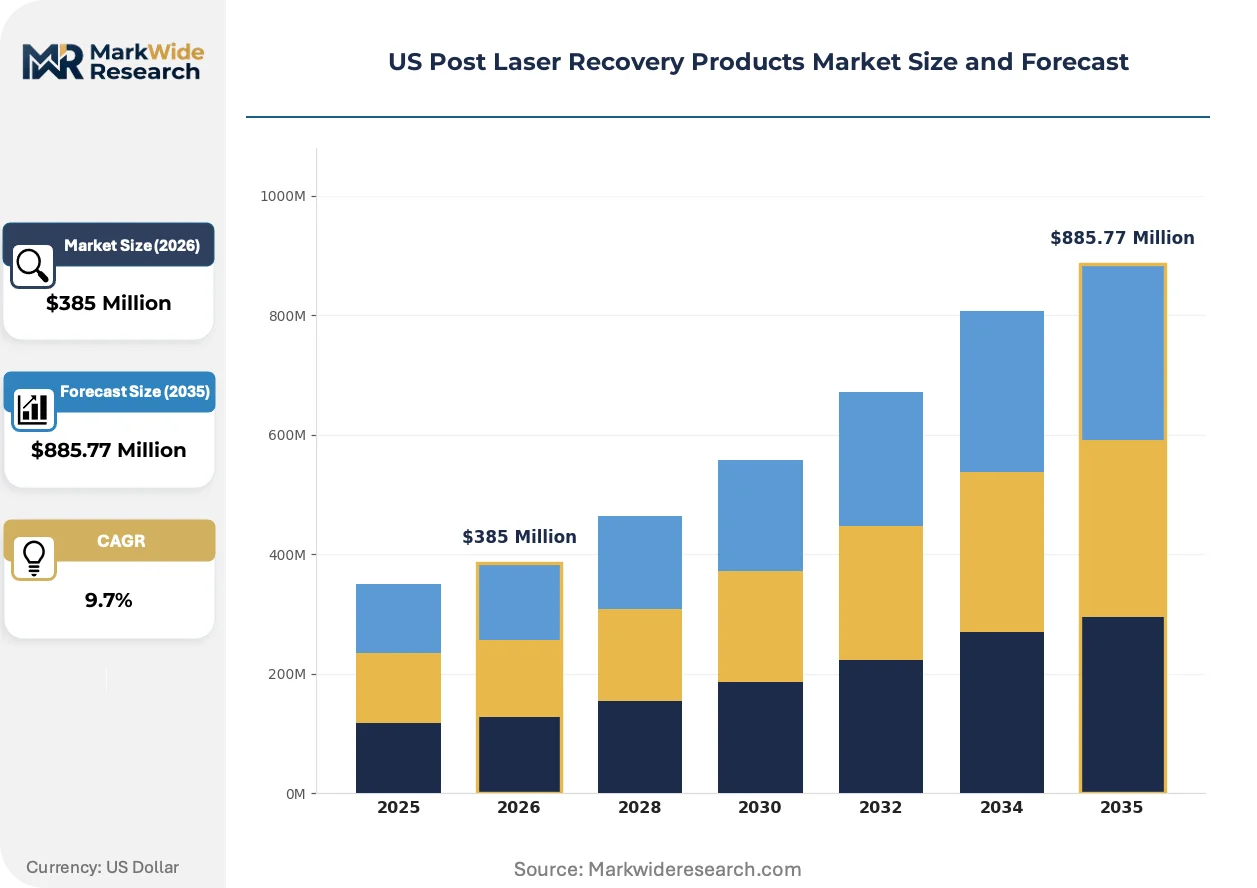
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $885.77 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Masks, Sprays Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Clinics, Hospitals, Homecare, Dermatology Centers Packaging Type: Tubes, Bottles, Jars, Sachets |
| Companies Covered | Synergie Skin, Bynacht, NeoGenesis, Elixir Cosmeceuticals, Koru Pharma, CALECIM Clinic, RAI Aesthetics, OxygenCeuticals, LA CLINICA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Post Laser Recovery Products Market Strategic Shifts & Innovations
Active ingredient delivery mechanisms are undergoing fundamental redesign as synthetic biology converges with transdermal penetration science, compressing development cycles for next-generation recovery formulations.
Peptide-infused serums are integrating nanostructured lipid carriers to enhance epidermal penetration of growth factors. Dermatology centers in the Northeast corridor are adopting these systems at accelerated pace for post-ablative protocols. This convergence is integrating premium and standard product tiers, eroding traditional price stratification based on botanical versus synthetic origin claims.
FDA oversight of cosmetic wound-healing claims under 21 CFR requirements is tightening labeling substantiation thresholds. Product developers must now complete clinical studies demonstrating measurable re-epithelialization acceleration. Post-laser recovery creams and gels face the most stringent scrutiny, with California and New York state medical boards enforcing additional post-procedure care documentation.
Homecare channel expansion is disrupting traditional clinic-centric dispensing models. Direct-to-consumer peptide mask subscriptions are capturing patients who previously relied exclusively on in-office product procurement. This behavioral shift concentrates in urban coastal markets where telemedicine follow-up protocols have normalized remote post-procedure monitoring.
US Post Laser Recovery Products Market Segmentation
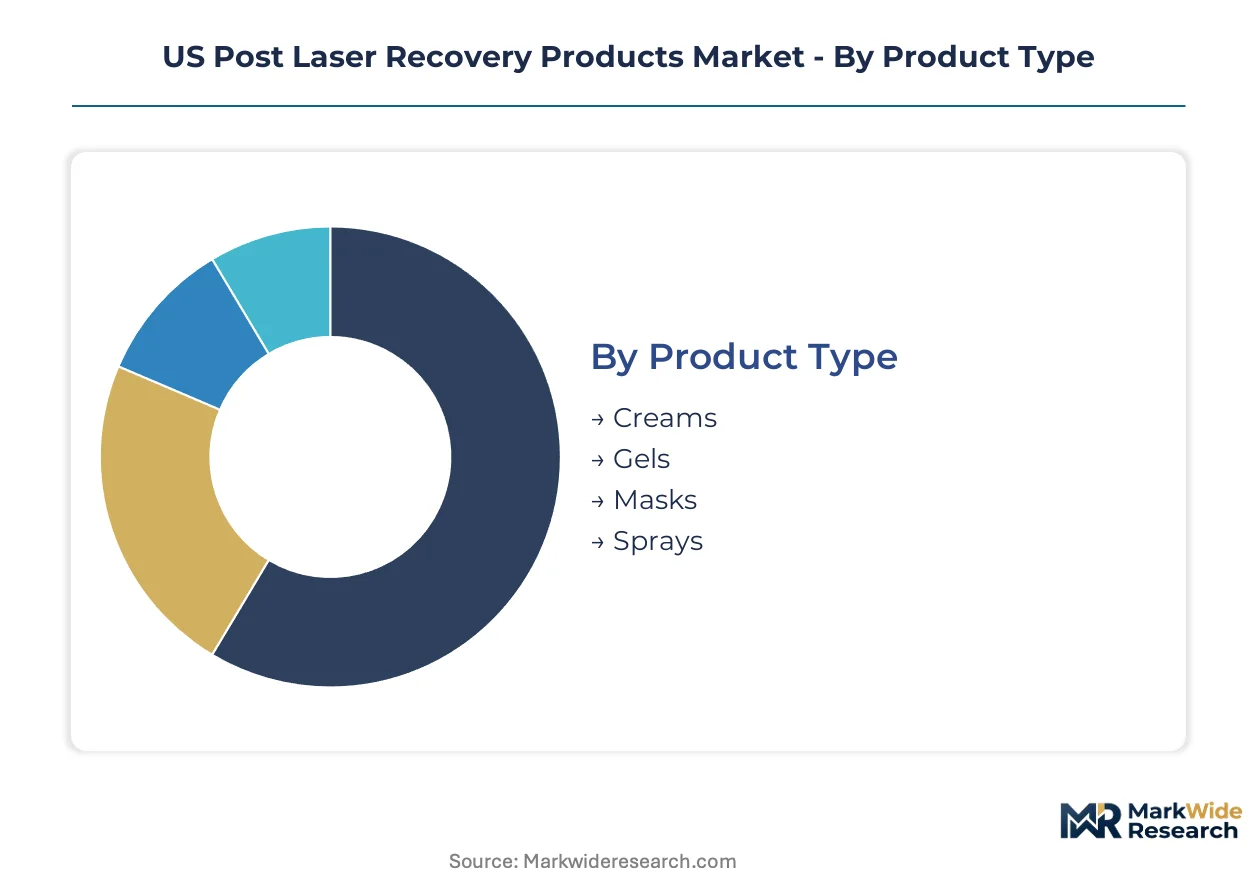
Recovery product portfolios fragment across formulation physics, administration protocols, and care settings. Each segmentation dimension carries distinct margin profiles, regulatory pathways, and procurement decision-makers.
Product Type:
Formulation viscosity and occlusion properties determine reimbursement eligibility and patient compliance rates.
- Creams:Occlusive emulsions with ceramide-rich matrices dominate clinic dispensing due to established insurance coding for post-ablative protocols. California dermatology networks account for disproportionate procurement volumes following state medical board documentation requirements.
- Gels:Hydrogel vehicles with rapid evaporative cooling suit non-ablative laser sequences. Texas ambulatory centers favor gel formats for same-day discharge protocols where minimal residue accelerates patient throughput.
- Masks:Occlusive sheet systems concentrate peptide delivery for homecare continuation.
- Sprays:Aerosolized non-contact application targets infected or highly sensitized treatment zones.
Creams lead volumes today; sprays are gaining share fastest.
Delivery Mode:
Biological penetration depth and FDA classification status separate prescription-required from over-the-counter channels.
- Topical:Surface-acting formulations with epidermal growth factor stabilization. Northeast corridor dermatology centers prioritize topical systems for their alignment with OSHA clinic handling guidelines and reduced staff training burdens.
- Transdermal:Nanostructured lipid carriers enable growth factor penetration into dermal repair zones. Florida medical spas drive adoption for combination therapy protocols involving fractional resurfacing.
- Oral:Systemic collagen synthesis support via amino acid complexes.
- Injectable:Subcutaneous platelet-derived preparations for deep tissue remodeling.
Topical systems dominate dispensing today; transdermal formats show steepest expansion trajectory.
End User:
Procurement authority and patient volume determine contract structure and SKU complexity.
- Dermatology Centers:High-margin dispensing with protocol-driven formulary control. California and New York state medical board documentation mandates concentrate procurement authority here.
- Homecare:Direct-to-consumer subscriptions bypass clinic margins. Urban coastal markets normalize telemedicine follow-up protocols that enable remote product fulfillment.
- Clinics:General aesthetic practices with standardized recovery kits.
- Hospitals:Hospital-affiliated departments face constrained choices under OSHA workplace safety guidelines.
Dermatology centers capture the largest margin pool; homecare channels expand most quickly.
Packaging Type:
Dispensing precision and contamination risk shape unit economics and regulatory classification.
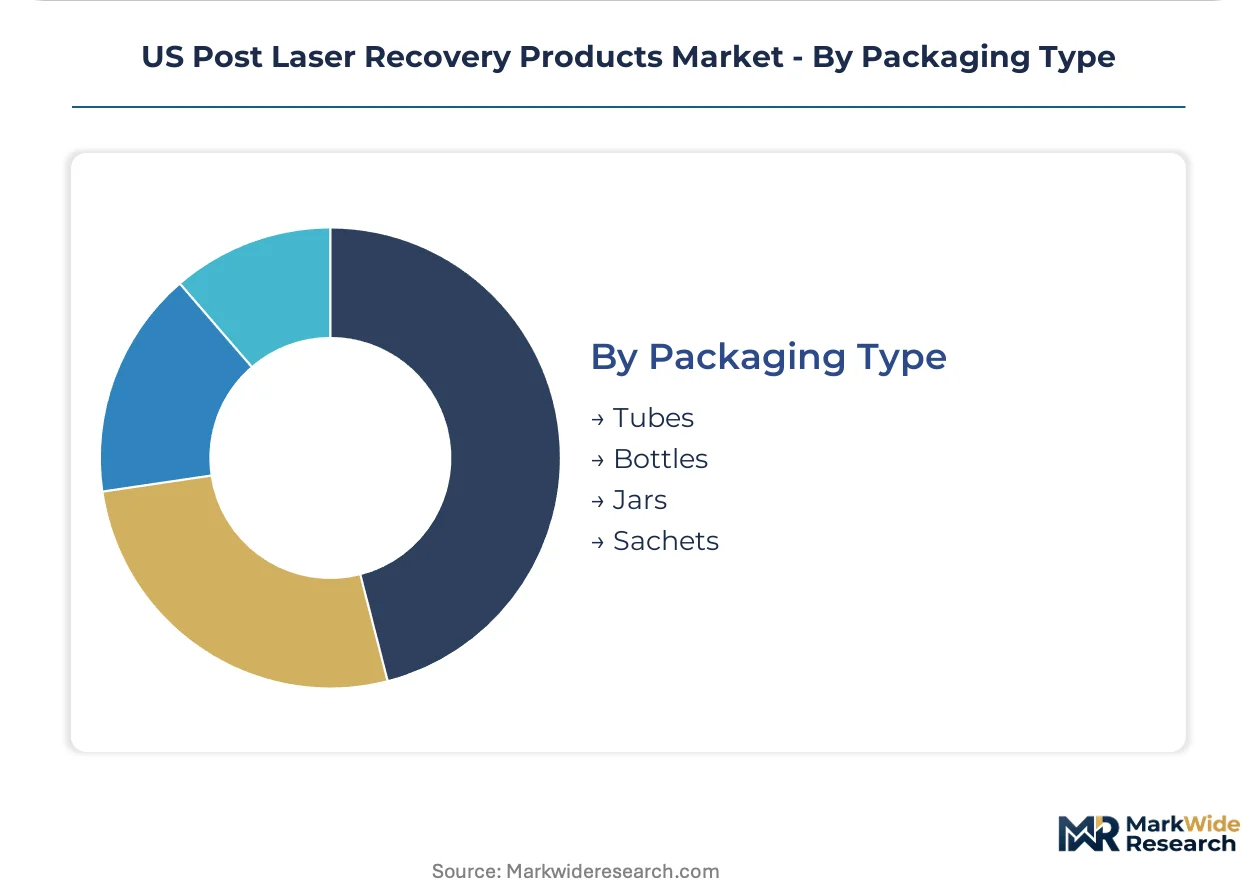
- Tubes:Collapsible aluminum or laminate structures with airless pump compatibility. Texas and Florida clinic networks prefer tubes for their portability and reduced cross-contamination risk in high-throughput settings.
- Sachets:Single-unit dose packaging eliminates multi-use contamination. California dermatology centers adopt sachets for trial-size dispensing and travel-kit bundling.
- Bottles:Glass or PET containers for serum formulations.
- Jars:Wide-mouth containers for mask and balm textures.
Tubes dominate institutional procurement; sachets are climbing the fastest in subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California dermatology networks anchor procurement volumes for post-laser recovery products, driven by state medical board documentation mandates and elevated aesthetic procedure density. Texas and New York corridor markets follow with distinct procurement patterns shaped by ambulatory center throughput requirements and Northeast corridor clinical validation standards.
California
Los Angeles and San Francisco Bay Area dermatology centers drive disproportionate cream and gel procurement following California Medical Board post-procedure care documentation requirements. FDA 21 CFR oversight of cosmetic wound-healing claims tightens labeling substantiation thresholds for products dispensed through these channels. Peptide-infused serum adoption concentrates in Beverly Hills and Palo Alto clinical networks where stem-cell signaling protein formulations command premium positioning.
Texas
Dallas and Houston ambulatory surgical centers prioritize gel formats for same-day discharge protocols where rapid evaporative cooling accelerates patient throughput. Texas Medical Board enforcement of post-procedure care timelines mandates specific recovery product stocking. Austin and San Antonio clinic networks are expanding spray format trials for infected treatment zones, aligning with OSHA workplace safety guidelines for non-contact application.
New York
Manhattan and Long Island dermatology centers enforce the Northeast corridor's most stringent clinical validation thresholds for barrier restoration claims. New York State Department of Health regulations on medical spa operations constrain dispensing authority to licensed practitioners. Westchester and Hudson Valley clinic networks are integrating nanostructured lipid carrier systems for transdermal growth factor delivery in fractional resurfacing protocols.
Florida
Miami and Palm Beach medical spas drive transdermal format adoption for combination therapy protocols involving ablative laser sequences. Florida Board of Medicine scope-of-practice expansions enable advanced practice providers to dispense recovery products in supervised settings. Tampa and Orlando clinic networks are capturing incremental homecare value through telemedicine-enabled remote product fulfillment.
Massachusetts
Boston-Cambridge dermatology departments affiliated with academic medical centers face constrained formulation choices under joint commission workplace safety requirements. Massachusetts Board of Registration in Medicine enforces post-procedure care documentation that elevates procurement standards. Worcester and Springfield clinical networks are piloting oxygen-delivery technology integration for post-ablative repair protocols.
US Post Laser Recovery Products Market Key Industry Players
Global majors compete with regional champions across clinical validation and ingredient sourcing dimensions, creating a tiered structure where premium positioning depends on biotech-derived active credentials. Market concentration remains moderate, with specialized formulators capturing margin pools that mass-market skincare manufacturers cannot access. Three archetypes dominate: stem-cell signaling protein specialists, Scandinavian-origin ingredient purveyors, and oxygen-delivery technology controllers. Capacity expansion in peptide raw material synthesis and strategic partnerships with ambulatory surgical center networks represent the dominant competitive moves reshaping procurement relationships.
Within the biotechnology-anchored tier, NeoGenesis and CALECIM Clinic occupy positions defined by regenerative medicine positioning, while OxygenCeuticals exemplifies the technology-licensing archetype through controlled oxygen-delivery systems. Elixir Cosmeceuticals represents the geographic-origin differentiation model with Scandinavian sourcing credentials. These three companies anchor distinct competitive vectors that mid-tier formulators struggle to replicate given raw material concentration among specialized suppliers.
| Leading Market Players |
|---|
| Synergie Skin |
| Bynacht |
| NeoGenesis |
| Elixir Cosmeceuticals |
| Koru Pharma |
| CALECIM Clinic |
| RAI Aesthetics |
| OxygenCeuticals |
| LA CLINICA |
| Others |
Cost & Logistics Intelligence
California Medical Board post-procedure documentation mandates are compressing procurement timelines for clinically validated topical delivery systems, forcing peptide raw material suppliers to expand fermentation capacity and elevating input costs across mid-tier formulator portfolios. This demand-side specification tightening propagates through contract manufacturing networks, restructuring margin distribution between biotech-anchored premium suppliers and botanical-based legacy alternatives.
Pricing Analysis
Synthetic growth factor input costs pass through directly to finished product pricing, with peptide-infused serums commanding premium positioning over traditional botanical extracts. Three-tier pricing structure across premium, standard, and economy levels separates stem-cell signaling protein formulations from ceramide-rich matrices and basic hydrogel vehicles. Pricing pressure stems from direct-to-consumer peptide mask subscriptions eroding clinic-dispensed margins. Dermatology centers show lowest price sensitivity due to protocol-driven formulary control, while general aesthetic clinics face acute cost compression.
Supply Chain Analysis
Peptide raw material supply rests on specialized biotech producers concentrated in Massachusetts and California, with Scandinavian-origin ingredient sourcing adding geographic diversification for premium positioning. Key inputs include synthetic epidermal growth factors, nanostructured lipid carriers, and ceramide matrices. Single-source vulnerability concentrates around stem-cell signaling protein fermentation capacity. Distribution runs through dermatology center procurement committees, ambulatory surgical center formularies, and direct-to-consumer subscription fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US post-laser recovery products market represents a late-cycle quality story as FDA 21 CFR oversight and state medical board documentation mandates elevate clinical validation thresholds, redirecting procurement toward biocompatible peptide formulations with substantiated barrier restoration claims.
For Market Incumbents: Deepen captive supply relationships with specialized peptide fermentation facilities to secure raw material allocation priority against mid-tier formulator competition. Expand nanostructured lipid carrier manufacturing capacity in the Northeast corridor to capture transdermal format growth. Invest in clinical substantiation infrastructure to defend premium positioning as FDA labeling requirements tighten. For New Entrants and Emerging Players: FDA 21 CFR oversight of cosmetic wound-healing claims opens a window for clinically validated topical delivery systems that can demonstrate measurable re-epithelialization acceleration. Target ambulatory surgical center spray format procurement in Texas and Florida where same-day discharge protocols prioritize non-contact application. Pursue telemedicine-enabled direct-to-consumer fulfillment partnerships to bypass traditional clinic-centric dispensing barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators possessing in-house peptide stability expertise and established clinical channel relationships. Five-to-ten year viability favors companies with backward integration into synthetic growth factor production and diversified geographic sourcing credentials. Monitor evolving FDA guidance on regenerative medicine products as the primary inflection indicator for scope-of-practice expansion and dispensing authority redefinition.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Raw Material Backward Integration | In-house synthetic growth factor production secures allocation priority against supply-constrained mid-tier competitors. |
| Clinical Substantiation Infrastructure Investment | FDA 21 CFR compliance capabilities differentiate premium positioning as labeling scrutiny intensifies. |
| Transdermal Delivery Technology Licensing | Nanostructured lipid carrier partnerships enable penetration into Florida medical spa combination therapy protocols. |
| Direct-to-Consumer Subscription Platform Launch | Telemedicine-enabled fulfillment captures patient migration from clinic-dispensed to homecare channels. |
| Ambulatory Surgical Center Spray Format Development | Non-contact application aligns with OSHA guidelines and Texas same-day discharge throughput requirements. |
Research Approach
Coverage spans California, Texas, New York, Florida, and Massachusetts, with primary inputs from each state cluster combined with secondary validation. Interviews with dermatology center procurement directors, ambulatory surgical center formulary managers, contract manufacturing executives, and state medical board regulatory affairs specialists inform demand-side dynamics. Secondary sources include FDA 21 CFR guidance documents, state medical board post-procedure care protocols, OSHA workplace safety guidelines, and hospital-affiliated dermatology department procurement databases. Bottom-up volume modeling triangulates against top-down market sizing across product type, delivery mode, and end user segments.
Granularity-level modeling disaggregates the analysis window by formulation physics, administration protocol, and care setting, with additional dimensioning by state regulatory cluster and clinical channel type. CAGRs derive from segment-level volume trajectory analysis incorporating peptide raw material supply constraints and homecare channel substitution elasticities. Forecast inputs include FDA regenerative medicine guidance evolution timelines, state scope-of-practice expansion probabilities, and ambulatory surgical center throughput optimization trends.
Revisions become necessary when FDA guidance on regenerative medicine products materializes in unanticipated directions, when peptide raw material supply disruptions alter input cost trajectories, or when state medical board documentation mandates expand beyond current California and New York precedents. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Sophorolipids Market