
 Decabromodiphenyl Ether Market | 2026-2036
Decabromodiphenyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Decabromodiphenyl Ether Market Analysis
Phosphorus-nitrogen synergist formulations is tilting the flame retardant technology stack away from legacy halogenated architectures without sacrificing polypropylene ignition resistance. Albemarle Corporation leverages its bromine captive supply from Arkansas brine operations to sustain cost positions in North American automotive compounding. ICL Group anchors its competitiveness through integrated Dead Sea bromine extraction and downstream derivative production across European and Asian formulation facilities.
Decabromodiphenyl ether constitutes a brominated diphenyl ether with ten bromine substituents, typically supplied as a white crystalline powder with melting points near 300°C and serving primarily as an additive flame retardant in high-impact polystyrene and polyolefin matrices. The plastics application segment dominates volume flows, particularly in electronics housings and appliance components where UL-94 V-0 ratings remain mandatory. Powder form commands premium positioning over granules in automated dosing systems for extrusion compounding, while emulsion grades are gaining traction in textile back-coating operations across South Asian manufacturing clusters.
EPA evaluation protocols under the Toxic Substances Control Act and ECHA substance-of-very-high-concern listings under REACH constrain unrestricted decaBDE placement in consumer goods and construction materials across North America and Europe. China's MEE enforcement of GB standards for persistent organic pollutants shapes import thresholds and domestic production quotas for brominated flame retardant manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions that either restrict or grandfather existing decaBDE applications, as this fragmentation determines where formulation investments migrate and which chemistries capture displaced volume.
Market Dynamics
REACH substance-of-very-high-concern listings and EPA TSCA evaluation protocols are forcing simultaneous phase-down and grandfathered-use coexistence, splitting formulation investments between legacy decaBDE retention and phosphorus-nitrogen alternative migration.
Growth Catalysts
- Automotive compounding demand:Electric vehicle battery enclosures and high-voltage connector housings require UL-94 V-0 rated materials, sustaining decaBDE consumption in crash-resistant polypropylene formulations.
- China GB standards enforcement:Domestic electronics manufacturing quotas under MEE persistent organic pollutant protocols preserve captive brominated flame retardant capacity for export-oriented appliance production.
- Textile back-coating expansion:South Asian manufacturing clusters are adopting emulsion-grade decaBDE for synthetic fabric fire resistance in contract furnishing and transportation seating.
Market Restraints
- Bromine feedstock concentration:Dead Sea and Arkansas brine operations control 70% of elemental bromine supply, creating input cost volatility when extraction disruptions occur.
- Phosphorus-nitrogen substitution:Intumescent formulations in polyolefins achieve comparable ignition resistance without halogen content, capturing specification share in European consumer goods.
- ECHA authorization requirements:REACH Annex XIV sunset dates force downstream users to submit continued-use justifications or reformulate, extending compliance timelines and freezing spot purchasing.
Strategic Opportunities
- India construction chemicals:BIS fire safety mandates for high-rise building insulation create first-mover positioning for decaBDE suppliers establishing local compounding partnerships.
- Recycling stream integration:Flame retardant recovery from e-waste plastics enables circular material loops, with decaBDE stability supporting multiple reprocessing cycles versus degradable alternatives.
- Marine and rail interiors:Updated IMO and EN 45545 fire safety standards expand addressable volume in mass transit seating and vessel compartment paneling beyond traditional electronics.
Industry Challenges
- Regulatory divergence management:Formulators must maintain parallel product lines for jurisdictions with conflicting decaBDE status, multiplying SKU complexity and inventory carrying costs.
- Analytical testing capacity:Persistent organic pollutant detection at ppb levels requires GC-MS instrumentation and trained technicians that remain scarce in secondary manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decabromodiphenyl Ether Market |
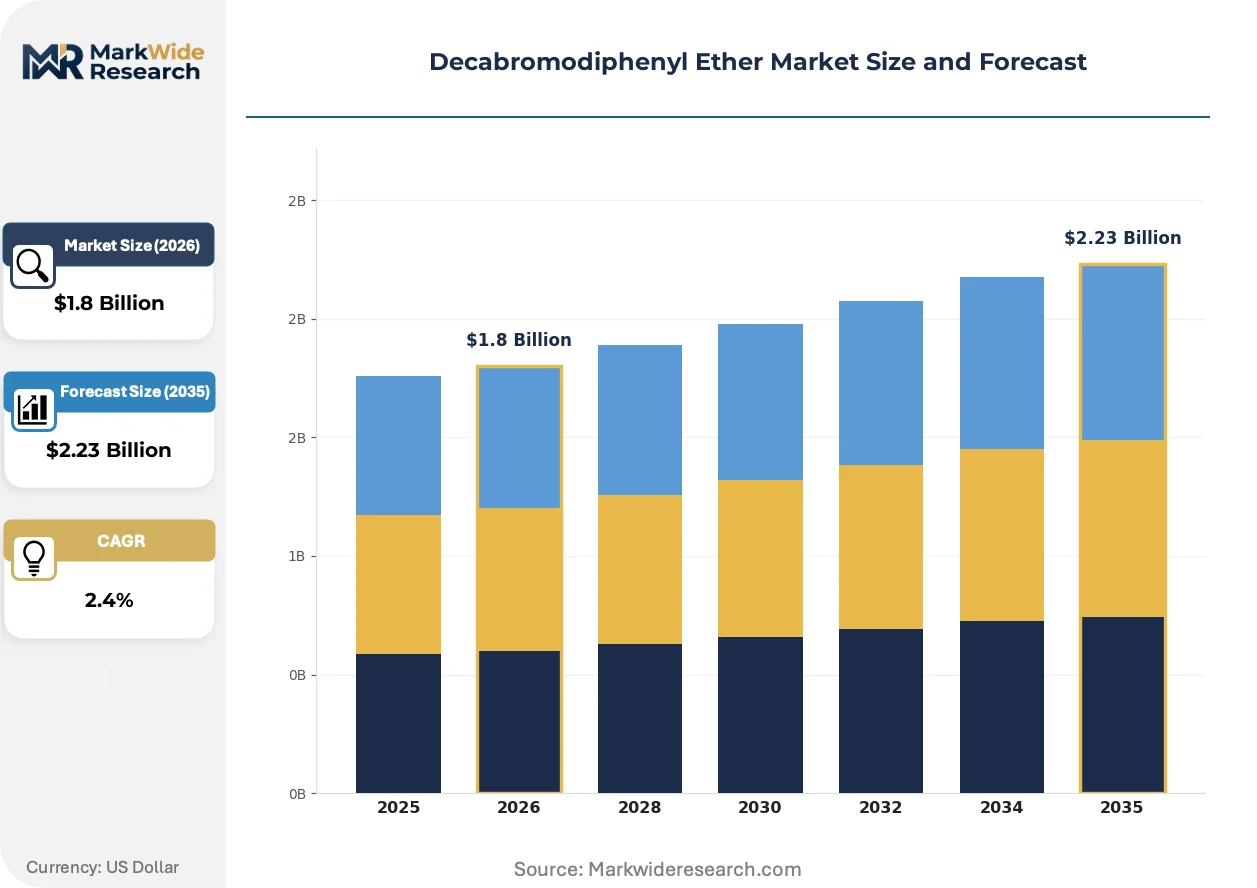
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Textiles, Electronics, Coatings End Use Industry: Automotive, Construction, Consumer Goods, Aerospace Form: Granules, Powder, Liquid, Emulsion Application: Flame Retardants, Cable Insulation, Foam Production, Surface Treatment |
| Companies Covered | Albemarle Corporation, ICL Group, LANXESS, Qingdao Shida Chemical Co., Ltd., Shandong Novista Chemicals Co., Ltd., Tosoh Corporation, BASF SE, Shandong Moris Tech Co., Ltd., Unibrom Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decabromodiphenyl Ether Market Emerging Trajectories
Formulation chemistry is diverging along regulatory fault lines, with halogenated and halogen-free architectures competing for specification dominance across automotive, electronics, and construction end-uses.
Reactive brominated epoxy oligomers are migrating from additive decaBDE systems in printed circuit board laminates. Taiwan and South Korean substrate manufacturers are accelerating qualification timelines for covalently bound flame retardants that resist leaching during end-of-life processing. This migration is compressing spot demand for conventional decaBDE in high-layer-count server board applications.
ECHA's 2023 updated restriction proposal on polybrominated diphenyl ethers tightens concentration thresholds in articles and mixtures. Downstream electronics assemblers in Germany and Poland are redesigning housing geometries to reduce flame retardant loading while maintaining thermal runaway containment. Small appliance categories face the steepest compliance cost escalation as reformulation cycles compress from 36 to 18 months.
Automotive OEMs are consolidating qualified material suppliers to reduce homologation burden. Tier-1 compounders in Michigan and Bavaria now specify multi-year volume commitments in exchange for dedicated production slots, displacing spot purchasing for commodity flame retardant grades. This concentration is most visible in North American electric vehicle platform rollouts where battery pack fire safety certification gates dominate material selection timelines.
Decabromodiphenyl Ether Market Segmentation
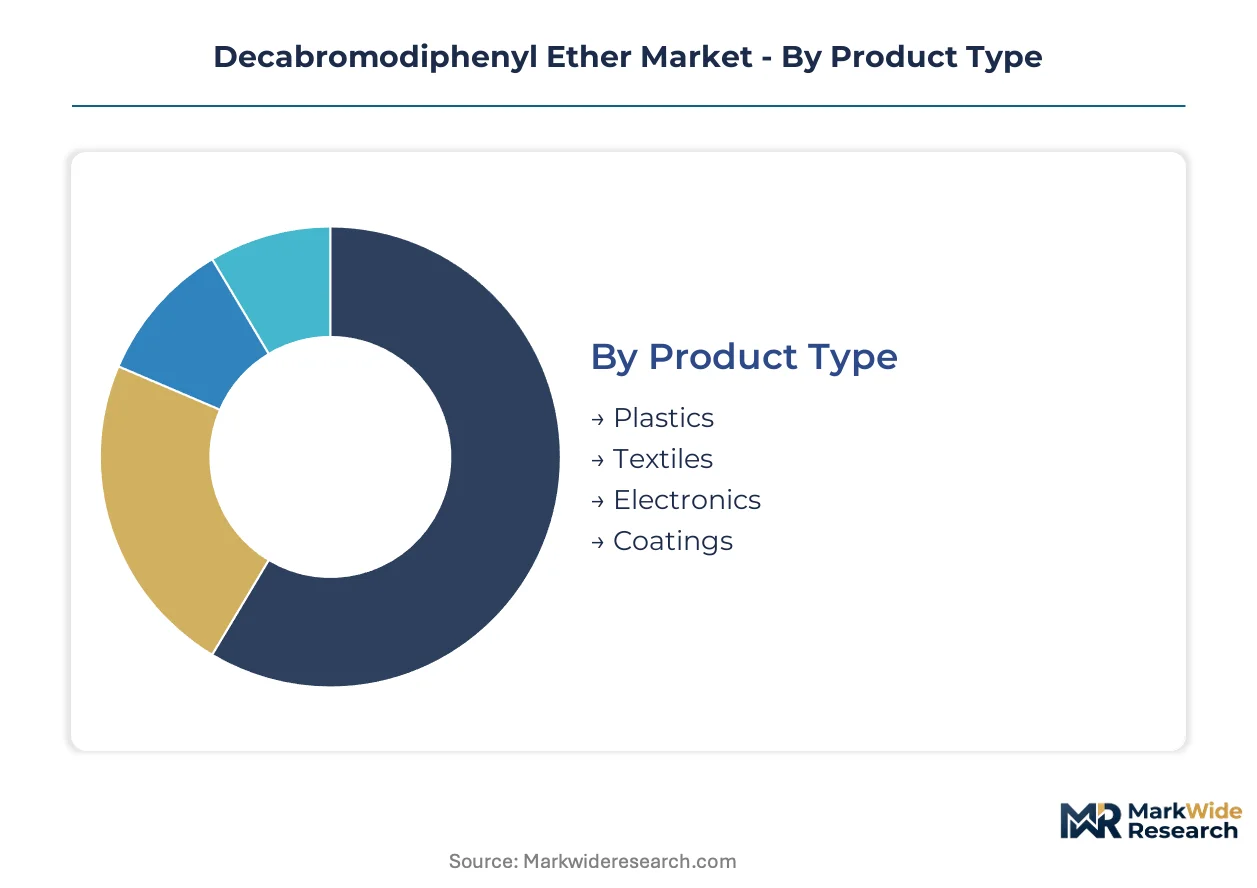
Decabromodiphenyl ether demand fragments across material matrices, processing forms, and regulatory jurisdictions. Each segment carries distinct formulation requirements and compliance burdens that shape supplier positioning and margin structures.
Product Type:
Mature industrial applications anchor volume flows while emerging electronics specifications drive specification upgrades.
- Plastics:High-impact polystyrene and polypropylene compounding consumes the bulk of decaBDE output, particularly in appliance housings and automotive interior panels where UL-94 V-0 ratings remain non-negotiable. Chinese electronics manufacturing clusters sustain captive demand for decaBDE-laden ABS formulations in export-oriented consumer goods.
- Electronics:Printed circuit board laminates and connector housings require thermal stability above 280°C, pushing specification toward higher-purity grades. Taiwan substrate manufacturers are accelerating migration to reactive brominated epoxy oligomers that resist leaching during end-of-life processing.
- Textiles:Synthetic fabric back-coating operations in South Asian manufacturing clusters adopt emulsion-grade decaBDE for contract furnishing and transportation seating fire resistance.
- Coatings:Intumescent architectural formulations leverage decaBDE as a synergist with phosphorus-nitrogen systems in high-rise building insulation applications.
Plastics retains volume leadership; electronics holds the steepest expansion curve.
End Use Industry:
Customer procurement patterns diverge between long-term automotive contracts and spot purchasing in construction chemicals.
- Automotive:Electric vehicle battery enclosures and high-voltage connector housings require crash-resistant polypropylene formulations with UL-94 V-0 ratings. Tier-1 compounders in Michigan and Bavaria now specify multi-year volume commitments in exchange for dedicated production slots.
- Construction:BIS fire safety mandates for high-rise building insulation in India create first-mover positioning for suppliers establishing local compounding partnerships. ECHA REACH Annex XIV sunset dates force European construction material producers to submit continued-use justifications or reformulate entirely.
- Consumer Goods:Small appliance categories face compressed reformulation cycles from 36 to 18 months as housing geometries are redesigned to reduce flame retardant loading while maintaining thermal runaway containment.
- Aerospace:Cabin interior paneling and seating applications require compliance with updated fire safety standards, though volume remains constrained by qualification timelines and material substitution toward covalently bound alternatives.
Automotive commands the densest contract coverage; construction carries the highest regulatory uncertainty.
Form:
Processing economics favor powder and granule formats, though emulsion grades are capturing textile and coating share.
- Powder:Automated dosing systems for extrusion compounding prefer micronized crystalline grades with consistent particle size distribution. Premium positioning reflects handling efficiency and reduced dust exposure in continuous production environments.
- Granules:Masterbatch formats simplify downstream incorporation in polyolefin matrices, particularly favored by mid-sized compounders lacking precision feeding equipment. Dust containment advantages support workplace exposure compliance.
- Liquid:Solvent-based formulations serve niche coating applications where dispersion uniformity exceeds cost sensitivity.
- Emulsion:Water-based systems gain traction in textile back-coating operations across Bangladesh and Vietnam manufacturing clusters, replacing solvent-borne alternatives under MEE volatile organic compound enforcement.
Powder maintains specification dominance; emulsion is climbing the fastest on textile demand.
Application:
Functional performance requirements separate commodity flame retardant specifications from specialized cable and foam applications.
- Flame Retardants:Additive incorporation into thermoplastic matrices constitutes the core application, with loading levels calibrated to achieve specific ignition resistance ratings without degrading mechanical properties.
- Cable Insulation:Low-smoke zero-halogen formulations in European markets are displacing decaBDE in building wire applications, though marine and rail cable specifications retain brominated systems for stringent fire safety performance.
- Foam Production:Expanded polystyrene insulation boards for construction applications utilize decaBDE as a processing stabilizer alongside flame retardant function, particularly in markets where GB standards enforcement remains uneven.
- Surface Treatment:Back-coating and impregnation processes for technical textiles require emulsion-compatible grades with controlled viscosity profiles for uniform substrate penetration.
Flame retardants anchor volume; surface treatment is gaining share fastest on textile diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and electronics contract manufacturers concentrate procurement power across four distinct regulatory zones, each imposing divergent compliance burdens on decaBDE formulation strategies.
United States
Electric vehicle battery enclosure production in Michigan and Ohio sustains polypropylene compounding demand with UL-94 V-0 specifications. EPA TSCA evaluation protocols under Section 6 require ongoing risk assessments for persistent organic pollutants. Albemarle Corporation leverages captive bromine supply from Arkansas brine operations to serve Tier-1 compounders in the Detroit metropolitan corridor.
Germany
Automotive interior panel specifications from BMW and Volkswagen anchor European consumption of high-purity decaBDE grades. ECHA REACH Annex XIV sunset dates force compounders in Bavaria and North Rhine-Westphalia to submit continued-use authorizations or accelerate reformulation timelines. Tier-1 suppliers around Munich now demand multi-year volume commitments to justify dedicated production slots.
China
Domestic electronics manufacturing quotas under MEE enforcement of GB standards for persistent organic pollutants preserve captive brominated flame retardant capacity. The Yangtze River Delta and Pearl River Delta manufacturing clusters sustain bulk consumption in export-oriented appliance housings and high-impact polystyrene formulations for consumer goods production.
India
BIS fire safety mandates for high-rise building insulation in Mumbai and Delhi-NCR create first-mover positioning for suppliers establishing local compounding partnerships. Construction chemical distributors in Maharashtra and Gujarat are qualifying decaBDE-synergist formulations for expanded polystyrene board applications ahead of anticipated enforcement expansion.
Japan
Printed circuit board laminate manufacturers in the Kanto region accelerate qualification of reactive brominated epoxy oligomers as alternatives to additive decaBDE systems. METI chemical management guidelines influence substrate producer decisions on covalently bound flame retardants for high-layer-count server board applications in Tokyo-Osaka industrial corridors.
Decabromodiphenyl Ether Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. The vendor base separates into integrated bromine producers with captive elemental supply, mid-scale derivative manufacturers with regional formulation expertise, and specialty distributors with technical service capabilities. Consolidation pressures favor backward integration into bromine extraction and downstream compounding partnerships. Capacity rationalization and geographic licensing agreements constitute the dominant competitive moves as regulatory divergence multiplies SKU complexity.
Within the integrated producer tier, Albemarle Corporation and ICL Group exemplify upstream control strategies through Arkansas brine and Dead Sea extraction operations respectively. LANXESS occupies a position bridging commodity chemical scale with flame retardant application engineering. Among Asia-Pacific derivative specialists, Tosoh Corporation and Shandong Novista Chemicals Co., Ltd. represent regional formulation capabilities serving electronics and automotive end-uses with proximity to manufacturing clusters.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group |
| LANXESS |
| Qingdao Shida Chemical Co., Ltd. |
| Shandong Novista Chemicals Co., Ltd. |
| Tosoh Corporation |
| BASF SE |
| Shandong Moris Tech Co., Ltd. |
| Unibrom Corporation |
| Others |
Supply Flow & Price Mechanics
REACH Annex XIV sunset date exposure concentrates pricing power among authorized suppliers while fragmenting procurement strategies across grandfathered-use and reformulation camps. This regulatory chokepoint widens tier spreads between ECHA-authorized premium grades and spot-traded standard material while reshaping inventory positioning toward jurisdictions with divergent decaBDE status.
Pricing Analysis
Cost-plus contracts with bromine feedstock indexation dominate long-term supply agreements between Arkansas and Dead Sea producers and Tier-1 automotive compounders. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade purity specifications from industrial compounding grades and spot-traded commodity lots. Cost compression in standard grades is intensifying because phosphorus-nitrogen alternatives achieve comparable UL-94 ratings in polypropylene at lower loadings. Small appliance manufacturers exhibit the highest price sensitivity due to compressed reformulation cycles, while electric vehicle battery enclosure producers accept premium positioning for multi-year supply security.
Supply Chain Analysis
Elemental bromine extraction concentrates in Israel and the United States, with downstream derivative production anchored in China, Germany, and India. DecaBDE manufacturing draws from captive brine operations, aromatic intermediate streams, and specialized bromination reactor capacity. Single-source vulnerability runs through Dead Sea extraction disruptions, which propagate rapidly into global flame retardant derivative availability. Distribution runs through qualified distributor networks with technical service capabilities, particularly for REACH-authorized material movement across European compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against phosphorus-nitrogen intumescent systems that capture specification share in European consumer goods and automotive interiors. Incumbents must navigate reformulation timelines that compress from thirty-six to eighteen months in small appliance categories.
For Market Incumbents: Build regulatory authorization moats through ECHA continued-use submission capabilities and captive bromine supply integration. Secure multi-year volume commitments from electric vehicle platform engineers in exchange for dedicated production slots. Defend against LANXESS and ICL Group expansion by anchoring formulation partnerships with Michigan and Bavaria Tier-1 compounders before REACH sunset dates freeze spot purchasing.
For New Entrants and Emerging Players: India's construction chemical underpenetration offers first-mover positioning ahead of BIS fire safety mandate expansion into high-rise insulation. Target Maharashtra and Gujarat expanded polystyrene board applications through local compounding joint ventures. Penetrate South Asian textile back-coating clusters in Bangladesh and Vietnam with emulsion-grade technical service capabilities that incumbent distributors lack.
For Investors and Strategic Acquirers: REACH Annex XIV authorization reshapes the acquisition landscape toward ECHA-authorized asset scarcity and stranded capacity risk in non-compliant facilities. Five-to-ten year viability hinges on grandfathered-use volume retention versus phosphorus-nitrogen displacement velocity. Acquire integrated bromine-to-derivative producers with Dead Sea or Arkansas feedstock control. Watch ECHA restriction proposal tightening thresholds as the signal for accelerated reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Captive Dead Sea or Arkansas brine supply insulates margin compression from feedstock volatility. |
| REACH Authorization Investment | ECHA continued-use submission capability preserves European automotive and electronics specification access. |
| Local Compounding Partnership | Maharashtra and Gujarat facility presence captures India BIS mandate enforcement in construction chemicals. |
| Emulsion Grade Technical Service | Bangladesh and Vietnam textile back-coating support displaces solvent-borne alternatives under MEE VOC rules. |
| Multi-Year Volume Commitment Structure | Detroit and Munich Tier-1 automotive contracts reduce spot exposure and homologation burden concentration. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flame retardant procurement managers at automotive Tier-1 compounders, technical directors at electronics substrate manufacturers, plant managers at bromine extraction facilities, and construction chemical distributors in India. Secondary validation drew from ECHA restriction proposal documentation, EPA TSCA Section 6 risk evaluation dockets, MEE GB standard enforcement circulars, SEC 10-K filings from Albemarle Corporation and ICL Group, and customs trade data for brominated derivative flows. Bottom-up segment sizing triangulated against top-down bromine consumption attribution across end-use industries.
Calibration against historical REACH authorization timelines and phosphorus-nitrogen substitution elasticities shaped projection mechanics across the analysis window. Segmentation dimensions modeled include grade purity tier, plastics versus electronics versus textile end-use, powder versus emulsion form factor, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume forecasts incorporating electric vehicle platform rollout schedules and India construction chemical enforcement phasing. Industry-specific inputs captured MEE persistent organic pollutant quota allocations and ECHA sunset date compliance cost modeling.
The forecast holds incumbent behavior within observed patterns; aggressive capacity rationalization by integrated producers or accelerated phosphorus-nitrogen substitution by German automotive OEMs would shift outcomes beyond modeled ranges. Cross-checking against bromine derivative trade flow data from Israel and Jordan customs authorities is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Cummene Derivatives Market
Chemicals
Aromatic Polyamine Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Guaiazulene Market
Chemicals
Isopropanolamine Market
Chemicals
Pyrimidine Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Trimethylamine Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Methylamines Market
Chemicals
United States Construction Chemicals Market