
 Marula Oil Market | 2026-2036
Marula Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Marula Oil Market Outlook
Multi-source sourcing from Southern African cooperatives is broadening as brands seek supply resilience. African Botanics leverages direct community partnerships to secure premium unrefined grades. Phytoafrica GmbH anchors its European distribution through certified cold-pressed supply chains. DLG Naturals competes on volume scale across refined oil segments for industrial buyers.
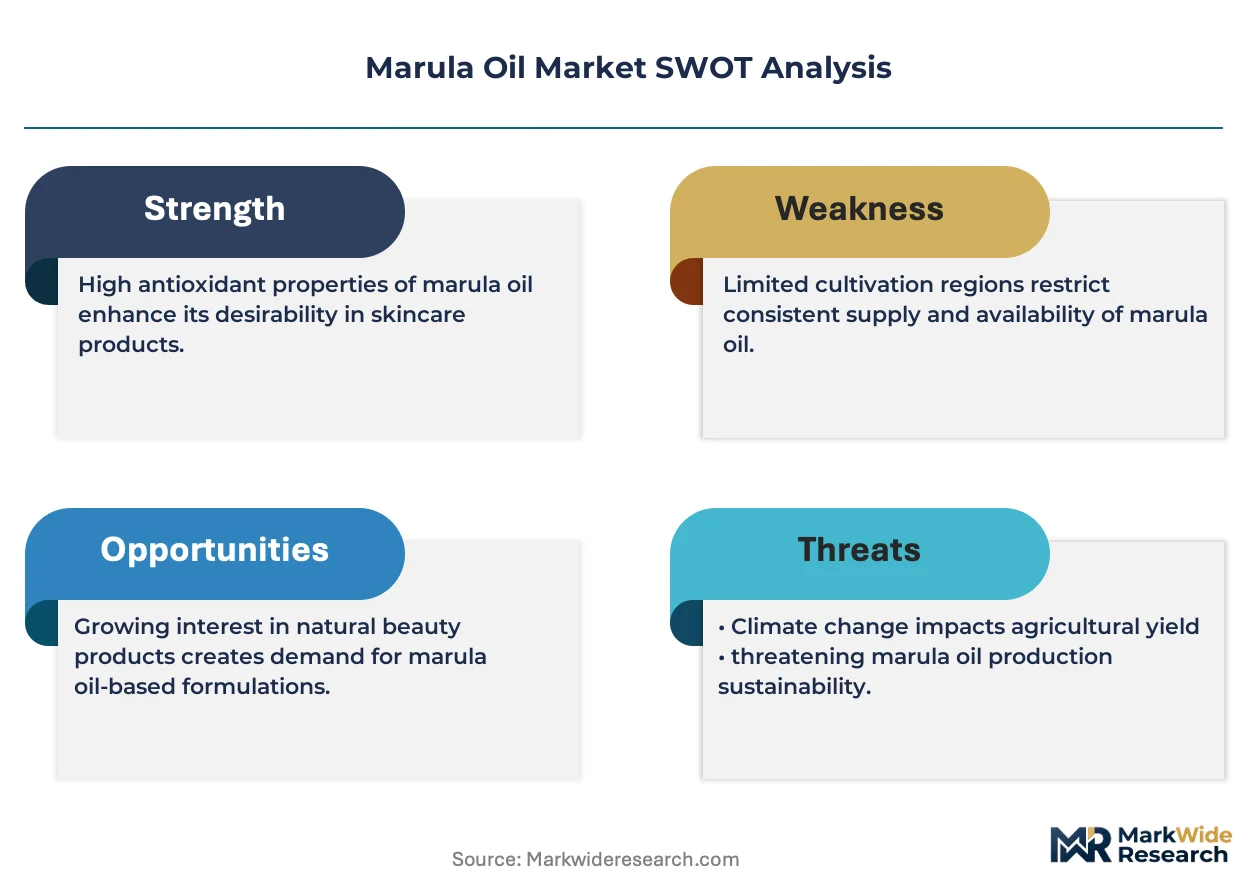
Marula oil is a fixed vegetable oil expressed from the kernels of Sclerocarya birrea, containing oleic acid levels exceeding 70% and demonstrating high oxidative stability due to natural tocopherols. Cold-pressed marula oil retains superior antioxidant profiles for cosmetic formulations, while refined variants serve broader food and pharmaceutical applications where color neutrality matters. The cosmetics application commands premium positioning through facial oil and anti-aging serum demand, whereas food manufacturers represent an emerging volume channel as culinary grade certifications expand. Beauty brands as end users currently dominate procurement volumes, though health stores are gaining traction through direct-to-consumer private label expansion.
EC 1223/2009 governs cosmetic safety assessments for marula oil formulations entering Europe, while South Africa's Department of Agriculture, Land Reform and Rural Development regulates export phytosanitary certification for kernel shipments. BIS standards in India and FDA cosmetic labeling rules in the United States create fragmented compliance landscapes that favor suppliers with multi-jurisdictional documentation capabilities. Stakeholders must monitor evolving organic certification requirements and community benefit-sharing regulations that increasingly determine market access eligibility.
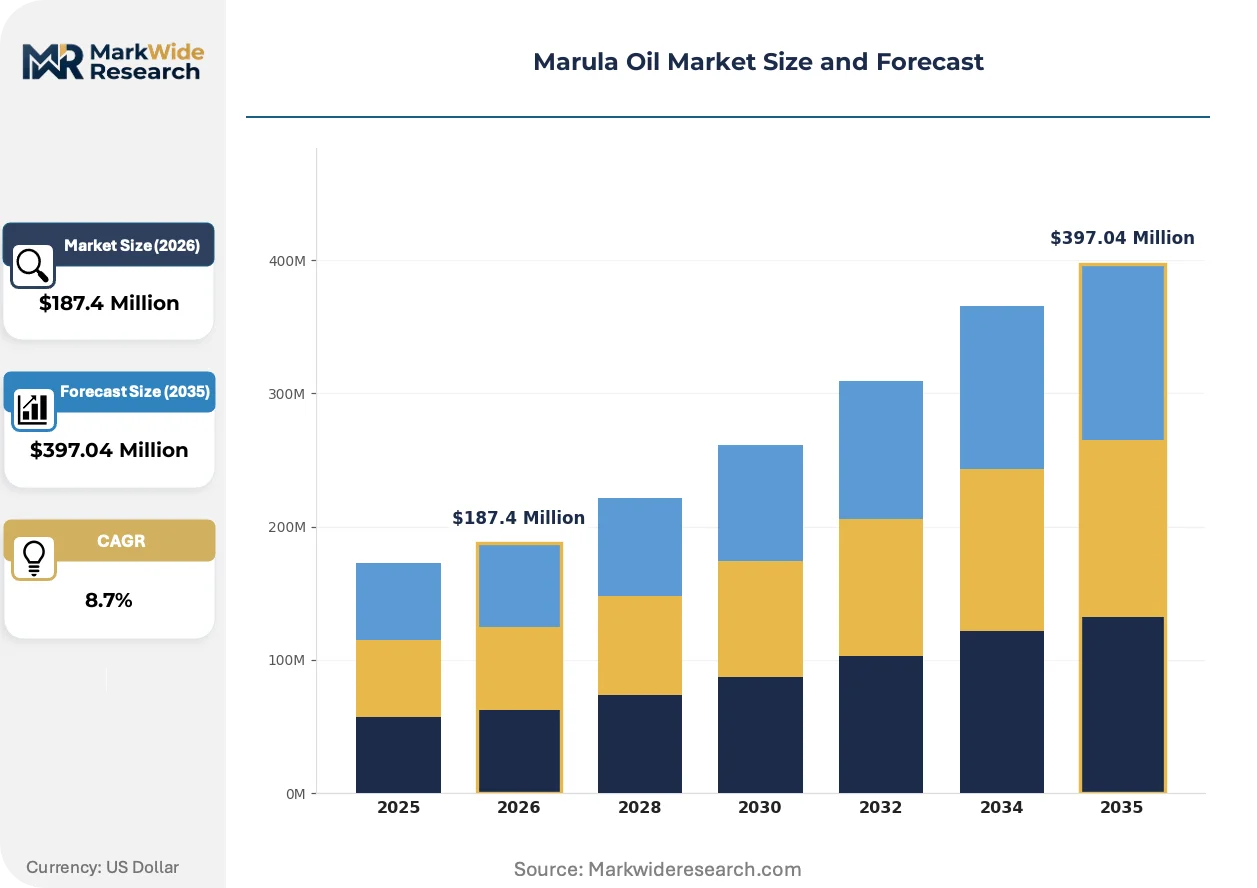
Market Dynamics
REACH compliance deadlines are compressing formulation timelines for European cosmetic brands sourcing marula oil, forcing suppliers to accelerate traceability documentation and cold-chain verification protocols.
Growth Catalysts
- EC 1223/2009 Safety Assessments:European cosmetic regulation mandates comprehensive toxicological dossiers for vegetable oils, creating competitive moats for suppliers with established documentation capabilities.
- Cold-Pressed Extraction:Supercritical CO2 and mechanical cold-press technologies preserve tocopherol profiles above 70°C threshold limits, satisfying premium cosmetic grade specifications.
- Southern African Cooperative Networks:Community-based collection systems in Namibia and Botswana secure kernel supply through benefit-sharing agreements that stabilize raw material access.
Market Restraints
- Kernel Supply Concentration:Wild harvest dependency across Limpopo Basin ecosystems limits scalable cultivation alternatives, concentrating sourcing risk in drought-prone regions.
- Oleic Acid Substitutes:Argan oil and squalane demonstrate comparable oxidative stability indices, pressuring marula's premium positioning in facial serum formulations.
- Phytosanitary Certification Friction:South Africa's export documentation requirements create 4-8 week shipment delays, constraining just-in-time inventory models for European manufacturers.
Strategic Opportunities
- India BIS Standard Alignment:Emerging ayurvedic cosmetic manufacturers seek cold-pressed vegetable oils meeting Bureau of Indian Standards purity specifications for domestic and export markets.
- Culinary Grade Certification Expansion:Food-grade marula oil applications in gourmet cooking and nutraceutical capsules represent underdeveloped volume channels beyond cosmetic dominance.
- Blockchain Traceability Integration:Distributed ledger verification of cooperative harvest records satisfies EUDR due diligence requirements for deforestation-free supply chains.
Industry Challenges
- Analytical Chemist Scarcity:Specialized lipid profile characterization and oxidative stability testing require expertise in gas chromatography methods that outpaces regional training pipeline output.
- Organic Certification Timelines:ECOCERT and USDA Organic conversion periods demand 3-year field history documentation that delays market access for newly certified cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marula Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Unrefined, Essential Oil Application: Cosmetics, Personal Care, Food, Pharmaceuticals End User: Beauty Brands, Food Manufacturers, Health Stores, Retailers Packaging Type: Bottles, Tubes, Jars, Pouches |
| Companies Covered | Lonza Venkatramna Industries, Aethon International LLP, Phytoafrica GmbH, MarulaLab, DLG Naturals, African Botanics, Givaudan, Cedarome, Africa Natural Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marula Oil Market Strategic Shifts
Supercritical extraction infrastructure is migrating from batch to continuous processing configurations, compressing unit economics for premium-grade marula oil while biochemical assay standardization reshapes quality verification protocols across buyer specifications.
Enzymatic degumming technology is consolidating quality control workflows by replacing conventional acid-refining steps with selective phospholipase treatments. Mid-tier cosmetic manufacturers in Germany and France adopt these systems to reduce neutral oil losses below 2%. The consolidation is compressing price premiums between refined and unrefined grades.
REACH Annex XVII restrictions on allergen labeling thresholds are tightening disclosure requirements for cosmetic formulations containing nut-derived oils. European formulators now demand complete protein removal certificates from marula suppliers. Compliance investments favor established exporters with in-house laboratory capabilities over trading intermediaries.
Direct-to-consumer subscription models are displacing traditional distributor relationships for specialty oil brands. Health store chains in California and New York pilot private-label marula facial oils with QR-linked provenance storytelling. This channel rotation concentrates marketing spend on digital education rather than wholesale trade show presence.
Marula Oil Market Segmentation
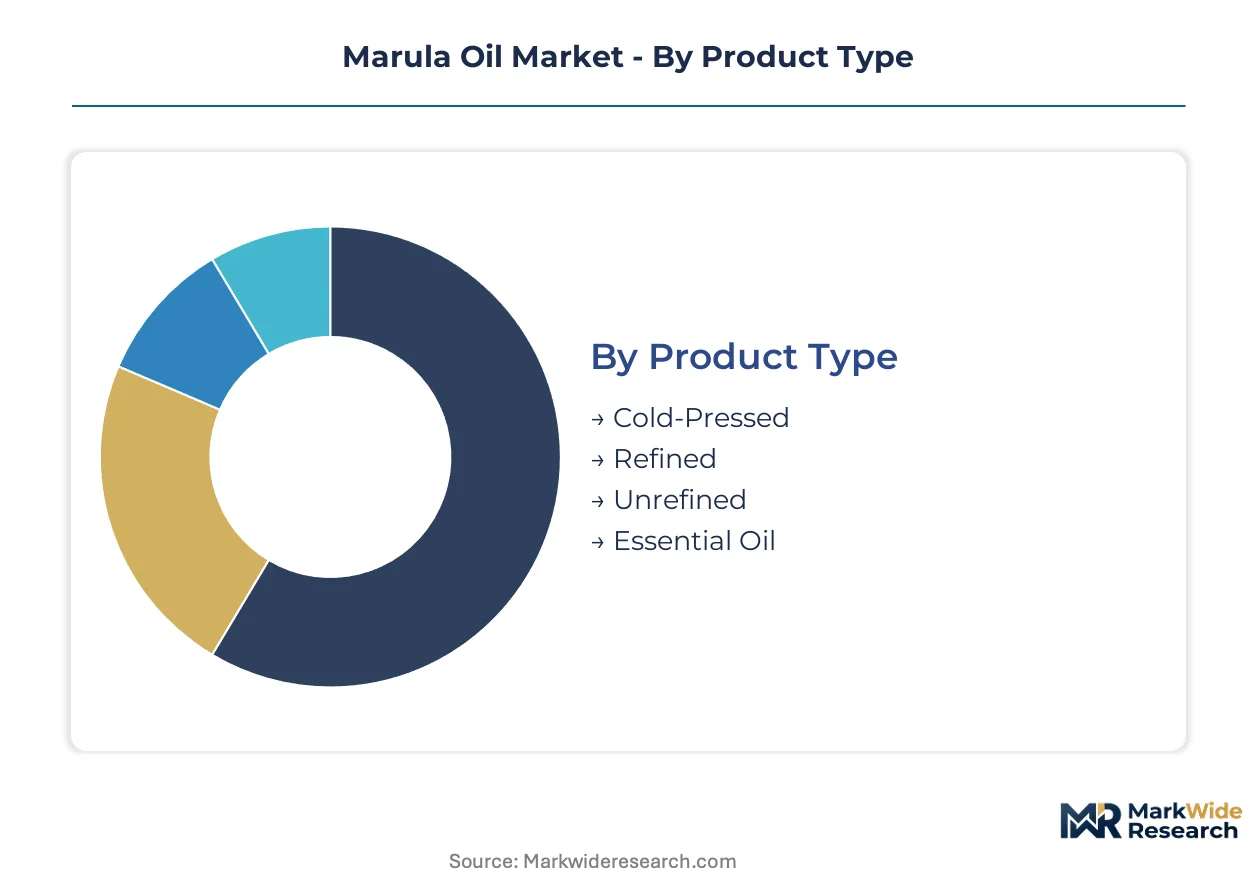
Marula oil procurement strategies diverge sharply across extraction grades and end-use specifications. Buyers prioritize cold-pressed variants for antioxidant retention while industrial users accept refined grades for cost efficiency.
Product Type:
Supply concentration in Southern African cooperatives favors mechanical extraction methods that preserve kernel integrity through controlled temperature protocols.
- Cold-Pressed:Mechanical extraction below 70°C preserves tocopherol concentrations above 400mg/kg. Premium cosmetic manufacturers in France and Germany specify this grade for facial serum formulations where oxidative stability indices determine shelf-life performance.
- Refined:Neutralized and deodorized through steam distillation to achieve color values below 2.0 R. Industrial food processors in South Africa and Namibia source this grade for cooking oil blends where flavor neutrality outweighs nutrient retention priorities.
- Unrefined:Filtered only through sedimentation, retaining characteristic nutty aroma and golden hue. Artisanal soap makers and small-batch cosmetic formulators seek this grade for natural positioning claims.
- Essential Oil:Steam-distilled from marula fruit pulp rather than kernels, yielding volatile aromatic compounds for fragrance applications.
Cold-pressed absorbs the bulk of installed capacity; unrefined is expanding most quickly through direct-to-consumer channels.
Application:
Cost tier differentiation separates premium cosmetic positioning from commodity food and pharmaceutical volume plays.
- Cosmetics:Facial oils and anti-aging serums command formulation premiums through oleic acid content exceeding 70%. REACH Annex XVII compliance requirements in Europe mandate complete protein removal documentation, favoring suppliers with in-house laboratory capabilities.
- Personal Care:Hair treatments and body lotions utilize marula oil for emollient properties without the oxidative sensitivity of polyunsaturated alternatives. Formulators in California health store chains specify this segment for private-label expansion.
- Food:Culinary-grade certifications remain underdeveloped relative to cosmetic channels, though gourmet cooking applications in South Africa and Botswana are gaining regulatory clarity.
- Pharmaceuticals:Soft-gel capsule formulations require supercritical CO2 extraction to meet residual solvent standards for nutraceutical applications.
Cosmetics absorbs the bulk of installed capacity; food is climbing the fastest as culinary certifications mature.
End User:
Customer type determines procurement scale and specification rigor, from multinational beauty brands to fragmented health store networks.
- Beauty Brands:Multinational manufacturers specify cold-pressed grades with batch-specific oxidative stability certificates. Direct community partnerships in Namibia secure supply priority through benefit-sharing agreements.
- Food Manufacturers:Volume buyers prioritize refined grades with FSSC 22000 food safety certifications for industrial cooking oil applications.
- Health Stores:California and New York chains pilot private-label facial oils with QR-linked provenance storytelling, displacing traditional distributor relationships.
- Retailers:Mass-market supermarkets stock refined marula oil for cooking applications where price sensitivity limits premium positioning.
Beauty brands absorb the bulk of installed capacity; health stores are gaining share fastest through subscription model adoption.
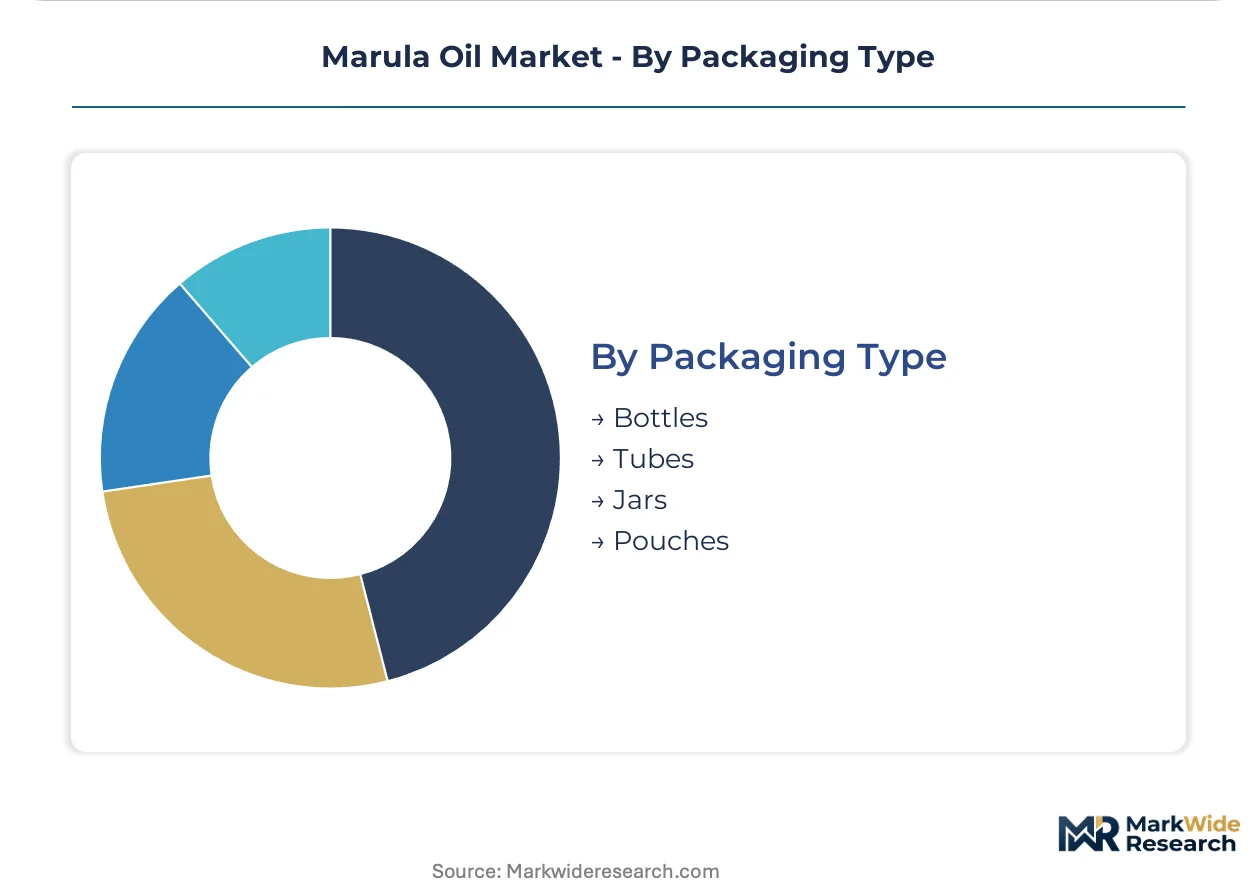
Packaging Type:
Volume considerations favor bulk formats for industrial buyers while premium positioning drives small-format innovation.
- Bottles:Amber glass with UV protection dominates premium cosmetic positioning, though lightweight PET alternatives penetrate mass-market channels.
- Tubes:Aluminum-laminate constructions suit travel-size facial oil formats for airline retail and subscription box inclusion.
- Jars:Wide-mouth glass containers serve body butter and hair mask formulations where scoop access matters.
- Pouches:Stand-up flexible packaging reduces shipping costs for food-grade refined oil in institutional catering quantities.
Bottles absorb the bulk of installed capacity; pouches show steepest expansion trajectory through food service channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Limpopo Basin ecosystem anchors commercial marula kernel harvests, with wild collection networks extending across Southern African savanna corridors. Supply chain control tightens as cooperatives consolidate collection rights through community benefit-sharing frameworks.
South Africa
Phytosanitary certification requirements from the Department of Agriculture, Land Reform and Rural Development govern kernel exports from Limpopo and Mpumalanga provinces. Cold-pressed extraction facilities cluster around Polokwane and Nelspruit, serving European cosmetic manufacturers with REACH-compliant documentation packages.
Namibia
Community-based natural resource management programs secure harvest access across communal lands in the north-central regions. Direct partnership agreements between cooperatives and premium beauty brands bypass traditional trading intermediaries. Windhoek hosts the primary oil pressing infrastructure for export-grade unrefined production.
Germany
EC 1223/2009 compliance mandates drive demand for batch-specific oxidative stability certificates from Southern African suppliers. Cosmetic formulators in Hamburg and Munich specify supercritical CO2 extraction grades for facial serum applications. ECHA registration requirements favor established importers with in-house analytical capabilities.
United States
FDA cosmetic labeling rules govern marula oil distribution through health store chains in California and New York. Private-label subscription models displace traditional distributor relationships. Los Angeles and Brooklyn anchor direct-to-consumer fulfillment networks for provenance-linked facial oil brands.
India
BIS vegetable oil purity specifications shape procurement from ayurvedic cosmetic manufacturers in Maharashtra and Karnataka. Cold-pressed grade demand accelerates as domestic formulators seek export-ready certification. Mumbai and Bangalore concentrate import logistics and quality verification laboratories.
Marula Oil Market Competitive Environment
Global majors compete with regional champions across extraction technology tiers, with Southern African cooperatives holding kernel supply advantages against European and North American formulators. Market structure fragments across unrefined artisanal producers, mid-scale cold-press operators, and industrial refining facilities. Three archetypes dominate: community-anchored cooperatives with direct brand partnerships, European distributors with certification infrastructure, and volume-scale refiners serving food and pharmaceutical channels. Capacity expansion and strategic partnership formation represent the primary competitive moves as traceability requirements harden.
Within the cooperative-anchored tier, African Botanics and Phytoafrica GmbH exemplify divergent geographic positioning—one Southern African, one European—while occupying complementary positions in premium unrefined supply chains. DLG Naturals sits within the scale-driven refining segment. Lonza Venkatramna Industries represents the Indian manufacturing presence seeking BIS-aligned export grades. MarulaLab and Aethon International LLP occupy mid-tier positions between artisanal collection and industrial processing.
| Leading Market Players |
|---|
| Lonza Venkatramna Industries |
| Aethon International LLP |
| Phytoafrica GmbH |
| MarulaLab |
| DLG Naturals |
| African Botanics |
| Givaudan |
| Cedarome |
| Africa Natural Oils |
| Others |
Value Chain & Pricing Dynamics
Captive supply networks anchored in Southern African cooperative partnerships anchor both procurement security and premium pricing power for marula oil suppliers. This integration choice insulates cold-pressed grade producers from commodity spot volatility while concentrating margin capture among community-certified operators.
Pricing Analysis
Batch-specific oxidative stability certificates bundled with REACH-compliant documentation packages command premium positioning over unbundled refined grades. Three-tier pricing structure across cold-pressed, unrefined, and refined levels separates cosmetic manufacturers from food processors and artisanal formulators. Cost compression in refined segments is intensifying because enzymatic degumming technology neutralizes quality premiums. Industrial food manufacturers exhibit highest price sensitivity; premium beauty brands demonstrate lowest sensitivity due to traceability requirements.
Supply Chain Analysis
Direct-to-brand channels handle multinational beauty manufacturer demand while health store subscription models bypass traditional distributors. Kernel supply draws from South Africa, Namibia, and Botswana through wild harvest collection networks. Cold-pressed extraction equipment, phytosanitary certification infrastructure, and analytical laboratory capacity represent critical input dependencies. Single-source vulnerability concentrates in drought-prone Limpopo Basin ecosystems. Distribution runs through certified cooperative exporters with multi-jurisdictional documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around traceability compliance investments that marginalize trading intermediaries lacking laboratory infrastructure. REACH documentation deadlines and organic certification timelines force weaker players toward acquisition or exit.
For Market Incumbents: Extend laboratory capabilities to capture protein removal certificate demand from European formulators facing REACH Annex XVII tightening. Anchor supply priority through benefit-sharing agreement expansion in Namibian communal lands. Squalane and argan oil substitution threats in facial serum formulations demand antioxidant profile differentiation through supercritical CO2 extraction investment. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting California and New York health store chains with QR-linked provenance storytelling. Culinary-grade certification expansion in South Africa and Botswana represents the most penetrable white-space channel. Private-label partnerships with ayurvedic cosmetic manufacturers seeking BIS-aligned export grades offer secondary entry angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of community-anchored cooperatives with ECOCERT conversion timelines already initiated. Long-term viability hinges on deforestation-free supply chain verification capabilities satisfying EUDR due diligence requirements. Blockchain traceability integration adoption rates signal inflection timing for premium grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Partnerships | Direct community agreements in Namibia secure kernel supply priority through benefit-sharing frameworks. |
| Cold-Pressed Capacity Expansion | Supercritical CO2 infrastructure migration from batch to continuous processing compresses unit economics for cosmetic grades. |
| Blockchain Traceability Implementation | Distributed ledger verification satisfies EUDR due diligence requirements for deforestation-free supply chain documentation. |
| Culinary Grade Certification Pursuit | Food-grade pathway development in South Africa unlocks underdeveloped volume channels beyond cosmetic dominance. |
| Analytical Laboratory Investment | In-house oxidative stability testing capabilities capture REACH-compliant documentation demand from European formulators. |
Study Parameters
Trade databases, cooperative export records, and cosmetic regulatory filings formed the secondary backbone of this analysis. Primary interviews with cold-press facility operators, European cosmetic formulators, and phytosanitary certification officers combined with secondary validation across Bureau of Indian Standards documentation and ECHA registration records. Bottom-up kernel harvest estimates and top-down cosmetic ingredient demand triangulation anchored supply-demand balance assessments.
Historical trendline analysis of cold-pressed grade premiums against refined oil spreads informed projection frameworks across the modeling period. Segmentation dimensions spanned extraction technology tier, end-use application, and certification status. CAGRs derived from weighted average of volume trajectory and price evolution assumptions. Forecast inputs incorporated organic certification conversion pipeline visibility and supercritical extraction capacity expansion schedules.
Drought frequency in Limpopo Basin harvest zones, REACH documentation deadline acceleration, and squalane substitution elasticity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding cooperative network stability and culinary grade regulatory clarity progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Caryophyllene Market