
 North America Chromatography Resins Market | 2026-2036
North America Chromatography Resins Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chromatography Resins Market Analytics
Platform licensing revenue is reshaping competitive economics as vendors bundle resin supply with method development services. Thermo Fisher Scientific leverages its analytical instrument installed base to secure long-term resin supply contracts. Merck KGaA anchors its position through backward integration into raw agarose production for affinity chromatography media.
Chromatography resins comprise porous polymer or silica-based beads functionalized with ligands that selectively bind target molecules during liquid-phase separation. Manufacturers control pore size distribution and particle diameter to optimize resolution and flow characteristics for biomolecule purification. Affinity resins command premium positioning due to protein A ligand scarcity and batch-to-batch consistency requirements. Ion exchange resins compete on capacity and regeneration cycles in downstream bioprocessing workflows.
FDA process validation guidelines and USP monographs for biologics manufacturing shape resin qualification protocols and supplier audit intensity. EPA discharge standards for organic solvents influence technology selection between liquid chromatography and supercritical fluid alternatives. Stakeholders must monitor how USP-NF chapter revisions for chromatographic reagents affect resin specification requirements and vendor switching costs.
Market Dynamics
FDA process analytical technology mandates are compressing resin qualification timelines while protein A ligand scarcity concentrates supplier power among integrated agarose producers. Contract manufacturers in Massachusetts and New Jersey are locking in multi-year resin supply agreements to secure batch consistency for monoclonal antibody pipelines.
Growth Catalysts
- Biologics manufacturing expansion:Contract development organizations in Massachusetts and New Jersey are scaling single-use bioreactor capacity, driving parallel resin consumption for downstream purification workflows.
- FDA process analytical technology guidelines:Real-time release testing requirements are forcing manufacturers to qualify high-performance resins with tighter batch-to-batch consistency specifications.
- Monoclonal antibody pipeline density:Oncology and autoimmune therapeutic development in the northeastern United States is concentrating demand for protein A affinity chromatography media.
Market Restraints
- Protein A ligand supply concentration:Recombinant protein A production is captive to three specialized fermentation facilities, creating single-source vulnerability for affinity resin manufacturers.
- Raw agarose price volatility:Seaweed harvest variability in the North Atlantic is transmitting cost instability to base bead producers.
- EPA solvent discharge standards:Organic solvent recovery requirements for large-scale chromatography operations are adding capital intensity to facility expansions.
Strategic Opportunities
- Continuous bioprocessing adoption:Multi-column periodic counter-current systems are creating demand for smaller-particle, higher-pressure resins in Canadian biologics facilities.
- Cell and gene therapy purification:Viral vector manufacturing in Texas and California is opening specifications for novel affinity ligands targeting adeno-associated virus serotypes.
- USP-NF chapter harmonization:Pending revisions to chromatographic reagent monographs are creating first-mover advantage for resins pre-qualified to draft standards.
Industry Challenges
- Resin lifetime validation complexity:Demonstrating consistent performance across hundreds of regeneration cycles requires extensive documentation for FDA submission packages.
- Legacy facility retrofit constraints:Older purification suites in New Jersey and Pennsylvania lack hydraulic capacity for high-pressure packed bed operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chromatography Resins Market |
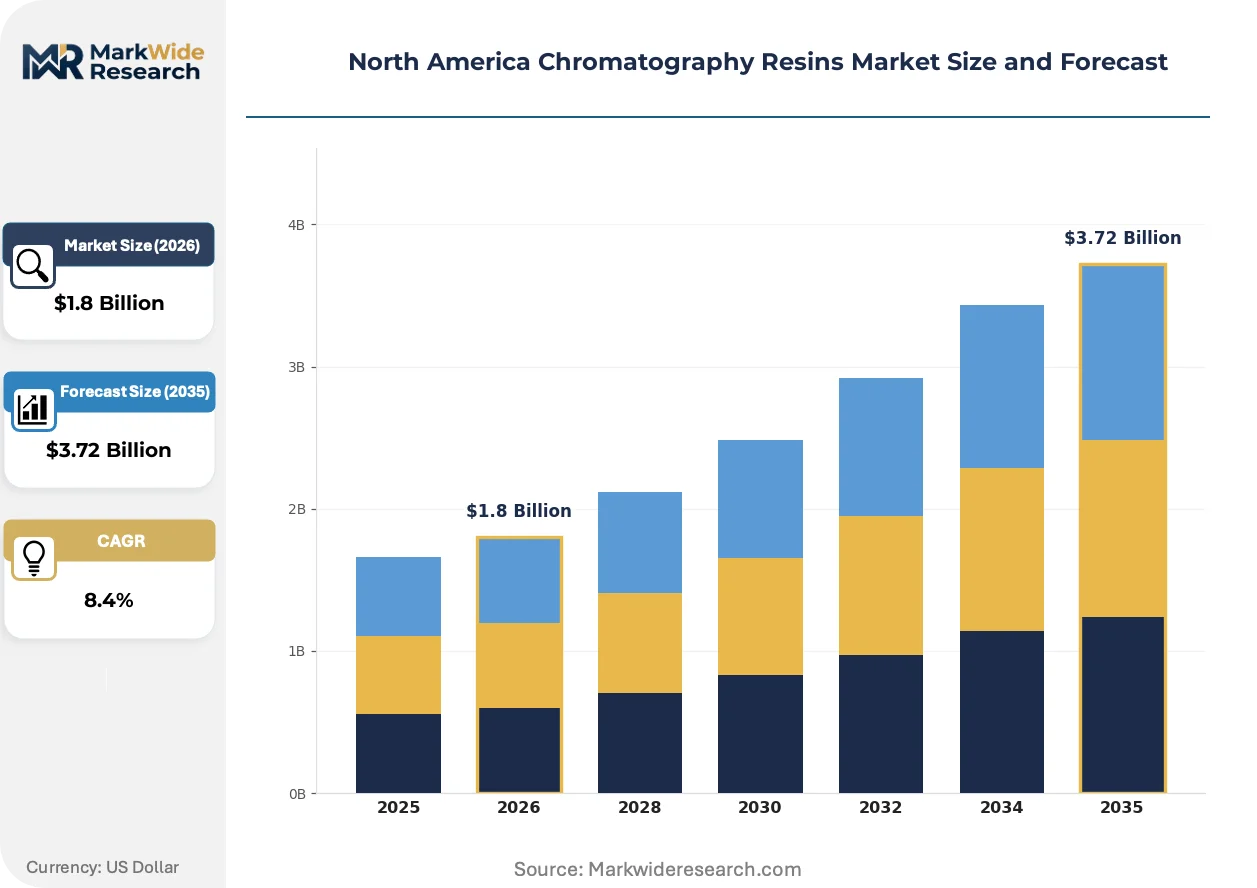
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Affinity Resins, Ion Exchange Resins, Reverse Phase Resins, Size Exclusion Resins End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Environmental Testing Labs Application: Protein Purification, Drug Development, Quality Control, Academic Research Technology: Liquid Chromatography, Gas Chromatography, Supercritical Fluid Chromatography, Hyphenated Techniques |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, GE Healthcare, Bio-Rad Laboratories, Agilent Technologies, Avantor, DuPont de Nemours, Mitsubishi Chemical Corporation, Purolite Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chromatography Resins Market Evolving Landscape
Resin architecture is evolving toward higher binding capacity and mechanical stability to support intensified bioprocessing. Manufacturers are reconfiguring ligand chemistry and base matrix composition to match continuous manufacturing throughput requirements.
Single-use chromatography systems are migrating from stainless steel batch operations in legacy biologics facilities. Mid-scale contract manufacturers in North Carolina and Maryland are adopting disposable flow paths to reduce cross-contamination risk between campaigns. This shift is compressing demand for traditional large-diameter packed columns while expanding specifications for pre-packed, gamma-irradiated resin cartridges.
FDA guidance on co-processed excipients is tightening documentation requirements for resin-derived impurities in final drug substance. Biopharmaceutical sponsors must now demonstrate clearance of leachable ligand fragments and base matrix components through validated orthogonal assays. Small-molecule and peptide manufacturers are most affected, accelerating qualification of synthetic polymer resins with cleaner extractables profiles.
Integrated supply contracting is consolidating procurement decisions at the platform level rather than the resin SKU level. Large biopharmaceutical sponsors in Massachusetts are bundling resin supply with method development and regulatory filing support from preferred vendors. This pattern is most visible among sponsors with multiple assets in Phase III, where timeline risk outweighs unit cost optimization.
North America Chromatography Resins Market Segmentation
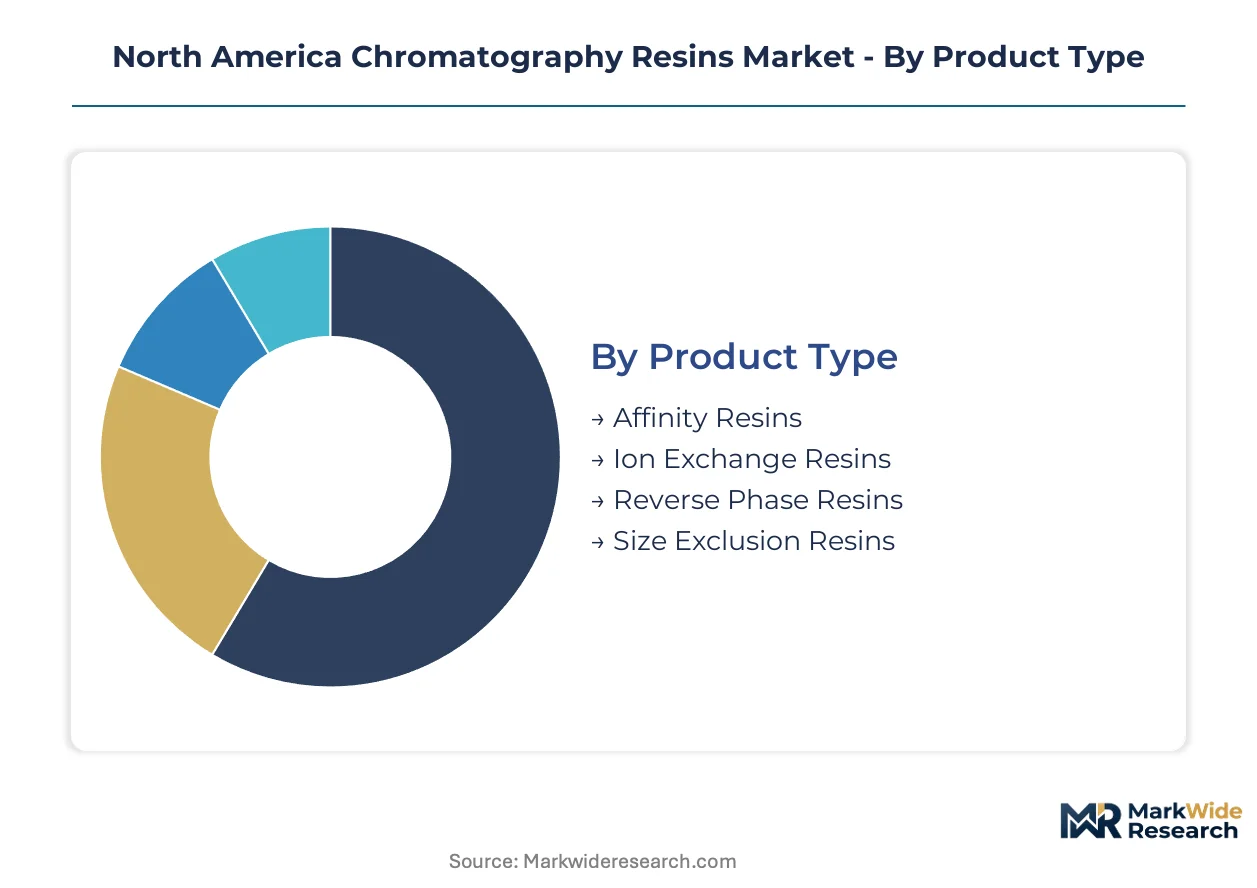
Chromatography resin purchasing decisions fragment across four distinct axes: product chemistry dictates purification performance, end-user scale determines contract structure, application urgency shapes qualification timelines, and technology platform constrains physical resin specifications. Understanding these intersecting dimensions reveals where vendor bundling strategies capture margin and where unmet specification gaps create entry opportunities.
Product Type:
Cost tier stratification separates premium affinity media from commodity ion exchange alternatives, with price spreads reflecting ligand scarcity and manufacturing complexity rather than base bead economics alone.
- Affinity Resins:Protein A-functionalized agarose beads achieve selective monoclonal antibody capture through Fc region binding. Massachusetts and New Jersey contract manufacturers consume the majority of North American supply for Phase III oncology pipelines, with batch-to-batch consistency requirements compressing vendor qualification to three integrated producers.
- Ion Exchange Resins:Cation and anion variants separate molecules by surface charge distribution at lower unit cost than affinity alternatives. High-cycle regeneration protocols in Pennsylvania legacy facilities favor strong ion exchangers with demonstrated alkaline stability across hundreds of reuse cycles.
- Reverse Phase Resins:Hydrophobic silica or polymer matrices retain small molecules and peptides through non-polar interactions. Peptide manufacturers in California specify C18-functionalized particles for insulin analog purification workflows.
- Size Exclusion Resins:Porous matrices fractionate by hydrodynamic radius without binding interactions. Viral vector producers in Texas adopt these for aggregate removal in gene therapy downstream processing.
Affinity Resins holds installed capacity. Ion Exchange Resins is rotating up the share rankings as continuous bioprocessing intensification demands higher cycling efficiency.
End User:
Customer type determines procurement leverage, with large pharmaceutical sponsors extracting platform-level concessions unavailable to fragmented academic buyers.
- Pharmaceutical Companies:Integrated biopharmaceutical sponsors in Massachusetts negotiate multi-year resin supply agreements bundling media, method development, and regulatory filing support. FDA process validation timelines create switching costs that lock in preferred vendor relationships across asset portfolios.
- Biotechnology Firms:Venture-backed developers in Cambridge and South San Francisco prioritize pre-qualified resin SKUs to compress IND-to-BLA timelines. Single-use purification systems dominate their facility designs, favoring gamma-irradiated pre-packed cartridges over bulk resin procurement.
- Academic Research Institutions:University core facilities purchase smaller batch quantities through distributor channels rather than direct manufacturer contracts. NIH grant funding cycles create lumpy demand patterns with price sensitivity to per-gram resin costs.
- Environmental Testing Labs:EPA compliance monitoring drives solid-phase extraction resin consumption for pollutant detection. Water testing laboratories in the Great Lakes region specify mixed-mode resins for simultaneous recovery of polar and non-polar contaminants.
Pharmaceutical Companies command volume concentration. Biotechnology Firms are climbing the fastest as monoclonal antibody pipeline density expands.
Application:
Application urgency stratifies qualification intensity, with commercial manufacturing demanding exhaustive documentation that research-scale use escapes.
- Protein Purification:Downstream bioprocessing workflows isolate therapeutic proteins from cell culture harvest through sequential chromatography steps. Protein A affinity capture followed by ion exchange polishing dominates monoclonal antibody processes in New Jersey and Massachusetts contract manufacturing organizations.
- Drug Development:Preclinical and clinical supply production requires resin lots qualified for GMP use with full traceability documentation. Phase I sponsors in Maryland prioritize speed-to-clinic over unit cost optimization in resin selection.
- Quality Control:Analytical chromatography for release testing and stability monitoring consumes high-purity resin grades with minimal extractables. USP-NF chapter compliance drives specification rigor for final drug substance impurity profiling.
- Academic Research:Fundamental studies of protein structure and function employ resin formats optimized for flexibility rather than throughput. Core facilities at Texas Medical Center and Boston research clusters maintain diverse resin libraries for method exploration.
Protein Purification anchors manufacturing demand. Drug Development is gaining share fastest as clinical pipeline density concentrates in the northeastern United States.
Technology:
Technology platform constrains resin physical specifications, with pressure rating and solvent compatibility requirements diverging sharply across modalities.
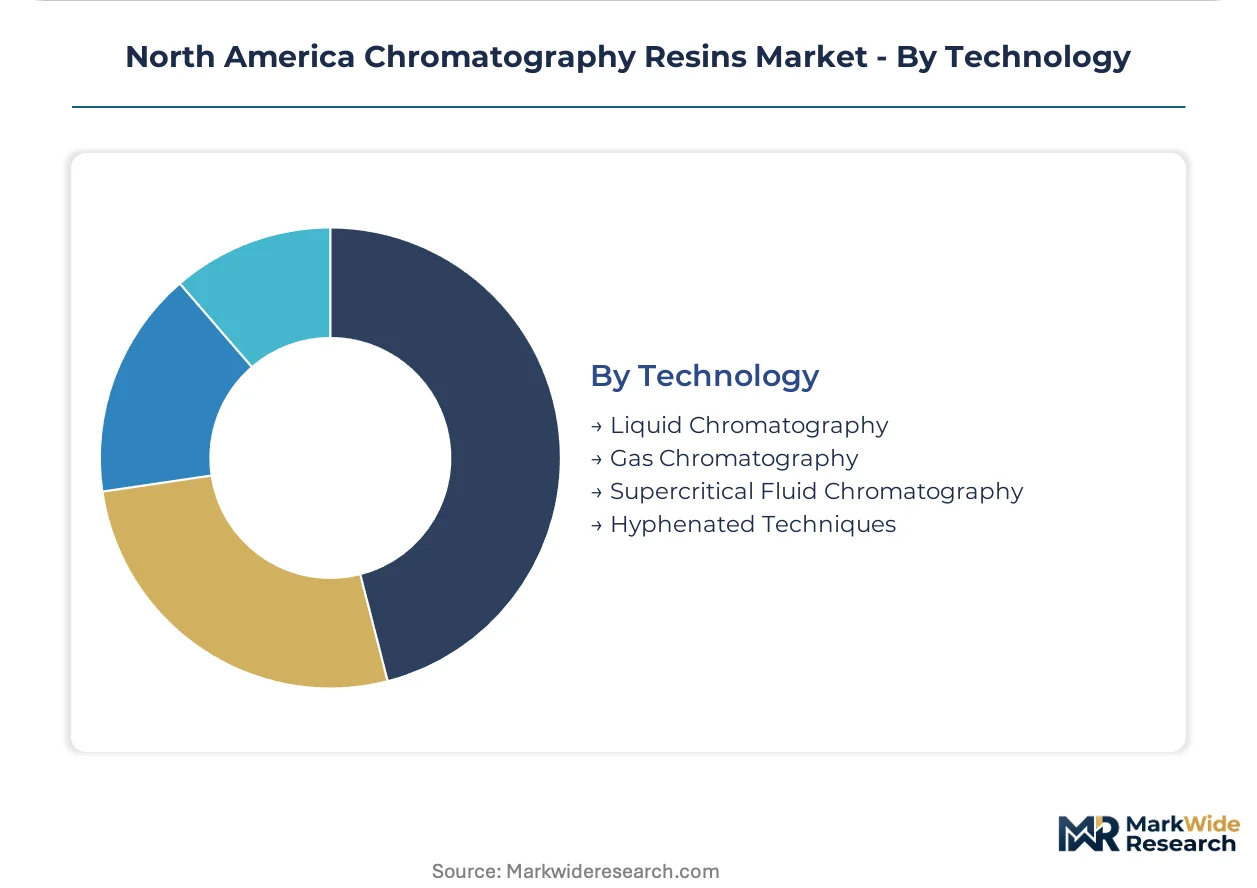
- Liquid Chromatography:Aqueous mobile phase systems dominate biopharmaceutical purification, driving demand for hydrophilic base matrices with protein-compatible ligand chemistries. High-performance liquid chromatography variants in Canadian facilities specify smaller particle diameters for resolution-critical separations.
- Gas Chromatography:Volatile analyte separation employs packed columns with solid stationary phases rather than functionalized beads. Environmental testing applications in EPA Region 5 consume specialized resins for atmospheric pollutant monitoring.
- Supercritical Fluid Chromatography:CO2-based mobile phases enable rapid chiral separations with reduced organic solvent consumption. Chiral stationary phase resins from Pennsylvania specialty manufacturers serve pharmaceutical impurity profiling needs.
- Hyphenated Techniques:LC-MS and GC-MS coupling demands ultra-low bleed resins to prevent ion source contamination. Metabolomics researchers at California institutions drive specifications for minimal fragment release under high-sensitivity detection.
Liquid Chromatography dominates installed base. Supercritical Fluid Chromatography is rotating up the share rankings as EPA discharge standards intensify solvent recovery requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers in Massachusetts and New Jersey exhibit low price elasticity for protein A resins due to FDA validation lock-in, while academic core facilities in the Great Lakes region demonstrate high sensitivity to per-gram costs.
United States
Massachusetts contract development organizations drive premium resin consumption for Phase III monoclonal antibody pipelines. FDA process analytical technology guidelines compress qualification timelines for high-performance affinity media. The Boston-Cambridge biotech corridor concentrates demand for protein A-functionalized agarose beads.
Canada
Canadian biologics facilities adopt multi-column periodic counter-current systems requiring smaller-particle, higher-pressure resins. Health Canada alignment with FDA validation standards streamlines cross-border supply agreements. Toronto and Montreal manufacturing clusters source pre-packed gamma-irradiated cartridges for single-use purification workflows.
Mexico
Environmental testing laboratories in Mexico City and Guadalajara consume solid-phase extraction resins for EPA-compliant water quality monitoring. Mexican pharmaceutical regulators harmonize with USP-NF monographs for chromatographic reagents. Northern border states specialize in analytical resin distribution serving maquiladora quality control operations.
North America Chromatography Resins Market Competitive Landscape
Integrated life science conglomerates and specialized chromatography media producers split the market through divergent bundling strategies. Three to four suppliers capture the majority of protein A affinity resin volume due to captive ligand fermentation capabilities. The competitive terrain separates into platform-integrators, raw material backward-integrators, and application-specialists. Capacity expansion in agarose bead production and strategic partnerships for continuous bioprocessing resin development represent the dominant competitive moves.
Within the platform-integrator tier, Thermo Fisher Scientific and GE Healthcare exemplify vendors leveraging analytical instrument installed bases to secure long-term resin supply contracts. Merck KGaA occupies a distinct position through upstream control over raw agarose production for affinity chromatography media.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| GE Healthcare |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Avantor |
| DuPont de Nemours |
| Mitsubishi Chemical Corporation |
| Purolite Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity in synthetic polymer base bead production is compressing margins for commodity ion exchange resins while tightening supply for protein A-functionalized agarose beads. Contract manufacturers in Massachusetts and New Jersey absorb premium pricing for affinity media due to FDA validation lock-in, whereas academic buyers in the Great Lakes region negotiate aggressively on per-gram costs for research-grade alternatives.
Pricing Analysis
Platform licensing and method development services now generate more lifetime value than resin unit sales alone. Three-tier pricing structure across premium, standard, and economy levels reflects batch-to-batch consistency grades and GMP certification status rather than base bead chemistry alone. Pricing pressure stems from raw agarose harvest variability in the North Atlantic transmitting cost instability downstream. Biotechnology firms in Cambridge demonstrate highest price sensitivity due to venture funding cycles, while Phase III sponsors in Massachusetts prioritize timeline security over unit cost optimization.
Supply Chain Analysis
Contract manufacturing concentration among Massachusetts and New Jersey biologics facilities anchors North American demand for protein A resins. Supply draws from captive fermentation facilities in the United States, agarose extraction operations in coastal Maine and Maritime Canada, and specialty chemical producers in Pennsylvania. Single-source vulnerability for recombinant protein A ligand production creates structural risk for affinity resin availability. Distribution runs through direct manufacturer contracts for pharmaceutical sponsors and distributor channels for academic and environmental testing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing adoption represents an early-cycle expansion story as Canadian and northeastern United States facilities retrofit for multi-column periodic counter-current systems. FDA process analytical technology mandates are accelerating qualification demands and locking in vendor relationships before competitive alternatives mature.
For Market Incumbents: Insulate market position through captive protein A ligand fermentation capacity and backward integration into raw agarose production. Thermo Fisher Scientific's instrument-installed-base bundling and Merck KGaA's upstream bead manufacturing control exemplify defensible moats. Priority investment in continuous bioprocessing resin specifications will preempt emerging entrant challenges. For New Entrants and Emerging Players: Pursue viral vector purification specifications for gene therapy manufacturing in Texas and California, where novel affinity ligands for adeno-associated virus serotypes remain underdeveloped. Cell and gene therapy applications offer the most penetrable segment due to absence of established protein A analogs. Go-to-market positioning through pre-qualified disposable cartridge formats accelerates qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across synthetic polymer resin production as continuous manufacturing reduces column volume requirements. Long-term viability favors platform-integrators with analytical instrument ecosystems over standalone media producers. Acquisition target archetype: specialty ligand developers with Health Canada and FDA pre-qualification dossiers. Monitor USP-NF chapter revision timing as inflection indicator for vendor switching cost dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Protein A Ligand Fermentation Capacity Expansion | Captive supply of recombinant ligand insulates against single-source vulnerability for affinity resin production. |
| Continuous Bioprocessing Resin Development | Smaller-particle, higher-pressure specifications match multi-column periodic counter-current adoption in Canadian facilities. |
| Platform Licensing with Method Development Bundling | Long-term supply contracts with Massachusetts sponsors extract value beyond unit resin sales through regulatory filing support. |
| Pre-Packed Gamma-Irradiated Cartridge Formats | Single-use purification workflows in Maryland and North Carolina contract manufacturing reduce cross-contamination risk. |
| USP-NF Chapter Pre-Qualification Investment | First-mover advantage from draft standard alignment creates switching cost barriers before monograph finalization. |
Research Methodology
Cross-validation between primary interviews with bioprocessing executives and secondary regulatory filing analysis anchors the qualitative findings. The research combined discussions with downstream process development leads, regulatory affairs specialists at contract manufacturing organizations, resin procurement managers, and FDA compliance officers with review of USP-NF monograph drafts, EPA discharge standard revisions, and SEC disclosures from integrated life science conglomerates. Bottom-up triangulation across resin consumption patterns and top-down validation against biologics manufacturing capacity expansion produced convergent estimates.
Calibration against historical protein A resin adoption curves and ion exchange media replacement cycles shaped the analytical framework. The model segmented across product chemistry tiers, end-user scale categories, application urgency levels, and technology platform specifications throughout the forecast period. CAGRs derived from intensity-of-use metrics per bioreactor liter and continuous bioprocessing penetration assumptions. Key inputs included monoclonal antibody pipeline density in the northeastern United States and Health Canada alignment with FDA validation timelines.
Sensitivities concentrate around protein A ligand supply disruptions, raw agarose harvest volatility, and USP-NF chapter revision timing. Forecasts reflect documented assumptions regarding continuous bioprocessing adoption rates and contract manufacturing capacity expansion. Quarterly review of FDA process analytical technology guidance updates and EPA solvent discharge enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Global Mandelic Acid Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market