
 Pegylated Lipids Market | 2026-2036
Pegylated Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Pegylated Lipids Market Insights
Buyer concentration among messenger RNA vaccine developers is restructuring procurement dynamics across the pegylated lipids supply base. Merck KGaA leverages its integrated excipient manufacturing network to sustain long-term contracts with major pharmaceutical formulators. Evonik Industries AG anchors European supply through specialized lipid production capabilities, while Avanti Polar Lipids competes on custom synthesis services for early-stage gene therapy developers.
Pegylated lipids are amphiphilic molecules composed of a lipid anchor conjugated to a polyethylene glycol (PEG) chain, typically synthesized through carbodiimide coupling or click chemistry to achieve precise chain lengths of 1–5 kDa for controlled steric stabilization. These materials primarily serve as critical excipients in nanoparticle formulations, where the PEG corona prevents opsonization and prolongs systemic circulation of encapsulated therapeutics. Lipid nanoparticles dominate current revenue pools due to their established role in COVID-19 and influenza mRNA vaccines, while gene therapy applications represent the fastest-expanding segment as adeno-associated virus alternatives gain regulatory traction. Chemical synthesis methods retain the largest installed manufacturing base, though biochemical methods are capturing growing interest from sustainability-focused biotechnology firms.
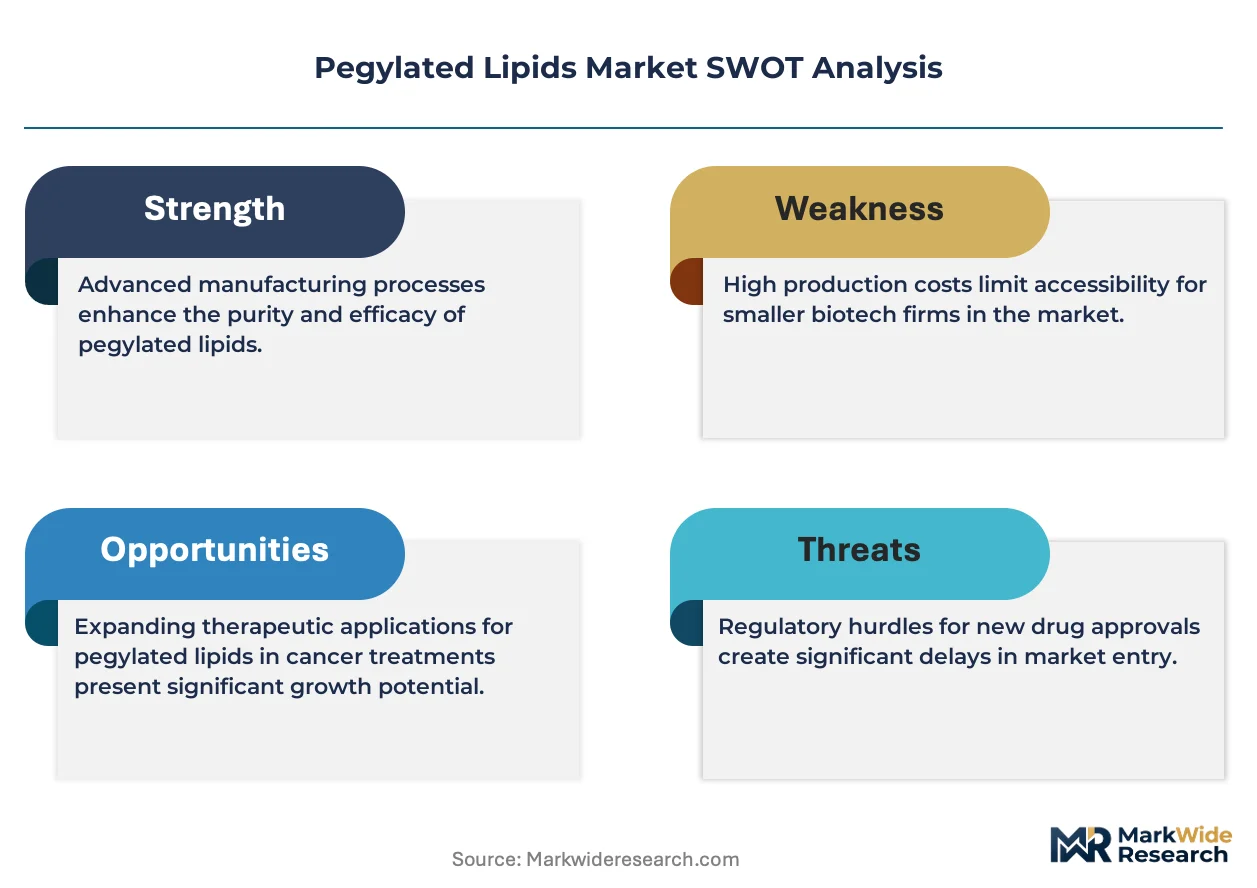
FDA oversight of lipid excipient quality attributes and EMA's evolving guidelines for nucleic acid drug substance characterization jointly elevate compliance costs for market entrants. ISO 10993 biocompatibility testing standards and USP-NF monograph requirements for PEGylated excipients further constrain supplier qualification timelines. Stakeholders must monitor emerging regulatory divergence between FDA and EMA on lipid impurity thresholds to anticipate reformulation investments and dual-filing strategies.
Market Dynamics
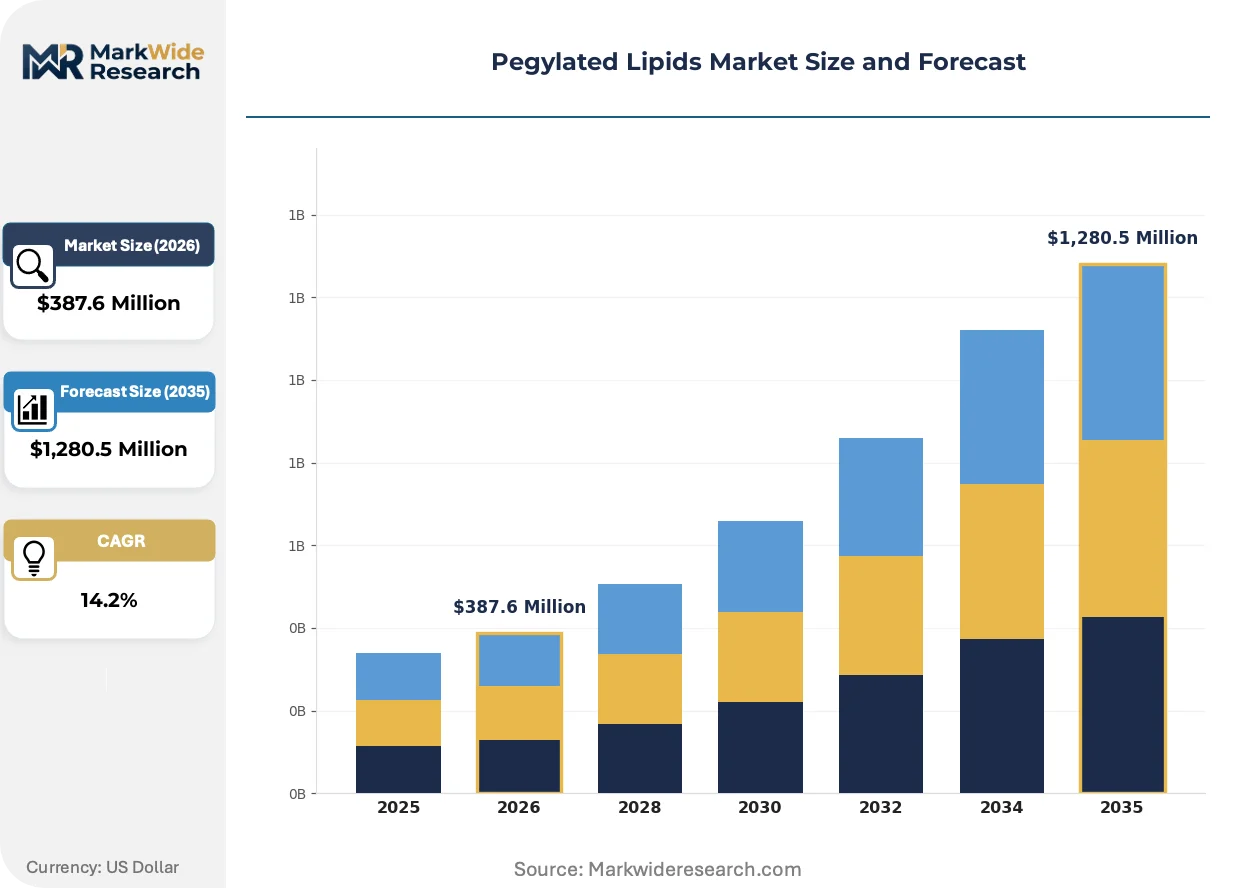
Messenger RNA vaccine developers are consolidating procurement power around specialized lipid suppliers capable of meeting FDA nucleic acid excipient guidance, compressing supplier qualification timelines and reshaping contract structures across the pegylated lipids value chain.
Growth Catalysts
- Lipid Nanoparticle Scale-Up:Pharmaceutical formulators expanding mRNA manufacturing capacity require steric-stabilizing excipients at commercial volumes, pulling specialized lipid synthesis into dedicated production lines.
- ISO 10993 Harmonization:Converging biocompatibility testing standards across FDA and EMA jurisdictions reduce dual-filing burdens for qualified suppliers, accelerating cross-border formulation approvals.
- Gene Therapy Pipelines:Adeno-associated virus alternatives in clinical development specify PEGylated lipid nanoparticles for non-viral nucleic acid delivery, opening adjacent demand pools beyond infectious disease vaccines.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Polyethylene glycol production depends on petrochemical derivatives subject to energy-price fluctuations, compressing margin predictability for specialty lipid manufacturers.
- Massachusetts-California Supply Concentration:Biotech manufacturing corridors cluster procurement volumes in two US states, creating geographic vulnerability to regional logistics disruptions or state-level environmental enforcement.
- Click Chemistry Patent Thickets:Copper-free strain-promoted azide-alkyne cycloaddition methods remain encumbered by university-held intellectual property, limiting process freedom for commercial scale-up.
Strategic Opportunities
- Indian Contract Manufacturing:CDSCO's streamlined excipient registration pathways and domestic PEG supply base position Indian producers to capture outsourced synthesis from Western pharmaceutical formulators.
- Biochemical Synthesis Methods:Enzymatic PEGylation and lipid conjugation using engineered acyltransferases offers sustainability-aligned alternatives to carbodiimide chemistry, attracting ESG-mandated procurement policies.
- Cell Therapy Ex Vivo Loading:mRNA electroporation into patient-derived cells for CAR-T and regenerative applications requires specialized lipid formulations distinct from systemic nanoparticle designs.
Industry Challenges
- Phospholipid Purification Expertise:Synthetic chemists capable of achieving pharmaceutical-grade lipid purity specifications remain concentrated at a handful of academic centers and specialized contract manufacturers.
- Multi-Attribute Method Validation:USP-NF monograph compliance for PEG molecular weight distribution, lipid chain saturation, and endotoxin levels demands capital-intensive analytical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pegylated Lipids Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipid Nanoparticles, Liposomes, Micelles, Emulsions End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Application: Drug Delivery, Vaccine Development, Gene Therapy, Cancer Treatment Technology: Chemical Synthesis, Biochemical Methods, Formulation Techniques, Analytical Methods |
| Companies Covered | Merck KGaA, NOF Corporation, BroadPharm, Avanti Polar Lipids, Lipoid, Jenkem, Evonik Industries AG, CordenPharma International, Creative PEGworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pegylated Lipids Market Trends and Innovations
Bioconjugation chemistry and regulatory science are advancing in parallel, with formulation developers demanding precise PEG chain length control while agencies tighten impurity profiling requirements for nucleic acid therapeutics.
Microfluidic manufacturing platforms for lipid nanoparticle assembly are absorbing investment from mRNA vaccine producers seeking batch-to-batch consistency at commercial scale. These continuous-flow systems enable precise control over mixing parameters that determine particle size distribution. Novartis and Sanofi manufacturing subsidiaries are retrofitting traditional stirred-tank operations with microfluidic modules, compressing process development timelines for new therapeutic indications.
EMA's 2023 revision to nucleic acid drug substance characterization guidelines elevates lipid impurity threshold scrutiny for marketing authorization holders in European markets. The guideline mandates identification and quantification of degradants arising from PEG oxidation and lipid hydrolysis under accelerated stability conditions. Formulators with approved COVID-19 vaccines are reformulating buffer compositions and overwrapping configurations to maintain compliance across shelf-life extensions.
Long-term offtake agreements are displacing spot purchasing as the dominant procurement modality among messenger RNA vaccine developers with approved products. These contracts specify minimum volume commitments, dedicated manufacturing slots, and co-investment in supplier capacity expansion. The shift concentrates purchasing power among three to five pharmaceutical formulators, squeezing margin flexibility for mid-tier lipid suppliers competing on custom synthesis services.
Pegylated Lipids Market Segmentation
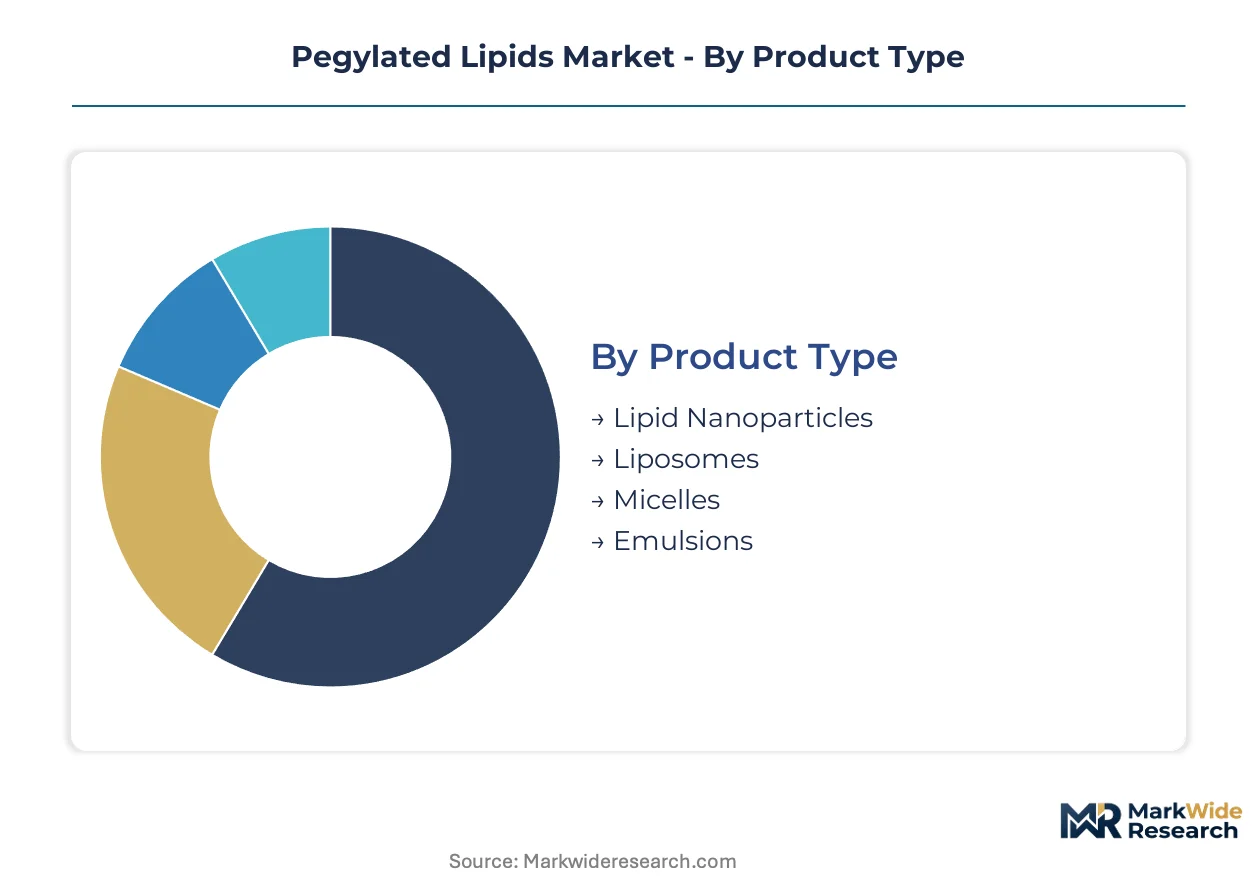
Pegylated lipids serve distinct formulation architectures with divergent purity requirements and procurement patterns. Segmentation reveals how therapeutic modality and manufacturing scale reshape supplier relationships across the value chain.
Product Type:
Formulation architecture determines steric stabilization needs, particle size targets, and regulatory validation burden for excipient suppliers.
- Lipid Nanoparticles:Solid lipid cores surrounded by PEGylated phospholipid shells enable encapsulation of nucleic acid payloads. Massachusetts and California biotech corridors concentrate procurement for mRNA vaccine manufacturing, where FDA nucleic acid excipient guidance elevates supplier qualification thresholds.
- Liposomes:Bilayer vesicle structures with surface-grafted PEG chains extend circulation half-life for small-molecule and protein therapeutics. Established oncology applications in European markets face reformulation pressure from EMA impurity threshold revisions.
- Micelles:Core-shell assemblies below 50 nm diameter solubilize hydrophobic APIs for parenteral delivery.
- Emulsions:PEG-stabilized oil-in-water systems serve nutritional and diagnostic applications with lower purity specifications.
Volume sits with lipid nanoparticles; growth tilts toward liposomes as gene therapy pipelines mature.
End User:
Buyer scale and regulatory sophistication fragment procurement patterns across the customer base.
- Pharmaceutical Companies:Large formulators with approved mRNA products negotiate multi-year offtake agreements specifying dedicated manufacturing slots and co-investment in supplier capacity. FDA compliance documentation requirements compress vendor pools to qualified specialists.
- Biotechnology Firms:Mid-stage developers prioritize custom synthesis flexibility and rapid scale-up timelines over unit cost optimization.
- Academic Institutions:Research-scale procurement emphasizes catalog availability and technical support for protocol development.
- Research Organizations:Government-funded labs drive standardization through reference material programs and collaborative analytical method validation.
Contract value concentrates with pharmaceutical companies; biotechnology firms expand fastest as gene therapy pipelines advance.
Application:
Therapeutic mechanism dictates payload compatibility, release kinetics, and toxicology testing requirements.
- Drug Delivery:PEGylated lipids enable controlled release of small molecules and biologics across oncology, cardiovascular, and CNS indications. Formulators targeting the United States market navigate FDA combination product regulations when device components integrate with lipid-based drug substances.
- Vaccine Development:mRNA and self-amplifying RNA platforms require ionizable lipids combined with PEGylated structural components for endosomal escape. Post-pandemic manufacturing capacity consolidation has shifted procurement power toward established vaccine producers with commercial scale operations.
- Gene Therapy:Non-viral nucleic acid delivery for CRISPR and antisense oligonucleotides specifies distinct lipid compositions from infectious disease applications.
- Cancer Treatment:Tumor-targeted nanoparticles exploit enhanced permeability and retention effects with surface-modified PEG coronas.
Revenue weight rests with vaccine development; gene therapy applications climb the fastest as adeno-associated virus alternatives gain regulatory traction.
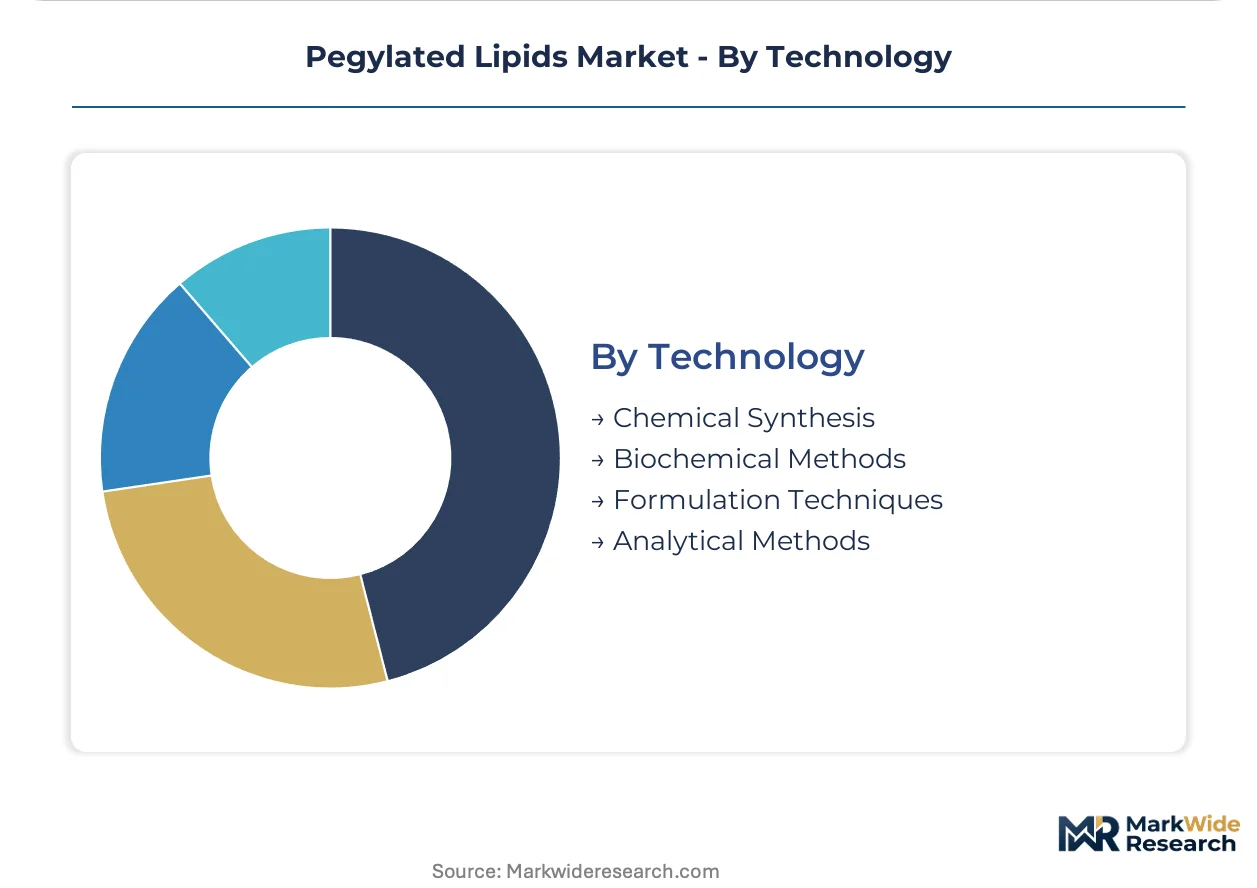
Technology:
Manufacturing methodology determines reproducibility, environmental footprint, and intellectual property exposure.
- Chemical Synthesis:Carbodiimide coupling and click chemistry dominate installed capacity for PEG-lipid conjugation. Petrochemical-derived ethylene oxide feedstock exposes margins to energy price volatility, particularly for European producers facing ETS carbon pricing pressure.
- Biochemical Methods:Enzymatic PEGylation using engineered acyltransferases offers sustainability-aligned alternatives attracting ESG-mandated procurement from biotechnology firms.
- Formulation Techniques:Microfluidic mixing platforms enable precise control over particle size distribution for commercial lipid nanoparticle assembly.
- Analytical Methods:Multi-attribute method validation for molecular weight distribution, lipid chain saturation, and endotoxin levels demands capital-intensive infrastructure.
Installed capacity favors chemical synthesis; biochemical methods gain share fastest as sustainability criteria penetrate supplier selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide feedstock availability clusters polyethylene glycol production near Gulf Coast petrochemical corridors in the United States and Antwerp-Rotterdam chemical hubs in Europe, anchoring pegylated lipid supply chains to these localities.
United States
Messenger RNA vaccine manufacturers in Massachusetts and California biotech corridors drive concentrated procurement volumes for lipid nanoparticle excipients. FDA nucleic acid excipient guidance elevates supplier qualification thresholds, compressing vendor pools to qualified specialists. Greater Boston and San Francisco Bay Area manufacturing clusters negotiate multi-year offtake agreements with dedicated production slots.
Germany
Specialized lipid production capabilities anchor European supply through integrated chemical manufacturing networks. EMA nucleic acid drug substance characterization guidelines mandate stringent lipid impurity threshold scrutiny for marketing authorization holders. Frankfurt-Rhine-Main and Bavarian chemical corridors house contract manufacturing organizations serving gene therapy developers.
China
Domestic PEG supply base and expanding biopharmaceutical manufacturing capacity position Chinese producers to serve regional vaccine developers. NMPA oversight of excipient quality attributes aligns with international standards for nucleic acid therapeutics. Yangtze River Delta biotech clusters absorb investment in lipid nanoparticle formulation infrastructure.
India
CDSCO streamlined excipient registration pathways attract outsourced synthesis from Western pharmaceutical formulators seeking cost-competitive manufacturing. Domestic ethylene glycol production from petrochemical feedstocks supports PEG conjugation chemistry scale-up. Hyderabad and Mumbai-Pune pharmaceutical corridors develop specialized lipid purification capabilities for export markets.
Switzerland
Gene therapy pipelines specifying non-viral nucleic acid delivery create adjacent demand pools for precision PEGylated lipid formulations. Swissmedic regulatory frameworks for advanced therapy medicinal products impose rigorous characterization standards on excipient suppliers. Basel-Zurich biotech corridor concentrates formulation development expertise for clinical-stage developers.
Pegylated Lipids Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biochemical synthesis methods and sustainability-aligned alternatives. The supplier base concentrates around integrated chemical manufacturers with pharmaceutical-grade purification infrastructure and specialized contract manufacturers offering custom synthesis flexibility. Three archetypes dominate: multinational excipient suppliers with dedicated lipid production lines, mid-scale specialists competing on rapid scale-up timelines, and research-scale providers emphasizing catalog breadth for early-stage developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as messenger RNA vaccine developers consolidate procurement power.
Within the integrated multinational tier, Merck KGaA and Evonik Industries AG exemplify archetypes combining broad excipient portfolios with regulatory qualification depth. Avanti Polar Lipids occupies a position among specialized contract manufacturers emphasizing custom synthesis services for biotechnology firms. These three entities represent the competitive spectrum from scale-driven supply security to flexibility-oriented technical partnership.
| Leading Market Players |
|---|
| Merck KGaA |
| NOF Corporation |
| BroadPharm |
| Avanti Polar Lipids |
| Lipoid |
| Jenkem |
| Evonik Industries AG |
| CordenPharma International |
| Creative PEGworks |
| Others |
Pricing and Supply Chain Analysis
Messenger RNA vaccine developers with commercial manufacturing footprints command pricing leverage through multi-year offtake agreements that lock in dedicated production slots and co-investment terms. Pharmaceutical-grade purification capabilities remain scarce relative to demand, compressing margin flexibility for mid-tier suppliers competing on custom synthesis services.
Pricing Analysis
High-volume contract manufacturing separates from research-scale catalog pricing across a three-tier structure anchored in certification grade and volume scale. FDA-qualified suppliers capture premium positioning through nucleic acid excipient compliance documentation, while biotechnology firms face cost compression from ESG-mandated procurement policies favoring biochemical synthesis methods. Price sensitivity concentrates among early-stage gene therapy developers optimizing burn rates, whereas approved vaccine manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Massachusetts and California biotech corridors operate hub-and-spoke patterns feeding lipid nanoparticle formulation suites. Ethylene oxide feedstock draws from Gulf Coast petrochemical corridors in the United States and Antwerp-Rotterdam chemical hubs in Europe, tethering PEG production to energy-price volatility. Single-source vulnerability concentrates in phospholipid purification expertise held by a handful of academic centers and specialized contract manufacturers. Distribution runs through qualified supplier networks with ISO 10993 biocompatibility documentation and USP-NF monograph compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade lipid purification capacity scarcity props pricing power for qualified suppliers, creating durable margin pools for incumbents with regulatory documentation depth.
For Market Incumbents: Anchor long-term supply security through backward integration into ethylene oxide feedstock or captive PEG production capabilities. Incumbents should co-invest with messenger RNA vaccine developers in dedicated manufacturing slots to preempt emerging biochemical synthesis entrants from capturing ESG-mandated procurement volumes. For New Entrants and Emerging Players: Enzymatic PEGylation technology offers a technology-first wedge into sustainability-aligned biotechnology firm procurement policies. New entrants should target Indian contract manufacturing white space, where CDSCO streamlined excipient registration pathways and domestic PEG supply bases enable cost-competitive scale-up without FDA qualification timelines. For Investors and Strategic Acquirers: The window for entry favors specialized contract manufacturers with custom synthesis capabilities and rapid scale-up infrastructure. Acquisition targets should demonstrate phospholipid purification expertise and multi-attribute method validation infrastructure. Watch for EMA-FDA regulatory divergence on lipid impurity thresholds as the signal indicating reformulation investment cycles and dual-filing strategy demands.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated lipid production lines serving Massachusetts and California biotech corridors secure multi-year offtake agreements with mRNA vaccine developers. |
| Backward Integration | Captive ethylene oxide feedstock production insulates margin predictability from Gulf Coast petrochemical price volatility. |
| Green Manufacturing Transition | Enzymatic PEGylation using engineered acyltransferases attracts ESG-mandated procurement from sustainability-focused biotechnology firms. |
| Long-term Supply Agreement | Co-investment structures with pharmaceutical formulators lock in dedicated manufacturing slots and compress supplier qualification timelines. |
| Regulatory Approval Pathway | FDA nucleic acid excipient guidance compliance documentation elevates vendor pools to qualified specialists with USP-NF monograph infrastructure. |
Research Methodology
SEC 10-K filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with lipid synthesis chemists, regulatory affairs leads at excipient suppliers, and procurement managers at messenger RNA vaccine developers combined with FDA guidance document analysis and USP-NF monograph review. Bottom-up triangulation across product type, application, and end-user segments validated top-down demand estimates from pharmaceutical manufacturing capacity announcements.
Historical trendline analysis of lipid nanoparticle excipient procurement volumes informed projection modeling across the analysis window. Segmentation dimensions included formulation architecture, therapeutic modality, manufacturing methodology, and regional regulatory cluster. CAGRs derived from pharmaceutical manufacturing capacity expansion announcements, gene therapy pipeline advancement rates, and biochemical synthesis technology adoption curves. Industry-specific inputs incorporated EMA impurity threshold revision impacts and ISO 10993 harmonization timelines.
Several conditions sit outside the modeled scope, including university-held click chemistry patent litigation outcomes and state-level environmental enforcement actions in Massachusetts or California. Forecasts reflect documented assumptions regarding regulatory convergence and feedstock price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
GLDA Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Pyrrolidone Market