
 5-Hydroxymethylfurfural Market | 2026-2036
5-Hydroxymethylfurfural Market Size, Share, and Industry Trends Forecast 2026-2036
5-Hydroxymethylfurfural Market Analytics
Pharmaceutical-grade HMF purity specifications is rotating the competitive landscape toward higher-margin supply tiers. AVA Biochem AG anchors European production capacity through its Biel facility. Merck KGaA leverages analytical-grade distribution networks to sustain premium positioning. Zhejiang Sugar Energy Technology dominates cost-optimized bio-based output for Asian industrial buyers.
5-Hydroxymethylfurfural is a furan derivative synthesized from hexose dehydration, typically achieving purity thresholds above 99% for pharmaceutical applications through catalytic conversion of fructose or glucose feedstocks. The compound functions primarily as a platform chemical for producing furandicarboxylic acid, bio-based polymers, and pharmaceutical intermediates. Bio-based product type segments command widening margin pools as REACH and EU Green Deal compliance costs penalize synthetic routes. Pharmaceutical application segments lead value concentration due to stringent purity requirements, while biofuels segments compete on feedstock scale rather than specification premiums.
EMA pharmaceutical excipient guidelines, REACH substance registration thresholds, and EU Green Deal bio-based content mandates collectively elevate compliance costs for non-European suppliers. FDA food additive safety assessments and EPA renewable fuel standards create parallel compliance architectures in North America. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and certification investment sequencing.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supply tiers and forcing capital reallocation toward catalytic conversion infrastructure. REACH bio-based mandates and EMA excipient standards are eliminating synthetic-route suppliers from European tender pools.
Growth Catalysts
- EU Green Deal bio-based content mandates:Industrial buyers in Germany and the Netherlands face binding procurement quotas for platform chemicals. HMF qualifies under the EU Taxonomy for sustainable activities, unlocking green financing for production scale-up.
- Furandicarboxylic acid polymerization:PET replacement demand from beverage packaging converters is pulling HMF through the value chain as a FDCA precursor. Polymer producers in Belgium and Spain are qualifying bio-based feedstocks for bottle-grade resin.
- Fructose feedstock optimization:C5-C6 sugar separation advances at Nordic biorefineries are lowering unit conversion costs. Enzymatic dehydration patents filed by Danish technical universities are transferring to pilot-scale demonstration.
Market Restraints
- Glucose isomerization cost volatility:Corn starch and sucrose prices swing with Brazilian harvest cycles and US ethanol policy. Input cost pass-through clauses in long-term supply agreements are tightening margin floors.
- Single-facility European concentration:AVA Biochem's Biel plant accounts for the majority of pharmaceutical-grade nameplate capacity. Contingency planning for force majeure events is absorbing working capital across downstream formulators.
- Cellulosic ethanol substitution:Second-generation biofuel producers are competing for identical C6 sugar feedstocks. Renewable diesel tax credits in the US are diverting biomass streams from chemical applications.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO is harmonizing with ICH Q3C residual solvent guidelines, creating a pathway for imported HMF in generic API manufacturing. Domestic formulators in Hyderabad and Ahmedabad are evaluating bio-based alternatives to petroleum-derived intermediates.
- Continuous flow reactor deployment:Microreactor engineering from Swiss process intensification specialists is enabling distributed production at lower capital intensity. Modular units reduce transport costs for Asian industrial buyers.
- Japan METI carbon neutrality innovation fund:Grants for bio-based platform chemicals are covering 30-50% of demonstration plant costs. Japanese chemical conglomerates are scouting European technology partners for licensed production.
Industry Challenges
- Catalytic chemist talent scarcity:Heterogeneous catalyst design for selective fructose dehydration requires rare expertise at the intersection of carbohydrate chemistry and materials science. European technical universities are struggling to fill industrial research chairs.
- REACH substance registration timeline compression:Full dossier submission for HMF derivatives at tonnage bands above 100 tonnes per annum requires 18-24 month toxicology studies. Registration costs are front-loading before revenue confirmation from offtake agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5-Hydroxymethylfurfural Market |
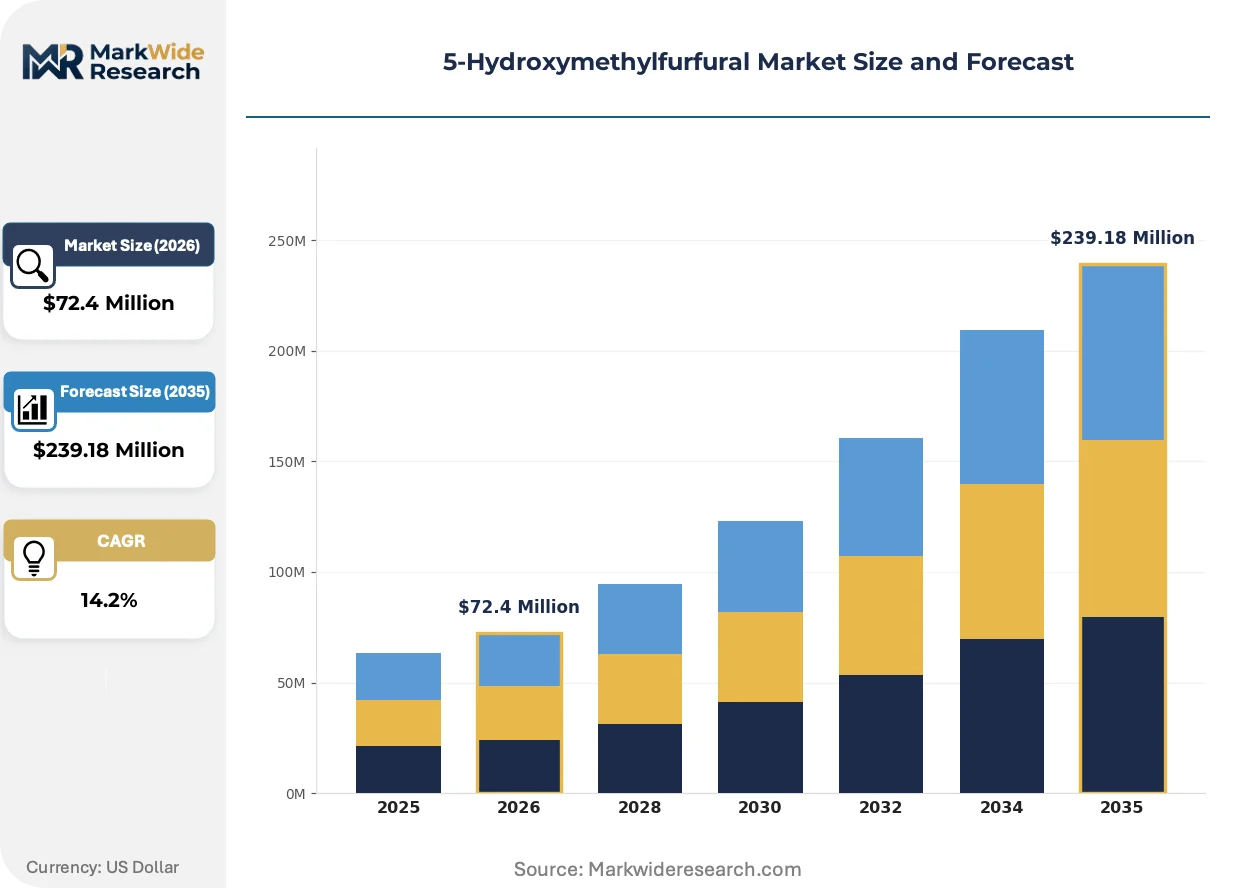
| Market Size in 2026 | $72.4 Million |
| Market Size in 2035 | $239.18 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Bio-based, Industrial Application: Food & Beverage, Pharmaceuticals, Cosmetics, Biofuels End User: Food Manufacturers, Drug Manufacturers, Cosmetic Companies, Research Institutions Distribution Channel: Online Retail, Wholesale, Direct Sales, Others |
| Companies Covered | AVA Biochem AG, Merck KGaA, Robinson Brothers Limited, Zhejiang Sugar Energy Technology Co. Ltd., Xuzhou Ruisai Technology Industrial Co Ltd., Penta Manufacturer, NBB Company, Beijing Lys Chemicals, Wutong Aroma Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5-Hydroxymethylfurfural Market Evolving Landscape
Heterogeneous catalysis and continuous processing are displacing batchwise mineral acid routes, while regulatory carbon accounting is embedding into procurement specifications. These shifts are reconfiguring where value accumulates across the HMF value chain.
Ion-exchange resin catalysts with sulfonic acid functionalization are supplanting homogeneous sulfuric acid systems in fructose dehydration. Specialty chemical producers in Switzerland and Germany are retrofitting fixed-bed reactors to capture yield improvements and eliminate neutralization waste streams. This technology transition is compressing the cost gap between bio-based and fossil-derived platform chemicals.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions reporting for imported chemicals. Downstream polymer processors in Italy and France are demanding cradle-to-gate lifecycle data from HMF suppliers. Bio-based product segments are capturing premium positioning as synthetic routes face shadow carbon pricing in tender evaluations.
Formulators are consolidating supplier relationships around dual-certified partners who maintain both REACH registration and EMA excipient master files. Procurement teams at German and Swiss pharmaceutical manufacturers are reducing qualified vendor lists from twelve to four. This concentration is visible most acutely in parenteral-grade applications where audit fatigue limits multi-sourcing strategies.
5-Hydroxymethylfurfural Market Segmentation
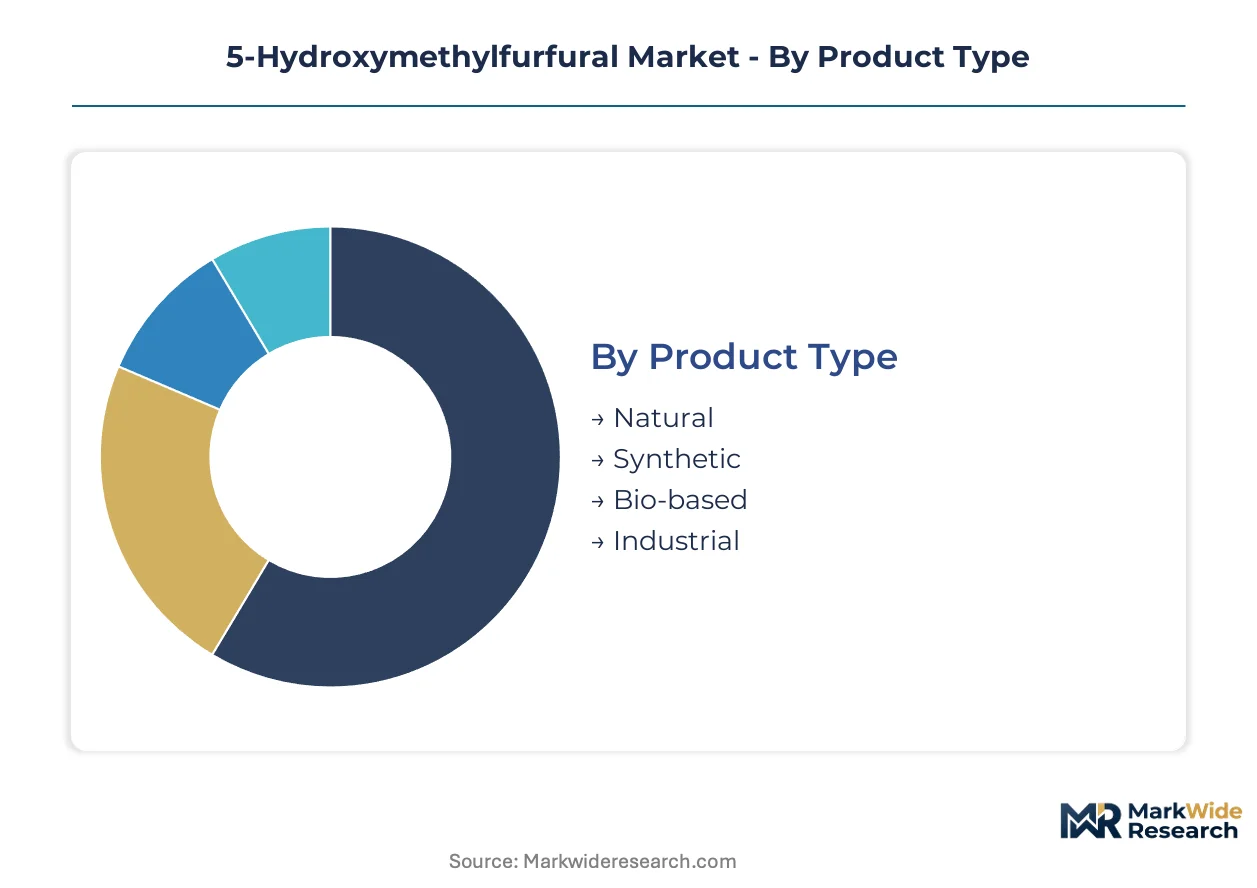
HMF market segmentation reveals how purity grades and regulatory certifications partition value capture across the value chain. Product type and application dimensions show the steepest margin stratification, with pharmaceutical-grade specifications commanding premium positioning over industrial commodity tiers.
Product Type:
Bio-based and natural segments concentrate margin pools where REACH compliance and EMA excipient standards create specification premiums that synthetic routes cannot match.
- Bio-based:Catalytic conversion of fructose or glucose feedstocks achieves purity thresholds above 99% for pharmaceutical applications. Demand concentrates in Germany and Switzerland where AVA Biochem and Merck KGaA serve polymer producers qualifying bio-based feedstocks for bottle-grade resin under EU Green Deal mandates.
- Natural:Hexose dehydration through enzymatic routes without synthetic catalyst residues meets clean-label positioning requirements. Food manufacturers in France and Italy are sourcing natural-grade HMF for caramel color alternatives as EFSA scrutiny tightens on synthetic additives.
- Synthetic:Mineral acid-catalyzed batch production serves industrial solvent and intermediate applications where cost minimization dominates procurement criteria.
- Industrial:Lower-purity grades for bulk chemical processing compete primarily on feedstock scale and logistics optimization rather than certification premiums.
Bio-based holds installed capacity. Natural is rotating up the share rankings.
Application:
Pharmaceutical applications accumulate the widest specification premiums, while biofuels segments compete on feedstock throughput and carbon intensity accounting.
- Pharmaceuticals:Active ingredient precursors and excipient applications require EMA master file documentation and ICH Q3C residual solvent compliance. Parenteral-grade specifications in Germany and Switzerland limit qualified suppliers to dual-certified partners with REACH registration and excipient dossiers.
- Biofuels:FDCA polymerization for PET replacement pulls HMF through the value chain as beverage packaging converters in Belgium and Spain qualify bio-based feedstocks. Polymer producers demand cradle-to-gate lifecycle data under EU carbon border adjustment mechanisms.
- Food & Beverage:Flavor precursor and caramel color applications face EFSA safety assessments and clean-label positioning requirements from retail brand owners.
- Cosmetics:Bio-based platform chemical demand from formulators seeking petroleum-derived intermediate alternatives, particularly in fragrance and active ingredient synthesis.
Pharmaceuticals anchors value concentration. Biofuels is climbing the fastest as polymer offtake agreements accelerate.
End User:
Drug manufacturers concentrate procurement around reduced vendor lists, while research institutions drive pilot-scale demand for novel catalytic process validation.
- Drug Manufacturers:Generic API producers in Hyderabad and Ahmedabad are evaluating bio-based alternatives as CDSCO harmonizes with ICH guidelines, creating import pathways for pharmaceutical-grade HMF.
- Food Manufacturers:Clean-label caramel color and flavor precursor procurement from European retail brand owners demanding EFSA-compliant natural additives.
- Cosmetic Companies:Bio-based active ingredient and fragrance intermediate sourcing from formulators responding to consumer preference shifts.
- Research Institutions:Continuous flow reactor and microreactor engineering validation for distributed production models.
Drug manufacturers hold procurement volume. Research institutions is gaining share fastest through technology licensing partnerships.
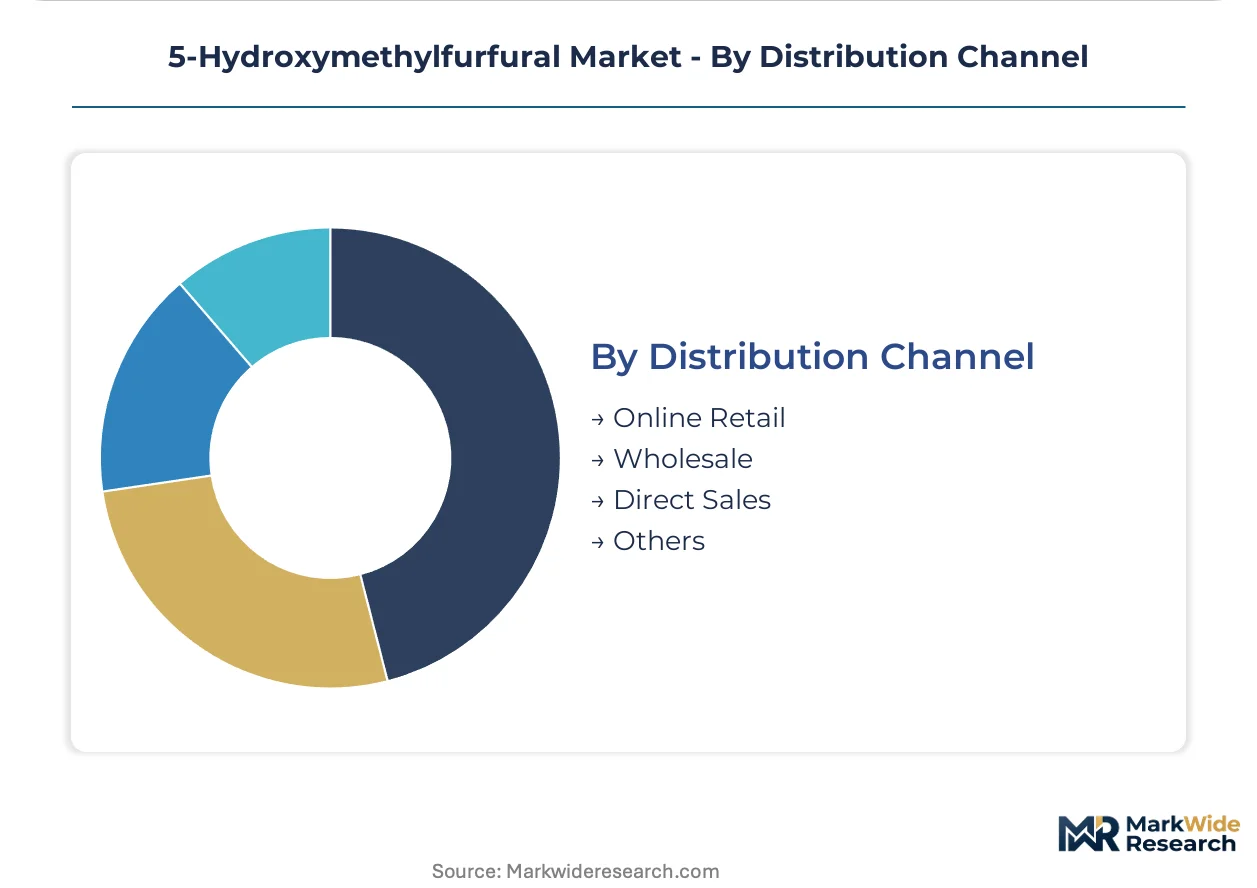
Distribution Channel:
Direct sales concentrate pharmaceutical-grade transactions where audit requirements and master file documentation favor supplier-customer proximity.
- Direct Sales:Pharmaceutical-grade HMF moves through qualified supplier relationships with EMA excipient documentation and REACH registration verification. German and Swiss manufacturers are consolidating around four dual-certified partners.
- Wholesale:Industrial-grade volume distribution for biofuels and bulk chemical applications where specification uniformity permits third-party logistics.
- Online Retail:Research-grade and small-batch procurement for pilot-scale catalytic process development and academic validation studies.
- Others:Specialty chemical distributors serving cosmetic and food ingredient formulators with blended product portfolios.
Direct sales holds contract value. Wholesale is expanding most quickly as biofuels volume scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AVA Biochem's Biel facility in Switzerland concentrates pharmaceutical-grade nameplate capacity, while German polymer producers and Chinese industrial buyers anchor demand at opposite ends of the specification spectrum. Regulatory divergence between REACH jurisdictions and emerging markets is fragmenting procurement strategies across three continents.
Germany
Industrial buyers in the Rhineland and Bavaria face binding bio-based procurement quotas under EU Green Deal mandates. ECHA REACH registration requirements for HMF derivatives above 100 tonnes per annum compress supplier qualification timelines. The Biel facility across the Swiss border ships pharmaceutical-grade output to Frankfurt and Ludwigshafen polymer clusters qualifying bio-based feedstocks for bottle-grade resin.
Switzerland
Swissmedic pharmaceutical excipient standards and EMA master file documentation create dual-certification barriers for imported material. Swiss process intensification specialists in Basel transfer microreactor engineering to Japanese chemical conglomerates through METI carbon neutrality innovation fund partnerships. The Biel production complex anchors European pharmaceutical-grade supply as downstream formulators consolidate vendor lists.
China
Cost-optimized bio-based output from Zhejiang and Jiangsu provinces serves Asian industrial buyers through enzymatic dehydration routes. MIIT dual carbon goals and GB standards for bio-based platform chemicals tighten feedstock compliance requirements for export-oriented producers. The Yangtze River Delta concentrates fructose feedstock optimization research at technical universities transferring patents to pilot-scale demonstration.
India
Generic API producers in Hyderabad and Ahmedabad evaluate bio-based alternatives as CDSCO harmonizes with ICH Q3C residual solvent guidelines. The country's national pharmaceutical regulator creates import pathways for pharmaceutical-grade HMF in excipient applications. Domestic formulators absorb REACH-equivalent compliance costs to qualify for European tender pools.
Japan
METI carbon neutrality innovation fund grants cover demonstration plant costs for licensed European catalytic conversion technology. Japanese chemical conglomerates scout Swiss and German partners for continuous flow reactor deployment. The Kanto and Kansai industrial corridors concentrate polymer offtake agreements pulling HMF through the value chain as FDCA precursors for PET replacement.
5-Hydroxymethylfurfural Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European specialists commanding specification premiums while Asian producers compete on feedstock scale. The market structures around three tiers: dual-certified pharmaceutical-grade suppliers, industrial-scale bio-based producers, and synthetic-route commodity players. Strategic moves concentrate on catalytic conversion infrastructure investment and REACH registration dossier completion.
Within the European specialist tier, AVA Biochem AG and Merck KGaA exemplify dual-certified positioning through EMA excipient documentation and REACH registration. Zhejiang Sugar Energy Technology Co. Ltd. anchors cost-optimized supply for Asian industrial buyers. Robinson Brothers Limited occupies a position bridging pharmaceutical-grade distribution and specialty chemical intermediates.
| Leading Market Players |
|---|
| AVA Biochem AG |
| Merck KGaA |
| Robinson Brothers Limited |
| Zhejiang Sugar Energy Technology Co. Ltd. |
| Xuzhou Ruisai Technology Industrial Co Ltd. |
| Penta Manufacturer |
| NBB Company |
| Beijing Lys Chemicals |
| Wutong Aroma Chemicals |
| Others |
Value Network & Pricing Analysis
Fructose-to-HMF catalytic substitution is redrawing procurement geography as Nordic biorefinery patents transfer to Asian demonstration plants, compressing the cost gap between enzymatic and mineral acid routes while concentrating premium-tier supply around Swiss-German REACH-EMA dual certification.
Pricing Analysis
REACH bio-based content mandates and EMA excipient standards dictate the pricing tier structure across pharmaceutical, industrial, and research-grade segments. Pricing stratifies across pharmaceutical-grade with dual certification, industrial bio-based with single REACH registration, and synthetic commodity tiers competing on feedstock scale. Cost compression in industrial grades is intensifying because Zhejiang producers optimize enzymatic dehydration yields. Generic API manufacturers in India exhibit highest price sensitivity, while German polymer producers absorb premium positioning for cradle-to-gate lifecycle compliance.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade procurement as downstream formulators buffer against AVA Biochem's single-facility concentration, while industrial buyers favor just-in-time fructose feedstock management. Supply concentrates in Switzerland, Germany, and China's Zhejiang province. Catalytic conversion infrastructure draws from Nordic enzymatic patents, Brazilian corn starch cycles, and US ethanol policy swings. Single-source vulnerability at the Biel facility exposes European pharmaceutical formulators to force majeure contingency costs. Distribution runs through direct sales for pharmaceutical-grade with EMA master file documentation, wholesale for industrial biofuels volume, and online retail for research-grade pilot batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for catalytic process optimization and REACH registration consulting are expanding faster than commodity HMF offtake, creating recurring revenue layers that decouple supplier economics from feedstock volatility.
For Market Incumbents: Fortify dual-certified positioning by completing REACH dossier submissions for HMF derivatives above 100 tonnes before tonnage band deadlines compress. Backward integration into fructose feedstock optimization at Nordic biorefineries reduces exposure to Brazilian harvest cycle volatility. Channel control through direct sales relationships with consolidated German vendor lists limits audit fatigue exposure.
For New Entrants and Emerging Players: CDSCO excipient qualification fast-tracks create import pathways into Indian generic API manufacturing as domestic formulators evaluate bio-based alternatives. Target Hyderabad and Ahmedabad pharmaceutical clusters with distributed microreactor deployment to bypass European single-facility concentration. Licensing Swiss continuous flow engineering through METI-funded Japanese partnerships accelerates capital-efficient scale-up.
For Investors and Strategic Acquirers: The market sits at a regulatory compliance phase that favors catalytic technology licensors over commodity producers. Five-to-ten year viability hinges on REACH registration completion and EMA master file maintenance rather than feedstock cost position. Acquisition candidates with heterogeneous catalyst IP and existing dual certification command structural scarcity premiums. Monitor CDSCO-ICH harmonization progress as inflection signal for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fructose Feedstock | Nordic biorefinery partnerships reduce Brazilian corn starch price volatility exposure. |
| REACH Registration Dossier Completion | Full submission for HMF derivatives above 100 tonnes unlocks European tender pool access. |
| Continuous Flow Reactor Deployment | Swiss microreactor engineering licenses lower capital intensity for Asian distributed production. |
| EMA Excipient Master File Maintenance | Dual certification with REACH registration qualifies suppliers for German parenteral-grade procurement. |
| CDSCO Excipient Qualification | Harmonization with ICH Q3C guidelines creates import pathways for Indian generic API manufacturing. |
Research Methodology
Cross-validation between primary interviews with catalytic chemists, pharmaceutical procurement managers, and polymer offtake directors and secondary validation through ECHA REACH registration databases, EU Green Deal taxonomy disclosures, and customs trade data anchors the qualitative findings. Plant managers at Nordic biorefineries, distribution channel partners in Swiss-German pharmaceutical corridors, and technical R&D directors at enzymatic dehydration specialists provided operational perspective. Bottom-up capacity assessments at named production facilities triangulate with top-down demand modeling from polymer and pharmaceutical end-use segments.
Sensitivity analysis around fructose feedstock price volatility, REACH registration timeline compression, and CDSCO regulatory harmonization pace shapes the analytical framework across the projection horizon. Segmentation dimensions include product type grade tier, application end-use industry, and regional regulatory cluster. CAGRs derive from installed capacity expansion schedules, offtake agreement visibility, and substitution elasticity between bio-based and synthetic routes. Catalytic conversion yield improvements and carbon border adjustment mechanism implementation pace serve as key forecast inputs.
Underlying assumptions cover sustained EU Green Deal procurement quota enforcement and EMA excipient standard stability, with deviation risk concentrated in glucose isomerization cost swings and single-facility supply concentration. Forecasts reflect these conditions without scenario weighting. Revision becomes warranted when CDSCO-ICH harmonization crosses implementation thresholds or when second-generation biofuel tax credit diversion exceeds modeled biomass competition intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market