
 North America Chitosan Market | 2026-2036
North America Chitosan Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chitosan Market Intelligence
Market Context
Canadian crustacean processing capacity is realigning toward higher-value chitosan extraction rather than conventional waste disposal. FMC Corporation leverages its agricultural chemical heritage to push chitosan into crop protection formulations. Primex EHF anchors North Atlantic supply chains through its Icelandic marine sourcing operations. KitoZyme S.A. competes on fungal-derived chitosan purity, avoiding seasonal crustacean supply volatility entirely.
Technical Definition and Segment Structure
Chitosan is a linear polysaccharide derived from chitin deacetylation, typically achieving 70-95% deacetylation and molecular weights ranging from 50 to 2,000 kDa, functioning primarily as a bioadhesive, film-forming agent, and antimicrobial barrier across industrial and biomedical applications. Chitosan powder commands the dominant product position due to its storage stability and formulation flexibility in pharmaceutical and agricultural compounding. Waste water treatment applications are expanding fastest among application segments, driven by EPA effluent limits on heavy metal discharge that favor bioflocculant alternatives to synthetic polymers. The healthcare end user segment captures the deepest margin pools, where FDA-regulated medical device and drug delivery applications command premium pricing over commodity food and cosmetic grades.
Regulatory Frame and Outlook
The EPA regulates chitosan-based water treatment additives under FIFRA and TSCA, while the FDA oversees medical and food-grade chitosan through GRAS notifications and device master files, collectively elevating compliance costs but filtering out low-purity competitors. Health Canada and PMRA maintain parallel but non-identical biopolymer registration pathways that create incremental testing burdens for cross-border suppliers. Stakeholders must monitor evolving FDA guidance on chitosan nanoparticle drug delivery systems and EPA biopesticide registration timelines to time capacity investments against regulatory clarity.
Market Dynamics
EPA effluent limits on heavy metal discharge are compressing synthetic polymer use in water treatment, forcing municipal utilities and industrial plants toward bioflocculant alternatives. This regulatory pressure is restructuring supplier relationships and purity requirements across the value chain.
Growth Catalysts
- FDA GRAS pathway expansion:Food-grade chitosan approvals for functional food coatings are opening shelf-stable packaging applications previously blocked by synthetic barrier films.
- Biotech corridor clustering:Boston and San Diego pharmaceutical formulators are scaling chitosan nanoparticle drug delivery matrices for controlled-release oncology therapeutics.
- Crustacean waste valorization:Canadian Atlantic processing facilities are redirecting shell waste from landfill disposal to dedicated chitosan extraction lines.
Market Restraints
- Seasonal raw material volatility:Snow crab and shrimp harvest fluctuations in the Gulf of Maine create input cost instability for crustacean-derived producers.
- Fungal chitosan price premium:KitoZyme's fermentation-based purity advantage commands manufacturing cost multiples that constrain mass-market penetration.
- Deacetylation degree standardization gaps:Inconsistent 70-95% purity specifications across end-use applications force redundant testing and inventory segmentation.
Strategic Opportunities
- Mexican aquaculture waste streams:Pacific coast shrimp farming operations remain untapped for chitosan extraction infrastructure.
- Chitosan-graphene composite membranes:Converging nanomaterial integration is enabling next-generation water filtration with antimicrobial surface properties.
- USDA BioPreferred program procurement:Federal purchasing mandates for biobased products are creating guaranteed offtake channels for agricultural-grade chitosan.
Industry Challenges
- Biopolymer characterization expertise shortage:Analytical chemists capable of validating molecular weight distributions and deacetylation degrees for FDA master files remain scarce in the Great Lakes manufacturing belt.
- Cross-border registration friction:Health Canada and PMRA parallel testing requirements for crop protection formulations impose 18-24 month approval delays versus single-jurisdiction competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chitosan Market |
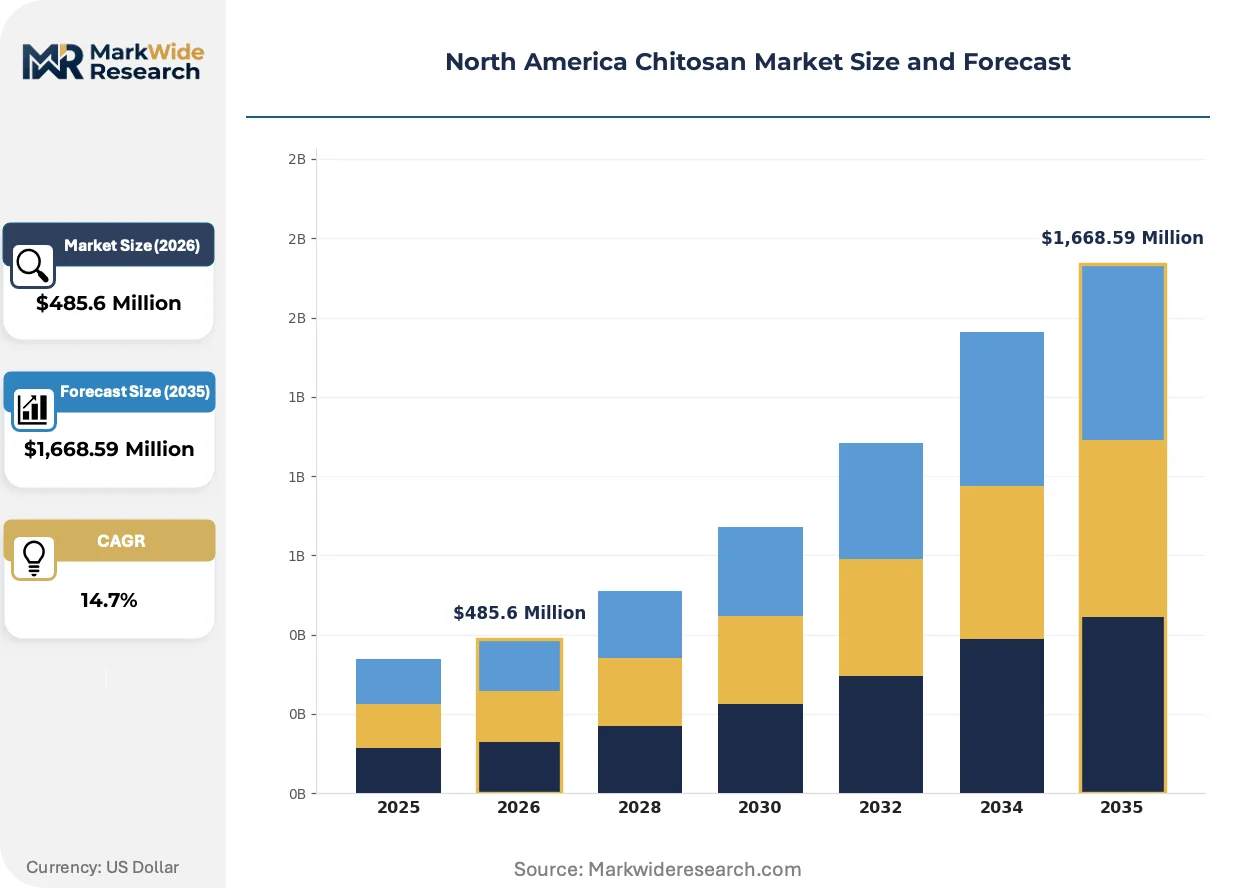
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,668.59 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan Flakes, Chitosan Powder, Chitosan Capsules, Chitosan Solution Application: Food Preservation, Waste Water Treatment, Pharmaceuticals, Agriculture End User: Food Industry, Healthcare, Cosmetic Industry, Agriculture Sector Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Heppe Medical Chitosan GmbH, KitoZyme S.A., FMC Corporation, Primex EHF, Advanced Biopolymers AS, Biophrame Technologies, United Chitotechnologies Inc., Chitogen Inc., GTC Bio Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chitosan Market Strategic Shifts & Innovations
Electrochemical deacetylation methods and enzymatic processing routes are displacing conventional chemical treatments, reducing alkali waste streams while tightening molecular weight control for pharmaceutical specifications.
Enzymatic chitosan production from fungal mycelium is electrifying purity benchmarks in medical device applications. Pharmaceutical formulators in Minnesota and New Jersey are adopting fungal-derived grades at triple-digit annual expansion rates. This biomanufacturing shift is compressing seasonal supply risk premiums previously embedded in crustacean-based contract pricing.
The EPA's 2023 biopesticide registration acceleration framework is compressing review timelines for chitosan-based crop protection formulations. Agricultural chemical distributors are expanding technical service teams to support grower education on biofungicide application protocols. Midwest row-crop operators represent the fastest-adopting buyer segment, driven by glyphosate resistance management mandates.
Direct procurement relationships between pharmaceutical manufacturers and Icelandic marine processors are displacing traditional distributor intermediaries. Large-volume buyers in Massachusetts and California are negotiating multi-year supply agreements with defined purity tiers and molecular weight specifications. This channel restructuring is most advanced in parenteral drug delivery applications where FDA master file consistency requirements favor captive supply arrangements.
North America Chitosan Market Segmentation
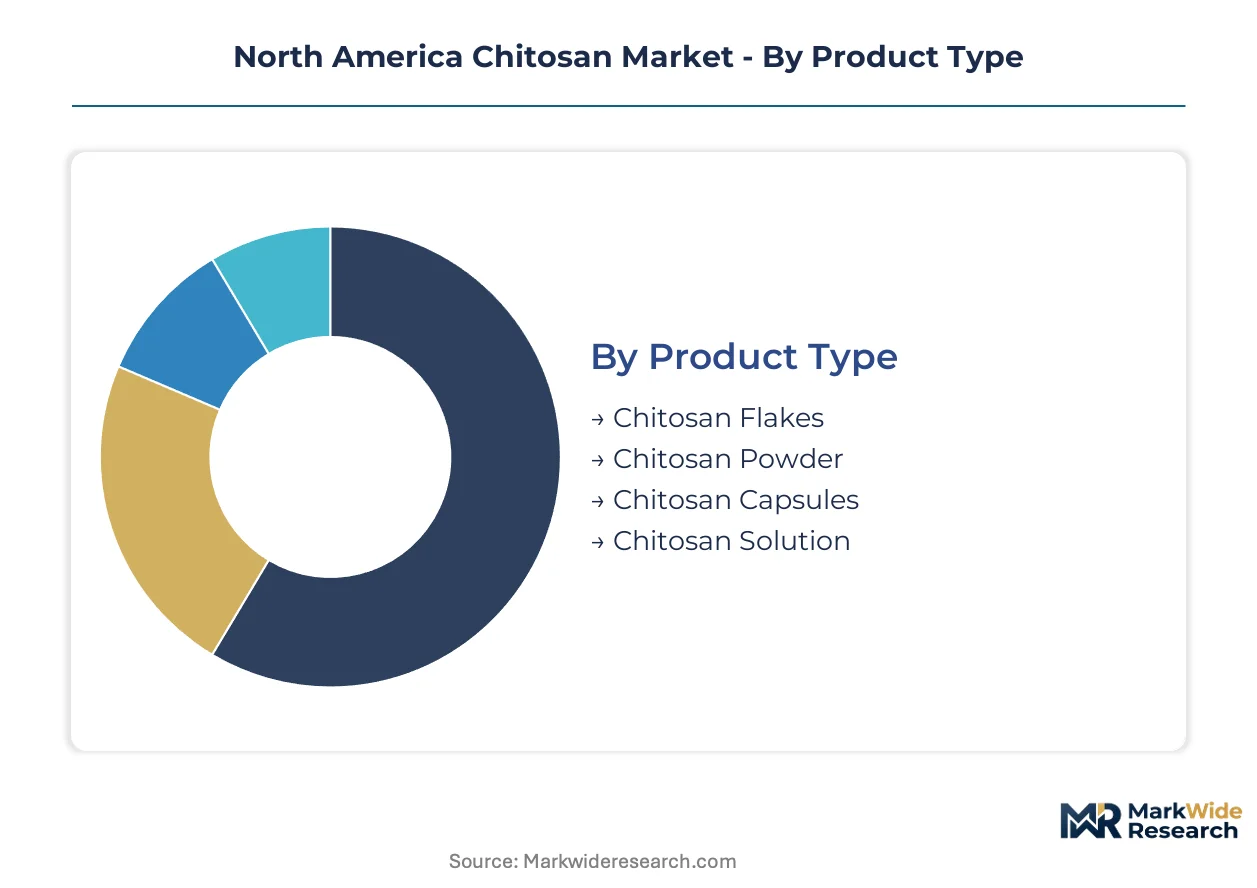
Chitosan segmentation in North America reflects divergent purity requirements across FDA-regulated medical applications and EPA-governed industrial uses. Certification pathways determine margin capture, with pharmaceutical-grade specifications commanding premium positioning over commodity agricultural grades.
Product Type:
FDA GRAS notifications apply to food-grade powders and solutions, while EPA FIFRA registrations govern flakes used in biopesticide formulations. Medical device master files concentrate in powder segments with defined molecular weight distributions.
- Chitosan Powder:Dominant storage-stable format achieving 70-95% deacetylation for pharmaceutical compounding and agricultural formulation. Boston and San Diego biotech corridors concentrate demand for nanoparticle drug delivery matrices with controlled-release specifications.
- Chitosan Solution:Liquid formulation bypasses reconstitution steps in wastewater treatment plants and cosmetic manufacturing. Municipal utilities in the Great Lakes region favor ready-to-dose solutions for heavy metal flocculation under tightening EPA effluent limits.
- Chitosan Flakes:Intermediate processing form preferred by agricultural chemical blenders for slow-dissolution crop protection applications.
- Chitosan Capsules:Pre-metered dosage units serving dietary supplement manufacturers with standardized potency claims.
Leading the category by volume: Chitosan Powder. Growing fastest: Chitosan Solution.
Application:
Cost tier stratification separates premium pharmaceutical applications from volume-driven water treatment and agricultural segments. FDA-regulated uses bear the highest compliance burden per dollar of material consumed.
- Waste Water Treatment:Bioflocculant replacement for synthetic polymers in heavy metal capture. EPA effluent discharge mandates are accelerating municipal adoption across the Great Lakes manufacturing belt and Gulf Coast petrochemical corridors.
- Pharmaceuticals:Drug delivery matrices, wound dressings, and medical device coatings requiring validated molecular weight consistency. Parenteral applications in Massachusetts and California command strictest purity tiers with captive supply arrangements.
- Food Preservation:Edible barrier coatings extending shelf stability for fresh produce and protein products under FDA GRAS pathways.
- Agriculture:Biofungicide and biofertilizer applications regulated under EPA biopesticide frameworks with compressed review timelines.
Expanding most quickly: Waste Water Treatment. Deepest margin capture: Pharmaceuticals.
End User:
Customer type determines procurement pattern, with healthcare buyers negotiating multi-year purity-tiered contracts while agricultural sectors purchase through seasonal distributor networks.
- Healthcare:Hospitals, pharmaceutical manufacturers, and medical device producers requiring FDA master file consistency. Minnesota and New Jersey formulators are adopting fungal-derived grades at accelerated rates to bypass crustacean supply volatility.
- Food Industry:Processors and packaging manufacturers seeking GRAS-certified barrier properties for shelf-stable protein and produce applications.
- Agriculture Sector:Row-crop operators in the Midwest adopting biofungicides for glyphosate resistance management under distributor technical support programs.
- Cosmetic Industry:Formulators leveraging film-forming and antimicrobial properties in personal care products with moderate purity requirements.
Highest volume concentration: Healthcare. Fastest adoption velocity: Agriculture Sector.
Distribution Channel:
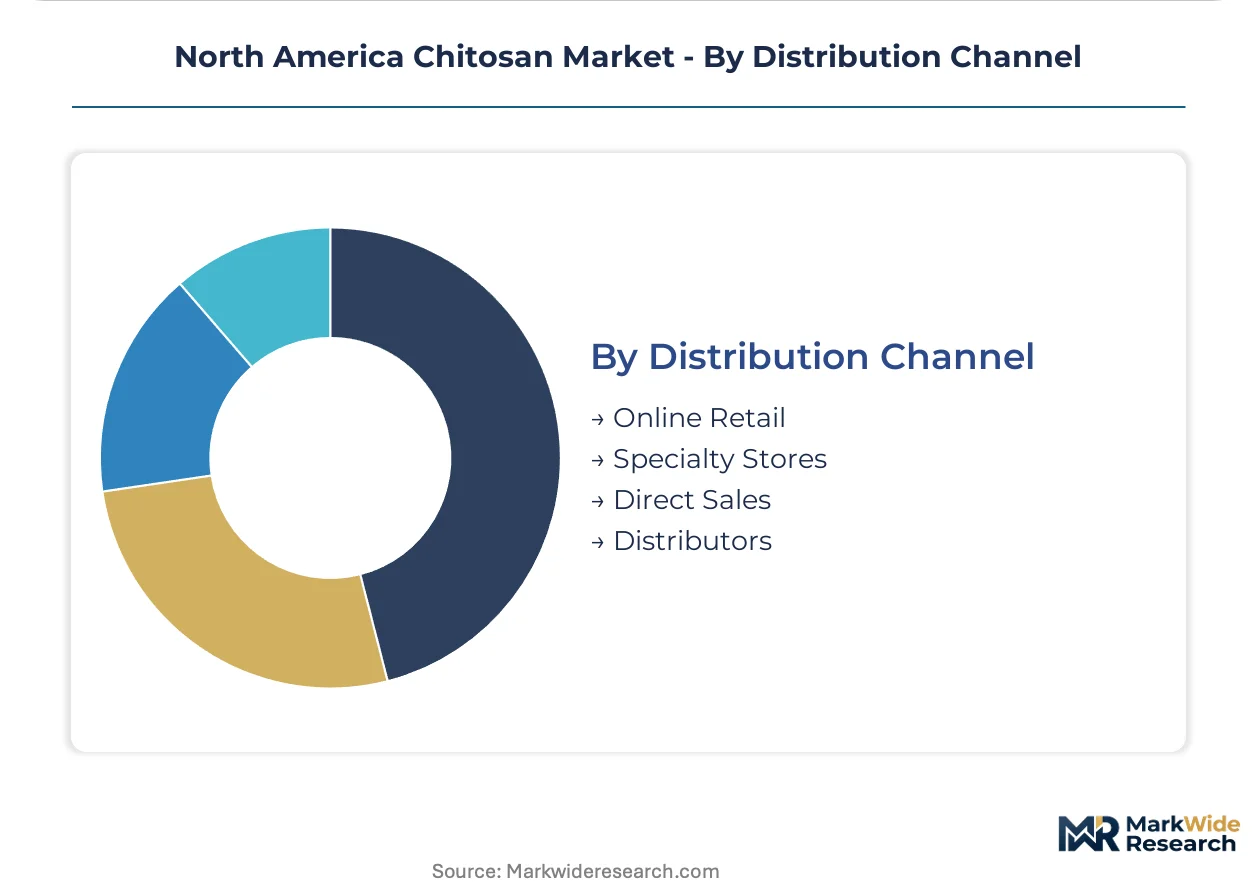
Supply concentration shapes channel selection, with direct procurement displacing intermediaries in high-volume pharmaceutical applications while specialty stores serve fragmented cosmetic and food segments.
- Direct Sales:Multi-year agreements between large-volume pharmaceutical manufacturers and Icelandic marine processors with defined molecular weight specifications. Massachusetts and California buyers lead this channel restructuring.
- Distributors:Agricultural chemical distributors expanding technical service teams for grower education on biopesticide application protocols across Midwest row-crop regions.
- Specialty Stores:Regional suppliers serving cosmetic formulators and small-scale food processors with flexible order quantities.
- Online Retail:E-commerce platforms capturing research-grade and small-volume orders from academic institutions and startup formulators.
Dominant by transaction value: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
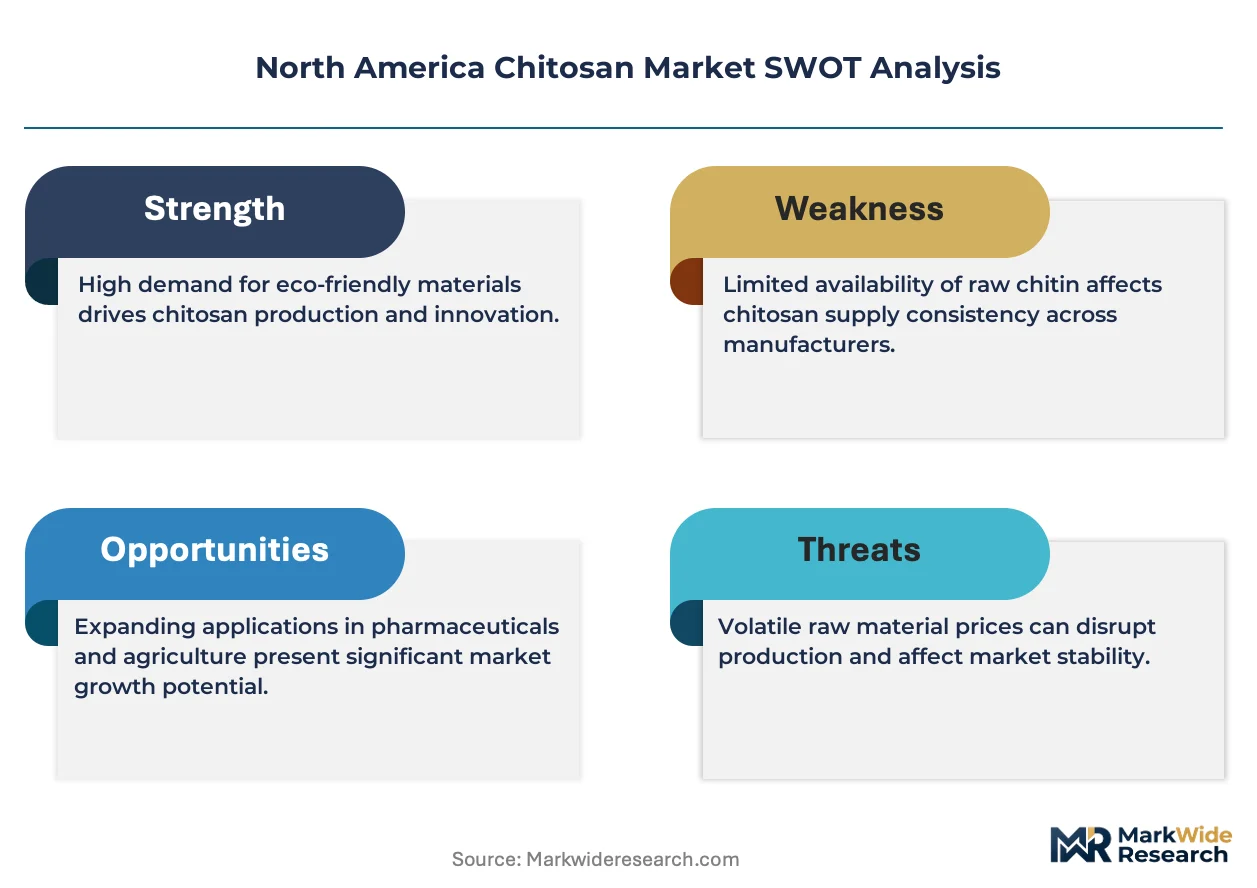
Atlantic crustacean harvesting grounds anchor North American chitosan feedstock availability. Gulf of Maine snow crab operations and Pacific Northwest shrimp processing generate the shell waste streams feeding regional extraction capacity.
United States
Pharmaceutical formulators in Massachusetts and California drive demand for validated molecular weight distributions. FDA master file requirements for parenteral drug delivery applications favor multi-year supply agreements with defined purity tiers. Boston and San Diego biotech corridors concentrate nanoparticle matrix development for controlled-release oncology therapeutics.
Canada
Atlantic processing facilities redirect shell waste from landfill disposal to dedicated chitosan extraction lines. Health Canada and PMRA maintain parallel biopolymer registration pathways that create incremental testing burdens for cross-border suppliers. Quebec and Atlantic Canada crustacean processors realign toward higher-value extraction rather than conventional waste disposal.
Mexico
Pacific coast shrimp farming operations remain untapped for chitosan extraction infrastructure. The national pharmaceutical regulator oversees medical-grade biopolymer imports while environmental agencies govern industrial water treatment applications. Sinaloa and Sonora aquaculture regions hold latent feedstock potential for future processing investment.
North America Chitosan Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue fungal-derived purity advantages and direct pharmaceutical procurement relationships. The supplier base stratifies across crustacean-extraction incumbents, fermentation-based specialists, and agricultural chemical diversifiers. Three archetypes dominate: marine-source extractors with seasonal supply exposure, mycelium-based producers bypassing harvest volatility, and chemical conglomerates leveraging crop protection distribution networks. Capacity expansion and backward integration into raw material sourcing represent the dominant competitive vectors.
Within the fermentation-specialist tier, KitoZyme S.A. exemplifies purity-driven positioning through fungal-derived production. FMC Corporation anchors the agricultural diversification archetype, drawing on crop protection formulation heritage. Primex EHF represents North Atlantic supply chain concentration through Icelandic marine sourcing operations.
| Leading Market Players |
|---|
| Heppe Medical Chitosan GmbH |
| KitoZyme S.A. |
| FMC Corporation |
| Primex EHF |
| Advanced Biopolymers AS |
| Biophrame Technologies |
| United Chitotechnologies Inc. |
| Chitogen Inc. |
| GTC Bio Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned Icelandic marine processors and private-equity-rolled-up crustacean extractors anchor North American chitosan supply, their concentrated ownership patterns enabling multi-year contract discipline with pharmaceutical buyers while buffering spot-market volatility through captive cold-chain infrastructure.
Pricing Analysis
Warranty and technical service bundling separates pharmaceutical-grade contracts from commodity agricultural sales, with FDA master file support and validated molecular weight certificates included in premium tiers but unbundled for standard grades. Three-tier pricing structure across premium, standard, and economy levels reflects deacetylation degree and endotoxin testing rigor. Cost compression in agricultural grades is intensifying because fungal-derived alternatives bypass seasonal supply premiums. Municipal wastewater utilities exhibit highest price sensitivity due to budget-constrained procurement, while parenteral drug manufacturers prioritize purity consistency over unit cost.
Supply Chain Analysis
Freight costs from Icelandic marine operations and Canadian Atlantic processing facilities to Massachusetts and California pharmaceutical corridors represent a material landed-cost component, favoring Great Lakes utilities with shorter haul distances. Supply concentrates in Iceland, Canada, and the United States, with Pacific coast Mexican aquaculture remaining undeveloped. Raw material flows draw from snow crab shell waste, shrimp processing residuals, and fungal mycelium fermentation feedstocks. Single-source vulnerability runs through seasonal crustacean harvest fluctuations in the Gulf of Maine. Distribution runs through direct procurement channels for pharmaceutical volumes and agricultural chemical distributors for crop protection formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American chitosan supply remains structurally constrained by analytical chemist shortages and cross-border registration bottlenecks, propping pricing power for validated producers against commodity-grade competitors.
For Market Incumbents: Lock in multi-year supply agreements with defined molecular weight specifications and purity tiers to preempt fungal-derived substitution threats from KitoZyme-grade competitors. Secure backward integration into Icelandic or Canadian Atlantic crustacean processing capacity to neutralize seasonal raw material volatility. Invest in FDA master file maintenance and electrochemical deacetylation equipment to sustain pharmaceutical-grade margin premiums. For New Entrants and Emerging Players: Electrochemical processing technology offers a wedge against alkali-waste-intensive incumbents, enabling tighter molecular weight control for drug delivery specifications. Target Mexican Pacific coast aquaculture waste streams for greenfield extraction infrastructure, exploiting untapped shrimp farming residuals. Pursue USDA BioPreferred program certification to access federal procurement channels for agricultural-grade volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-based specialists with purity advantages in Minnesota and New Jersey pharmaceutical corridors, where triple-digit adoption rates for fungal-derived grades signal structural demand shift. Long-term viability hinges on regulatory clarity around FDA nanoparticle guidance and EPA biopesticide timelines. Monitor Health Canada-PMRA harmonization progress as inflection signal for cross-border supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crustacean Processing | Captive supply from Icelandic and Canadian Atlantic facilities neutralizes seasonal input volatility. |
| Electrochemical Deacetylation Scale-Up | Alkali waste reduction tightens molecular weight control for FDA-regulated pharmaceutical specifications. |
| FDA Master File Investment | Validated consistency requirements favor parenteral drug delivery applications in Massachusetts corridors. |
| USDA BioPreferred Certification | Federal procurement mandates create guaranteed offtake channels for agricultural-grade chitosan. |
| Cross-Border Registration Harmonization | Health Canada and PMRA alignment would compress approval timelines for crop protection formulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning pharmaceutical formulators, agricultural chemical distributors, municipal wastewater procurement officers, and biomedical engineers. FDA GRAS notifications, EPA FIFRA registrations, and Health Canada biopolymer pathways provided regulatory validation. Bottom-up volume estimates from extraction facility capacity and top-down demand segmentation from end-use applications were triangulated for consistency.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories and purity-tier pricing dynamics. Modeled inputs included crustacean harvest forecasts from Gulf of Maine and North Atlantic fisheries, fungal fermentation capacity expansion plans, and EPA effluent limit enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration or delay in FDA nanoparticle guidance and EPA biopesticide registration frameworks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Atelocollagen Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Hydrogel Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Chitosan Market
Biomaterials
Heparin Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
South America Collagen Market
Biomaterials
Biomaterial in Surgical Mesh Market