
 Polyquaternium 6 Market | 2026-2036
Polyquaternium 6 Market Size, Share, and Industry Trends Forecast 2026-2036
Polyquaternium 6 Market Analytics
Biodegradable cationic polymer synthesis is tilting formulation strategies toward plant-derived feedstocks across personal care supply chains. BASF SE leverages its integrated polymer platform to sustain cost advantages in high-purity grades. Evonik Industries AG anchors its position through specialized quaternization technology for pharmaceutical-grade specifications. Dow Chemical Company competes on manufacturing scale across liquid and emulsion forms for industrial applications.
Polyquaternium 6 denotes a cationic homopolymer of diallyldimethylammonium chloride (DADMAC), typically supplied as a 40% aqueous solution with molecular weights ranging from 100,000 to 500,000 g/mol, functioning primarily as a conditioning agent and film former in rinse-off and leave-on products. Hair Care applications dominate volume consumption due to persistent consumer preference for detangling and anti-static performance in rinse-off conditioners. Cosmetics end use generates premium margin pools as brands demand pharmaceutical-grade certification and low residual monomer content for facial formulations. Liquid form leads shipment volumes while powder variants command higher unit economics in professional salon channels and concentrated industrial blends.
REACH registration requirements in Europe, China's GB/T 13529 standards for cationic surfactants, and FDA cosmetic ingredient safety guidelines collectively elevate compliance costs while restricting non-compliant suppliers from premium market tiers. ECHA substance evaluation protocols are tightening residual DADMAC monomer thresholds, forcing reformulation investments across mid-tier producers. Stakeholders must monitor regulatory divergence between European hazard-classification trends and emerging economy enforcement capacity to align regional product portfolios with diverging compliance landscapes.
Market Dynamics
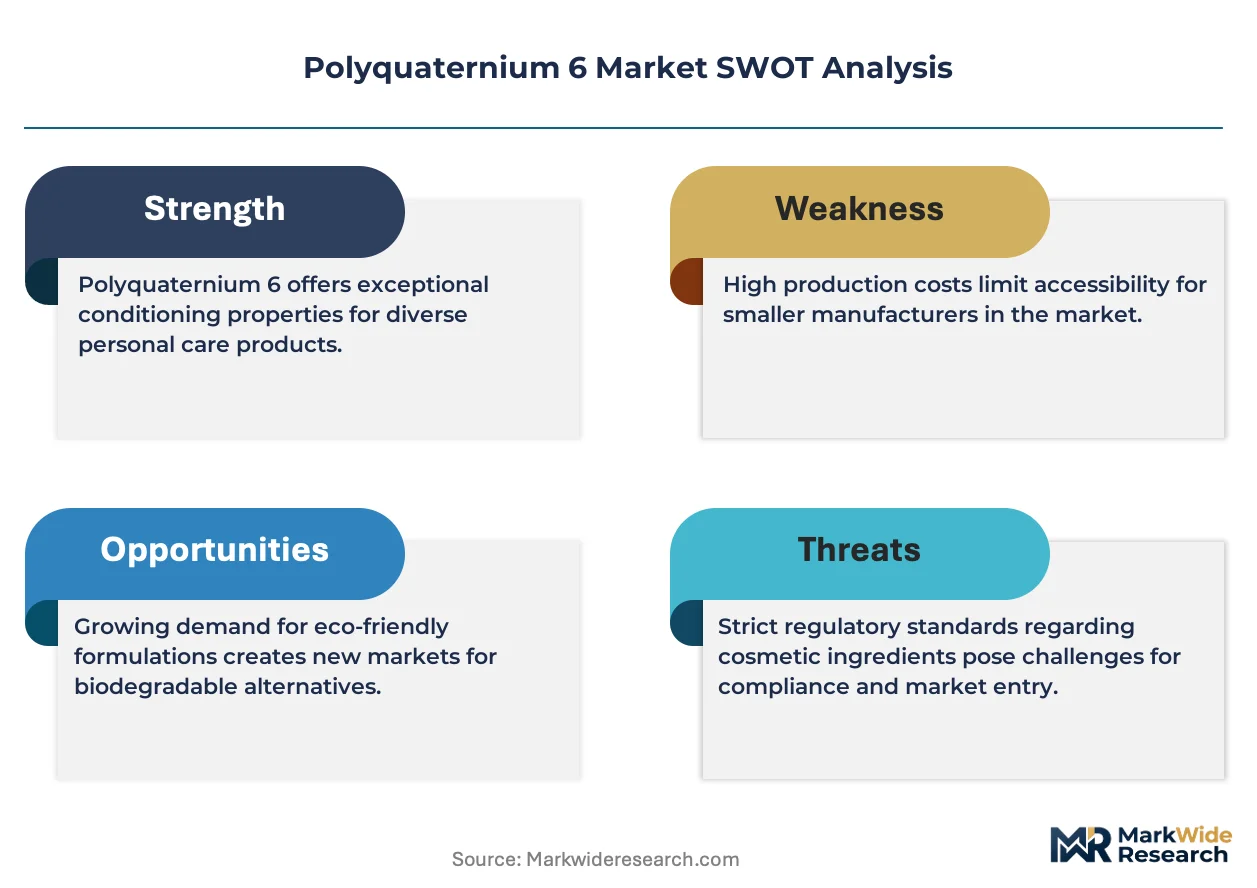
Biodegradable cationic polymer synthesis is redirecting formulation strategies toward plant-derived feedstocks, compressing margins for petrochemical-based producers while rewarding integrated suppliers with captive bio-based raw material streams.
Growth Catalysts
- REACH residual monomer thresholds:ECHA substance evaluation protocols are tightening purity requirements, disqualifying non-compliant suppliers from premium European cosmetic tiers and consolidating demand among certified producers.
- Hair care conditioning expansion:European and Asian hair care brands are broadening quaternized polymer use across rinse-off and leave-on formulations, sustaining volume pull through professional salon and mass retail channels.
- China's GB/T 13529 alignment:Domestic cationic surfactant standards are converging with international purity benchmarks, enabling qualified international suppliers to access pharmaceutical-grade certification pathways.
Market Restraints
- DADMAC feedstock volatility:Allyl chloride and dimethylamine input costs fluctuate with chlor-alkali cycle swings, squeezing margin stability for non-integrated polymer manufacturers.
- German manufacturing concentration:BASF SE and Evonik Industries AG anchor European high-purity supply, creating bottleneck risk for buyers seeking alternative qualified sources.
- Silicone quaternary substitution:Amodimethicone and bis-aminopropyl dimethicone conditioners threaten Polyquaternium 6 share in premium detangling applications where sensory performance dominates.
Strategic Opportunities
- India personal care penetration:CDSCO cosmetic ingredient registration pathways are streamlining, opening access for compliant suppliers to serve underdeveloped regional formulator networks.
- Pharmaceutical-grade certification:Low residual monomer specifications for facial and ocular formulations command 40-60% unit premiums over standard industrial grades.
- Bio-based DADMAC feedstocks:Fermentation-derived dimethylamine and bio-allyl alcohol convergence is enabling mass-balance certified polymer lines for clean beauty positioning.
Industry Challenges
- Quaternization process expertise:Specialized reactor design and reaction control capabilities constrain qualified production capacity expansion, limiting new entrant participation.
- Multi-jurisdiction dossier maintenance:Parallel REACH, FDA cosmetic ingredient, and China NMPA filing requirements impose sustained regulatory affairs overhead on mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyquaternium 6 Market |
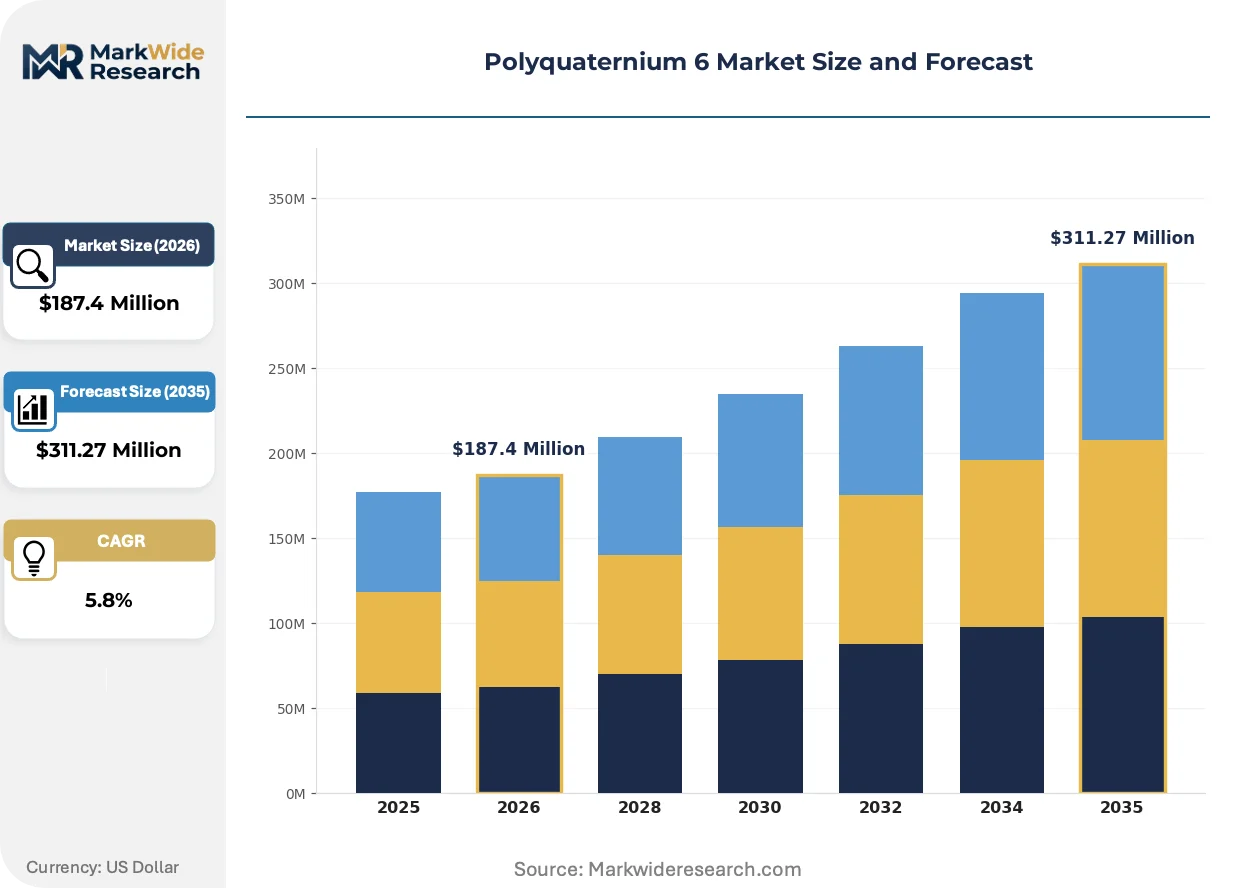
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Hair Care, Skin Care, Fabric Care, Personal Care Product Type: Conditioners, Shampoos, Creams, Gels End Use Industry: Cosmetics, Pharmaceuticals, Household, Industrial Form: Liquid, Powder, Gel, Emulsion |
| Companies Covered | Lubrizol Corporation, Solvay, BASF SE, Evonik Industries AG, Ashland Global Holdings Inc., Trulux, IRO Group, Clariant, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyquaternium 6 Market Evolving Landscape
Formulation science advances and regulatory tightening are compressing the viable technology set while rewarding suppliers with integrated bio-based platforms and pharmaceutical-grade certification capabilities.
Enzymatic quaternization pathways are replacing conventional acid-catalyzed processes in pilot-scale production. Specialty chemical producers in Germany and the Netherlands are scaling these routes to reduce energy intensity and residual monomer formation. The technology is rendering obsolete traditional high-temperature quaternization reactors for premium cosmetic grades.
EU Green Deal chemical sustainability criteria are extending to cationic polymer feedstock provenance. ECHA is evaluating mass-balance accounting methodologies for bio-based content claims, forcing reformulation investments across suppliers dependent on fossil-derived DADMAC. Hair care brands with European manufacturing footprints are accelerating supplier audits to pre-empt compliance gaps.
Direct procurement from polymer manufacturers is displacing distributor intermediaries among large personal care formulators. Unilever and L'Oréal procurement teams are consolidating qualified supplier lists and negotiating multi-year offtake agreements with integrated producers. This pattern is most visible in Germany and France, where concentration of cosmetic headquarters enables supplier rationalization.
Polyquaternium 6 Market Segmentation
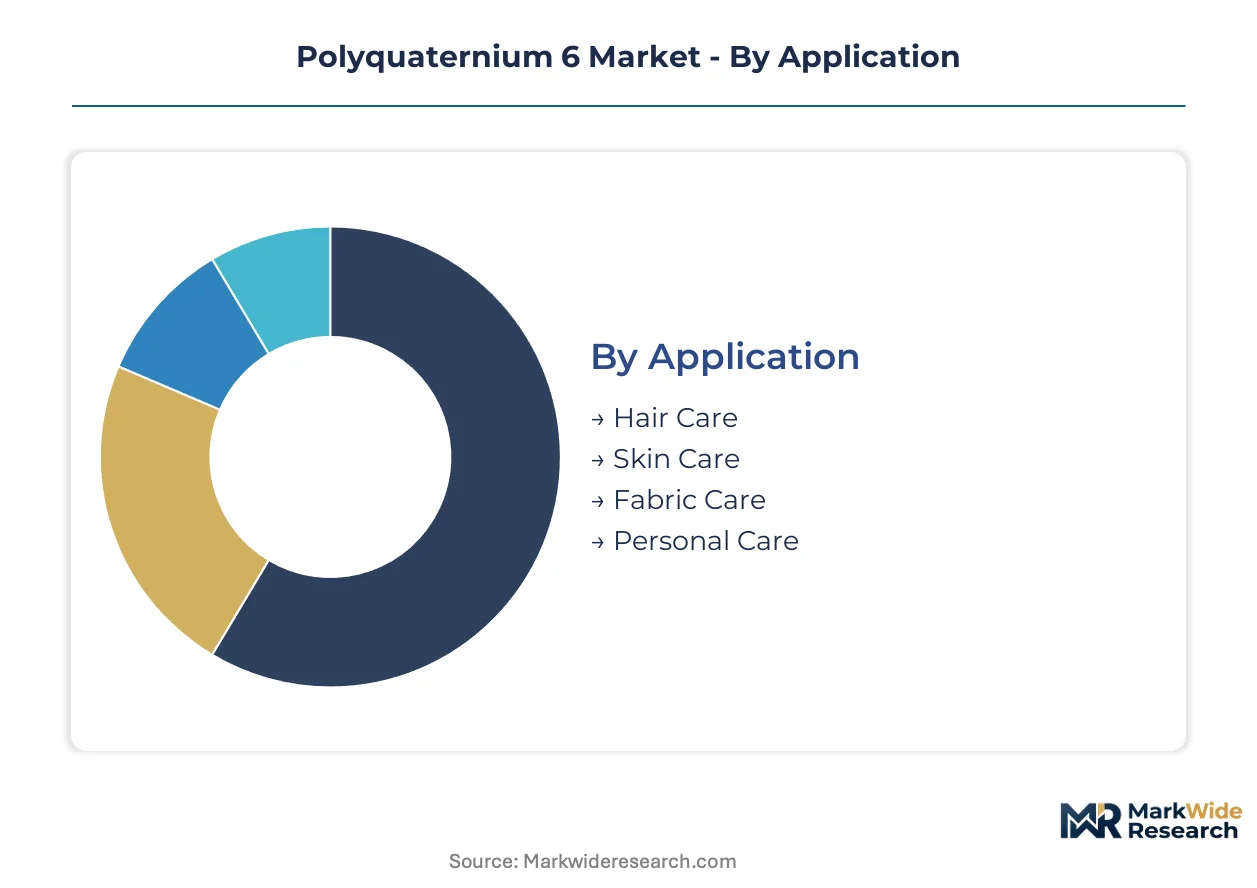
Polyquaternium 6 formulations diverge sharply across conditioning intensity requirements, regulatory compliance tiers, and manufacturing scale economics. Understanding these segment boundaries enables suppliers to align purification investments with margin capture potential.
Application:
Conditioning performance demands span rinse-off durability through leave-on film persistence, creating distinct specification thresholds.
- Hair Care:Rinse-off conditioners and detangling sprays require molecular weights between 100,000-300,000 g/mol for optimal deposition without buildup. German and Chinese formulators dominate volume procurement for mass-market and professional salon lines.
- Skin Care:Facial moisturizers and body lotions demand sub-50 ppm residual DADMAC monomer to meet pharmaceutical-grade certification. Premium margin pools concentrate in French and Japanese cosmetic headquarters where ocular safety testing is mandatory.
- Fabric Care:Laundry softeners exploit cationic charge density for fiber lubrication.
- Personal Care:Deodorants and shaving preparations utilize anti-static film formation.
The dominant share belongs to Hair Care, while Skin Care is closing the gap fastest on certification premium capture.
Product Type:
Formulation viscosity and delivery mechanism dictate polymer concentration and compatibility requirements.
- Conditioners:Rinse-off formulations represent the highest volume consumption, with cationic polymer loading at 0.5-2.0% active content. Asian hair care brands in South Korea and Thailand are expanding quaternized polymer use across treatment and mask segments.
- Shampoos:Secondary conditioning in cleansing bases requires anionic compatibility strategies. Brazilian and Mexican formulators drive Latin American volume through mass-market 2-in-1 positioning.
- Creams:Leave-on skin conditioning demands low-irritation specifications.
- Gels:Clear formulations require specific molecular weight distribution for optical clarity.
Conditioners maintain volume leadership, though Shampoos are expanding most quickly through emerging market 2-in-1 adoption.
End Use Industry:
Regulatory stringency and certification depth separate margin tiers across industrial classifications.
- Cosmetics:Facial and premium body formulations command pharmaceutical-grade certification with 40-60% unit premiums over industrial grades. REACH-registered suppliers in Germany and the Netherlands capture disproportionate share in European clean beauty lines.
- Pharmaceuticals:Ocular and wound care applications impose the strictest residual monomer thresholds. Swiss and Japanese pharmaceutical manufacturers source exclusively from dedicated GMP-certified polymer facilities.
- Household:Fabric softeners and surface cleaners tolerate higher monomer content for cost efficiency.
- Industrial:Water treatment and paper processing applications prioritize charge density over purity.
Cosmetics holds the revenue concentration, with Pharmaceuticals climbing fastest on therapeutic-grade certification expansion.
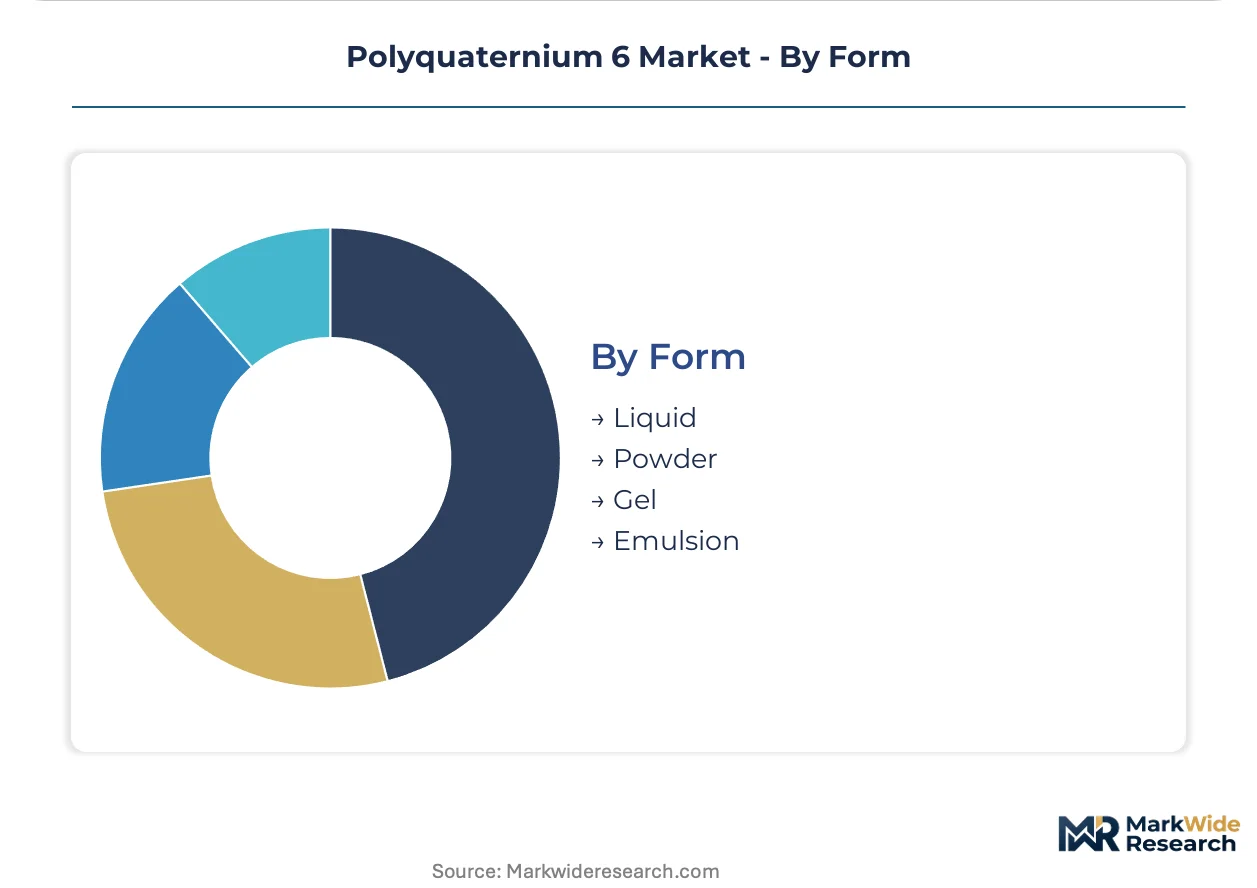
Form:
Physical state determines logistics economics, shelf stability, and formulation integration protocols.
- Liquid:40% aqueous solution dominates shipment volumes for ease of handling and direct incorporation. Dow Chemical and BASF manufacturing sites in the United States and Germany supply bulk tanker quantities to large personal care formulators.
- Powder:Spray-dried variants enable concentrated industrial blends and professional salon powders. Italian and Spanish distributors serve Mediterranean cosmetic compounders seeking reduced transport costs.
- Gel:Pre-thickened systems simplify formulator processing.
- Emulsion:Oil-in-water dispersions target specific sensory requirements.
Liquid commands absolute volume share, yet Powder is gaining ground fastest through professional channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polymer manufacturers export high-purity grades to French and Japanese cosmetic formulators, establishing the dominant trade-flow corridor for pharmaceutical-certified material.
United States
Dow Chemical's manufacturing scale anchors industrial-grade supply for fabric softener and water treatment applications. FDA cosmetic ingredient safety guidelines govern residual monomer thresholds for leave-on skin formulations. Houston and Freeport petrochemical clusters concentrate cationic polymer production alongside captive DADMAC feedstock supply.
Germany
BASF SE and Evonik Industries AG dominate European pharmaceutical-grade certification through integrated polymer platforms. REACH registration requirements and ECHA substance evaluation protocols enforce sub-50 ppm residual DADMAP purity standards. Ludwigshafen and Marl chemical parks concentrate quaternization expertise for premium cosmetic supply.
China
Domestic hair care brands in Shanghai and Guangzhou drive volume consumption for rinse-off conditioning formulations. GB/T 13529 standards for cationic surfactants align with international purity benchmarks, streamlining NMPA cosmetic ingredient registration. Yangtze River Delta chemical manufacturers scale aqueous solution output for Asian personal care supply chains.
India
CDSCO cosmetic ingredient registration pathways are streamlining access for compliant international suppliers. Maharashtra and Gujarat personal care formulators expand quaternized polymer use in emerging mass-market shampoo segments. Mumbai-Pune industrial corridor concentrates contract manufacturing for regional hair care brands.
Japan
PMDA pharmaceutical-grade specifications govern ocular and wound care applications with strictest residual monomer thresholds. Osaka and Tokyo cosmetic headquarters source exclusively from dedicated GMP-certified polymer facilities. Kansai region formulators command premium positioning through sensory performance requirements in professional salon channels.
Polyquaternium 6 Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive feedstock positions and specialized quaternization capabilities. Mid-tier producers face margin compression from regulatory compliance investments while premium tiers reward pharmaceutical-grade certification. Three strategic archetypes dominate: integrated petrochemical majors with backward DADMAC control, specialty polymer houses with quaternization expertise, and regional distributors serving compounder networks. Capacity expansion and portfolio diversification toward bio-based feedstocks represent the dominant competitive moves.
Among German-based integrated suppliers, BASF SE and Evonik Industries AG exemplify the premium-tier archetype through REACH-registered pharmaceutical-grade platforms. Dow Chemical Company occupies the scale-driven position for industrial and mass-market cosmetic applications. Lubrizol Corporation and Solvay sit within the specialty chemical tier, leveraging formulation science capabilities to serve brand-direct procurement channels.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Solvay |
| BASF SE |
| Evonik Industries AG |
| Ashland Global Holdings Inc. |
| Trulux |
| IRO Group |
| Clariant |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors carry DADMAC feedstock and finished aqueous solutions between German polymer hubs and French cosmetic formulators, with tariff-adjusted logistics costs compressing margins for non-integrated distributors while amplifying pricing power for producers with captive Rhine-Ruhr manufacturing footprints.
Pricing Analysis
Enzymatic quaternization technology commands 25-35% premiums over conventional acid-catalyzed grades, while legacy high-temperature reactor output faces margin erosion from energy intensity penalties and residual monomer disqualification. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates certification depth, with REACH-registered German producers capturing premium tiers. Cost compression in industrial grades intensifies because Chinese Yangtze River Delta manufacturers scale aqueous solution output. Mass-market hair care formulators in Brazil and Mexico exhibit highest price sensitivity, while Swiss and Japanese pharmaceutical manufacturers show lowest elasticity due to GMP certification requirements.
Supply Chain Analysis
Export-control restrictions on specialized quaternization reactor technology limit capacity expansion licensing from German and Dutch engineering firms to non-EU destinations, constraining qualified production growth outside integrated chemical parks. Supply concentrates in Germany, China, and the United States, with Ludwigshafen, Shanghai, and Houston anchoring regional output. Allyl chloride and dimethylamine feedstocks draw from chlor-alkali cycle production in the US Gulf Coast and European chemical parks. Single-source vulnerability runs through German pharmaceutical-grade certification capacity, where BASF SE and Evonik Industries AG control REACH-registered supply. Distribution runs through direct procurement agreements with large personal care formulators displacing distributor intermediaries in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment creates durable barriers: ECHA substance evaluation protocols and REACH registration requirements impose sunk-cost burdens that new entrants cannot replicate without multi-year compliance investments.
For Market Incumbents: Harden pharmaceutical-grade certification depth by expanding GMP-capable reactor capacity in Marl and Ludwigshafen chemical parks to preempt Swiss and Japanese pharmaceutical demand growth. Deepen backward integration into bio-based DADMAC feedstocks through fermentation-derived dimethylamine partnerships, defending against silicone quaternary substitution threats in premium detangling applications.
For New Entrants and Emerging Players: Pursue CDSCO-registered supply to Maharashtra and Gujarat personal care formulators, where streamlined cosmetic ingredient registration creates accessible white space. Target India's underdeveloped professional salon channel with powder-form Polyquaternium 6 for concentrated treatment masks, leveraging Italian distributor relationships for Mediterranean market entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier European specialty chemical houses with REACH-registered assets but lacking integrated DADMAC feedstock positions. Five-to-ten-year viability favors producers with mass-balance certified bio-based lines aligned to EU Green Deal chemical sustainability criteria. Watch ECHA mass-balance accounting methodology rulings as inflection signal for feedstock provenance premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based DADMAC | Fermentation-derived dimethylamine partnerships secure mass-balance certification for clean beauty positioning. |
| GMP-Capable Reactor Capacity Expansion | Dedicated pharmaceutical-grade facilities capture 40-60% unit premiums from Swiss and Japanese ocular formulation demand. |
| Long-Term Offtake Agreements with Formulators | Unilever and L'Oréal procurement consolidation rewards qualified suppliers with volume visibility and reduced distributor costs. |
| Joint Venture with Indian CDSCO-Registered Compounders | Mumbai-Pune corridor access penetrates underdeveloped mass-market shampoo segments with localized aqueous solution supply. |
| Green Manufacturing Transition Certification | EU Green Deal alignment preempts ECHA feedstock provenance audits for European hair care brand supplier qualification. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with polymer plant managers, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA substance evaluation dossiers. Bottom-up volume estimates from grade-tier production capacities triangulated against top-down demand modeling from end-use industry consumption patterns.
Forecast inputs span grade tier, end-use industry, physical form, and regional production hub segmentation across the projection horizon. CAGRs derive from regression analysis of historical volume-price relationships, with pharmaceutical-grade certification premiums and bio-based feedstock conversion rates as industry-specific demand elasticity drivers. Modeled outputs reflect capacity utilization assumptions at German, Chinese, and US manufacturing clusters.
Sensitivities concentrate around ECHA residual monomer threshold revisions, chlor-alkali cycle input cost volatility, and silicone quaternary substitution rates in premium conditioning applications. Forecasts reflect documented assumptions on regulatory enforcement capacity divergence between European and emerging economy markets. Material shifts in EU Green Deal chemical sustainability criteria implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Myrcene Market