

4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market Size, Share, and Industry Trends Forecast 2026-2036
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market Insights
A shift from single-source to multi-source procurement is repositioning how specialty chemical buyers secure 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid supply. BASF SE leverages its integrated sulfone chemistry platform to control raw material flows from upstream sulfur derivatives. Merck KGaA sustains laboratory-grade dominance through stringent purity protocols that exceed standard industrial specifications. TCI Chemicals anchors Asian distribution networks with localized synthesis capabilities and rapid custom synthesis turnaround.
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid is a cyclic sulfone ester featuring a propyl substituent at the 4-position of the dioxathiolane ring, synthesized via sulfonation of corresponding diol precursors followed by oxidation to the dioxide form. The compound functions primarily as a reactive diluent and viscosity modifier in high-performance adhesive formulations and as a process solvent in specialty polymerization reactions. Pharmaceutical-grade material commands premium positioning due to stringent impurity profiles required for active pharmaceutical intermediate applications, while technical-grade supply serves volume-driven coatings and sealants segments where cost efficiency outweighs ultra-high purity demands. Monomer-grade product leads current revenue contribution, though polymer-bound stabilizer forms are gaining traction in electronics packaging applications requiring thermal stability above standard industrial thresholds.
EPA industrial chemical oversight and REACH substance registration in Europe impose divergent testing burdens on manufacturers seeking cross-border market access. BIS certification requirements in India add a third compliance layer for suppliers targeting pharmaceutical contract manufacturing demand. Stakeholders must monitor evolving hazard classification updates across these jurisdictions, as reclassification would trigger reformulation costs and customer qualification timelines that extend well beyond typical procurement cycles.
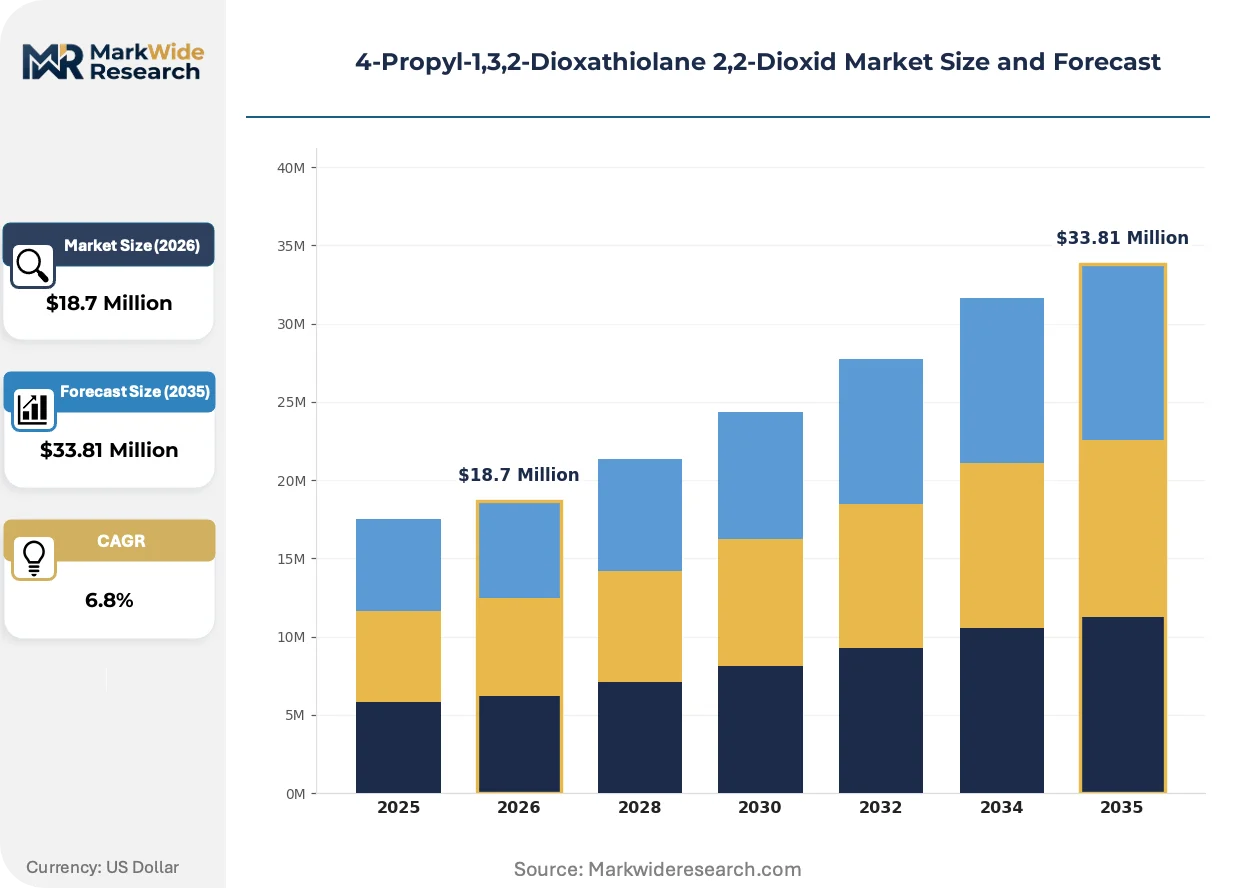
Market Dynamics
REACH compliance deadlines and EPA industrial chemical oversight are compressing qualification timelines for 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid suppliers, forcing simultaneous investment in purity upgrades and multi-source procurement infrastructure.
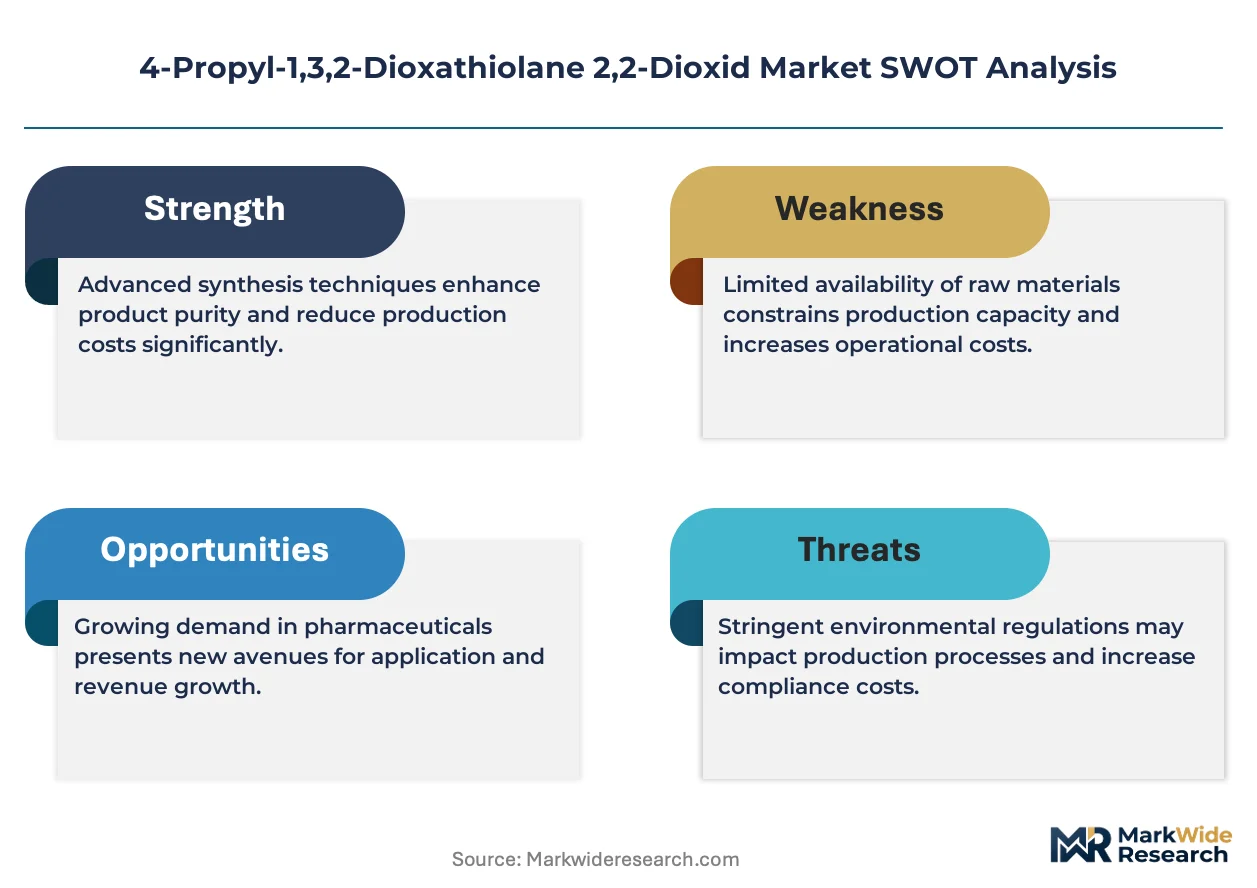
Growth Catalysts
- Adhesives sector expansion:Electronics packaging manufacturers in Germany are scaling high-performance adhesive formulations that require sulfone-derived reactive diluents for thermal stability above standard thresholds.
- REACH substance registration:European regulatory clarity on cyclic sulfone esters is enabling qualified suppliers to secure long-term supply contracts with coatings producers seeking compliant material streams.
- Pharmaceutical-grade demand:Active pharmaceutical intermediate applications are pulling ultra-high purity monomer grades as CDSCO-aligned contract manufacturers in India expand sulfone chemistry capabilities.
Market Restraints
- Sulfur derivative input volatility:Upstream sulfur chemistry supply fluctuations create margin pressure for producers lacking backward integration into diol precursor synthesis.
- Supplier concentration risk:Technical-grade material production clusters in select Chinese chemical parks, exposing buyers to localized environmental enforcement disruptions.
- Substitution by bio-based diluents:Renewable glycerol carbonate formulations are displacing cyclic sulfone esters in cost-sensitive sealants segments where thermal performance requirements are moderate.
Strategic Opportunities
- India pharmaceutical manufacturing:BIS certification pathways for imported sulfone derivatives remain underdeveloped, creating first-mover positioning for compliant suppliers targeting CDSCO-registered API producers.
- Polymer-bound stabilizer forms:Electronics packaging applications above standard industrial thermal thresholds are opening demand for covalently bound stabilizer architectures.
- Dual carbon alignment:China's MEE enforcement of carbon intensity metrics is incentivizing domestic producers to adopt oxidation process improvements that reduce energy consumption per ton.
Industry Challenges
- Sulfonation process expertise scarcity:Specialized operators capable of managing diol-to-dioxide oxidation with consistent impurity control are concentrated among legacy sulfone chemistry specialists.
- Cross-jurisdiction qualification timelines:Simultaneous EPA pre-manufacture notification and REACH registration dossier preparation extends customer approval cycles beyond standard procurement planning horizons.
- Legacy formulation integration:Adhesive producers with established epoxy-amine cure systems face reformulation complexity when incorporating cyclic sulfone esters as viscosity modifiers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market Trends and Innovations
Continuous flow sulfonation reactor technology is displacing batch oxidation processes, enabling real-time impurity monitoring that aligns with tightening pharmaceutical-grade specifications while compressing cycle times for technical-grade production.
Continuous flow reactor architecture is integrating into commercial-scale 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid synthesis, replacing conventional batch sulfonation with segmented flow oxidation that enables precise temperature control. Specialty chemical manufacturers serving pharmaceutical contract manufacturing organizations are adopting this platform fastest, driven by lot-to-lot consistency requirements. The technology is integrating upstream purification steps previously handled as separate unit operations, collapsing capital intensity for new market entrants.
REACH Annex XVII restrictions on persistent organic pollutant precursors are tightening substance evaluation criteria for sulfone derivatives used in consumer-facing coatings applications. Industrial-grade suppliers face expanded testing burdens for ecotoxicological endpoints previously exempted under grandfathered registrations. German coatings producers are responding by segregating supply chains between pharmaceutical-intermediate and technical-grade material streams to prevent cross-contamination liability.
Multi-year offtake agreements are replacing spot market purchasing for monomer-grade material as electronics packaging manufacturers lock in supply security for thermal stabilizer formulations. Distributors with captive synthesis capabilities in Asia are capturing margin previously held by trading houses, compressing channel layers between producer and formulator. This restructuring is most visible in China, where localized custom synthesis turnaround has become a competitive discriminator for adhesive sector procurement teams.
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market Segmentation
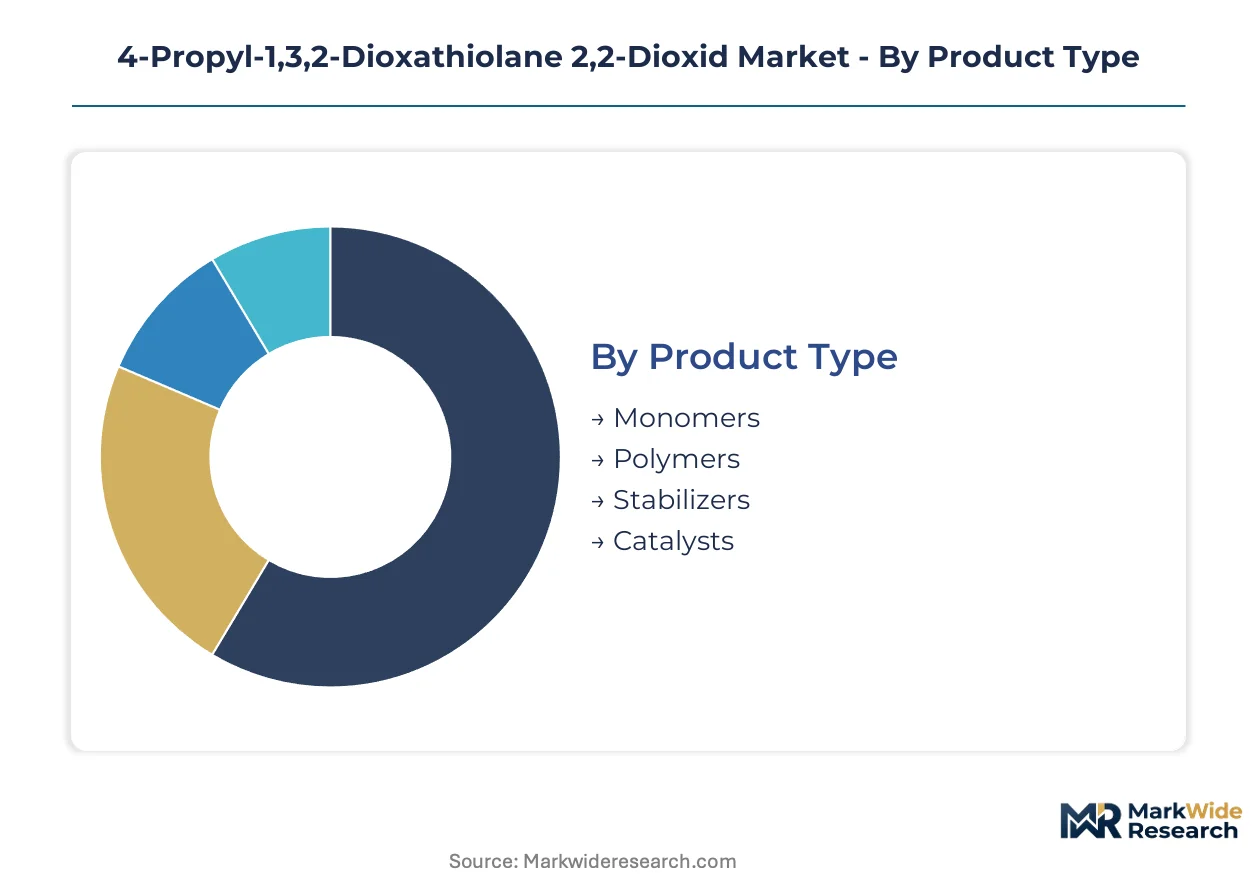
Formulators of 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid navigate distinct specification tiers across product types, purity grades, and end-use applications. Each segment imposes unique qualification barriers and margin structures that determine supplier positioning and procurement strategy.
Product Type:
Replacement cycles for cyclic sulfone esters accelerate as electronics manufacturers demand higher thermal stability thresholds, pushing formulators toward polymer-bound architectures that outlast monomer-based systems.
- Monomers:Unbound cyclic sulfone ester molecules serve as reactive diluents in high-performance adhesive formulations. Electronics packaging manufacturers in Germany concentrate procurement of monomer-grade material for thermal stabilizer applications requiring consistent lot-to-lot purity profiles under REACH substance registration protocols.
- Polymers:Covalently bound sulfone architectures integrate into polymer backbones for permanent thermal stabilization. Demand clusters in China where localized custom synthesis capabilities enable rapid turnaround for adhesive sector procurement teams seeking supply security through multi-year offtake structures.
- Stabilizers:Additive-grade sulfone derivatives extend service life of cured polymer systems. Coatings producers favor stabilizer forms for cost-sensitive sealants segments where moderate thermal performance suffices.
- Catalysts:Sulfone-derived catalytic species accelerate cure kinetics in epoxy-amine systems. Specialty chemical manufacturers deploy catalyst grades to reduce cycle times in high-throughput adhesive production lines.
Volume placements concentrate in Monomers; the faster expansion belongs to Polymers.
Grade:
Cost tier stratification separates qualification-intensive pharmaceutical applications from volume-driven industrial segments where purity premiums erode margin capture.
- Technical:Standard purity material serves coatings and sealants producers prioritizing cost efficiency over ultra-high purity specifications. Production clusters in select Chinese chemical parks expose buyers to localized environmental enforcement disruptions.
- Industrial:Mid-tier grade balances impurity control with scale economics for adhesive formulators serving automotive and construction sectors. EPA industrial chemical oversight compresses qualification timelines for cross-border supply.
- Laboratory:Analytical-grade material supports R&D scale-up and method validation activities. Merck KGaA sustains dominance through purity protocols exceeding standard industrial specifications.
- Pharmaceutical:Ultra-high purity monomer grades meet stringent impurity profiles for active pharmaceutical intermediate applications. CDSCO-aligned contract manufacturers in India pull pharmaceutical-grade supply as BIS certification pathways mature.
Revenue concentration sits in Pharmaceutical grades; Technical grades capture the highest shipment volumes.
Application:
Application-specific performance requirements dictate formulation architecture choices across thermal stability, viscosity modification, and cure kinetics.
- Adhesives:Reactive diluent functionality enables high-performance bonding systems for electronics packaging. German manufacturers scale formulations requiring sulfone-derived thermal stability above standard epoxy-amine thresholds.
- Coatings:Viscosity modification and flow control properties serve protective and decorative film applications. REACH Annex XVII restrictions on persistent organic pollutant precursors expand testing burdens for consumer-facing coatings streams.
- Sealants:Flexible cure systems incorporate cyclic sulfone esters for joint filling and gap sealing. Bio-based glycerol carbonate formulations displace sulfone chemistry in cost-sensitive segments where thermal demands are moderate.
- Elastomers:Crosslink density modification supports rubber compounding for dynamic applications. Demand remains specialized relative to adhesive and coatings volumes.
Adhesives command the dominant volume share; elastomer applications are climbing the fastest as dynamic performance requirements intensify.
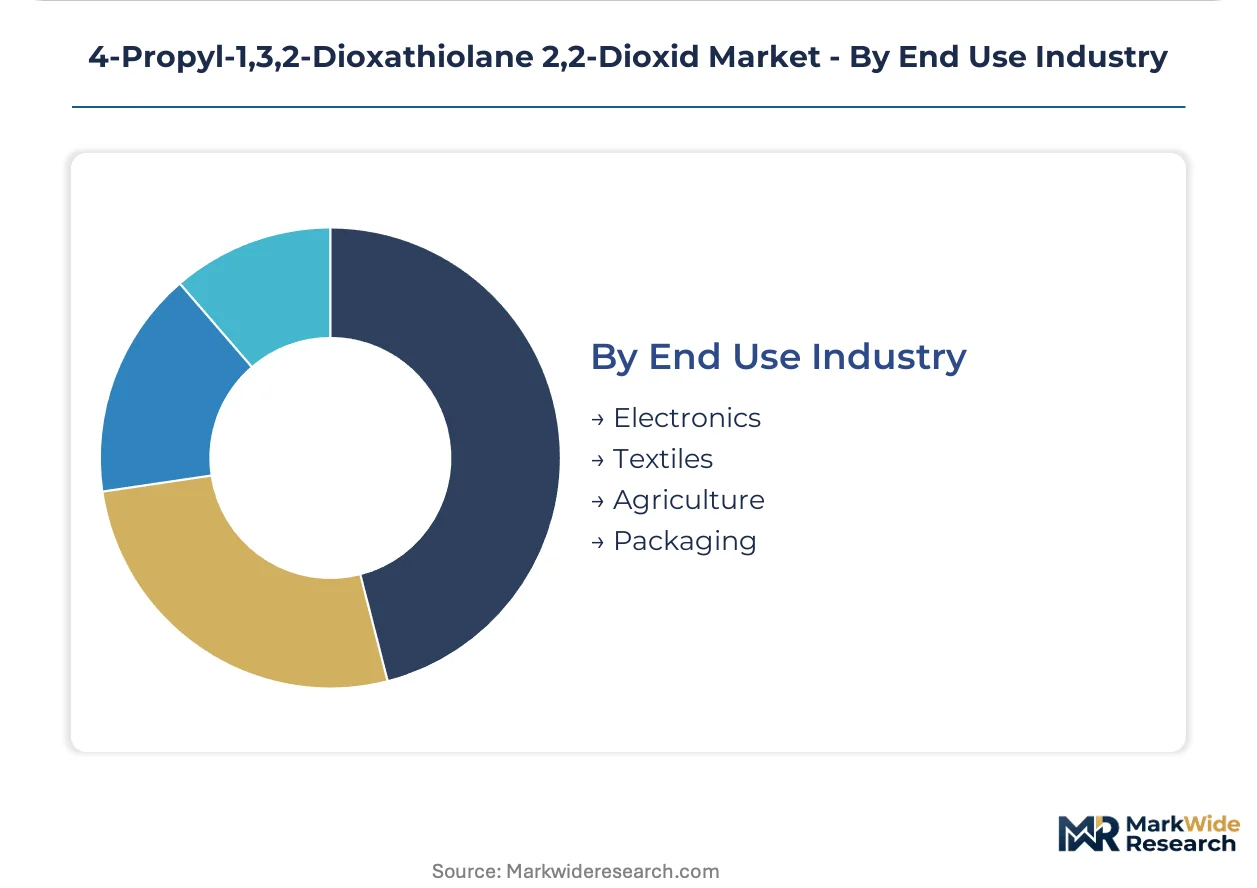
End Use Industry:
Customer-type differentiation separates specification-intensive electronics procurement from commodity-lean agricultural and textile applications.
- Electronics:Thermal stabilizer demand from packaging manufacturers drives monomer-grade procurement. Multi-year offtake agreements replace spot purchasing as supply security becomes paramount for German and Chinese producers.
- Textiles:Fiber treatment and finishing applications utilize sulfone derivatives for hand modification and durability enhancement. Volume scale trails electronics and packaging segments.
- Agriculture:Adjuvant and formulation aid applications serve crop protection chemistry. Cost sensitivity limits grade selection to technical and industrial tiers.
- Packaging:Food-contact and industrial packaging adhesives require compliant sulfone ester streams. BIS certification requirements in India add compliance layers for suppliers targeting this segment.
Electronics anchors the value pool; packaging applications show the steepest expansion trajectory as flexible packaging demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfur derivative availability along the Rhine corridor and propylene feedstock access in Shandong Province anchor regional production economics for 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid manufacturers.
Germany
Electronics packaging adhesive formulators in Bavaria and Baden-Württemberg scale procurement of monomer-grade sulfone esters for thermal stabilizer applications. ECHA REACH substance registration deadlines compress qualification timelines for coatings producers seeking compliant material streams. The Ludwigshafen chemical cluster sustains backward-integrated sulfone chemistry capabilities that control diol precursor flows.
China
Localized custom synthesis turnaround in Jiangsu and Zhejiang provinces attracts multi-year offtake agreements from electronics manufacturers. MEE enforcement of dual carbon intensity metrics incentivizes oxidation process improvements that reduce energy consumption per ton. The Yangtze River Delta concentration of technical-grade production exposes buyers to localized environmental enforcement disruptions.
United States
Specialty adhesive producers in Texas and the Gulf Coast region require pharmaceutical-grade material for active pharmaceutical intermediate applications. EPA industrial chemical oversight and pre-manufacture notification requirements extend customer approval cycles beyond standard procurement planning horizons. Houston-area chemical parks host sulfonation process operators with legacy expertise in diol-to-dioxide oxidation.
India
CDSCO-aligned contract manufacturers in Maharashtra and Gujarat expand sulfone chemistry capabilities for API production. BIS certification pathways for imported sulfone derivatives remain underdeveloped, creating first-mover positioning for compliant suppliers. The Mumbai-Pune pharmaceutical corridor pulls ultra-high purity monomer grades as domestic synthesis capacity scales.
Japan
Electronics material suppliers in the Kansai region procure polymer-bound stabilizer forms for packaging applications above standard industrial thermal thresholds. METI chemical substance regulations align with REACH substance evaluation criteria for cross-border supply qualification. The Osaka-Kobe industrial zone maintains stringent impurity control protocols for semiconductor-grade material streams.
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market Competitive Landscape
Capacity expansion dominates the current landscape as specialty chemical manufacturers invest in continuous flow sulfonation reactor technology to displace batch oxidation processes. The vendor base stratifies across three tiers: integrated petrochemical majors with captive sulfur derivative supply, mid-scale custom synthesis specialists serving pharmaceutical contract manufacturing organizations, and regional distributors with localized blending capabilities. Strategic archetypes include backward-integrated sulfone chemistry platforms, purity-focused laboratory-grade specialists, and rapid-turnaround custom synthesis operators. Competitive intensity centers on multi-source procurement infrastructure buildout and simultaneous purity upgrade investments to meet divergent EPA and REACH compliance thresholds.
Among European-based integrated chemical producers, BASF SE exemplifies the backward-integrated archetype through its Rhine corridor sulfone chemistry platform. Merck KGaA occupies a position within the laboratory-grade tier, sustaining dominance through purity protocols that exceed standard industrial specifications. TCI Chemicals anchors the Asia-Pacific rapid-turnaround segment with localized synthesis capabilities in Japan. These three players represent distinct competitive vectors: feedstock control, specification leadership, and geographic responsiveness.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| TCI Chemicals |
| Santa Cruz Biotechnology |
| Alfa Aesar |
| Biosynth |
| SynQuest Laboratories |
| AstaTech |
| Shijiazhuang Pengnuo Technology |
| Others |
Pricing and Supply Chain Analysis
Sulfur derivative spot indices on the Rotterdam barge market cascade through 4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid pricing tiers, compressing margins for non-integrated producers while amplifying backward-integrated positions. REACH registration cost amortization and EPA pre-manufacture notification burdens stratify procurement economics across pharmaceutical-grade and technical-grade buyer segments.
Pricing Analysis
Certification-bundling separates pharmaceutical-grade quotations inclusive of REACH dossier support from unbundled technical-grade spot transactions. Three-tier pricing structure across pharmaceutical, industrial, and technical levels reflects purity protocol divergence and customer qualification intensity. Cost compression in technical grades intensifies as bio-based glycerol carbonate substitutes erode volume positions in sealants. Coatings producers exhibit highest price sensitivity, while electronics packaging manufacturers absorbing thermal stabilizer premiums show lowest elasticity.
Supply Chain Analysis
Containerized freight cost volatility from Shanghai to Hamburg disrupts just-in-time procurement patterns for European adhesive formulators. Supply concentrates in Germany, China, and India, with production drawing from diol precursor streams anchored in propylene derivatives and sulfur chemistry. Single-source vulnerability pervades pharmaceutical-grade channels where sulfonation process expertise concentrates among legacy specialists. Distribution runs through distributor-synthesis hybrids in Asia and direct mill relationships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from simultaneous REACH purity upgrades and EPA notification timelines will force sub-scale batch operators into distressed exits or acquisition.
For Market Incumbents: Deploy continuous flow reactor capital to displace legacy batch oxidation capacity before regulatory qualification windows close. BASF SE and Merck KGaA should extend backward integration into diol precursor synthesis to neutralize sulfur derivative volatility, while locking multi-year offtake structures with electronics packaging manufacturers to preempt distributor disintermediation. For New Entrants and Emerging Players: Launch via BIS certification-first positioning in India, where CDSCO-aligned contract manufacturers seek compliant sulfone derivative supply. White-space targets include polymer-bound stabilizer architectures for Japanese semiconductor packaging and oxidation process efficiency plays under China's dual carbon enforcement. Custom synthesis turnaround capability represents the most penetrable wedge against established channel incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor sulfonation process specialists with captive diol supply in the Rhine corridor or Yangtze River Delta. Long-term viability hinges on regulatory qualification asset bases that outlast batch-technology obsolescence. Watch for REACH Annex XVII reclassification signals on cyclic sulfone esters as inflection indicators for reformulation-driven demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diol Precursors | Captive sulfur derivative supply neutralizes Rotterdam spot volatility for integrated producers. |
| Continuous Flow Reactor Deployment | Real-time impurity monitoring aligns with tightening pharmaceutical-grade specifications from ECHA. |
| BIS Certification Pathway Investment | First-mover positioning captures CDSCO-registered API producer demand in Maharashtra. |
| Multi-Year Offtake Agreement Structuring | Supply security commitments from German electronics manufacturers compress distributor margin capture. |
| Polymer-Bound Stabilizer R&D | Covalent architectures address thermal thresholds above standard industrial limits in Kansai packaging. |
Research Methodology
Document review covered ECHA registration dossiers, EPA pre-manufacture notifications, and CDSCO API manufacturing approvals, complemented by interviews with specialty chemical procurement leads, sulfonation plant managers, and pharmaceutical contract manufacturing executives. Secondary validation drew from customs trade data, Cefic sector reports, and SEC filings of listed chemical producers. Bottom-up volume triangulation against top-down value estimates anchored forecast robustness.
Segment-level projections across monomer-polymer-stabilizer-catalyst product types, pharmaceutical-industrial-technical-laboratory grade tiers, and electronics-packaging-textiles-agriculture end-use industries were generated through elasticity-adjusted extrapolation. CAGRs were derived from regression against historical sulfur derivative price cycles and adhesive sector output indices. Oxidation process energy intensity metrics and REACH compliance cost curves served as industry-specific forecast inputs.
Regulatory reclassification, sulfur feedstock supply disruption, and bio-based substitution acceleration are the dominant revision risks for projection validity. Forecasts embed assumptions on ECHA enforcement continuity and MEE carbon intensity policy stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.