
 Immunochemistry Products Market | 2026-2036
Immunochemistry Products Market Size, Share, and Industry Trends Forecast 2026-2036
Immunochemistry Products Market Outlook
Equipment leasing and reagent rental programs are fragmenting capital ownership across diagnostic networks. Danaher Corporation leverages its installed base of automated analyzers to lock in long-term consumable contracts. Thermo Fisher Scientific Inc. anchors its position through backward integration into antibody production. Bio-Rad Laboratories, Inc. differentiates via specialized quality control materials that laboratories require for regulatory compliance.
Immunochemistry products comprise antibody-antigen reaction systems used for detecting and quantifying biological targets, typically employing enzyme-linked signal amplification with detection thresholds reaching picogram-per-milliliter sensitivity. These systems serve clinical diagnostics and life science research by enabling precise measurement of proteins, hormones, and infectious disease markers. Reagent portfolios capture recurring revenue streams as laboratories consume antibodies, substrates, and wash buffers with each test cycle. ELISA technology dominates routine diagnostic throughput while flow cytometry commands premium positioning in specialized immunophenotyping applications. Instrument placements in hospital laboratories represent mature infrastructure with replacement cycles driving incremental upgrade demand.
The FDA enforces Clinical Laboratory Improvement Amendments that mandate analytical validation for immunochemistry assays used in patient care. ISO 15189 accreditation requirements in European diagnostic laboratories shape procurement specifications for traceable calibrators and control materials. WHO prequalification pathways influence purchasing decisions for immunoassay platforms deployed in infectious disease surveillance programs. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA standards for companion diagnostic immunoassays.
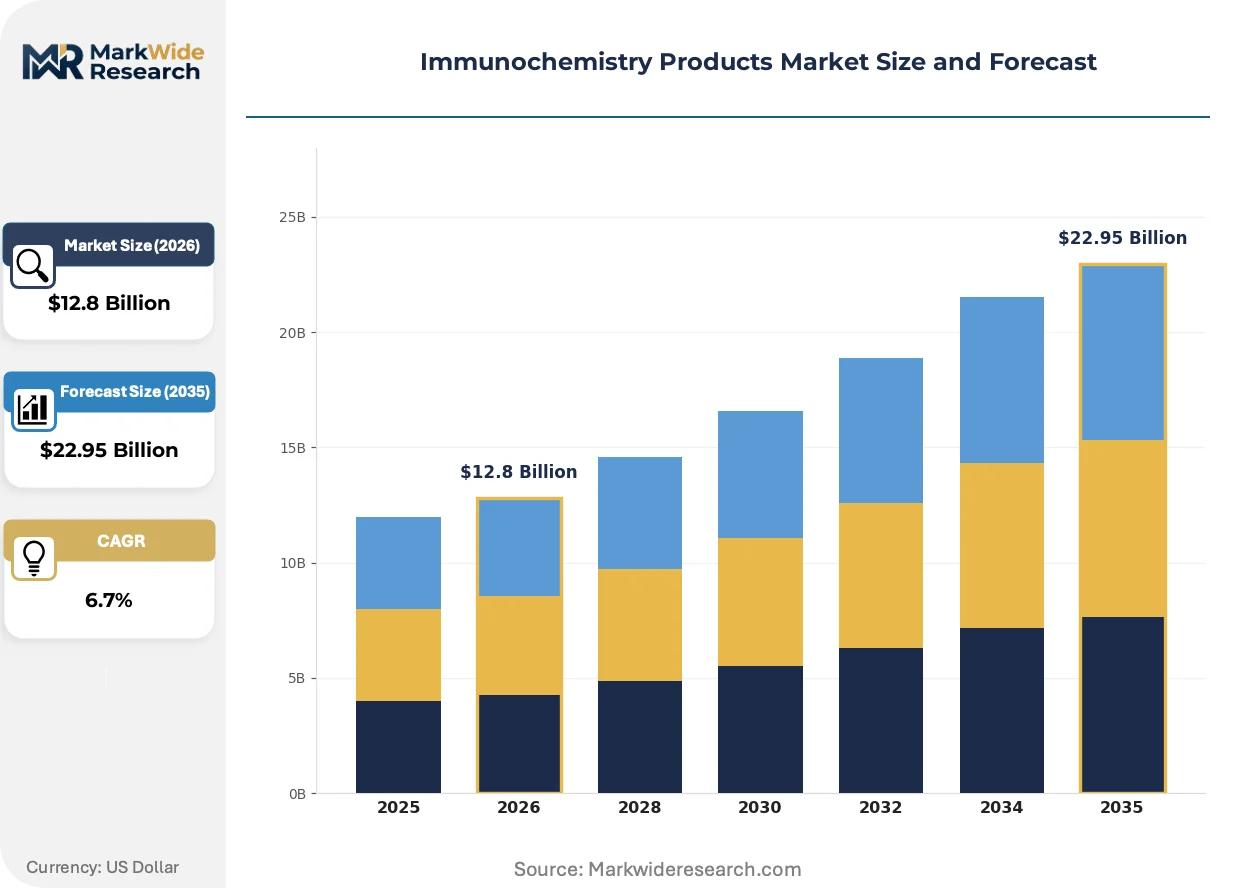
Market Dynamics
Hospital procurement consolidation in Germany is compressing vendor margins while simultaneously demanding higher-throughput automated immunoassay systems from suppliers. This buyer concentration is reshaping contract structures across European diagnostic networks.
Growth Catalysts
- CLIA-mandated analytical validation:The FDA's Clinical Laboratory Improvement Amendments require rigorous assay performance documentation. Diagnostic laboratories must continuously upgrade reagent portfolios to maintain compliance.
- Flow cytometry immunophenotyping:Specialized oncology and hematology workflows demand premium multiparametric cell analysis. Academic medical centers drive adoption of high-complexity testing platforms.
- German hospital network consolidation:Centralized purchasing authorities negotiate multi-year reagent supply agreements. Volume commitments lock in predictable consumable revenue streams for platform vendors.
Market Restraints
- Antibody raw material concentration:Hybridoma cell line production concentrates among limited contract manufacturing organizations. Supply disruptions propagate rapidly through downstream reagent supply chains.
- ISO 15189 traceability requirements:European diagnostic laboratories must source certified reference materials with documented metrological chains. Compliance costs escalate for smaller regional testing facilities.
- Lateral flow immunoassay substitution:Point-of-care diagnostic formats capture routine infectious disease testing previously routed to laboratory-based immunochemistry. Test decentralization erodes core laboratory volumes.
Strategic Opportunities
- Companion diagnostic immunoassay harmonization:Converging FDA and EMA technical standards create pathway efficiencies. Assay developers can pursue synchronized regulatory submissions across jurisdictions.
- India's CDSCO diagnostic registration pathway:The country's national pharmaceutical regulator is streamlining medical device approval timelines. Multinational manufacturers can accelerate market entry for automated analyzer platforms.
- WHO prequalification for infectious disease surveillance:Procurement frameworks for tuberculosis and HIV monitoring programs mandate validated immunoassay performance. Qualified suppliers gain preferential access to public health tenders.
Industry Challenges
- Multiplex assay development complexity:Simultaneous quantification of multiple analytes demands sophisticated antibody specificity engineering. Cross-reactivity mitigation extends validation timelines.
- Legacy analyzer integration friction:Hospital laboratories operate mixed-vendor instrument fleets. Interoperability gaps between competing platform ecosystems complicate workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunochemistry Products Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Consumables Technology: ELISA, Western Blotting, Flow Cytometry, Immunofluorescence End User: Research Laboratories, Hospitals, Diagnostic Centers, Academia Application: Biomarker Discovery, Disease Diagnosis, Drug Development, Basic Research |
| Companies Covered | PerkinElmer, Inc., Merck KGaA, F. Hoffmann-La Roche Ltd., Danaher Corporation, Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Abbott Laboratories, Illumina, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunochemistry Products Market Strategic Shifts
Digital immunoassay architectures are fundamentally altering detection sensitivity thresholds and signal processing workflows. These advances are compressing the performance gap between centralized laboratory instruments and distributed testing modalities.
Chemiluminescence detection chemistry is collapsing enzyme-linked signal amplification in high-throughput diagnostic applications. Clinical laboratories in the United States are retiring older ELISA-based workflows for hormone and tumor marker quantification. This transition eliminates manual pipetting steps and reduces technician hands-on time per reportable result.
EMA's In Vitro Diagnostic Medical Devices Regulation imposes strengthened clinical evidence requirements for companion diagnostic immunoassays. Manufacturers must generate prospective performance data rather than relying on analytical validation alone. Oncology assay developers are restructuring regulatory strategies to accommodate expanded post-market surveillance obligations.
Reagent rental contracts are displacing capital purchase models across hospital laboratory networks. Third-party distributors are losing direct vendor relationships as manufacturers establish captive leasing subsidiaries. This channel consolidation is most visible in Germany, where consolidated procurement entities negotiate total-cost-per-test agreements spanning seven-to-ten year terms.
Immunochemistry Products Market Segmentation
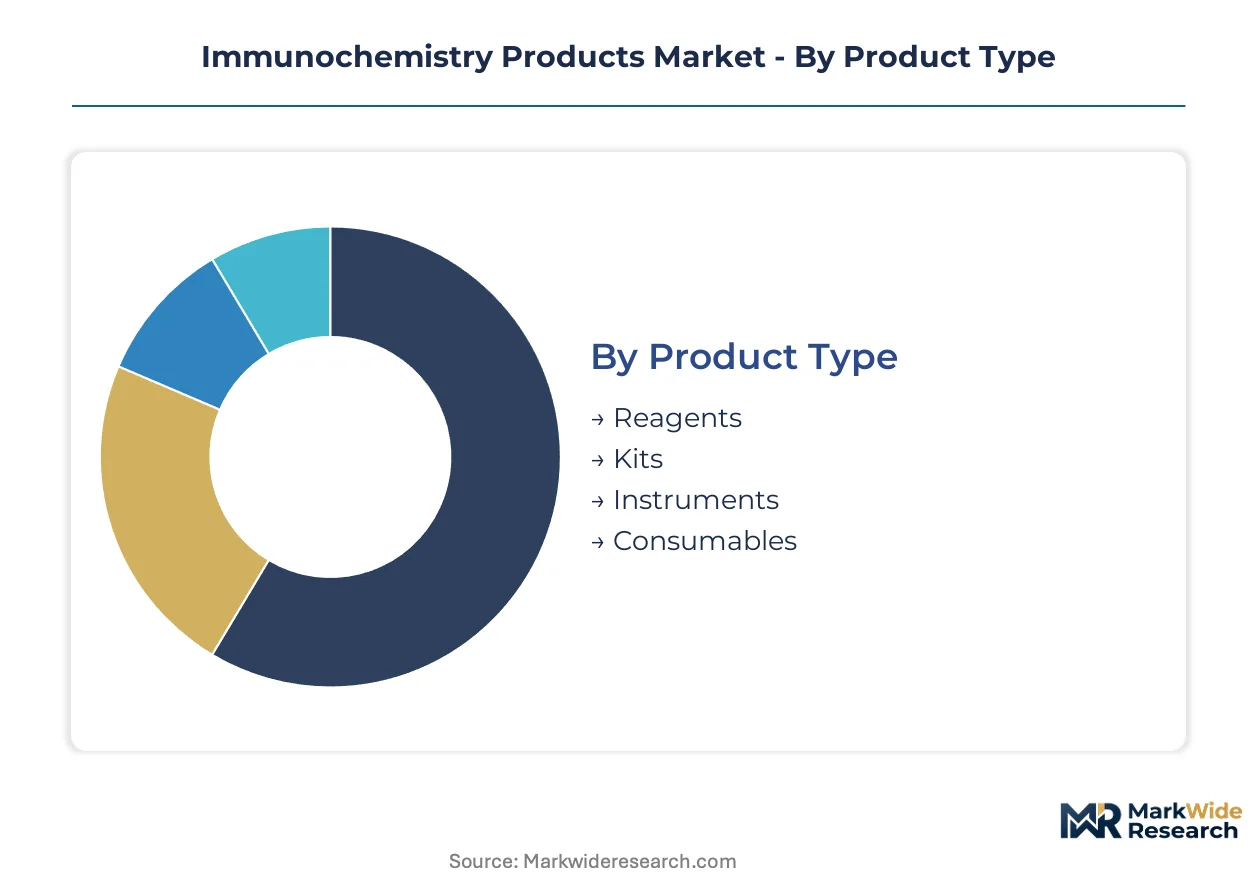
Immunochemistry product portfolios fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct procurement patterns, margin structures, and competitive dynamics that shape vendor positioning strategies.
Product Type:
Mature consumable categories dominate revenue recurrence while instrument placements anchor long-term vendor relationships.
- Reagents:Antibody-antigen binding formulations with defined specificity titers and stability profiles. Hospital laboratories in the United States consume these in continuous replenishment cycles tied to CLIA-mandated validation protocols.
- Kits:Pre-configured assay panels containing capture antibodies, detection enzymes, substrates, and calibrators in standardized formats. Diagnostic centers in Germany negotiate multi-year kit supply contracts through consolidated procurement networks.
- Instruments:Automated analyzers with throughput specifications ranging from benchtop units to high-capacity systems.
- Consumables:Microplates, pipette tips, wash buffers, and substrate reagents consumed per test cycle.
Reagents handle the majority of throughput; kits are expanding most quickly on share.
Technology:
Detection chemistry sophistication separates routine diagnostic applications from premium research workflows.
- ELISA:Enzyme-linked immunosorbent assay platforms using chromogenic or chemiluminescent signal amplification. Clinical diagnostic laboratories in the United States are retiring older ELISA workflows for hormone quantification in favor of chemiluminescence alternatives.
- Flow Cytometry:Multiparametric cell analysis systems employing fluorescent antibody panels for immunophenotyping. Academic medical centers drive adoption of high-complexity testing platforms for oncology and hematology applications.
- Western Blotting:Protein separation and antibody-based detection for molecular weight verification.
- Immunofluorescence:Microscopic visualization techniques for cellular and tissue antigen localization.
ELISA maintains the highest test volume; flow cytometry commands the steepest expansion trajectory.
End User:
Procurement authority concentration varies sharply across institutional categories, reshaping vendor sales approaches.
- Hospitals:Integrated health systems with centralized laboratory operations and capital equipment leasing preferences. German hospital networks are consolidating procurement for high-throughput immunochemistry systems through multi-year reagent rental agreements.
- Diagnostic Centers:Independent testing facilities focused on routine clinical assay throughput. These entities prioritize cost-per-test economics and regulatory compliance documentation.
- Research Laboratories:Biotechnology and pharmaceutical R&D operations requiring specialized assay development capabilities.
- Academia:University-based research programs with grant-funded equipment acquisition and open-architecture platform preferences.
Hospitals generate the largest consumable pull-through; diagnostic centers are gaining share fastest.
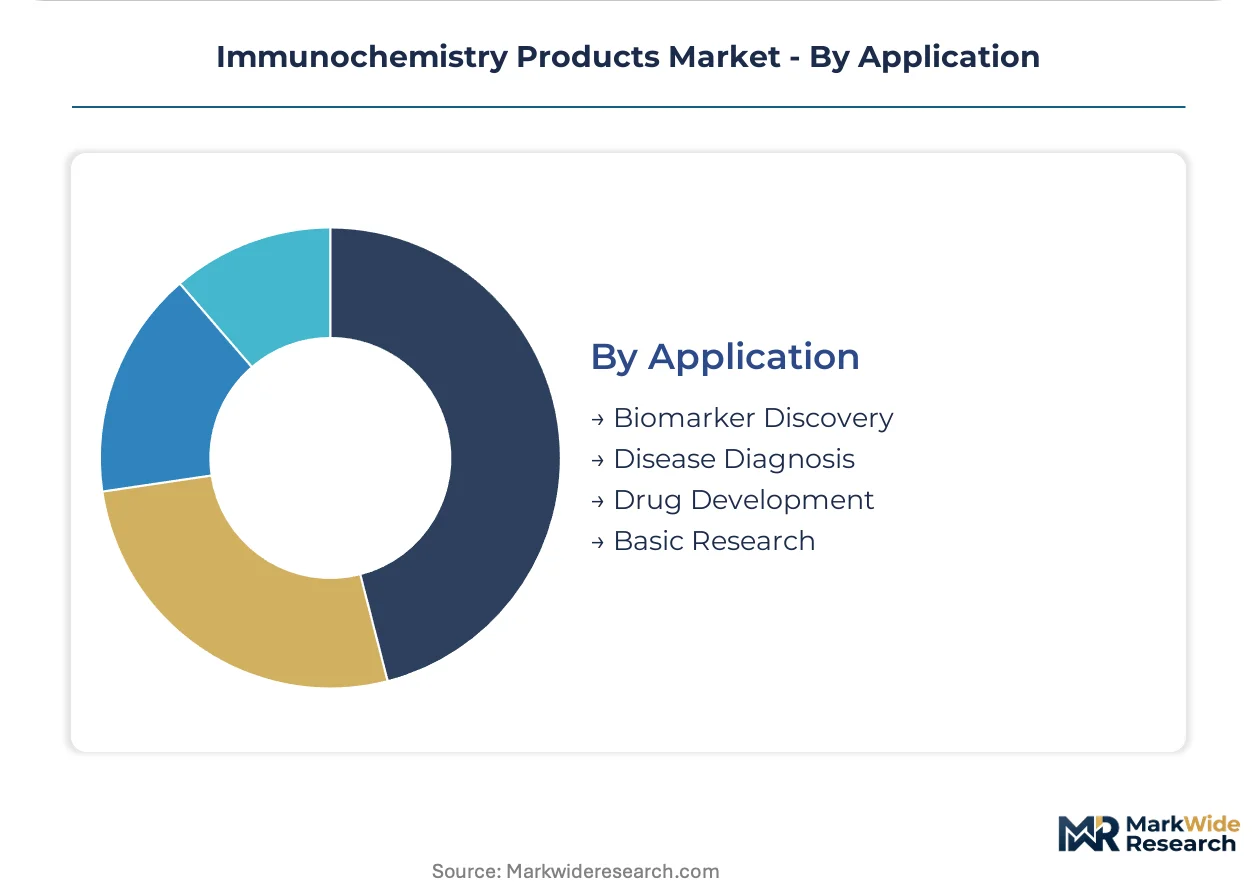
Application:
Clinical utility requirements impose stricter validation burdens than research-oriented use cases.
- Disease Diagnosis:Patient care applications requiring FDA-cleared or CE-marked assay performance documentation. EMA's In Vitro Diagnostic Medical Devices Regulation imposes strengthened clinical evidence requirements for companion diagnostic immunoassays in oncology.
- Drug Development:Pharmacokinetic and immunogenicity testing supporting therapeutic candidate progression. Contract research organizations integrate immunochemistry platforms into regulated bioanalytical workflows.
- Biomarker Discovery:Exploratory protein quantification for target identification and validation.
- Basic Research:Fundamental immunology and cell biology investigations without regulatory submission requirements.
Disease diagnosis commands the dominant installed base; drug development applications are climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of immunochemistry reagents and analyzers concentrate in developed diagnostic infrastructure markets, while manufacturing output clusters in jurisdictions with hybridoma cell line production capabilities and precision instrumentation engineering bases.
United States
Hospital laboratory automation upgrades and CLIA-mandated analytical validation protocols sustain demand for high-throughput immunoassay platforms. FDA premarket review pathways for novel diagnostic platforms compress validation timelines for assay developers. The Boston-Cambridge biotechnology corridor anchors hybridoma cell line development and antibody engineering operations.
Germany
Hospital network procurement consolidation is compressing vendor margins while demanding multi-year reagent rental agreements. EMA's In Vitro Diagnostic Medical Devices Regulation imposes strengthened clinical evidence requirements for companion diagnostic immunoassays. The Rhine-Ruhr metropolitan region concentrates automated analyzer manufacturing and precision optics engineering for detection systems.
China
Domestic diagnostic laboratory expansion and infectious disease surveillance program scale-up drive platform installations. NMPA medical device registration reforms are streamlining approval timelines for automated immunoassay systems. The Yangtze River Delta manufacturing belt concentrates microplate and consumable production for regional supply chains.
India
Diagnostic center franchising and public health screening program expansion generate consumable pull-through demand. CDSCO diagnostic registration pathway streamlining accelerates multinational market entry for analyzer platforms. The Hyderabad-Bangalore pharmaceutical corridor anchors contract research organization integration of immunochemistry into regulated bioanalytical workflows.
Japan
Aging population screening protocols and oncology biomarker testing sustain premium instrument placements. PMDA quality management system requirements shape procurement specifications for traceable calibrators. The Kansai region around Osaka maintains precision instrument manufacturing clusters for detection module assembly.
Immunochemistry Products Market Competitive Environment
On the supply side, the industry is consolidating around diversified life science conglomerates with captive antibody production and automated analyzer manufacturing capabilities. Three strategic archetypes dominate: integrated platform vendors bundling instruments with long-term reagent contracts, specialized quality control material suppliers, and precision detection technology developers. Competitive maneuvering concentrates on backward integration into antibody raw materials and geographic expansion through reagent rental subsidiaries.
Among diversified conglomerates, Danaher Corporation, Thermo Fisher Scientific Inc., and Bio-Rad Laboratories, Inc. exemplify distinct positioning vectors. Danaher anchors the integrated platform archetype through automated analyzer installed bases that lock in consumable revenue streams. Thermo Fisher occupies upstream control positioning via in-house antibody production capabilities that secure raw material supply chains. Bio-Rad represents the specialized quality control tier, supplying regulatory compliance materials that laboratories require for ISO 15189 accreditation maintenance.
| Leading Market Players |
|---|
| PerkinElmer, Inc. |
| Merck KGaA |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Illumina, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in hybridoma cell line production across Chinese contract manufacturing organizations is compressing antibody raw material costs while simultaneously eroding pricing power for downstream reagent suppliers. This utilization dynamic forces diagnostic platform vendors to absorb margin compression or accelerate backward integration into captive antibody production.
Pricing Analysis
Hospital procurement committees anchor contract structures around total-cost-per-test metrics spanning seven-to-ten year reagent rental agreements. Pricing stratifies across premium, standard, and economy tiers differentiated by CLIA validation documentation depth and ISO 15189 traceability certification. Cost compression in economy-tier consumables is intensifying because German hospital network consolidation centralizes purchasing authority. Academic research laboratories exhibit highest price sensitivity; reference laboratories running regulated diagnostic assays demonstrate lowest sensitivity due to reimbursement pass-through mechanics.
Supply Chain Analysis
Lonza, Samsung Biologics, and Boehringer Ingelheim hold concentrated contract manufacturing capacity for monoclonal antibody production. Geographic supply concentrates in China, Switzerland, and South Korea for hybridoma cell line development and precision detection module assembly. Raw material dependencies rest on fetal bovine serum, recombinant protein expression systems, and rare-earth phosphors for chemiluminescent substrates. Single-source vulnerability pervades specialized antibody clone lines protected by trade-secret fermentation protocols. Distribution runs through captive leasing subsidiaries displacing third-party diagnostic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where analyzer-reagent interoperability standards determine vendor lock-in durability. EMA's In Vitro Diagnostic Medical Devices Regulation is accelerating ecosystem consolidation around integrated platform architectures.
For Market Incumbents: Entrench installed base relationships through multi-year reagent rental contracts with minimum volume commitments that raise switching costs. Accelerate backward integration into hybridoma cell line production to neutralize raw material concentration risk from Chinese contract manufacturers. Defend against lateral flow immunoassay substitution by embedding chemiluminescence detection modules into distributed testing workflows. For New Entrants and Emerging Players: India's diagnostic center franchising expansion offers the most penetrable entry corridor for automated analyzer platforms. Target quality control materials supply to mid-tier laboratories seeking ISO 15189 accreditation without incumbent vendor dependency. Pursue WHO prequalification for tuberculosis and HIV immunoassays to unlock public health procurement frameworks in infectious disease surveillance programs. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because reagent pull-through economics dominate capital equipment placement returns. Acquisition target archetype: specialized antibody engineering firms with validated clone lines for multiplex oncology panels. Monitor CDSCO registration pathway streamlining as signal for multinational market entry acceleration in Indian diagnostic networks.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Seven-to-ten year agreements with German hospital networks lock in predictable consumable revenue streams. |
| Hybridoma Cell Line Acquisition | Captive antibody production neutralizes supply disruption risk from concentrated contract manufacturing organizations. |
| WHO Prequalification Pursuit | Validated immunoassay performance unlocks preferential access to tuberculosis and HIV public health tenders. |
| CDSCO Registration Acceleration | Streamlined Indian medical device approvals enable multinational analyzer platform market entry. |
| Companion Diagnostic Harmonization | Converging FDA and EMA technical standards create pathway efficiencies for synchronized regulatory submissions. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with diagnostic platform executives, clinical laboratory directors, hospital procurement managers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Medical Devices Regulation guidance documents, WHO prequalification assessment reports, and hospital GPO contract databases. Bottom-up instrument placement counts and top-down reagent consumption estimates were triangulated to anchor market sizing.
Forecast inputs considered product type segmentation across reagents, kits, instruments, and consumables; technology tiers spanning ELISA, chemiluminescence, and flow cytometry; and end-user categories including hospital networks, diagnostic centers, and research laboratories. CAGRs were derived from installed base replacement cycles, CLIA-mandated validation upgrade frequencies, and infectious disease surveillance program expansion trajectories across the analysis window. Pricing elasticity assumptions incorporated German procurement consolidation and Indian diagnostic franchising patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates into antibody raw material production would shift outcomes. Quarterly review of CDSCO registration timeline compression, EMA post-market surveillance obligation implementation, and hybridoma cell line capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Barium Derivatives Market