
 Rosin Market | 2026-2036
Rosin Market Size, Share, and Industry Trends Forecast 2026-2036
Rosin Market Outlook
ISO 9001 certification is rotating as the baseline qualification separating contract rosin suppliers from specialty extractors in this fragmented landscape. Green Dot Labs leverages captive biomass sourcing across multiple state-licensed cultivation zones to secure feedstock continuity. Rosin Tech Labs anchors its position through equipment-to-consumable bundling, selling presses alongside processed resin. 710 Labs differentiates via solventless extraction protocols that preserve full-spectrum terpene profiles for premium positioning.
Rosin denotes a solid resin obtained from the oleoresin of pine trees, primarily composed of abietic acid and pimaric acid isomers with softening points typically ranging from 70°C to 80°C, serving as a natural tackifier and film-forming agent across industrial formulations. Gum roin occupies the dominant volume position due to its direct tapping origin and lower processing overhead, while modified rosin derivatives command superior margin pools through esterification and hydrogenation upgrades that expand heat resistance. Adhesives applications lead consumption by tonnage, though cosmetics-grade formulations are gaining fastest as personal care brands reformulate away from petroleum-derived rheology modifiers.
REACH registration requirements in Europe and China's SAMR food-contact material standards are elevating testing burdens for cross-border rosin shipments, filtering out uncertified traders. The EPA's TSCA oversight in the United States adds another compliance layer for industrial-grade imports used in coatings and sealants. Stakeholders must monitor how dual carbon goals in major producing nations reshape pine plantation economics and resin tapping labor availability.
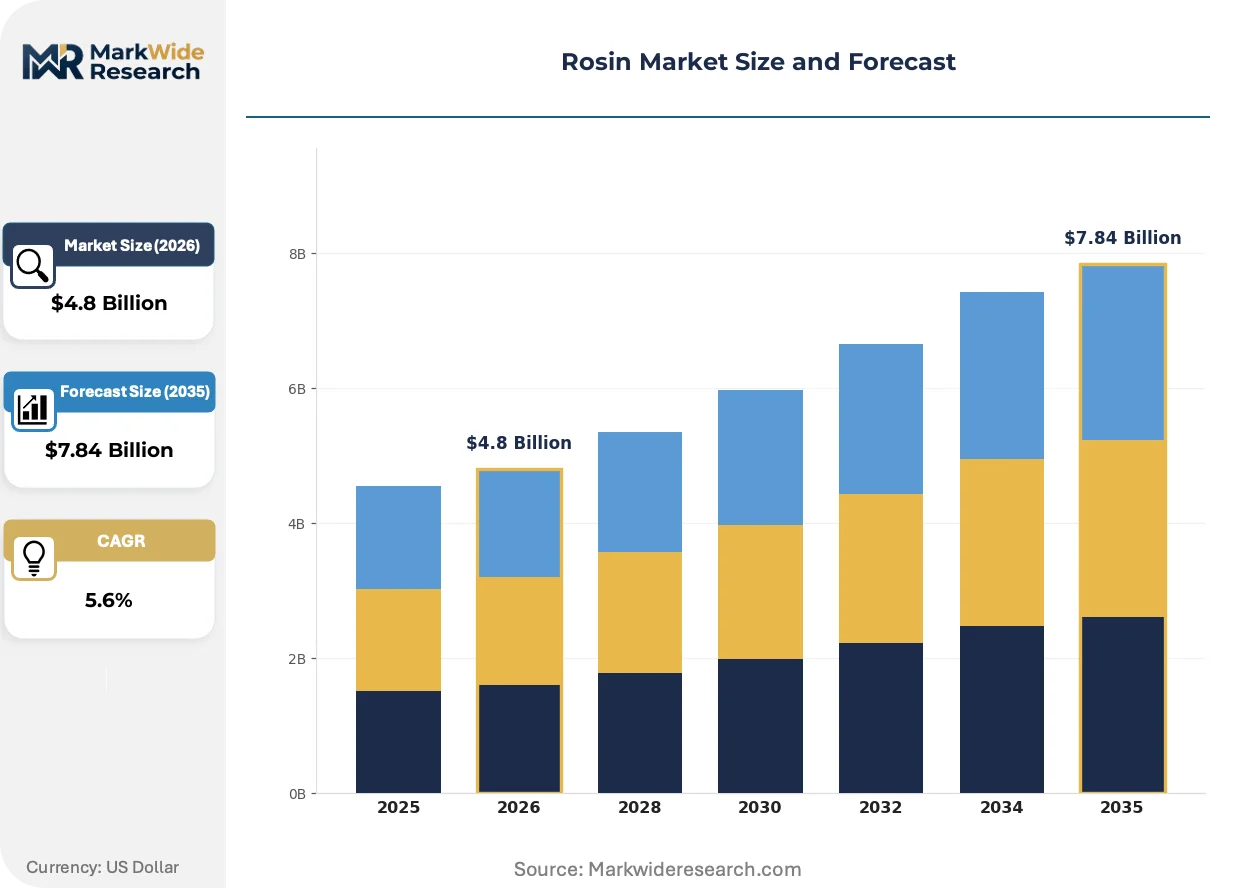
Market Dynamics
Water-based adhesive formulation mandates across Southeast Asian manufacturing hubs are compressing demand for petroleum-derived tackifiers while elevating certified gum rosin procurement. This regulatory pivot is restructuring supplier qualification hierarchies and concentrating contract volumes toward ISO 9001-certified extractors with verified plantation traceability.
Growth Catalysts
- REACH registration tiering:ECHA's escalating substance data requirements for industrial polymers are filtering uncertified traders from European supply chains. Certified gum rosin suppliers capture displaced volumes.
- Cosmetics reformulation:Personal care brands are eliminating petroleum-derived rheology modifiers. Natural rosin esters satisfy clean-label positioning while maintaining film-forming performance.
- Indonesian cooperative scaling:Pine tapping collectives in Sumatra and Kalimantan are consolidating harvesting capacity. Major derivative producers secure feedstock continuity through direct offtake agreements.
Market Restraints
- Crude tall oil substitution:Kraft pulp byproduct rosin competes on price in paper sizing and low-grade adhesives. CTO availability fluctuates with pulp mill operating rates.
- Chinese GB standard compliance costs:SAMR food-contact material testing burdens add certification overhead for cross-border shipments. Smaller exporters absorb margin compression or exit.
- Seasonal tapping labor constraints:Resin collection depends on manual labor availability in Brazilian and Indonesian plantation zones. Climate volatility disrupts harvest windows.
Strategic Opportunities
- India BIS adoption:Bureau of Indian Standards certification for natural resins remains underpenetrated. Early movers establish specification-setting authority ahead of formal mandates.
- Hydrogenated rosin esters:Heat-resistant derivatives open automotive underhood adhesives and solder flux applications. Esterification upgrades command margin expansion over unmodified grades.
- Direct-to-formulator digital channels:Specialty rosin producers bypass distributor markups through platform-based procurement. Mid-size adhesive compounders in Vietnam and Thailand source verified grades online.
Industry Challenges
- Terpenoid chemist scarcity:Hydrogenation and esterification process optimization requires specialized expertise. Universities in producing regions underinvest in natural products chemistry programs.
- Legacy ERP integration:Plantation cooperatives lack traceability systems for batch-level resin origin documentation. Blockchain pilot deployments face capital constraints and digital literacy gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosin Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gum Rosin, Powder Rosin, Colophony, Modified Rosin Application: Adhesives, Coatings, Printing Inks, Cosmetics End User: Manufacturing, Construction, Automotive, Personal Care Grade: Standard, Food Grade, Industrial Grade, High Purity |
| Companies Covered | Green Dot Labs, Rosin Tech Labs, 710 Labs, Kalya Extracts, Gold Canna, Lucky Elk, Simply Mary, 8 Six Brand, Alienlabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosin Market Strategic Shifts
Solventless extraction protocols and modified derivative processing are splitting competitive positioning between commodity volume suppliers and premium specialty extractors. Technology deployment now determines margin capture rather than feedstock access alone.
Supercritical CO2 rosin extraction is bifurcating quality tiers in cannabis and hemp derivative markets. Premium concentrate brands adopt cold-press mechanical methods to preserve full-spectrum terpene profiles. This technology is compressing margins for ethanol-extracted competitors while enabling solventless positioning at 40-60% price premiums.
China's dual carbon goals are tightening MEE oversight of pine plantation expansion and resin processing emissions. Smaller acid-grade rosin refineries face consolidation pressure from energy-intensity audits. Major producers in Fujian and Guangxi provinces are retrofitting biomass cogeneration to maintain operating licenses.
Certification-driven specification contracts are displacing spot-market purchasing among European adhesives formulators. Buyers now require REACH-compliant documentation and ISO 9001 chain-of-custody verification upfront. German and Dutch industrial distributors report 60-day average qualification cycles for new rosin suppliers, up from 14 days five years prior.
Rosin Market Segmentation
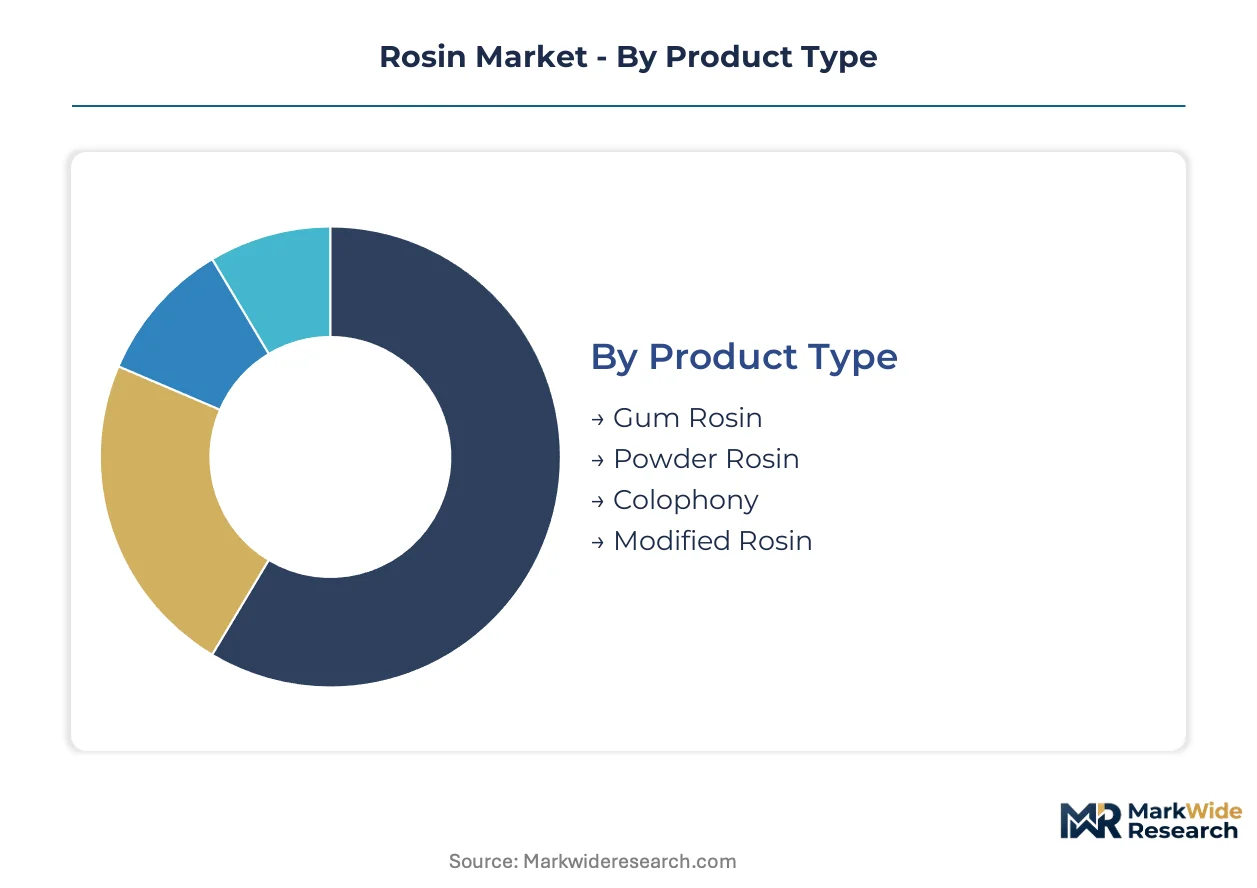
Rosin market segmentation reveals divergent supply chain configurations across product grades and end-use specifications. Certification requirements and formulation chemistry create distinct procurement channels that reshape competitive positioning among extractors and derivative producers.
Product Type:
Domestic consumption patterns favor unmodified grades in major producing nations, while export flows concentrate in upgraded derivatives for specialty applications.
- Gum Rosin:Direct-tapped oleoresin containing abietic and pimaric acid isomers with softening points between 70°C and 80°C. Demand concentrates in Indonesian and Brazilian domestic adhesives manufacturing, where water-based formulation mandates from Jakarta and São Paulo regulators elevate certified gum rosin procurement over petroleum-derived alternatives.
- Modified Rosin:Esterified or hydrogenated derivatives exhibiting enhanced heat resistance and oxidation stability. German and Dutch automotive suppliers absorb volumes for underhood adhesives and solder flux applications, with ECHA REACH registration tiering filtering uncertified competitors from European supply chains.
- Powder Rosin:Micronized particles sized for uniform dispersion in hot-melt and solvent-based adhesive systems.
- Colophony:Traditional violin rosin and pharmaceutical-grade resin requiring stringent purity controls for bow friction and topical applications.
Gum rosin holds the largest share; momentum sits with modified rosin as esterification upgrades command margin expansion.
Application:
Cost-tier differentiation separates commodity volume purchasers from premium formulators seeking certified grades for regulated end-uses.
- Adhesives:Natural tackifier replacing petroleum-derived alternatives in water-based formulations. Southeast Asian manufacturing hubs in Vietnam and Thailand drive procurement volume as environmental regulations tighten solvent-based system allowances.
- Cosmetics:Film-forming and rheology-modifying functions in personal care formulations. Clean-label positioning among European and North American brands accelerates reformulation away from synthetic modifiers, though SAMR food-contact testing burdens constrain Chinese exporter participation.
- Coatings:Binder and gloss-enhancing resin for protective and decorative surface treatments.
- Printing Inks:Viscosity control and pigment wetting agent in offset and gravure formulations.
Adhesives applications dominate by tonnage; cosmetics-grade formulations are climbing the fastest as personal care brands eliminate petroleum-derived rheology modifiers.
End User:
Customer-type stratification creates distinct qualification hierarchies, with regulated industries demanding chain-of-custody documentation absent from commodity procurement.
- Manufacturing:Broad industrial consumption spanning adhesives, sealants, and intermediate chemical synthesis. ISO 9001 certification operates as baseline supplier qualification, separating contract volumes from spot-market trading.
- Personal Care:Cosmetics and pharmaceutical formulations requiring food-grade or high-purity rosin certifications. BIS standards adoption in India remains underpenetrated, creating specification-setting opportunities for early movers ahead of formal mandates.
- Construction:Flooring adhesives, waterproofing membranes, and sealant applications.
- Automotive:Underhood adhesives, solder flux, and tire manufacturing additives.
Manufacturing absorbs the greatest volume; personal care generates the steepest expansion trajectory through clean-label reformulation.
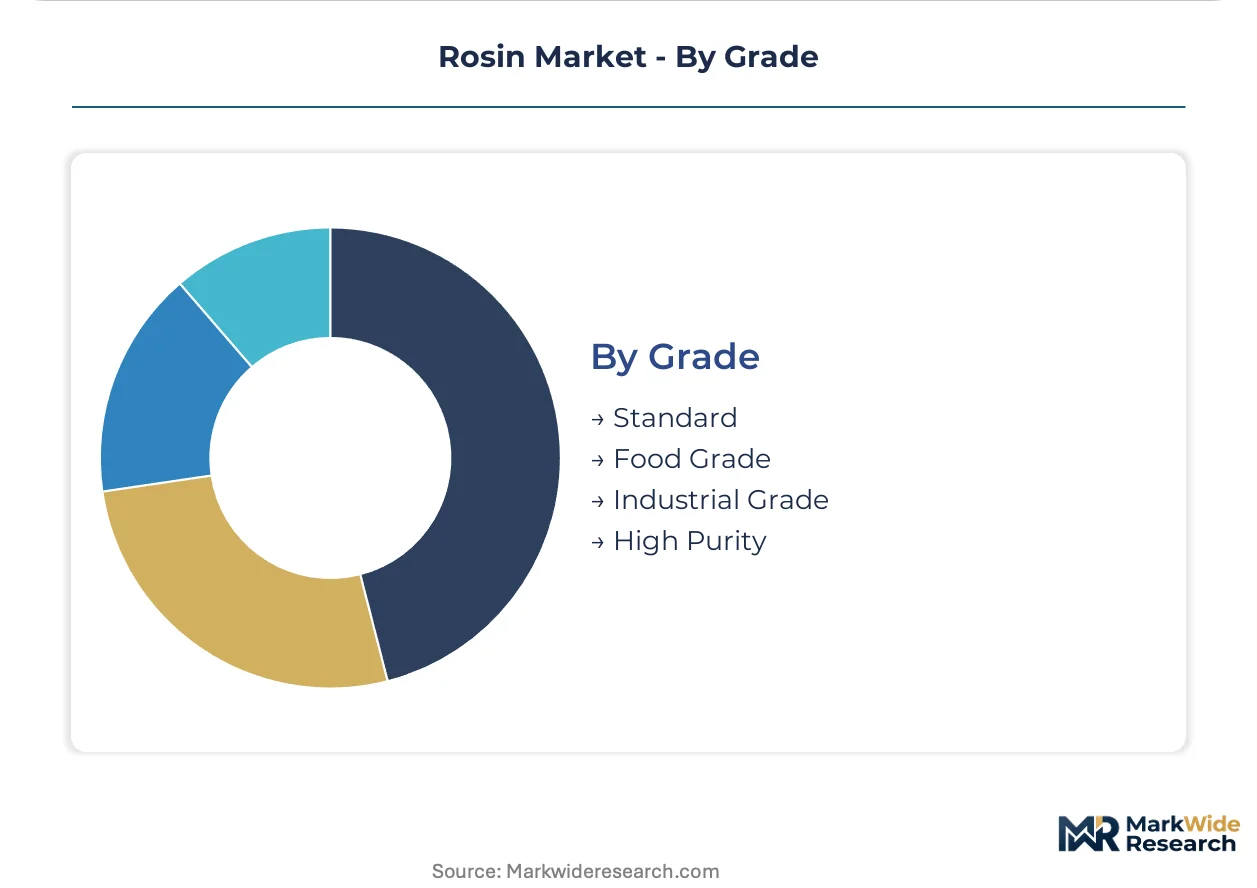
Grade:
Supply concentration among certified extractors shapes availability across purity tiers, with plantation traceability systems determining qualification for regulated applications.
- Industrial Grade:Standard acid-grade rosin for adhesives, coatings, and paper sizing. Chinese Fujian and Guangxi producers face MEE energy-intensity audit consolidation pressure, with biomass cogeneration retrofits maintaining operating licenses under dual carbon goals.
- Food Grade:Refined rosin meeting SAMR food-contact material standards and FDA indirect food additive specifications. Cross-border shipment testing burdens compress margins for smaller exporters while concentrating procurement among certified suppliers with verified plantation documentation.
- Standard:Unspecified general-purpose resin for non-critical industrial applications.
- High Purity:Ultra-refined grades for pharmaceutical, electronic, and analytical applications.
Industrial grade commands the greatest tonnage; food grade is gaining share fastest through regulatory elevation of certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in São Paulo state anchors Latin American rosin export logistics, handling containerized resin shipments bound for European adhesive formulators and Asian derivative producers.
Indonesia
Sumatran pine tapping cooperatives supply major gum rosin volumes to water-based adhesive manufacturers in Vietnam and Thailand. SAMR-compliant certification requirements from Beijing redirect procurement toward verified plantation traceability systems. Kalimantan extraction clusters face MEE-style emissions scrutiny as Jakarta aligns with dual carbon commitments.
Brazil
São Paulo state regulators enforce stringent resin quality protocols for food-contact applications. Pine plantation expansion in Minas Gerais and Paraná feeds acid-grade rosin refineries serving domestic coatings producers. The Port of Paranaguá consolidates export flows to German and Dutch automotive adhesive compounders.
China
Fujian and Guangxi province refineries retrofit biomass cogeneration to survive MEE energy-intensity audits under dual carbon enforcement. GB standards for food-contact resins concentrate procurement among certified gum rosin suppliers with documented chain-of-custody. Yangtze River Delta adhesive formulators absorb modified rosin derivatives for electronics assembly applications.
Germany
ECHA REACH registration tiering filters uncertified traders from European supply chains, concentrating contract volumes toward ISO 9001-certified extractors. North Rhine-Westphalia adhesive compounders specify hydrogenated rosin esters for automotive underhood applications. The Port of Rotterdam handles bulk resin transshipments from Indonesian and Brazilian origins.
United States
EPA TSCA oversight adds compliance layers for industrial-grade rosin imports used in coatings and sealants. Southeast Asian resin flows through West Coast ports to serve California-based personal care formulators eliminating petroleum-derived rheology modifiers. Texas Gulf Coast chemical processors absorb modified rosin derivatives for hot-melt adhesive production.
Rosin Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with ISO 9001 documentation separating contract suppliers from spot-market traders. The vendor base stratifies into plantation-integrated extractors, equipment-to-consumable bundlers, and solventless protocol specialists. Three archetypes dominate: captive biomass operators securing feedstock continuity, technology licensors bundling presses with processed resin, and premium-positioned extractors preserving full-spectrum terpene profiles. Competitive moves concentrate on strategic partnerships with tapping cooperatives and portfolio diversification into hydrogenated derivatives.
Within the solventless extraction tier, 710 Labs exemplifies premium positioning through full-spectrum preservation protocols. Green Dot Labs anchors the captive biomass archetype across multiple state-licensed cultivation zones. Rosin Tech Labs occupies the equipment-to-consumable bundling position, representing the technology-licensing competitive vector.
| Leading Market Players |
|---|
| Green Dot Labs |
| Rosin Tech Labs |
| 710 Labs |
| Kalya Extracts |
| Gold Canna |
| Lucky Elk |
| Simply Mary |
| 8 Six Brand |
| Alienlabs |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Indonesian pine tapping cooperatives and Southeast Asian adhesive manufacturers lock in feedstock continuity while capping price volatility exposure for both parties. These contracts bundle ISO 9001 certification requirements with volume commitments, embedding compliance costs directly into the pricing architecture.
Pricing Analysis
Certification level creates the primary spread between contract tiers. ISO 9001-certified gum rosin commands substantial premiums over uncertified spot-market grades, with REACH-registered modified derivatives occupying the top tier for European automotive adhesive compounders. Cost compression in standard acid-grade rosin intensifies as Chinese Fujian refineries absorb biomass cogeneration retrofit expenses under MEE dual carbon enforcement. Small-scale Brazilian exporters exhibit the highest price sensitivity, while German automotive suppliers prioritize heat-resistant hydrogenated esters regardless of unit cost.
Supply Chain Analysis
Port congestion at Santos and Paranaguá underwrites delivery uncertainty for Brazilian resin shipments bound for European automotive compounders. Raw material flows draw from Sumatran pine plantations, Minas Gerais tapping zones, and Guangxi province refineries, with oleoresin quality varying by harvest timing and climate conditions. Single-source vulnerability concentrates in Indonesian cooperative supply channels where manual labor availability fluctuates seasonally. Distribution runs through Rotterdam bulk transshipment terminals for European REACH-compliant volumes and Yangtze River Delta chemical processors for Chinese domestic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates multiple niche entry points as cosmetics reformulation accelerates demand for food-grade and high-purity rosin derivatives.
For Market Incumbents: Secure backward integration into pine plantation operations in Kalimantan and Paraná to insulate against seasonal labor disruptions and capture margin from oleoresin through finished derivative. Defend contract positions by accelerating hydrogenated ester capacity additions ahead of automotive underhood adhesive specification tightening. Invest in blockchain traceability pilots to satisfy emerging chain-of-custody requirements from European formulators. For New Entrants and Emerging Players: Lead with BIS certification positioning in India ahead of formal natural resin mandates, exploiting specification-setting authority in an underpenetrated compliance environment. Target cosmetics-grade gum rosin for North American personal care brands eliminating petroleum-derived rheology modifiers. Deploy direct-to-formulator digital procurement platforms to bypass established distributor markups in Vietnam and Thailand. For Investors and Strategic Acquirers: Plantation-integrated mid-tier extractors with existing ISO 9001 documentation and unutilized hydrogenation capacity represent the optimal acquisition profile for consolidation plays. Long-term viability hinges on dual carbon alignment in producing nations reshaping refinery operating economics. Monitor MEE audit enforcement intensity in Fujian and Guangxi provinces as an inflection indicator for Chinese supply consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantations | Captive oleoresin supply from Sumatran cooperatives insulates against seasonal labor volatility. |
| Hydrogenated Ester Capacity Expansion | Heat-resistant derivatives unlock automotive underhood applications at premium pricing tiers. |
| Blockchain Traceability Deployment | Batch-level origin documentation satisfies ECHA REACH chain-of-custody verification requirements. |
| BIS Certification Pre-Positioning | Early compliance in India establishes specification authority ahead of formal resin mandates. |
| Direct-to-Formulator Digital Channel | Platform-based procurement bypasses distributor markups for Vietnamese adhesive compounders. |
Study Parameters
A standing panel of pine plantation operations managers, adhesive compounder procurement directors, rosin derivative R&D leads, and European regulatory affairs specialists provided ongoing calibration across the primary research phase. Secondary validation drew from customs trade databases, ECHA REACH registration filings, Chinese MEE environmental audit disclosures, and SEC 10-K extracts from listed chemical processors. Bottom-up volume modeling across product grades and applications triangulated against top-down macroeconomic indicators to ensure internal consistency.
Output consistency was verified against external benchmarks including regional trade flow data and capacity utilization surveys from major producing clusters. The analytical framework segmented the market by product type, application chemistry, end-user industry, and certification grade across the projection horizon. CAGRs were derived from fitted growth curves incorporating regulatory enforcement timelines, plantation expansion economics, and substitution elasticity estimates for petroleum-derived tackifiers.
Forecasts assume regulatory continuity in ECHA REACH tiering, SAMR food-contact standards, and EPA TSCA oversight; material policy shifts would require re-modeling of cross-border shipment economics. Practitioners should keep alternative scenarios live as dual carbon goal enforcement intensity and seasonal labor availability patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Global Lactobionic Acid Market