
 Biocides for Leather Market | 2026-2036
Biocides for Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Biocides for Leather Market Intelligence
Multi-source procurement of active ingredients is restructuring supply relationships across the leather chemicals value chain. Lanxess AG leverages its backward integration into bromine derivatives to control cost volatility in bactericide production. BASF SE anchors European supply through its Ludwigshafen manufacturing complex, while Troy Corporation specializes in niche antifungal formulations for high-humidity tanning environments.
Biocides for leather comprise antimicrobial chemical agents—typically isothiazolinones, phenolic compounds, or organometallic complexes—applied during wet processing to prevent microbial degradation of collagen matrices. These substances function by disrupting cellular membranes or inhibiting enzymatic pathways in bacteria and fungi, preserving hide integrity from beamhouse through post-tanning stages. Organic biocides occupy the dominant revenue position due to broad-spectrum efficacy, though nanotechnology-based delivery systems represent the fastest-growing technology segment as tanners pursue reduced active-ingredient loadings. Application-level demand concentrates in tanning and preservation, where microbial control determines yield rates and downstream defect incidence.
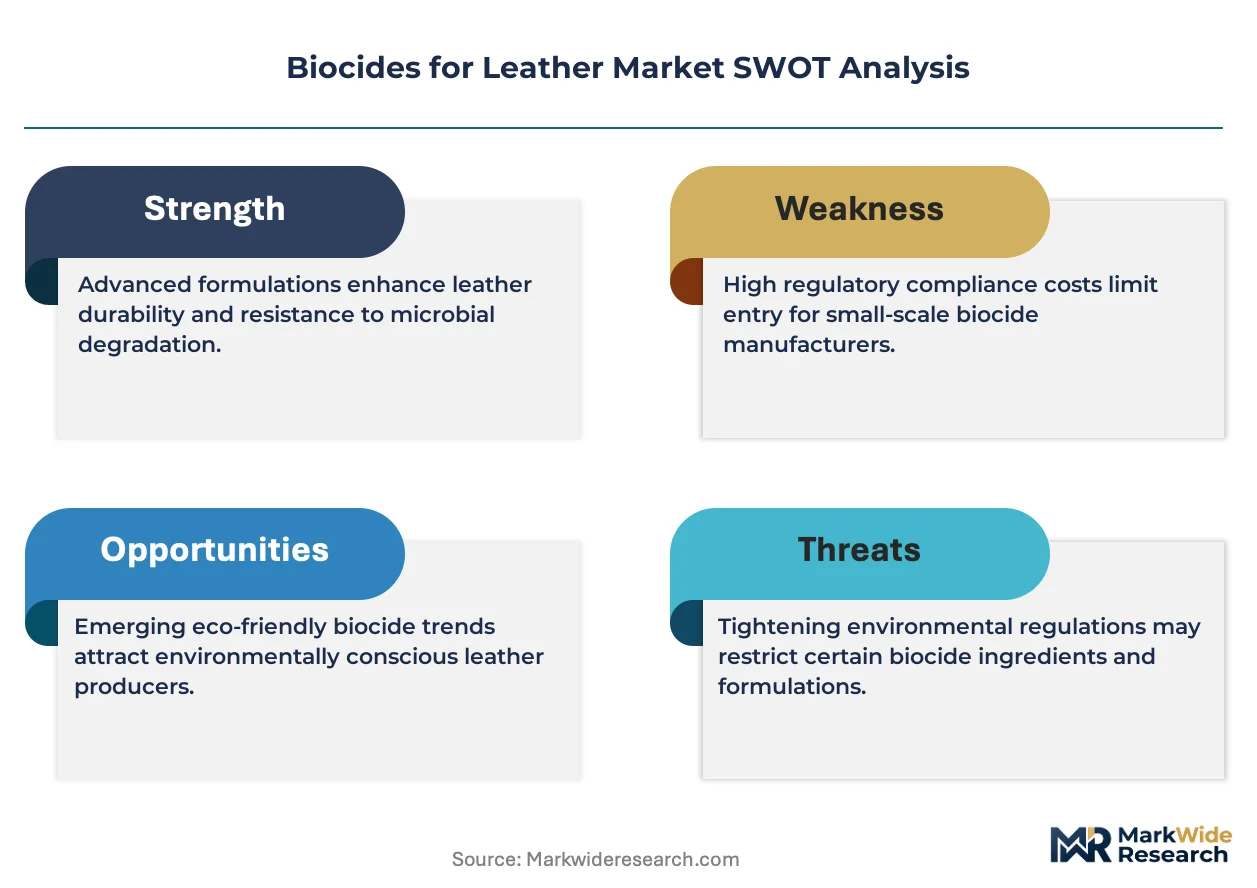
REACH registration requirements and the EU Biocidal Products Regulation govern active-substance approval cycles across European leather-producing regions, while EPA FIFRA registrations shape market access for US-formulated products. China's MEE enforces discharge standards that limit residual biocide concentrations in tannery effluent, redirecting investment toward biodegradable alternatives. Stakeholders must monitor evolving substance ban schedules and align R&D pipelines with regulatory pre-approval timelines to avoid portfolio obsolescence.
Market Dynamics
REACH substance review cycles and the EU Green Deal's biocide residue mandates are forcing tanneries to rebuild formulation portfolios from active ingredients upward, compressing approval timelines and supplier qualification windows simultaneously.
Growth Catalysts
- REACH authorization pressures:European tanneries accelerate adoption of pre-approved alternative chemistries to maintain market access, pulling demand toward ECHA-registered substances.
- Footwear hygiene specifications:Athletic and luxury shoe manufacturers now mandate antimicrobial-treated hides in procurement contracts, transmitting requirements upstream to beamhouse operations.
- Italy's Arzignano cluster concentration:Chemical suppliers co-locating with premium finishing operations enable rapid technical service response and joint formulation development.
Market Restraints
- Bromine derivative cost volatility:Backward-integrated producers control input costs while non-integrated formulators face margin compression from spot market exposure.
- Active substance approval timelines:ECHA's 3-5 year biocidal product authorization cycles delay new chemistry commercialization and extend payback periods.
- Water-based system performance gaps:Solvent-phase biocides retain efficacy advantages in fat-liquoring stages where aqueous alternatives show reduced penetration.
Strategic Opportunities
- Brazilian tannery modernization:Underpenetrated preservation chemical usage in São Paulo and Rio Grande do Sul processing hubs creates technical upgrade potential.
- Automotive interior specifications:OEM antimicrobial standards for leather seating surfaces open dedicated supply contracts distinct from footwear-grade formulations.
- Nanotechnology-biocide convergence:Encapsulation systems enabling reduced active-ingredient loadings align with MEE discharge limits in Chinese tannery clusters.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in collagen-matrix compatibility and effluent behavior commands premium compensation and extends hiring cycles.
- Legacy equipment retrofit requirements:Precision dosing systems for microencapsulated biocides demand capital outlays that mid-scale tanneries defer.
- Cross-border registration synchronization:Divergent EPA FIFRA and ECHA data requirements force duplicate toxicology studies and extend compliance calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocides for Leather Market |
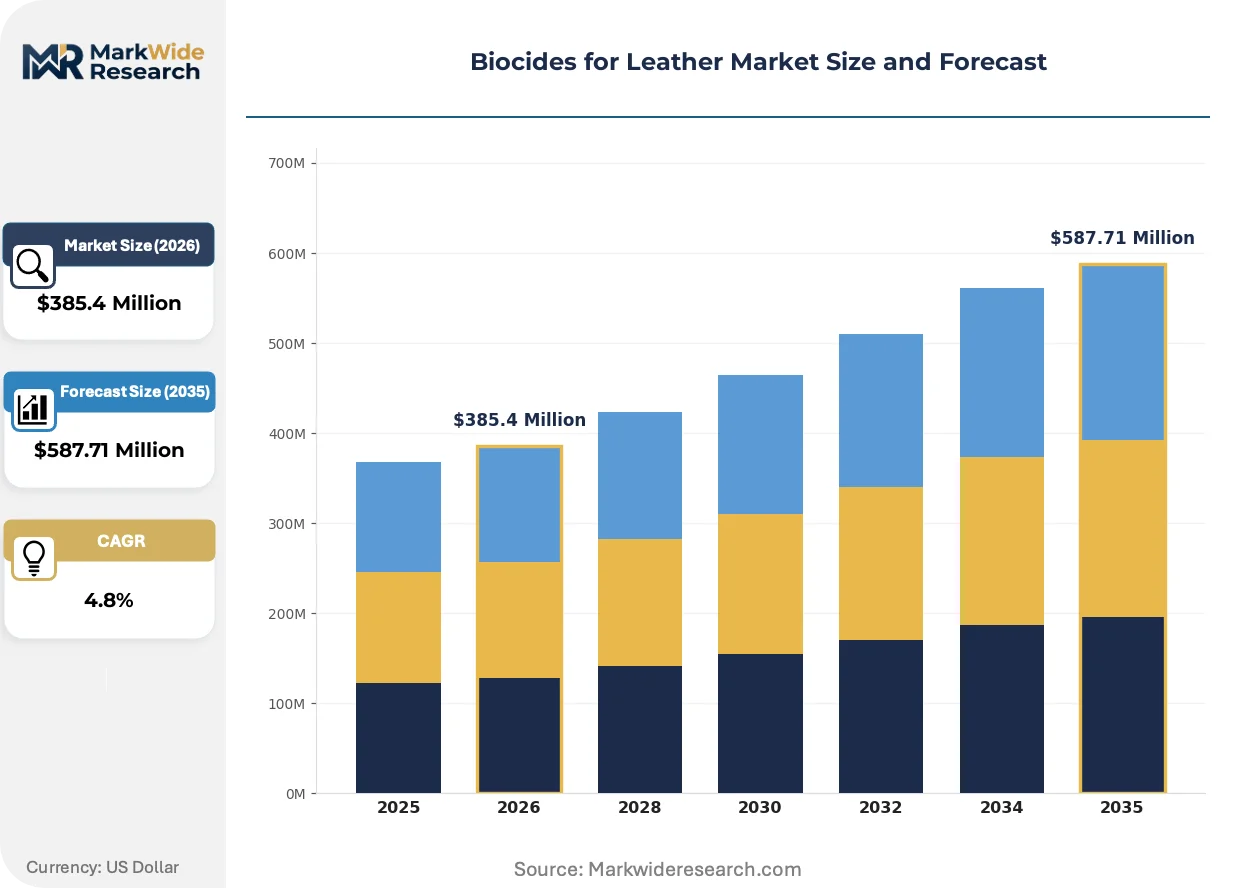
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Biocides, Inorganic Biocides, Antifungal Agents, Bactericides Application: Tanning, Preservation, Finishing, Cleaning End User: Footwear Manufacturers, Apparel Producers, Upholstery Firms, Leather Goods Producers Technology: Biochemical Methods, Physical Methods, Chemical Synthesis, Nanotechnology |
| Companies Covered | Lanxess AG, BASF SE, Troy Corporation, DuPont de Nemours, Inc., Vink Chemicals GmbH & Co. KG, Clariant AG, Archroma Management LLC, Huntsman International LLC, ICL Performance Products LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocides for Leather Market Strategic Shifts & Innovations
Formulation science is pivoting from broad-spectrum potency toward precision delivery systems that satisfy residue thresholds without sacrificing microbial control efficacy across wet processing stages.
Microencapsulation technology is expanding into beamhouse and preservation applications through controlled-release architectures that maintain protective concentrations over extended soaking periods. Italian and Spanish tanneries serving automotive OEMs are piloting these systems at commercial scale. The approach is compressing active-ingredient consumption rates by 30-40% compared to conventional dosing while meeting stricter effluent parameters.
ECHA's 2024-2027 substance evaluation roadmap is accelerating substitution pressures for isothiazolinone-class biocides in European leather finishing. Tanneries in Germany and the Netherlands face reformulation deadlines that compress qualification windows for alternative chemistries. High-value upholstery and glove segments are absorbing premium pricing for REACH-compliant formulations that maintain antifungal performance.
Footwear brand technical specifications are displacing generic commodity procurement across Asian tanning operations. Buyers now require batch-level efficacy documentation and third-party antimicrobial certification rather than supplier declarations. This pattern concentrates contract awards among chemical houses with in-house testing capabilities, visible most acutely in Vietnam and Indonesia export-processing zones supplying European retail chains.
Biocides for Leather Market Segmentation
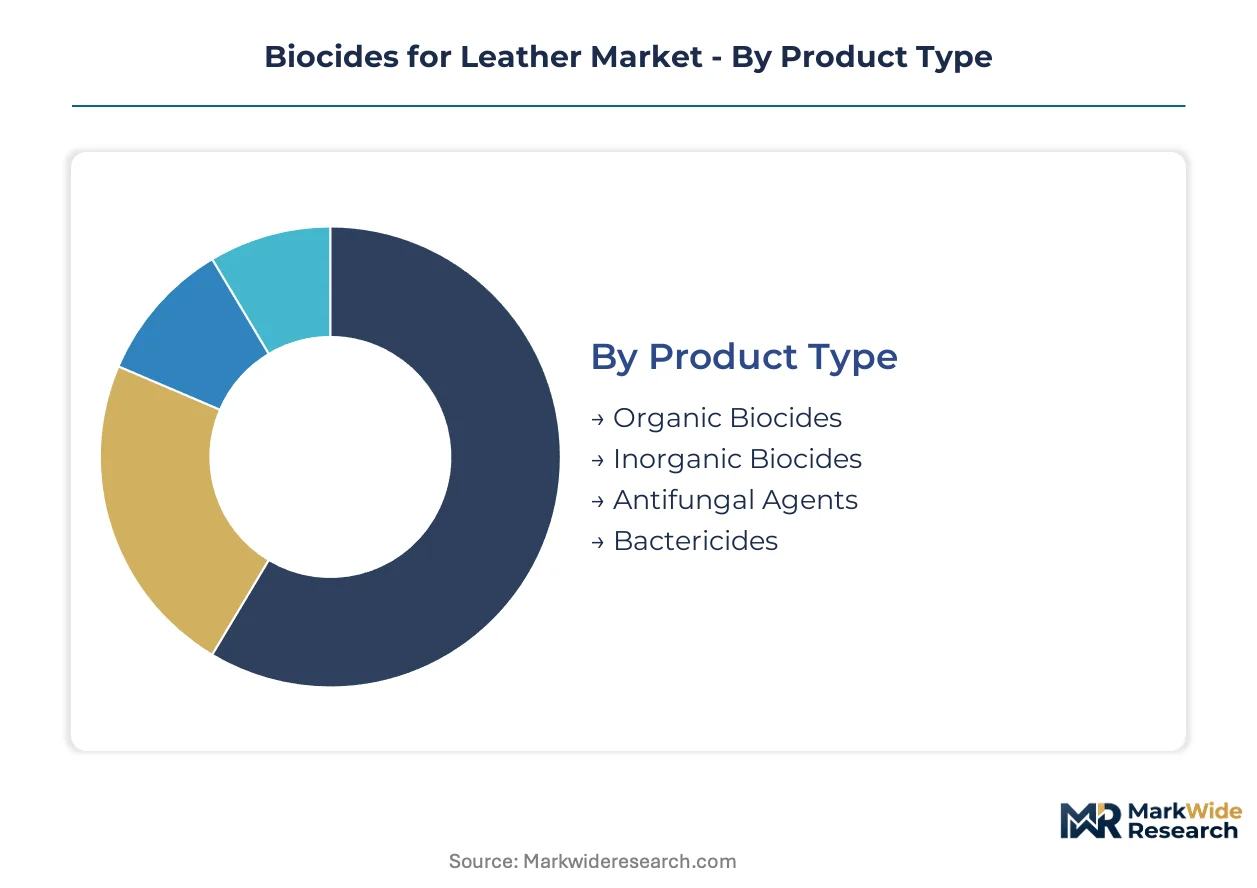
Leather biocide procurement patterns diverge sharply across product chemistry and processing stage, with regulatory pressure and end-use specifications driving segment-specific upgrade cycles. Tanneries must rebuild formulation portfolios around approved active substances while meeting brand-level antimicrobial documentation requirements.
Product Type:
Reformulation timelines compress as REACH substance evaluations force tanneries to replace legacy chemistries with pre-registered alternatives, reshaping procurement priorities across organic and inorganic categories.
- Organic Biocides:Isothiazolinone and phenolic compound formulations deliver broad-spectrum efficacy against bacterial and fungal degradation of collagen matrices. Demand concentrates in Italian Arzignano cluster tanneries serving luxury automotive OEMs, where REACH-compliant pre-approval status commands contract premiums.
- Inorganic Biocides:Organometallic complexes and metal salt derivatives provide durable antimicrobial protection in high-humidity preservation environments. Adoption is accelerating in Brazilian São Paulo processing hubs upgrading from underpenetrated traditional preservation methods to meet export certification standards.
- Antifungal Agents:Specialized azole and thiocarbamate formulations target dermatophyte and mold species in finished leather goods.
- Bactericides:Quaternary ammonium and halogenated compounds address gram-positive and gram-negative bacterial contamination during wet processing stages.
Volume placements concentrate in Organic Biocides; the faster expansion belongs to Inorganic Biocides.
Application:
Processing stage determines biocide specification intensity, with beamhouse operations requiring sustained antimicrobial concentration against putrefactive bacteria.
- Tanning:Chrome and vegetable tanning liquors incorporate biocides to prevent bacterial attack on pickled hides during prolonged drum processing. Italian and Spanish tanneries pilot microencapsulated delivery systems that reduce active-ingredient consumption while maintaining protective concentrations.
- Preservation:Salt-cured and dried hides receive antimicrobial treatment to arrest degradation during storage and transit. Brazilian modernization programs in Rio Grande do Sul are expanding chemical preservation penetration beyond traditional salting methods.
- Finishing:Post-tanning surface applications provide final antimicrobial protection for upholstery and glove leather segments.
- Cleaning:Maintenance biocide formulations extend service life of finished leather goods in consumer and institutional applications.
Procurement value clusters in Tanning; Preservation shows the steepest expansion trajectory as export-oriented tanneries upgrade infrastructure.
End User:
Brand technical specifications are displacing generic commodity procurement, with batch-level efficacy documentation becoming mandatory for contract qualification.
- Footwear Manufacturers:Athletic and luxury shoe brands now mandate antimicrobial-treated hides in procurement contracts, transmitting requirements upstream to beamhouse operations. Vietnam and Indonesia export-processing zones serving European retail chains concentrate demand among chemical houses with in-house testing capabilities.
- Apparel Producers:Garment leather applications require biocide compatibility with dyeing and softening chemistries.
- Upholstery Firms:High-value furniture and automotive seating segments absorb premium pricing for REACH-compliant formulations that maintain antifungal performance through extended service life.
- Leather Goods Producers:Handbag and accessory manufacturers prioritize surface finish compatibility and consumer safety certification.
Contract awards concentrate in Footwear Manufacturers; Upholstery Firms are climbing the fastest as automotive OEM antimicrobial standards proliferate.
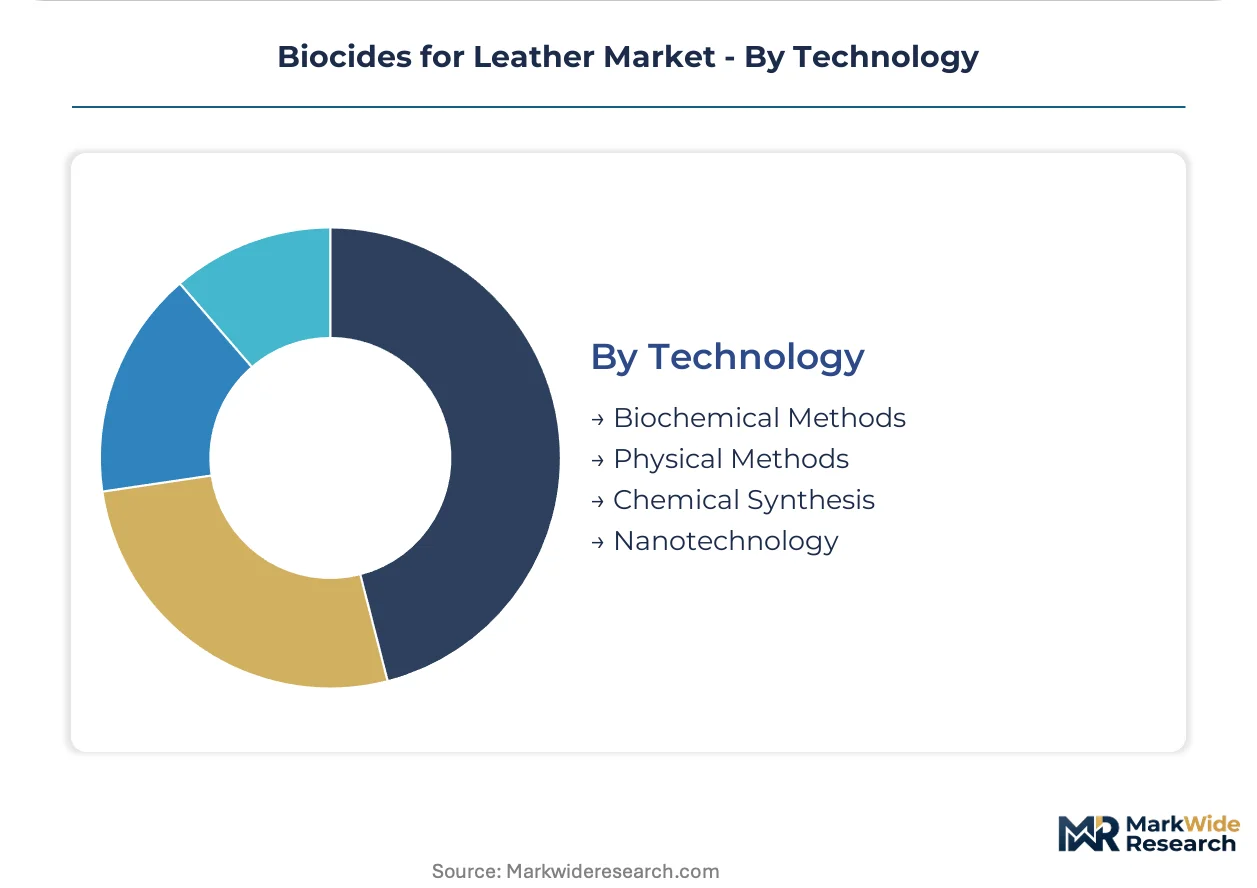
Technology:
Delivery system innovation determines competitive positioning, with precision release architectures enabling compliance with tightening effluent discharge limits.
- Nanotechnology:Encapsulation systems and controlled-release architectures enable 30-40% reduction in active-ingredient loadings while maintaining protective concentrations. Chinese tannery clusters under MEE discharge standards redirect investment toward these biodegradable-compatible alternatives.
- Chemical Synthesis:Conventional organic and inorganic synthesis routes dominate current production volumes through established cost structures.
- Biochemical Methods:Enzyme-based and bio-derived antimicrobial approaches target niche applications in premium natural leather positioning.
- Physical Methods:Irradiation and thermal treatments provide non-chemical alternatives for specific preservation scenarios.
Investment flows concentrate in Chemical Synthesis; Nanotechnology is gaining share fastest as regulatory pressure intensifies across major producing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian and Indian hide processing centers anchor raw-material flows into biocide-consuming tanneries, while European finishing clusters concentrate value-added formulation demand. Regulatory divergence across these production zones creates distinct procurement patterns for antimicrobial chemistries.
Italy
Arzignano's leather cluster drives premium biocide consumption for automotive and luxury footwear applications. REACH substance evaluation timelines compress reformulation windows for tanneries serving EU markets. Chemical suppliers co-locate with beamhouse operations to enable rapid technical service response.
China
Yangtze River Delta tanneries face MEE discharge standards that redirect investment toward biodegradable biocide alternatives. Export-oriented processors in Wenzhou and Haining upgrade preservation protocols to meet brand-level antimicrobial documentation requirements. Nanotechnology-based delivery systems gain traction as tanners pursue reduced active-ingredient loadings.
Brazil
São Paulo and Rio Grande do Sul processing hubs modernize underpenetrated preservation chemical usage to meet export certification standards. National agricultural regulators enforce residue thresholds on finished leather destined for European retail chains. Local tannery associations coordinate technical training programs for beamhouse biocide application.
Germany
Ludwigshafen chemical manufacturing anchors European supply for bromine-derived bactericides. ECHA authorization pressures accelerate adoption of pre-approved alternative chemistries among domestic tanneries. Bavarian automotive leather finishers pilot microencapsulated delivery systems at commercial scale.
Vietnam
Export-processing zones serving European retail chains concentrate demand among chemical houses with in-house testing capabilities. Footwear brand technical specifications displace generic commodity procurement across Ho Chi Minh City and Dong Nai tanning operations. Provincial environmental bureaus tighten effluent monitoring for biocide residues.
Biocides for Leather Market Key Industry Players
Global majors compete with regional champions across formulation development and technical service capabilities. Market structure tilts toward consolidated supply at the active-ingredient level and fragmented distribution at the tannery interface. Three archetypes dominate: backward-integrated bromine producers controlling input cost volatility, diversified chemical conglomerates anchoring regional supply networks, and niche specialists in antifungal formulations for high-humidity environments. Competitive moves center on co-location with premium tanning clusters and pre-registration of alternative chemistries ahead of REACH substance bans.
Within the diversified chemical tier, BASF SE and Lanxess AG exemplify scale-driven positioning across European leather-producing regions. Troy Corporation occupies a specialist position in antifungal formulation architectures. These three entities represent distinct strategic postures: conglomerate breadth, backward-integrated raw-material control, and targeted humidity-environment expertise.
| Leading Market Players |
|---|
| Lanxess AG |
| BASF SE |
| Troy Corporation |
| DuPont de Nemours, Inc. |
| Vink Chemicals GmbH & Co. KG |
| Clariant AG |
| Archroma Management LLC |
| Huntsman International LLC |
| ICL Performance Products LP |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap chemical formulators across Italy's Arzignano cluster maintain pricing discipline through captive technical service relationships, while their financing constraints limit capacity expansion and concentrate supply leverage with backward-integrated majors.
Pricing Analysis
Technical service bundling separates premium REACH-compliant formulations from unbundled commodity biocides in spot markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with automotive OEM contracts absorbing 40-60% premiums over footwear-grade equivalents. Cost compression in standard-tier bactericides is intensifying because Brazilian tannery modernization programs expand procurement volumes. Mid-scale beamhouse operators in Vietnam and Indonesia show highest price sensitivity, while luxury automotive finishers in Germany and Italy demonstrate inelastic demand for documented efficacy.
Supply Chain Analysis
Bromine derivative supply rests on German and Israeli specialty chemical producers, with organometallic active ingredients drawing from Chinese and Indian metal salt processors. Raw material dependencies span bromine brine extraction, thiazole intermediate synthesis, and microencapsulation polymer feedstocks. Single-source vulnerability concentrates in isothiazolinone precursor supply from Ludwigshafen-based manufacturing complexes. Distribution runs through regional chemical distributors co-located with tanning clusters, with direct supply agreements dominating premium formulation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance evaluation timelines and ECHA authorization pressures are forcing consolidation as non-integrated formulators face portfolio obsolescence and margin compression from extended approval cycles.
For Market Incumbents: Deepen backward integration into bromine derivatives or thiazole intermediates to control input cost volatility that erodes formulator margins. Accelerate pre-registration of alternative chemistries ahead of ECHA's 2024-2027 substance evaluation roadmap to defend market access. Prioritize co-location with Vietnam and Indonesia export-processing zones where footwear brand technical specifications concentrate contract awards among suppliers with in-house testing capabilities. For New Entrants and Emerging Players: The price-point gap between premium REACH-compliant formulations and economy-grade commodity biocides offers entry space for mid-tier specialists. Target Brazilian São Paulo and Rio Grande do Sul processing hubs where underpenetrated preservation chemical usage creates technical upgrade potential absent entrenched supplier relationships. Lead with nanotechnology-based delivery systems that satisfy MEE discharge standards while commanding 15-25% formulation premiums over conventional chemistries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Italian formulators facing REACH compliance cost burdens in Arzignano cluster proximity. Long-term viability over the analysis window hinges on regulatory pre-approval pipelines and automotive OEM qualification status. Watch ECHA substance ban announcements as inflection indicators that trigger accelerated M&A activity among cash-constrained specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Derivatives | Ludwigshafen-based producers control cost volatility that compresses non-integrated formulator margins. |
| REACH Pre-Registration of Alternative Chemistries | ECHA authorization timelines force portfolio rebuilding before isothiazolinone-class substance evaluations conclude. |
| Co-Location with Vietnam Export-Processing Zones | Footwear brand technical specifications concentrate contract awards among proximate suppliers with testing capabilities. |
| Microencapsulation Technology Licensing | Italian and Spanish automotive finishers pilot controlled-release systems that reduce active-ingredient consumption. |
| Long-Term Supply Agreements with Brazilian Tanneries | São Paulo modernization programs expand chemical preservation penetration beyond traditional salting methods. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among beamhouse operations managers, leather chemical procurement leads, ECHA regulatory affairs specialists, and automotive OEM material qualification engineers. Cefic sector reports, ECHA biocidal product registration databases, and Italian tannery association technical bulletins provided demand-side validation. Bottom-up volume estimates from tanning stage consumption rates triangulated against top-down chemical supplier revenue allocations.
Data-stream reconciliation across product chemistry, application stage, and end-use segmentation yielded volume and value outputs over the projection horizon. Modeled dimensions span organic versus inorganic biocide categories, beamhouse through finishing applications, and footwear versus automotive upholstery demand clusters. CAGRs derived from regression analysis against hide processing volumes and regulatory substitution timelines, with nanotechnology delivery system adoption curves incorporating MEE discharge standard compliance rates.
Inputs from ECHA registration databases and Brazilian tannery association surveys were available through the study window; gaps in proprietary formulation cost structures introduce uncertainty bands around supplier margin estimates. Forecasts reflect assumptions on REACH substance ban schedules and brand-level antimicrobial documentation adoption rates. Regulatory acceleration or delay in ECHA authorization timelines, plus footwear brand specification changes, constitute trigger factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Specialty Methacrylate Market