
 Fire Retardant Flexible Cable Market | 2026-2036
Fire Retardant Flexible Cable Market Size, Share, and Industry Trends Forecast 2026-2036
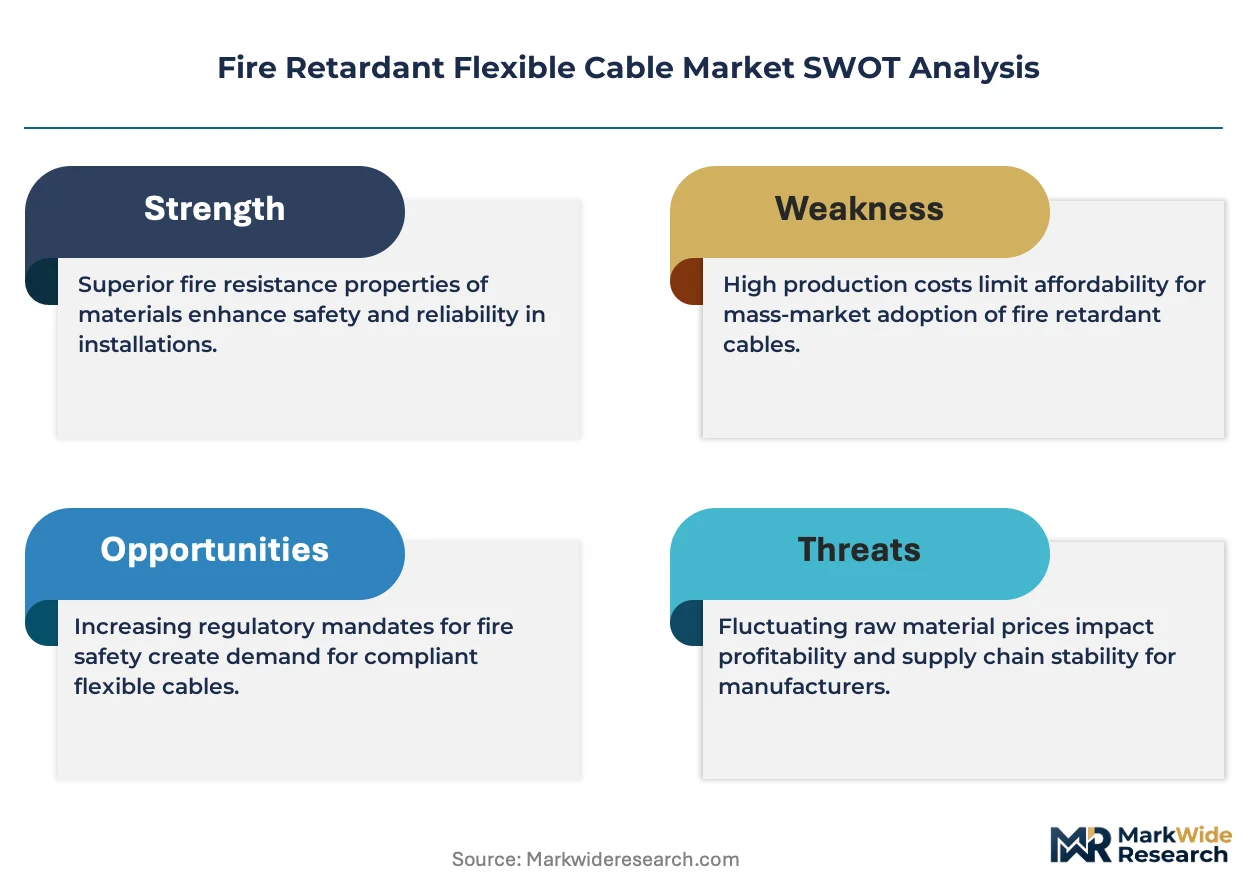
Fire Retardant Flexible Cable Market Analysis
Aftermarket cable inspection and certification revenue is reshaping profitability models across the value chain. Prysmian Group leverages its global testing laboratory network to capture recurring service contracts. Nexans anchors European utility replacement cycles through long-term maintenance agreements. LS Cable & System competes in Asian infrastructure tenders by bundling installation support with multi-decade performance warranties.
Fire retardant flexible cable combines halogen-free or low-smoke zero-halogen insulation with stranded copper conductors rated for repeated bending and elevated temperatures, typically manufactured through continuous vulcanization or silane cross-linking to maintain flexibility under mechanical stress while limiting flame propagation and toxic fume emission during combustion. Low voltage grades dominate volume in building infrastructure applications where conduit routing demands tight bending radii, while medium voltage specialty cables command premium positioning in marine and offshore platforms where fire performance must coexist with oil resistance and saltwater durability. Cross-linked polyethylene technology leads industrial equipment segments due to superior thermal aging characteristics, whereas thermoplastic elastomer formulations gain share in automotive wiring harnesses requiring cold-flex performance down to minus forty degrees Celsius.
Underwriters Laboratories UL 94 vertical burn standards and IEC 60332 flame spread protocols define minimum product acceptance thresholds in North American and European procurement specifications, while China's GB/T 19666 mandatory fire resistance ratings for public buildings create a bifurcated compliance landscape that favors manufacturers with multi-certification testing capabilities. India's BIS IS 694 and IS 7098 standards enforce low-smoke emission requirements in metro rail and hospital projects, tightening market access for uncertified imports. Stakeholders must monitor regulatory divergence between halogen-free material mandates in the European Union and cost-driven tolerance for PVC alternatives in emerging Asian construction markets when allocating R&D and certification budgets.
Market Dynamics
Halogen-free compound formulations are restructuring procurement specifications across commercial construction, as developers face tightening fire safety mandates that disqualify traditional PVC-insulated alternatives from high-occupancy building tenders.
Growth Catalysts
- Urban rail electrification:China's state-backed infrastructure mandates require fire-resistant cabling for metro expansion projects, creating sustained demand for low-smoke zero-halogen grades in tunnel and station applications.
- IEC 60332 flame spread protocols:European procurement specifications increasingly embed these testing standards into public building contracts, filtering supplier pools to certified manufacturers.
- Continuous vulcanization:This manufacturing process enables tighter bending radii in building infrastructure while maintaining thermal stability, opening specification opportunities in dense conduit routing.
Market Restraints
- Copper price volatility:Stranded conductor costs fluctuate with commodity markets, compressing margin stability for cable producers locked into long-term infrastructure contracts.
- Multi-certification testing burden:Divergent GB/T 19666, UL 94, and BIS IS 694 standards force redundant laboratory investments, raising fixed costs for market entry.
- Thermoplastic elastomer substitution:Cold-flex formulations for automotive wiring harnesses compete for polymer supply with fire-retardant grades, creating input competition.
Strategic Opportunities
- Saudi commercial construction:Giga-project developments specify halogen-free compounds to meet evolving fire safety codes, creating premium positioning for certified suppliers.
- Aftermarket certification services:Testing laboratory networks capture recurring revenue through multi-decade performance warranty validation and inspection contracts.
- Silane cross-linking convergence:Integration with thermoplastic elastomer formulations enables dual-performance cables serving both elevated temperature and sub-zero flex applications.
Industry Challenges
- Cross-linked polyethylene process engineering:Specialized thermal aging expertise remains concentrated among experienced compounders, constraining capacity expansion timelines.
- Multi-jurisdiction certification synchronization:Parallel GB/T, IEC, and BIS approval processes extend product launch cycles by 12-18 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Retardant Flexible Cable Market |
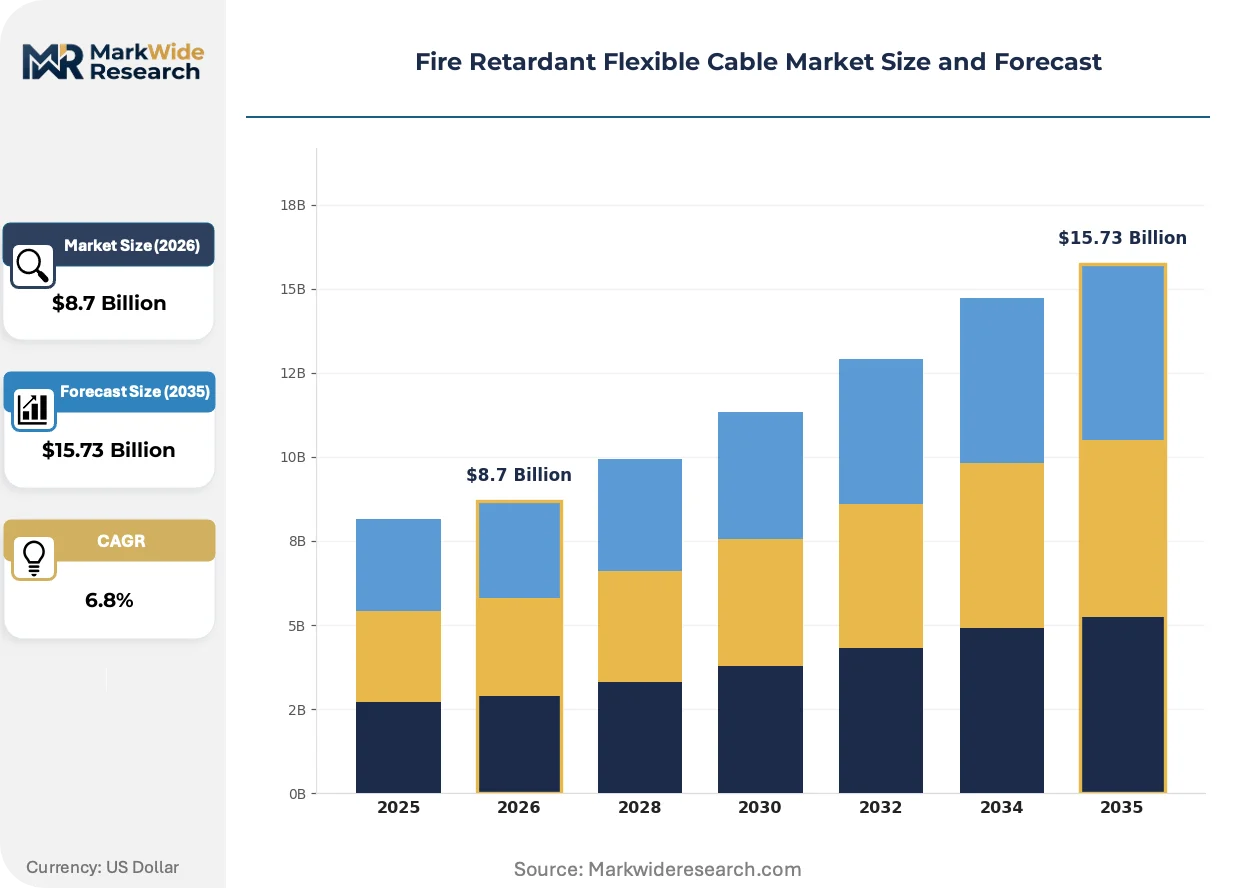
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Cables End User: Construction, Automotive, Marine, Aerospace Application: Electrical Wiring, Building Infrastructure, Industrial Equipment, Transportation Systems Technology: Polyvinyl Chloride, Cross-Linked Polyethylene, Thermoplastic Elastomers, Others |
| Companies Covered | Prysmian Group, Nexans, LS Cable & System, Lapp Group, HellermannTyton, V-GUARD INDUSTRIES, Havells India, Eland Cables, RSCC Wire and Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Retardant Flexible Cable Market Emerging Trajectories
Material science advances and procurement specification tightening are compressing the viable technology set for fire-rated flexible applications, favoring suppliers with integrated compound development and certification capabilities.
Silane cross-linking is collapsing the performance gap between thermoset and thermoplastic insulation systems. Marine and offshore platform contractors specify these hybrid formulations for combined oil resistance and saltwater durability. The technology is collapsing traditional grade boundaries that previously segmented low-voltage building cable from medium-voltage specialty applications.
REACH substance restrictions on halogenated flame retardants are forcing compound reformulation across European supply chains. Manufacturers face raw material qualification timelines that extend product development cycles. The regulatory pressure is most acute in public building segments where CE marking now requires documented low-smoke emission performance under EN 50399 testing protocols.
Maintenance agreement bundling is altering how European utilities engage cable suppliers. Long-term performance warranties displace transactional procurement for replacement cycles. This contractual evolution is most visible in German and French distribution network upgrades, where operators prioritize total cost of ownership over unit pricing.
Fire Retardant Flexible Cable Market Segmentation
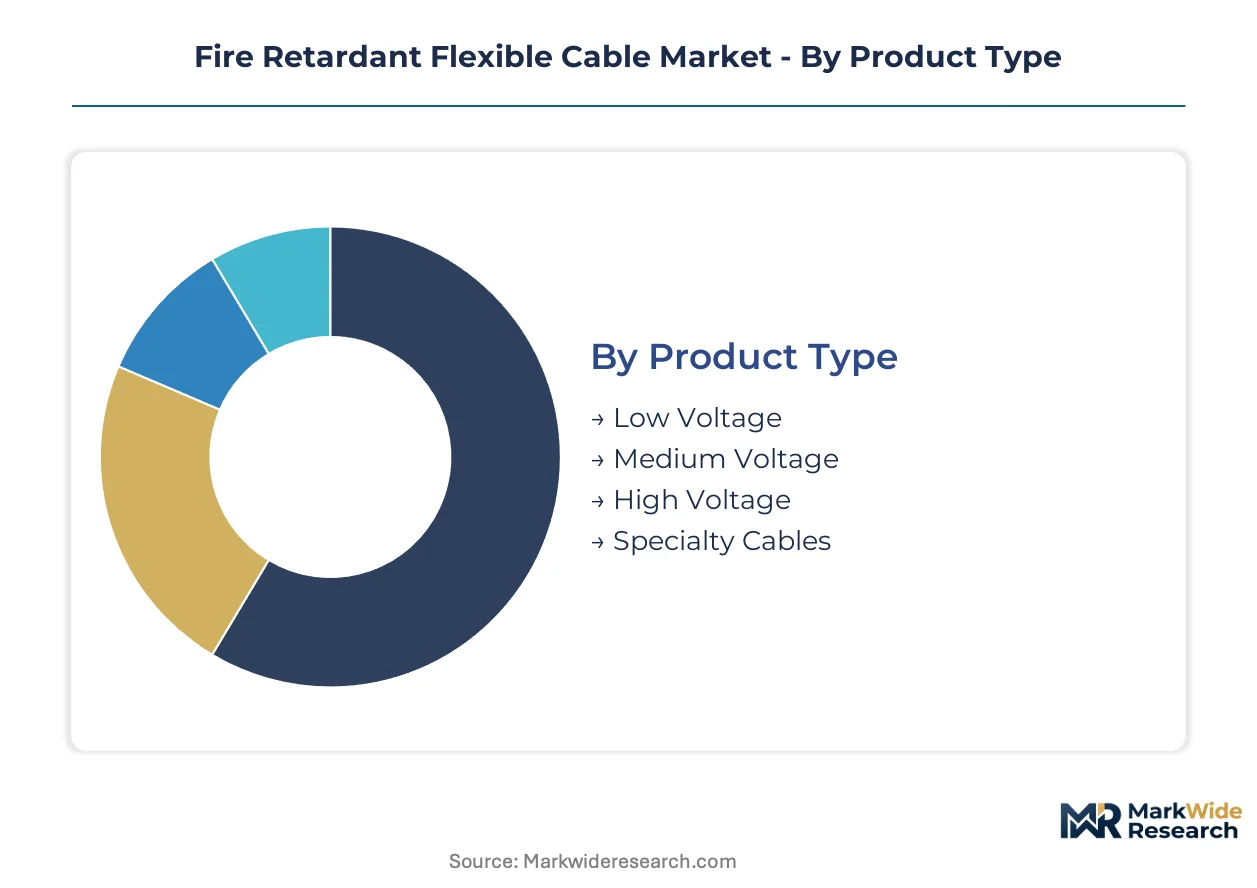
Fire retardant flexible cable segmentation reflects divergent service intensity across voltage classes and end-use environments. Procurement patterns in construction and transportation create distinct aftermarket revenue streams that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply by voltage rating, with medium voltage installations demanding multi-decade inspection contracts and low voltage projects generating volume-driven replacement cycles.
- Low Voltage:Halogen-free insulation with stranded copper conductors rated for repeated bending dominates building infrastructure where tight conduit routing requires tight bending radii. Demand concentrates in China's state-backed metro expansion and Saudi giga-project commercial construction driven by evolving fire safety codes mandating low-smoke zero-halogen grades.
- Medium Voltage:Cross-linked polyethylene technology delivers superior thermal aging characteristics for industrial equipment and offshore platforms where fire performance must coexist with oil resistance. Marine contractors in European waters specify these cables for combined saltwater durability and flame spread compliance under IEC 60332 protocols.
- High Voltage:Specialized formulations for utility-scale transmission with enhanced thermal stability requirements.
- Specialty Cables:Custom-engineered solutions for extreme environments including sub-zero automotive applications and aerospace weight-critical installations.
Low voltage holds the largest share; momentum sits with medium voltage as marine and offshore specifications tighten.
End User:
Cost tier differentiation separates specification-grade construction projects from price-sensitive automotive volume contracts.
- Construction:Commercial developers in the Middle East specify halogen-free compounds to meet evolving fire safety codes, creating premium positioning for certified suppliers. China's urban rail mandates sustain demand for low-smoke zero-halogen grades in tunnel and station applications.
- Automotive:Thermoplastic elastomer formulations gain share in wiring harnesses requiring cold-flex performance down to minus forty degrees Celsius. European OEM procurement prioritizes REACH-compliant compounds as substance restrictions force reformulation timelines.
- Marine:Offshore platform contractors demand combined oil resistance and saltwater durability through silane cross-linking technology.
- Aerospace:Weight-optimized specialty cables with stringent smoke emission and toxicity requirements for cabin safety.
Construction commands the premium tier; automotive offers the steepest expansion trajectory as electrification multiplies cable counts per vehicle.
Application:
Volume concentration in building infrastructure contrasts with margin-rich industrial equipment segments where performance warranties extend contractual horizons.
- Electrical Wiring:General-purpose installations across residential and commercial structures with baseline fire retardant requirements.
- Building Infrastructure:Dense conduit routing in high-occupancy buildings drives continuous vulcanization adoption for tighter bending radii. India's BIS IS 694 and IS 7098 standards enforce low-smoke emission requirements in metro rail and hospital projects.
- Industrial Equipment:Cross-linked polyethylene leads due to superior thermal aging characteristics in manufacturing environments. European utilities anchor replacement cycles through long-term maintenance agreements that displace transactional procurement.
- Transportation Systems:Combined mechanical stress and fire performance requirements for rail, marine, and aerospace mobility platforms.
Building infrastructure dominates volume; industrial equipment captures the fastest margin expansion through warranty bundling.
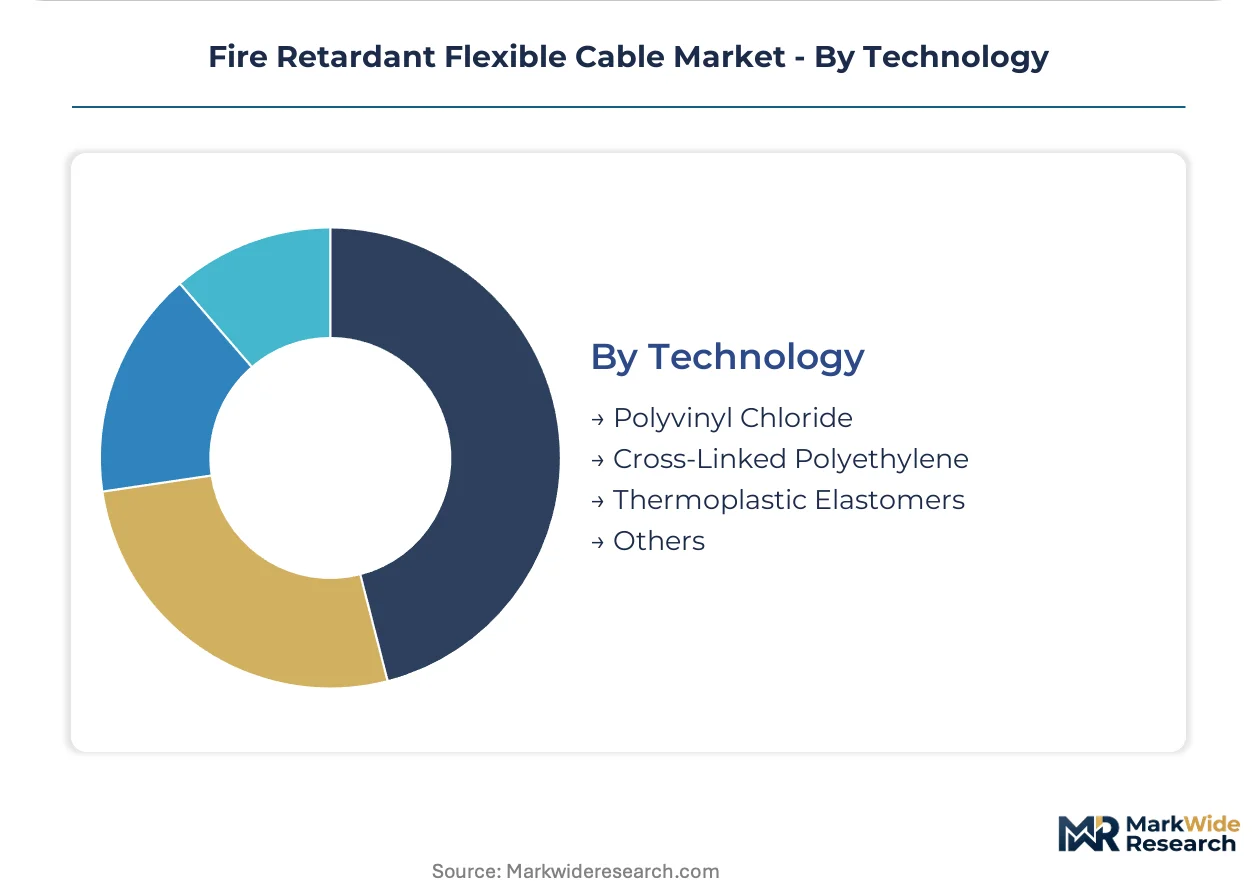
Technology:
Material maturity curves separate established thermoset processes from emerging thermoplastic formulations competing for polymer supply.
- Polyvinyl Chloride:Cost-driven tolerance persists in emerging Asian construction markets despite disqualification from high-occupancy tenders under tightening halogen-free mandates.
- Cross-Linked Polyethylene:Superior thermal aging characteristics concentrate expertise among experienced compounders, constraining capacity expansion timelines. The technology leads industrial equipment segments and commands premium positioning in medium voltage applications.
- Thermoplastic Elastomers:Cold-flex formulations for automotive wiring harnesses compete for polymer supply with fire-retardant grades, creating input competition. Silane cross-linking convergence enables dual-performance cables serving both elevated temperature and sub-zero flex applications.
- Others:Emerging halogen-free compounds including ethylene propylene rubber and silicone-based formulations for niche thermal and chemical resistance requirements.
Cross-linked polyethylene holds installed base dominance; thermoplastic elastomers are climbing the fastest as automotive cold-flex specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit the sharpest price sensitivity on copper-intensive contracts, while Middle Eastern developers absorb premium halogen-free grades without volume elasticity. European utilities anchor the least price-sensitive demand tier through long-term maintenance agreements.
China
State-backed urban rail mandates sustain demand for low-smoke zero-halogen grades in tunnel and station applications. GB/T 19666 mandatory fire resistance ratings for public buildings tighten compliance requirements. Yangtze River Delta manufacturers concentrate capacity expansion to serve metro electrification projects across Shanghai and Jiangsu province.
Germany
European utility replacement cycles anchor premium demand through long-term maintenance agreements that displace transactional procurement. REACH substance restrictions on halogenated flame retardants force compound reformulation across supply chains. Industrial clusters in North Rhine-Westphalia concentrate cross-linked polyethylene expertise among experienced compounders serving distribution network upgrades.
United States
Underwriters Laboratories UL 94 vertical burn standards filter supplier pools in public building contracts. Commercial construction in high-occupancy segments drives specification-grade procurement despite copper price volatility. Gulf Coast petrochemical corridors generate demand for medium voltage specialty cables combining fire performance with oil resistance.
Saudi Arabia
Giga-project commercial developments specify halogen-free compounds to meet evolving fire safety codes, creating premium positioning for certified suppliers. The country's national standards regulator enforces low-smoke emission requirements in high-occupancy structures. NEOM Northwest development concentrates demand for multi-certification cables serving smart city infrastructure.
India
Metro rail and hospital projects enforce BIS IS 694 and IS 7098 low-smoke emission standards, tightening market access for uncertified imports. Cost-driven tolerance for PVC alternatives persists in residential construction outside regulated public buildings. Maharashtra and Gujarat industrial corridors concentrate cable fabrication capacity serving domestic infrastructure tenders.
Fire Retardant Flexible Cable Market Vendor Landscape
Capability concentration sits with specialized compounders holding silane cross-linking expertise; scale advantage sits with diversified manufacturers serving multiple voltage classes. The market structures around three tiers: integrated materials-to-cable producers, regional testing-laboratory networks capturing aftermarket revenue, and automotive-focused cold-flex specialists. Dominant competitive moves include multi-certification testing investments compressing product launch cycles, and maintenance agreement bundling displacing transactional procurement in European utilities.
Among European-integrated manufacturers, Prysmian Group and Nexans exemplify the capability-tier archetype through global laboratory networks. LS Cable & System anchors the Asia-Pacific position, representing scale-driven competition in state-backed infrastructure tenders. These three occupy positions across the voltage-class spectrum from low-voltage building infrastructure through medium-voltage industrial applications.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| LS Cable & System |
| Lapp Group |
| HellermannTyton |
| V-GUARD INDUSTRIES |
| Havells India |
| Eland Cables |
| RSCC Wire and Cable |
| Others |
Supply Flow & Price Mechanics
Copper concentrate supply from Chilean and Peruvian mining corridors anchors raw material costs for stranded conductor production, concentrating margin capture with cable manufacturers holding long-term offtake agreements rather than spot-market purchasers. This upstream consolidation funnels pricing power toward integrated producers with captive smelter relationships, while tier-two compounders absorb volatility through shorter contract structures.
Pricing Analysis
Aftermarket certification and multi-decade performance warranty contracts drive lifetime value capture for established testing laboratory networks. Three-tier pricing structure across premium halogen-free, standard low-smoke, and economy PVC grades separates procurement tiers by certification level and after-sales bundling intensity. Pricing pressure stems from copper commodity swings compressing margins on fixed-price infrastructure tenders. European utilities anchored in long-term maintenance agreements exhibit the least price sensitivity, while Indian metro rail contractors negotiate aggressively on copper-intensive volume awards.
Supply Chain Analysis
Extended payment terms from Saudi giga-project developers and supply-chain finance facilities from Chinese state-backed infrastructure funds reshape working capital requirements across the value chain. Manufacturing concentrates in China, Germany, and India for compound development and cable fabrication. Raw material dependencies center on Chilean copper cathodes, South Korean halogen-free polymer feedstock, and German silane cross-linking agents. Single-source vulnerability runs through specialized thermal aging expertise concentrated among experienced European compounders. Distribution runs through certified distributor networks serving project-specified procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through multi-certification testing capabilities creates durable barriers against unqualified entrants.
For Market Incumbents: Build certification moats through parallel GB/T, IEC, and BIS approval investments that extend new entrant launch cycles. Deepen backward integration into halogen-free compound development to secure supply continuity against REACH substance restrictions. Prysmian Group and Nexans exemplify this archetype through global laboratory networks that capture recurring aftermarket revenue. Threat substitution from thermoplastic elastomer cold-flex specialists demands monitoring in automotive electrification segments. For New Entrants and Emerging Players: India's cost-driven residential construction outside BIS-regulated public buildings offers the most penetrable entry corridor for PVC-alternative suppliers. Saudi giga-project commercial developments specify halogen-free compounds but lack sufficient certified local fabrication capacity, creating white-space for testing-laboratory partnerships. Bundle installation support with multi-decade performance warranties to mimic incumbent contractual structures in European utility replacement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silane cross-linking and continuous vulcanization equipment upgrades as manufacturers converge thermoset and thermoplastic capabilities. Long-term viability favors targets with integrated compound-to-cable production and established multi-certification portfolios. Watch for inflection signals in BIS enforcement timelines for Indian hospital and metro rail projects, which would accelerate formal market access requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Testing Investment | Parallel GB/T, IEC, and BIS approvals compress product launch cycles against unqualified competitors. |
| Backward Integration into Compound Development | In-house halogen-free formulation secures supply continuity under REACH substance restrictions. |
| Aftermarket Service Network Expansion | Testing laboratory footprints capture recurring revenue from multi-decade performance warranty validation. |
| Silane Cross-Linking Capacity Addition | Hybrid thermoset-thermoplastic capabilities serve combined elevated temperature and cold-flex specifications. |
| Long-Term Maintenance Agreement Bundling | European utility replacement cycles displace transactional procurement through total cost of ownership contracts. |
Methodological Framework
Cross-validation between primary interviews with cable procurement officers at European utilities, compound development directors at Asian manufacturers, and certification laboratory managers anchors the qualitative findings. Secondary validation draws from BIS filing databases, IEC standard revision records, SEC 10-K disclosures from listed cable producers, and customs trade data for copper concentrate flows. Bottom-up project pipeline assessments triangulate against top-down voltage-class demand modeling.
Calibration against historical certification timeline data and copper price elasticity studies refines volume and value outputs across the analysis window. Segmentation dimensions span voltage rating, end-use environment, insulation technology, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to metro electrification project pipelines, commercial construction permit flows, and automotive wiring harness content expansion. Industry-specific inputs include GB/T 19666 enforcement trajectory and REACH substance restriction implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by capital-rich diversified industrials would shift outcomes. Macroeconomic deviation in copper markets, regulatory acceleration in Indian BIS enforcement, or technological breakthrough in thermoplastic elastomer fire-performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Fire Protective Materials Market