
 Guanidine Carbonate Market | 2026-2036
Guanidine Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Guanidine Carbonate Market Analysis
Pharmaceutical-grade specification tiers is unwinding across the guanidine carbonate value chain as downstream API makers enforce tighter purity thresholds. AlzChem AG leverages its European manufacturing base to supply high-purity grades for regulated pharmaceutical applications. Vihita Chem Private Limited anchors South Asian demand through specialized technical-grade production for agrochemical intermediates. Merck KGaA dominates laboratory and research-grade distribution through controlled channel networks.
Guanidine carbonate is an organic salt with the formula C2H10N6O3, typically synthesized from dicyandiamide and ammonium carbonate under elevated temperature and pressure, serving primarily as a precursor in pharmaceutical synthesis and as a pH buffer in industrial processes. Pharmaceutical-grade product types command premium positioning due to stringent impurity limits and certification overhead, while technical-grade segments compete on volume scale in agrochemical applications. Chemical manufacturing applications absorb the largest volume share, though food additive specifications are tightening fastest under evolving safety protocols.
REACH registration requirements in Europe, China's GB standards administered by SAMR, and FDA pharmaceutical excipient guidelines collectively elevate compliance costs for cross-border suppliers. These frameworks restrict market access for uncertified producers while rewarding documented quality systems. Stakeholders must monitor regulatory divergence between major import jurisdictions to anticipate specification-driven procurement shifts.
Market Dynamics
Pharmaceutical-grade specification tiers are unwinding across the guanidine carbonate value chain as downstream API makers enforce tighter purity thresholds and regulators tighten impurity limits for export markets.
Growth Catalysts
- REACH registration requirements:European ECHA mandates for chemical safety documentation are pulling high-purity grades into regulated pharmaceutical applications, rewarding producers with documented quality systems.
- Agrochemical intermediate demand:Technical-grade consumption is accelerating in India's Gujarat industrial corridor for pesticide synthesis and crop protection formulation.
- Shandong province manufacturing cluster:China's concentrated chemical production base is generating economies of scale in dicyandiamide feedstock processing, lowering unit conversion costs.
Market Restraints
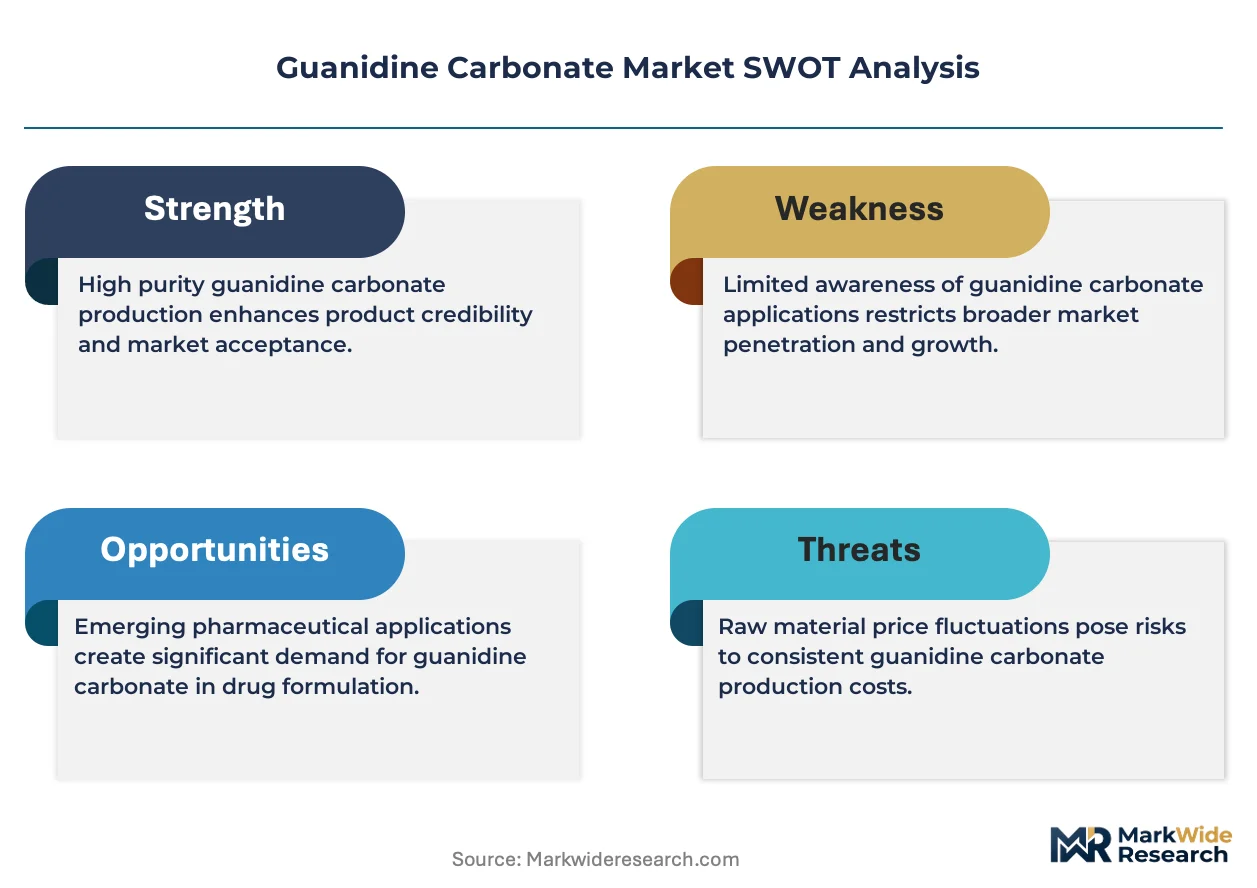
- Dicyandiamide price volatility:Feedstock cost swings from natural gas and cyanamide production cycles compress margin predictability for carbonate converters.
- Supply concentration risk:China's dominance in upstream dicyandiamide creates single-geography dependency for non-integrated carbonate producers.
- Technical-grade substitution:Guanidine hydrochloride and guanidine nitrate are displacing carbonate in certain pH buffering applications where water solubility requirements are less stringent.
Strategic Opportunities
- Food additive specification expansion:Evolving FSSAI safety protocols in India are opening formulation-grade demand for pH control in processed food applications.
- Laboratory reagent channel development:Direct-to-research distribution partnerships with academic institutions are bypassing traditional chemical distributor markups.
- Green chemistry process incentives:China's dual carbon goals under MEE guidance are subsidizing energy-efficient ammonium carbonate recovery systems in carbonate synthesis.
Industry Challenges
- Pharmaceutical excipient certification timelines:FDA DMF filing and EMA CEP approval processes extend market entry cycles by 18-36 months for new high-purity suppliers.
- Process analytical technology integration:Real-time purity monitoring systems require capital deployment that mid-scale producers struggle to justify against batch testing economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guanidine Carbonate Market |
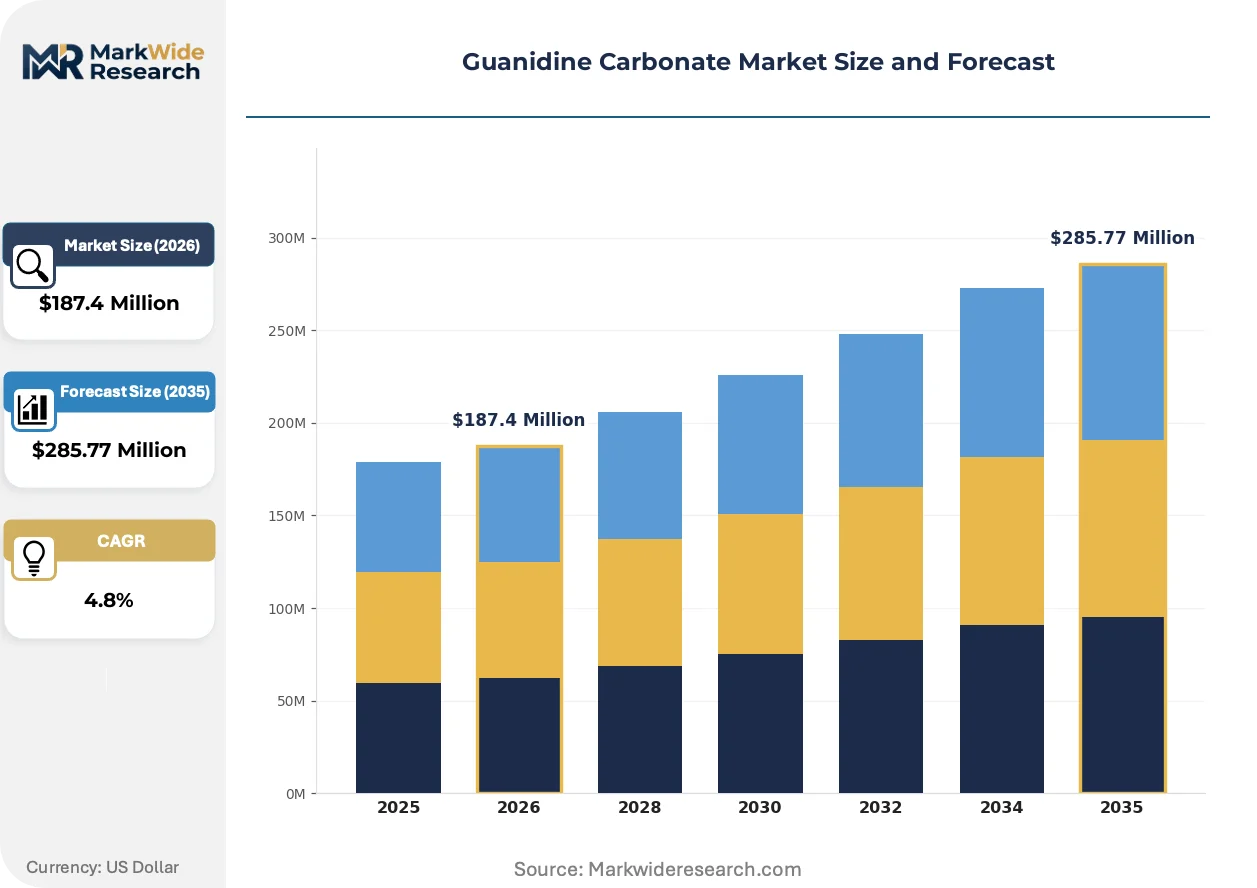
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Pharmaceutical Grade, Technical Grade, Industrial Grade Application: Pharmaceuticals, Agriculture, Chemical Manufacturing, Food Additives End User: Manufacturers, Research Institutions, Laboratories, Agricultural Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | AlzChem AG, Vihita Chem Private Limited, FabriChem, HSCC, Borealis AG, S.B. Organic, Merck KGaA, Shanghai Jucheng Chemical, AVATAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guanidine Carbonate Market Emerging Trajectories
Continuous processing technologies and regulatory data integrity requirements are actively reshaping how guanidine carbonate is manufactured, tested, and qualified for downstream pharmaceutical use.
Membrane filtration-based purification is fragmenting the traditional crystallization-dominated landscape for high-purity grade production. Specialty API manufacturers in Germany and Switzerland are adopting ceramic membrane systems for impurity removal at lower thermal exposure. This shift is fragmenting equipment vendor relationships as engineering firms with bioprocessing expertise displace conventional chemical equipment suppliers.
REACH Annex XVII restrictions on residual cyanamide derivatives are tightening testing protocols for European pharmaceutical excipient shipments. The industrial consequence is mandatory LC-MS impurity profiling that adds analytical cost but creates competitive moats for certified producers. API makers in the Netherlands and Denmark are responding by consolidating supplier lists to pre-qualified vendors with ECHA-registered dossiers.
Specification-driven procurement is compressing supplier qualification cycles as pharmaceutical buyers consolidate vendor panels around dual-source strategies. Traditional spot-market purchasing through chemical distributors is giving way to multi-year supply agreements with embedded quality audits. This behavioral shift is most visible among mid-sized generic API producers in India seeking CDSCO-compliant documentation packages for export filings.
Guanidine Carbonate Market Segmentation
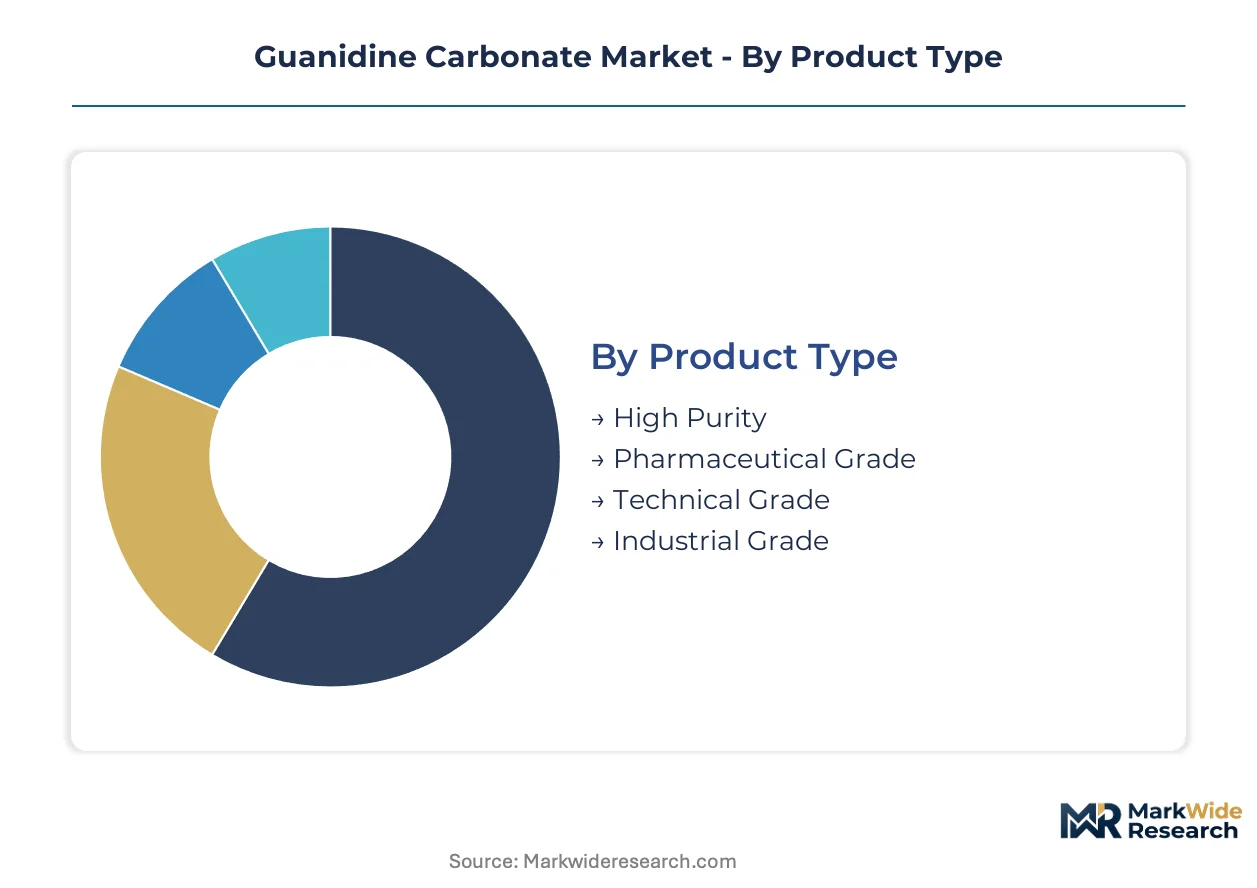
Guanidine carbonate segmentation reflects divergent purity standards across regulated and unregulated applications. Specification tiers separate premium pharmaceutical supply from commodity chemical flows, with certification overhead creating distinct margin architectures.
Product Type:
REACH registration and FDA DMF requirements fragment supply into documented quality tiers with escalating analytical burdens.
- Pharmaceutical Grade:Impurity limits below 0.1% for residual cyanamide derivatives with mandatory LC-MS batch certification. API manufacturers in Germany and Switzerland consolidate procurement around ECHA-registered dossiers to secure EMA CEP approval pathways.
- High Purity:Ceramic membrane filtration replaces thermal crystallization for specialty synthesis applications. Swiss and Dutch pharmaceutical excipient buyers are mandating real-time process analytical technology data packages from qualified vendors.
- Technical Grade:Standardized for agrochemical intermediate synthesis with less stringent moisture specifications.
- Industrial Grade:Bulk pH buffering applications in chemical manufacturing with minimal certification overhead.
Established volume favors Technical Grade; emerging adoption favors Pharmaceutical Grade.
Application:
End-use specifications range from food-contact safety protocols to laboratory reagent precision.
- Pharmaceuticals:Precursor synthesis for antiviral and metabolic disorder APIs with CDSCO-compliant documentation for Indian generic exporters. Gujarat-based manufacturers are expanding carbonate purchases to support ANDA filing volumes.
- Chemical Manufacturing:Dominant volume absorption for pH control in polymerization and electroplating baths. Shandong province chemical clusters leverage captive dicyandiamide supply to compress conversion economics.
- Agriculture:Pesticide formulation intermediates in India's crop protection sector.
- Food Additives:pH stabilization in processed foods under tightening FSSAI safety protocols.
Chemical Manufacturing commands current volume leadership; Pharmaceuticals climbs the fastest on specification premiums.
End User:
Customer scale determines procurement modality from spot purchasing to multi-year supply agreements.
- Manufacturers:Integrated API and agrochemical producers with backward integration into dicyandiamide processing. Large-scale buyers in China and India are consolidating vendor panels around dual-source qualification models.
- Research Institutions:Academic laboratories requiring small-batch reagent consistency with documented certificates of analysis. Direct distribution partnerships are displacing traditional chemical distributor markups.
- Laboratories:Analytical and quality control applications with stringent lot-to-lot uniformity requirements.
- Agricultural Companies:Formulation houses in Gujarat's industrial corridor sourcing technical-grade volumes for pesticide synthesis.
Manufacturers anchor procurement volume; Research Institutions expand most quickly through direct channel development.
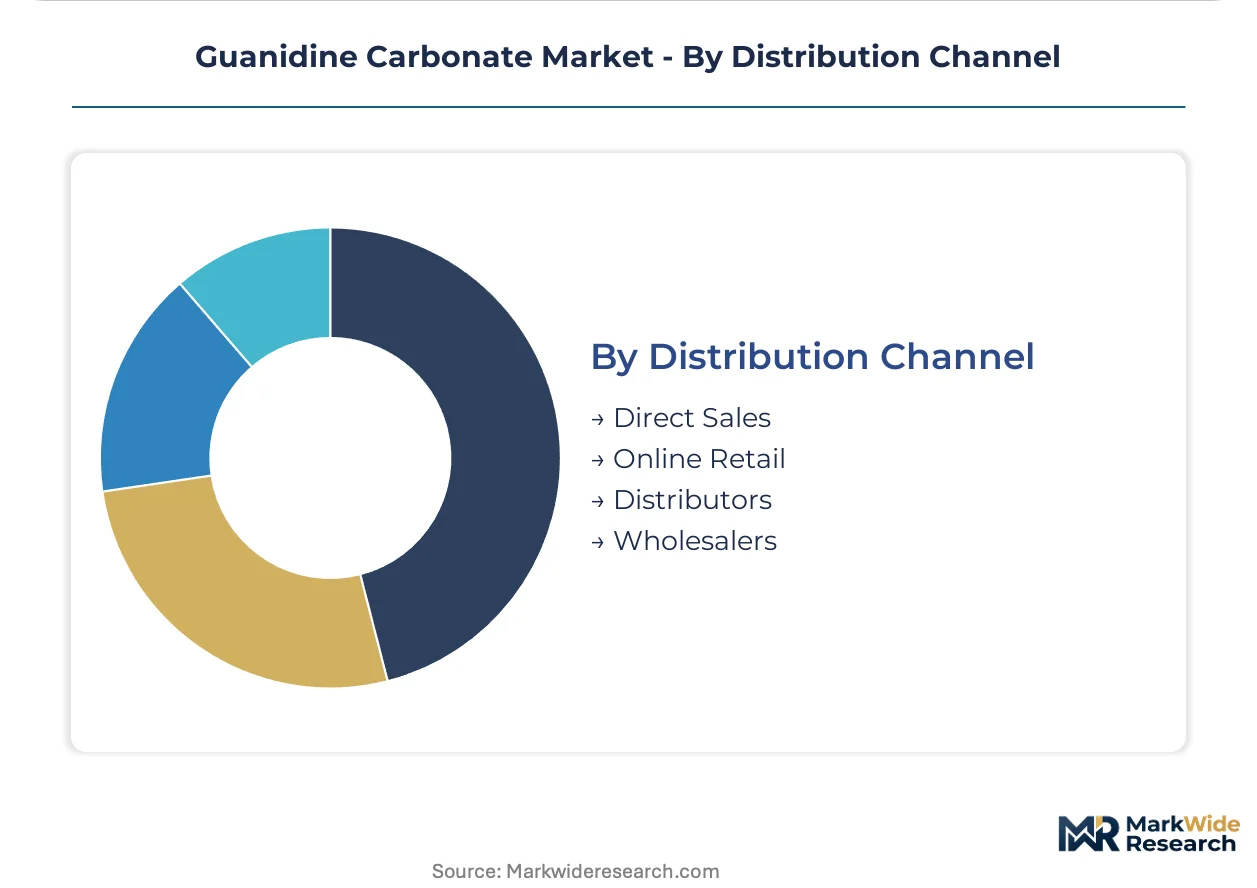
Distribution Channel:
Channel selection correlates with certification burden and customer technical sophistication.
- Direct Sales:Multi-year agreements with embedded quality audits for pharmaceutical-grade supply. Generic API producers in India are abandoning spot-market purchasing for pre-qualified vendor relationships.
- Distributors:Traditional chemical distribution networks serving mid-scale technical-grade buyers with inventory pooling.
- Online Retail:Laboratory reagent portals for research-grade small orders with rapid fulfillment.
- Wholesalers:Bulk commodity flows for industrial-grade applications with minimal specification overhead.
Distributors retain technical-grade dominance; Direct Sales gains share fastest on pharmaceutical consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping procurement patterns as pharmaceutical-grade specifications fragment supply sources across major consuming markets. Regional manufacturing clusters now compete on certification velocity rather than unit cost alone.
China
Shandong province chemical manufacturers dominate upstream dicyandiamide conversion, feeding carbonate output for both domestic pharmaceutical synthesis and export-grade technical applications. GB standards administered by SAMR mandate tightening purity documentation for cross-border shipments to regulated markets. Qingdao and Weifang industrial zones concentrate membrane filtration capacity upgrades for high-purity grade production.
Germany
Specialty API producers in Bavaria and North Rhine-Westphalia drive pharmaceutical-grade carbonate consumption for antiviral and metabolic disorder synthesis. REACH registration requirements through ECHA enforce documented quality systems that exclude uncertified Asian suppliers from qualified vendor lists. AlzChem AG anchors domestic supply through its Trostberg manufacturing base.
India
Gujarat's industrial corridor absorbs technical-grade volumes for agrochemical intermediate synthesis, while Maharashtra-based generic API makers expand pharmaceutical-grade purchases for ANDA filing documentation. CDSCO compliance protocols and FSSAI safety standards are bifurcating procurement into documented export grades versus domestic technical specifications. Ahmedabad and Vadodara formulation houses consolidate vendor panels around dual-source qualification models.
United States
FDA pharmaceutical excipient guidelines and DMF filing requirements extend supplier qualification timelines, compressing spot-market participation. Laboratory reagent distributors in Greater Boston and the San Francisco Bay Area anchor research-grade consumption through direct channel partnerships with academic institutions. EPA oversight of chemical manufacturing emissions shapes domestic production economics.
Switzerland
Specialty pharmaceutical excipient buyers in Basel and Zurich mandate real-time process analytical technology data packages from qualified vendors. Swissmedic oversight of pharmaceutical inputs reinforces EMA-aligned certification requirements. Ceramic membrane filtration adoption is concentrating among Basel-area API manufacturers seeking lower thermal exposure in purification workflows.
Guanidine Carbonate Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic proximity to regulated pharmaceutical markets. The vendor base stratifies into three tiers: integrated chemical conglomerates with backward dicyandiamide control, regional specialists with documented quality systems for export markets, and commodity converters competing on volume scale. Strategic moves center on multi-year supply agreements with embedded quality audits and membrane filtration technology licensing for purity tier upgrades.
Within the European-certified tier, AlzChem AG and Merck KGaA exemplify archetypes of documented quality system operators serving regulated pharmaceutical applications. Among South Asian specialists, Vihita Chem Private Limited occupies a position representing technical-grade production anchored to Gujarat's agrochemical demand cluster. Shanghai Jucheng Chemical sits within the scale-driven segment of Chinese manufacturers leveraging Shandong province feedstock proximity.
| Leading Market Players |
|---|
| AlzChem AG |
| Vihita Chem Private Limited |
| FabriChem |
| HSCC |
| Borealis AG |
| S.B. Organic |
| Merck KGaA |
| Shanghai Jucheng Chemical |
| AVATAR |
| Others |
Supply Flow & Price Mechanics
Multi-year supply agreements with embedded quality audits lock in both supply access and price visibility for pharmaceutical-grade guanidine carbonate buyers, insulating ECHA-registered producers from dicyandiamide feedstock volatility while compressing spot-market participation for uncertified converters.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across pharmaceutical, high-purity, technical, and industrial grade tiers. Price differentiation hinges on certification level—REACH registration and FDA DMF tiers command substantial premiums over technical-grade commodity flows. Pricing pressure stems from dicyandiamide cost volatility linked to natural gas and cyanamide production cycles, squeezing margin predictability for non-integrated carbonate converters. Research institutions exhibit highest price sensitivity due to small-batch procurement volumes, while specialty API manufacturers in Germany and Switzerland demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
China and India anchor upstream dicyandiamide conversion and downstream carbonate synthesis, with Shandong province chemical clusters and Gujarat's industrial corridor concentrating production capacity. Raw material dependencies center on dicyandiamide feedstock, ammonium carbonate reagent, and ceramic membrane filtration equipment for high-purity grades. Single-source vulnerability concentrates in China's dominance of upstream dicyandiamide, creating geographic dependency for non-integrated producers. Distribution runs through direct sales channels for pharmaceutical-grade supply, with traditional chemical distributors retaining technical-grade dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guanidine carbonate procurement is shifting toward platform-economics dynamics as pharmaceutical buyers consolidate vendor panels around interoperable quality documentation systems that streamline EMA CEP and CDSCO compliance pathways.
For Market Incumbents: Secure ECHA-registered dossier maintenance and real-time process analytical technology deployment to defend against membrane filtration-equipped specialty entrants. Backward integration into dicyandiamide feedstock insulates margin position against cyanamide price cycles. AlzChem AG's Trostberg manufacturing base exemplifies certification depth that locks out uncertified Asian suppliers from qualified vendor lists. For New Entrants and Emerging Players: Anchor in laboratory reagent channel development through direct distribution partnerships with academic institutions, bypassing traditional chemical distributor markups. Food additive specification expansion under tightening FSSAI safety protocols in India represents the most penetrable white-space target. Green chemistry process incentives under China's MEE dual carbon goals offer subsidized entry into energy-efficient ammonium carbonate recovery systems. For Investors and Strategic Acquirers: Capital is best deployed toward ceramic membrane filtration technology licensors and ECHA-registered quality system operators with documented pharmaceutical-grade production histories. Long-term viability hinges on regulatory certification velocity rather than unit cost scale. The signal to watch is CDSCO-compliant documentation package adoption among Gujarat-based generic API producers seeking ANDA filing support.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dicyandiamide | Captive feedstock supply insulates margin predictability against cyanamide price volatility cycles. |
| Ceramic Membrane Filtration Licensing | Swiss and Dutch pharmaceutical buyers mandate real-time PAT data packages from qualified vendors. |
| ECHA Registration Dossier Investment | REACH compliance creates competitive moats excluding uncertified producers from European pharmaceutical supply. |
| Direct Academic Distribution Partnerships | Research institutions bypass traditional chemical distributor markups through laboratory reagent portals. |
| Green Chemistry Process Certification | China's MEE dual carbon goals subsidize energy-efficient ammonium carbonate recovery in carbonate synthesis. |
Methodological Framework
A standing panel of pharmaceutical procurement managers, agrochemical formulation chemists, chemical distribution channel partners, and regulatory affairs specialists provided ongoing calibration across primary interview cycles, with secondary validation drawing from ECHA registration databases, SAMR GB standard filings, CDSCO export documentation records, and customs trade flow data. Bottom-up volume triangulation across grade-tier production estimates converged with top-down value derivation from contract pricing disclosures.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled encompass grade tier, end-use industry application, regional production hub concentration, and certification documentation package type. CAGRs were derived from iterative regression against feedstock cost indices and downstream demand elasticity parameters, incorporating pharmaceutical API filing volume trajectories and agrochemical intermediate consumption patterns as industry-specific forecast inputs.
Underlying assumptions cover REACH registration maintenance timelines, dicyandiamide feedstock price band stability, and membrane filtration technology diffusion rates, with deviation risk concentrated in regulatory divergence between EMA and CDSCO certification requirements. Recalibration cycles align with material shifts in pharmaceutical excipient purity thresholds and agrochemical formulation safety protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Uranyl Carbonate Market
Chemicals
Trimethylamine Market
Chemicals
Sodium Methoxide Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Isopropanolamine Market
Chemicals
Isoamyl Acetate Market
Chemicals
Lead Tetracetate Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Tanning Agents Market
Chemicals
Lime Sulfur Market
Chemicals
Antiozonant Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Global Boron Trifluoride Market