
 Denim Finishing Agents Market | 2026-2036
Denim Finishing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Denim Finishing Agents Market Intelligence
REACH is consolidating the European supplier base by restricting azo dyes and chromium-based mordants used in vintage denim finishes. Huntsman International LLC sustains its position through captive R&D on low-temperature enzymatic systems. Archroma competes via Bluesign-certified product lines that reduce water intensity in stone-wash applications. Rudolf GmbH anchors its business in metal-free polymer coatings that comply with evolving EU textile chemical regulations.
Denim finishing agents encompass chemical formulations applied to indigo-dyed cotton fabrics to modify hand feel, visual appearance, dimensional stability, or functional performance after garment assembly. These agents typically operate within narrow pH windows between 4.5 and 7.0 and require compatibility with indigo dye chemistries to prevent back-staining or shade variation. Enzymes dominate value contribution within product types due to premium pricing for cellulase variants that enable localized abrasion without mechanical damage. Liquid formulations lead the form category because pump-fed dosing systems in continuous wash lines favor flowable concentrates over powdered alternatives that generate airborne particulates.
EMA oversees chemical safety assessments for textile auxiliaries sold across EU member states, while India's Central Pollution Control Board enforces effluent load limits on denim washing units in the Tiruppur and Ahmedabad belts. The ZDHC MRSL creates a common reference for restricted substances that pushes formulators to replace nonylphenol ethoxylates in softening agents with biodegradable quaternary compounds. Stakeholders must monitor how Bangladesh's Department of Environment implements effluent standards for its expanding denim export sector, as enforcement timing will determine whether local mills adopt imported compliant chemistry or trigger regional supplier qualification programs.
Market Dynamics
Water scarcity across South Asia and the ZDHC MRSL zero-discharge mandate are compressing the process window for conventional denim washing, forcing mills to replace pumice stone and potassium permanganate with laser-compatible enzymatic systems.
Growth Catalysts
- Cellulase enzyme adoption:Bangladesh's garment processing cluster is upgrading wash lines to cellulase-based abrasion systems that eliminate mechanical damage while cutting water use by half.
- REACH chemical restrictions:The European regulation's ban on azo dyes and chromium mordants is redirecting procurement toward Bluesign-certified bio-based softeners.
- Gujarat water reuse mandates:India's state-level effluent regulations are accelerating demand for closed-loop finishing chemistry compatible with zero-liquid-discharge systems.
Market Restraints
- Indigo back-staining risk:Enzymatic systems operating outside the 4.5-7.0 pH window cause shade variation that rejects entire production batches.
- Petrochemical feedstock volatility:Polymer coating formulations depend on acrylate monomers whose pricing fluctuates with crude oil movements.
- Specialized supplier concentration:Metal-free polymer coatings compliant with EU textile regulations source from a narrow base of German and Swiss specialty chemical producers.
Strategic Opportunities
- Laser-denim convergence:Mills integrating laser abrasion hardware with low-temperature enzymatic finishing chemistry can bypass potassium permanganate entirely.
- Central Pollution Control Board enforcement:India's tightening effluent load limits on Tiruppur washing units create qualified demand for imported compliant chemistry.
- Vietnam processing expansion:Vertically integrated mills in Ho Chi Minh City's export corridor are greenfield-installing water-efficient finishing lines without legacy equipment conversion costs.
Industry Challenges
- Process engineer scarcity:Mills struggle to hire technicians capable of calibrating pH-sensitive enzymatic dosing systems across variable water hardness conditions.
- Certification timeline compression:Bluesign and ZDHC MRSL approval cycles for new formulations now exceed 18 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denim Finishing Agents Market |
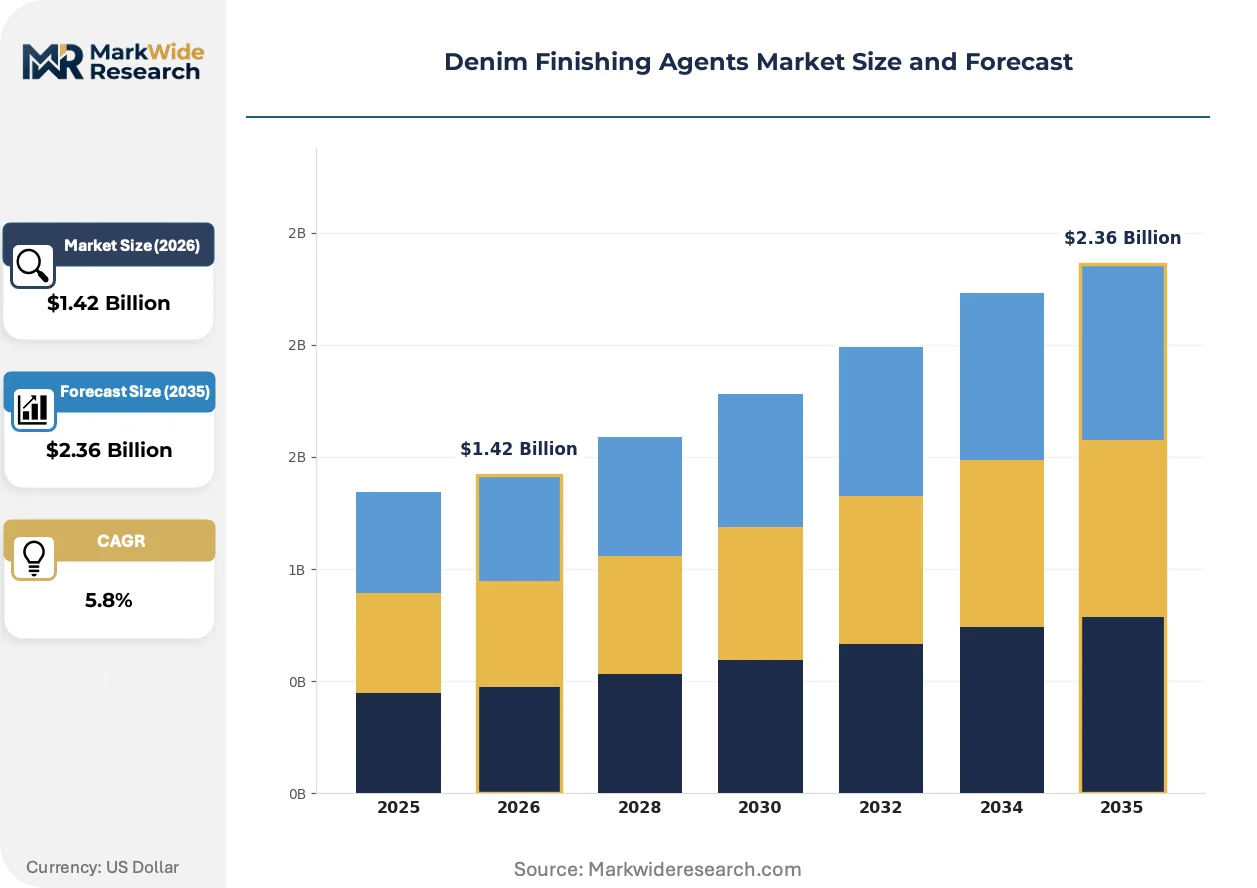
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Softening Agents, Anti-creasing Agents, Whiteners Application: Washing, Coating, Finishing, Dyeing Form: Liquid, Powder, Gel, Paste End User: Textile Manufacturers, Fashion Brands, Retailers, Wholesalers |
| Companies Covered | DyStar Group, Huntsman International LLC, Archroma, Novonesis Group, BASF SE, CHT Group, Pulcra Chemicals GmbH, Kemin Industries, Inc., Rudolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denim Finishing Agents Market Strategic Shifts & Innovations
Laser-compatible finishing chemistry is displacing mechanical abrasion across premium denim production, while regulatory pressure on water intensity forces simultaneous hardware and formulation upgrades.
Cellulase variants engineered for localized abrasion without fiber damage are electrifying the transition from pumice stone washing. Italian premium brands operating under ZDHC commitments have adopted these enzymes at scale since 2023. The technology is electrifying margin compression across conventional bleaching chemical suppliers as enzyme premiums stabilize below historical levels.
REACH authorization requirements for textile auxiliaries are tightening the supplier base for vintage denim finishes across EU member states. ECHA's restriction roadmap now targets nonylphenol ethoxylates in softening agents, forcing reformulation toward biodegradable quaternary compounds. Italian and Spanish finish houses are absorbing the highest compliance costs due to their concentration in heritage wash techniques.
Buyer consolidation among Bangladesh's top-ten garment exporters is compressing supplier qualification timelines from 24 months to 12 months. Mills now demand pre-certified chemistry bundles rather than discrete auxiliaries, displacing smaller regional formulators. This pattern is most visible in Dhaka's export processing zones where vertically integrated denim units source 80 percent of finishing agents through direct mill relationships.
Denim Finishing Agents Market Segmentation
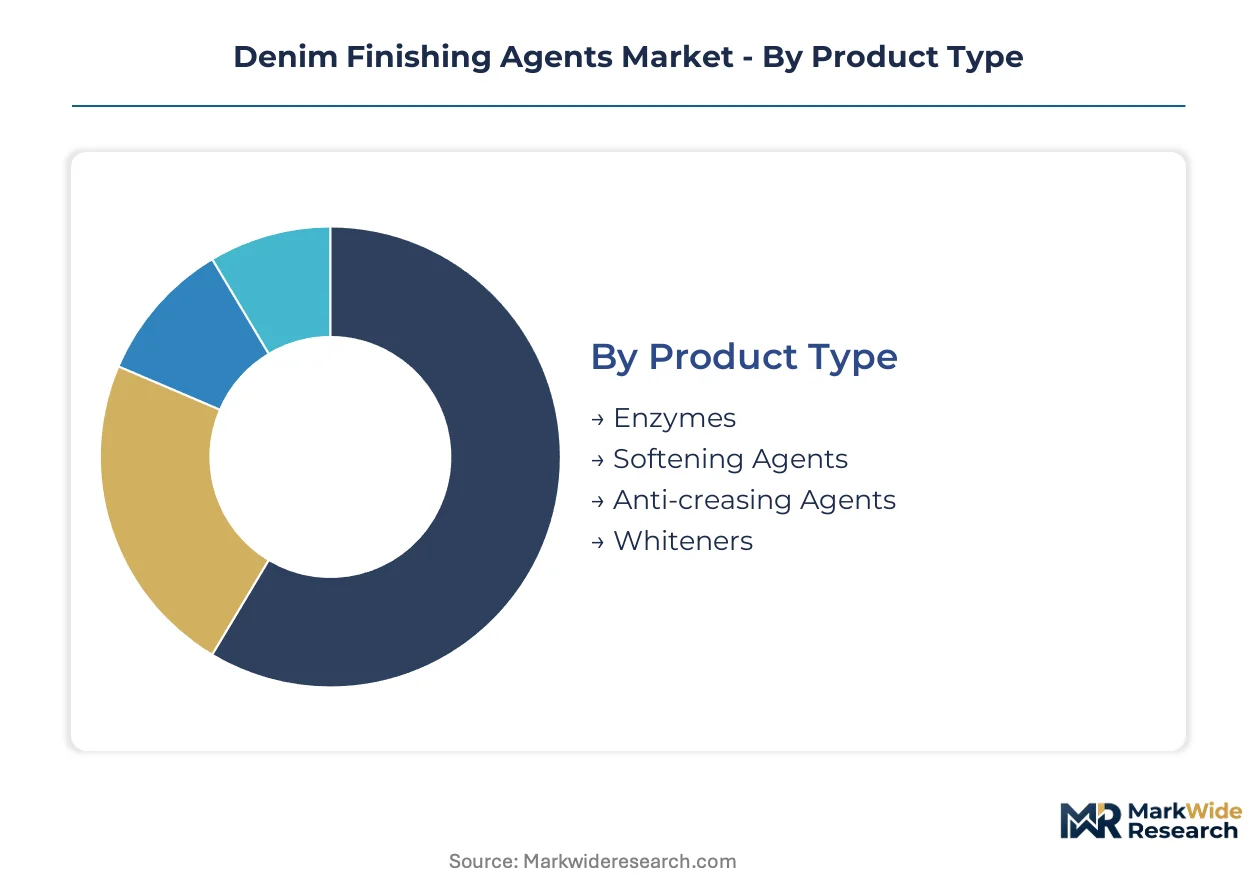
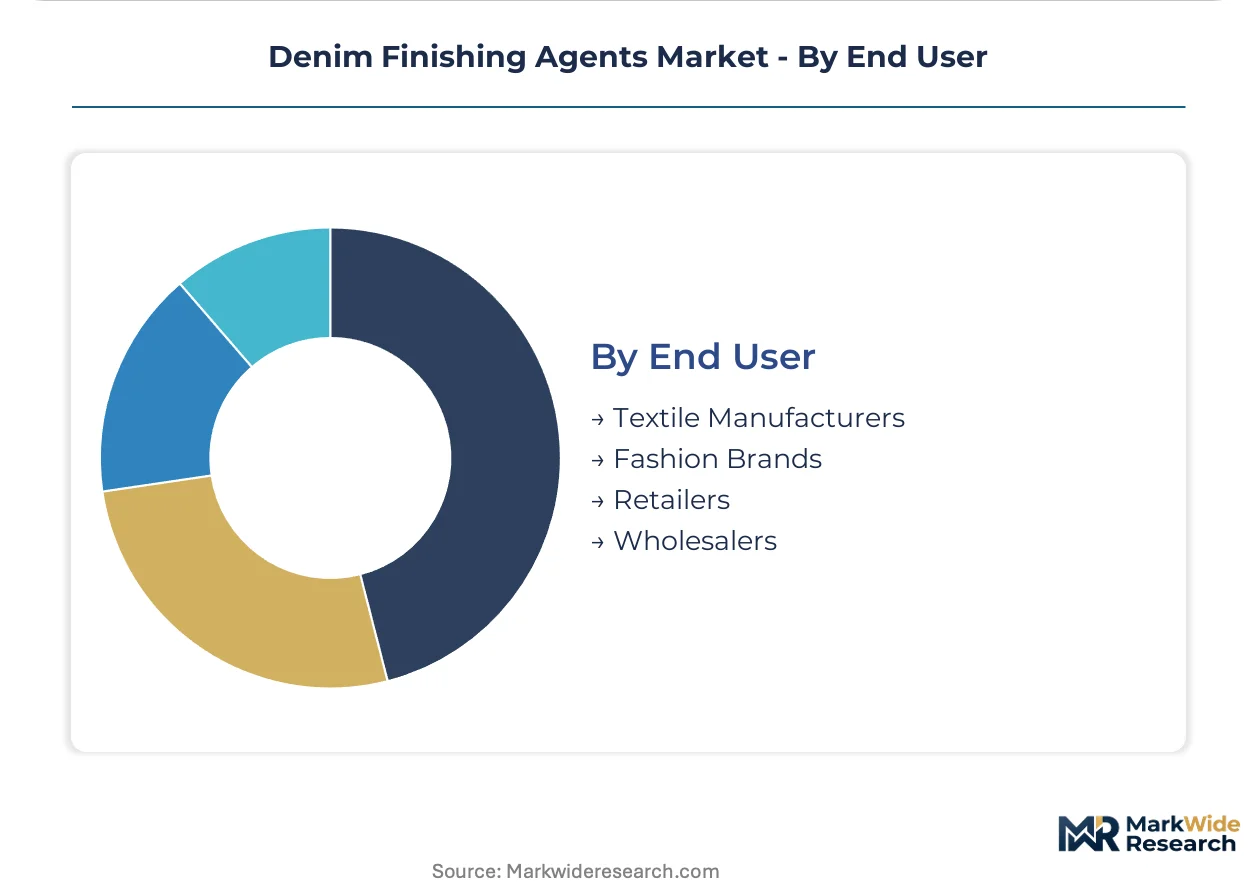
Segmentation in denim finishing agents reflects divergent upgrade cycles across hardware-dependent process lines and regulatory-driven chemistry substitutions. Mills select formulations based on compatibility with existing wash line infrastructure, effluent system design, and end-customer certification requirements.
Product Type:
Upgrade cycles vary sharply by chemistry family, with enzymatic systems displacing legacy formulations faster than commodity auxiliaries.
- Enzymes:Cellulase variants engineered for localized abrasion operate within strict 4.5-7.0 pH windows to prevent indigo back-staining. Bangladesh's garment processing cluster sources these at premium pricing to eliminate mechanical damage while halving water use.
- Softening Agents:Bio-based quaternary compounds are replacing nonylphenol ethoxylates under ECHA's restriction roadmap for textile auxiliaries. Italian finish houses absorb the highest compliance costs due to concentration in heritage wash techniques requiring reformulation.
- Anti-creasing Agents:Resin-based crosslinkers stabilize dimensional stability in stretch denim blends.
- Whiteners:Optical brightening agents face declining demand as raw denim aesthetics gain preference.
Volume placements concentrate in Softening Agents; the faster expansion belongs to Enzymes.
Application:
Process step selection determines chemical compatibility requirements and dosing system specifications.
- Washing:Stone-wash and enzyme-wash applications dominate chemical consumption. Tiruppur's denim washing units in India drive qualified demand for imported compliant chemistry as the Central Pollution Control Board tightens effluent load limits.
- Coating:Polymer finishes impart functional properties including water repellency and abrasion resistance. Metal-free polymer coatings compliant with EU textile regulations source from a narrow base of German and Swiss specialty chemical producers.
- Finishing:Final hand-modification treatments determine garment market positioning.
- Dyeing:Post-indigo color correction and topping processes require sulfur-compatible chemistry.
Placement intensity peaks in Washing; Coating is climbing the fastest on functional performance premiums.
Form:
Physical state selection follows dosing infrastructure constraints and occupational exposure controls.
- Liquid:Flowable concentrates enable pump-fed dosing in continuous wash lines. Dhaka's export processing zones favor liquid formulations for automated metering across high-volume garment finishing operations.
- Powder:Dry concentrates generate airborne particulates requiring containment systems. Powdered enzymes retain niche use in batch operations where water-free storage extends shelf stability.
- Gel:High-viscosity carriers suit targeted application methods.
- Paste:Thick consistency formulations enable manual spot treatment.
Liquid commands absolute volume share; Gel is gaining share fastest on precision application demand.
End User:
Customer type dictates procurement scale, technical service requirements, and certification documentation needs.
- Textile Manufacturers:Vertically integrated mills in Vietnam's Ho Chi Minh City export corridor greenfield-install water-efficient finishing lines without legacy conversion costs. These facilities demand pre-certified chemistry bundles rather than discrete auxiliaries.
- Fashion Brands:Premium denim labels in Italy and Japan specify enzyme-based finishing programs to meet ZDHC MRSL zero-discharge commitments. Brand-level procurement drives premium pricing for Bluesign-certified product lines.
- Retailers:Mass-market channels prioritize cost-optimized standard finishes.
- Wholesalers:Trading intermediaries supply smaller finish houses with commodity chemistry.
Procurement volume concentrates in Textile Manufacturers; Fashion Brands deliver the steepest expansion trajectory on sustainability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denim finishing demand clusters in South Asia's garment processing belt, with Bangladesh's export sector and India's Tiruppur-Ahmedabad corridor driving volume placement. European premium brands and East Asian technical mills anchor high-value specialty chemistry procurement.
Bangladesh
Dhaka's export processing zones process the majority of global denim garment finishing volume. The Department of Environment implements effluent standards that determine whether mills adopt imported compliant chemistry or trigger regional supplier qualification. Vertically integrated denim units in Gazipur and Narayanganj source pre-certified chemistry bundles through direct mill relationships.
India
Gujarat's state-level water reuse mandates and Tiruppur's Central Pollution Control Board enforcement accelerate demand for zero-liquid-discharge compatible finishing systems. Ahmedabad's denim washing cluster upgrades from conventional bleaching to laser-compatible enzymatic chemistry. Maharashtra's textile belt absorbs compliance costs through backward integration into captive water treatment infrastructure.
Italy
REACH authorization requirements and ECHA's restriction roadmap on nonylphenol ethoxylates redirect procurement toward Bluesign-certified bio-based softeners. Piedmont and Veneto finish houses concentrate in heritage wash techniques requiring costly reformulation. Premium denim brands operating under ZDHC commitments have adopted cellulase-based abrasion at scale.
Japan
METI guidelines on sustainable manufacturing push Osaka-based mills toward low-temperature enzymatic systems. Okayama's denim production cluster specializes in vintage reproduction finishes that historically relied on chromium-based mordants now restricted under EU import standards. Technical partnerships with German enzyme suppliers anchor quality positioning.
Vietnam
Ho Chi Minh City's export corridor attracts greenfield investment in water-efficient finishing lines without legacy equipment conversion costs. Vertically integrated mills demand pre-certified chemistry bundles from European and Japanese suppliers. Binh Duong province hosts the fastest capacity expansion for laser-integrated denim processing.
Denim Finishing Agents Market Key Industry Players
German and Swiss specialists anchor the premium compliance tier; Asian commodity producers hold volume placement in standard finishes. The supplier base concentrates around enzymatic systems and metal-free polymer coatings where regulatory certification creates barriers. Three archetypes dominate: integrated chemical conglomerates with captive textile divisions, specialty enzyme houses with ZDHC pre-certification, and regional formulators serving single-country garment clusters. Competitive moves center on Bluesign approval acceleration and direct mill technical service partnerships.
Among European-based formulators, Huntsman International LLC, Archroma, and Rudolf GmbH exemplify the compliance-driven premium tier. These entities occupy positions where REACH alignment and ZDHC MRSL certification function as competitive moats. DyStar Group and Novonesis Group represent the enzymatic specialization vector, with corporate structures reflecting consolidation across textile auxiliary portfolios. BASF SE anchors the diversified chemical conglomerate archetype, leveraging scale advantages across multiple industrial verticals. CHT Group, Pulcra Chemicals GmbH, and Kemin Industries, Inc. sit within mid-tier specialist positions serving regional garment processing clusters with customized formulation services.
| Leading Market Players |
|---|
| DyStar Group |
| Huntsman International LLC |
| Archroma |
| Novonesis Group |
| BASF SE |
| CHT Group |
| Pulcra Chemicals GmbH |
| Kemin Industries, Inc. |
| Rudolf GmbH |
| Others |
Cost & Logistics Intelligence
Vertically integrated denim mills in Bangladesh's garment processing cluster command volume-based contract pricing that compresses margins for standard softening agents while sustaining premiums for ZDHC MRSL-certified enzymatic systems. This buyer concentration forces suppliers to absorb reformulation costs for REACH-compliant chemistry or exit European procurement channels entirely.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to cellulase enzymes shipped on 48-hour notice to Dhaka's export processing zones, while spot inventory of commodity resin crosslinkers trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates Bluesign-certified bio-based softeners from conventional quaternary compounds and unbranded regional alternatives. Cost compression in standard-grade anti-creasing agents is intensifying because Indian mills backward integrate into captive resin production. Mass-market retailers exhibit highest price sensitivity, while Italian premium brands accept enzyme premiums for ZDHC compliance documentation.
Supply Chain Analysis
Freight costs from German and Swiss specialty chemical producers to South Asian garment clusters add 8-12 percent to delivered enzyme prices, favoring regional formulators in Gujarat and Maharashtra. Manufacturing concentrates in Germany, Switzerland, and India, with formulation tolling in Bangladesh for customs efficiency. Acrylate monomer feedstocks draw from petrochemical complexes in Saudi Arabia, South Korea, and Singapore. Single-source vulnerability pervades metal-free polymer coatings where ECHA authorization limits qualified suppliers. Distribution runs through direct mill technical service partnerships rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized supplier concentration in enzymatic systems and REACH-authorized coatings props pricing power for certified formulators. Capacity expansion in compliant chemistry lags Bangladesh's wash line upgrade cycle by 18-24 months.
For Market Incumbents: Lock in multi-year supply agreements with Bangladesh's top-ten garment exporters before regional qualification programs mature. Defend margin position by accelerating Bluesign approval timelines for cellulase variants through pre-submission ECHA consultation. Cellulase commoditization from Novonesis Group expansion threatens premium pricing. Backward integration into captive enzyme fermentation in Vietnam insulates against freight cost volatility. For New Entrants and Emerging Players: Mid-tier finish houses in Vietnam's Binh Duong province present the most penetrable buyer archetype, lacking established supplier relationships and facing urgent ZDHC compliance deadlines. White-space exists in laser-compatible enzymatic chemistry bundles for greenfield mills in Ho Chi Minh City's export corridor. Target India's Tiruppur washing cluster with zero-liquid-discharge compatible softening agents as Central Pollution Control Board enforcement tightens. Go-to-market through technical service partnerships with European enzyme houses seeking regional manufacturing presence. For Investors and Strategic Acquirers: The window for entry favors specialty enzyme houses with ZDHC pre-certification and established mill relationships in Bangladesh or Vietnam. Long-term viability hinges on regulatory certification moats that extend 5-10 years beyond patent expiration. Acquisition targets include mid-tier German formulators with ECHA-authorized product lines and underutilized capacity. Watch Bangladesh Department of Environment enforcement timing as the inflection signal for regional supplier qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive production in Vietnam insulates Huntsman and Archroma from freight cost volatility. |
| Bluesign Certification Acceleration | Pre-certified chemistry bundles displace discrete auxiliaries in Dhaka's export processing zones. |
| Long-term Supply Agreement | Direct mill relationships in Gazipur lock out emerging regional formulators from volume placement. |
| Joint Venture with Regional Toll Manufacturer | Gujarat-based formulation partnerships reduce import duty exposure for Swiss specialty producers. |
| Green Manufacturing Transition | Low-temperature enzymatic systems eliminate potassium permanganate from Italian heritage wash techniques. |
Research Approach
Document review covered ECHA restriction roadmaps, ZDHC MRSL version updates, and Central Pollution Control Board effluent notifications, complemented by interviews with plant managers at Bangladesh denim washing units, procurement leads at Italian finish houses, and technical R&D directors at German specialty chemical producers. Secondary validation drew from customs trade data, SEC 10-K filings of listed chemical conglomerates, and textile auxiliary industry association reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for apparel manufacturing.
Segment-level projections across enzymes, softening agents, anti-creasing agents, and coating polymers were generated through the analysis window, with application splits across washing, coating, finishing, and dyeing processes. Modeled dimensions included form type, end-user category, and regional production hub. CAGRs were derived from regression analysis of historical placement volumes against regulatory enforcement timelines and mill capacity expansion announcements. Key inputs comprised enzyme pricing indices, acrylate monomer cost curves, and certification timeline data from Bluesign and ZDHC.
Revisions become necessary when REACH authorization timelines accelerate, Bangladesh Department of Environment enforcement exceeds projected stringency, or laser-denim hardware adoption outpaces enzymatic chemistry supply. Forecasts reflect assumptions about regulatory compliance cost pass-through and mill upgrade cycle synchronization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market