
 Asia Textile Chemicals Market | 2026-2036
Asia Textile Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Textile Chemicals Market Outlook
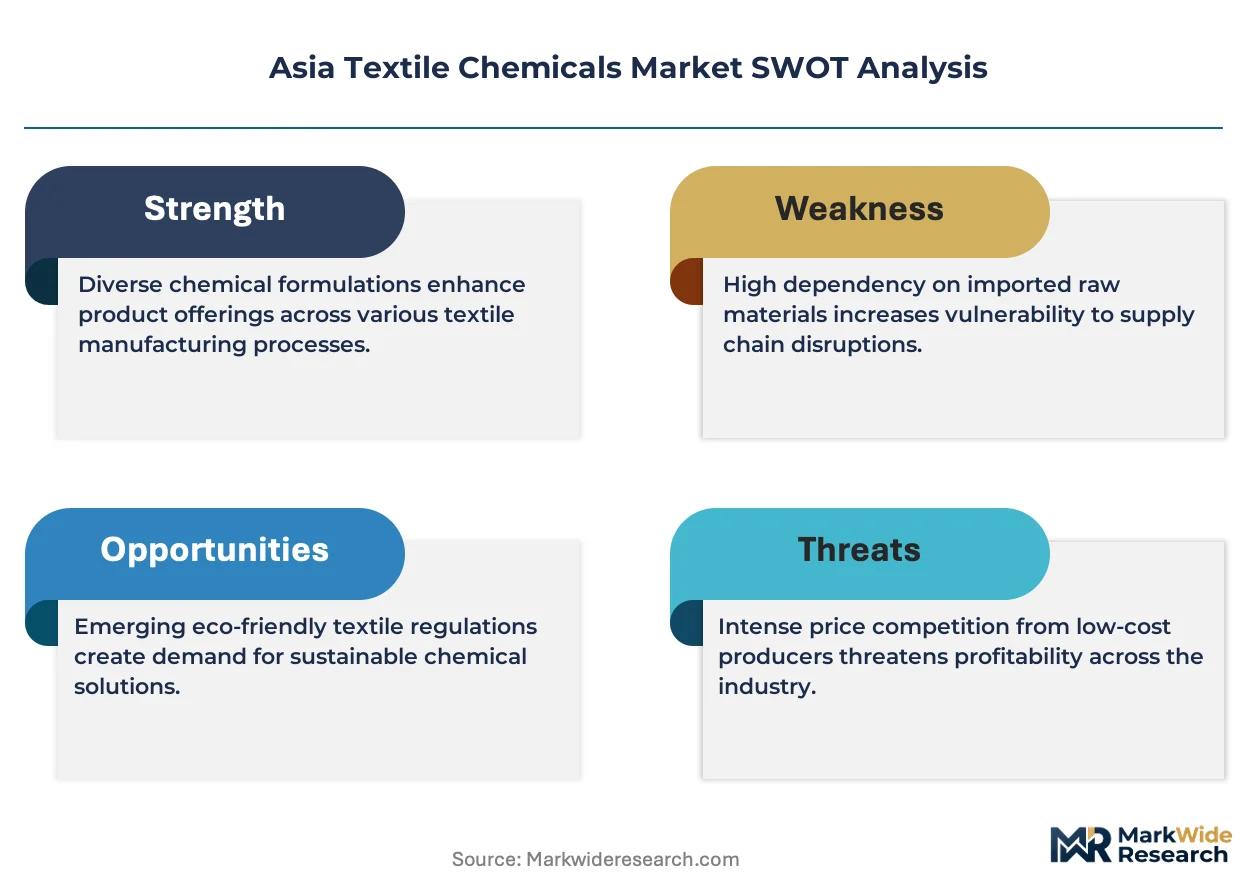
Technical service contracts for color management and effluent treatment systems is hardening into a core revenue stream beyond basic chemical sales. Huntsman Corporation anchors its Asia position through captive R&D centers in Shanghai that develop polyester-specific dyestuffs. Archroma Management LLC differentiates via its sustainable chemistry portfolio aligned with ZDHC compliance pathways. DyStar Group leverages backward integration into intermediate manufacturing to control input costs across its Thailand and China facilities.
Asia textile chemicals encompass formulated auxiliaries, reactive and disperse dyes, polymer coatings, and surfactant-based finishing agents engineered to bond with cellulose, protein, and synthetic fibers at temperatures between 40°C and 130°C; their primary purpose is to impart colorfastness, dimensional stability, and functional properties such as water repellency or antimicrobial resistance to fabrics destined for consumer and industrial end uses. Auxiliaries command the deepest margin pools where proprietary formulations for low-liquor ratio dyeing reduce water consumption by half versus conventional methods. Digital printing represents the fastest-expanding technology segment as inkjet-reactive chemistries displace rotary screen setups in short-run apparel production across Bangladesh and Vietnam.
China's MEE enforces wastewater discharge limits that compel dyehouses to adopt membrane bioreactor systems and switch to biodegradable surfactants. India's BIS certification mandates for textile colorants restrict import pathways for uncertified intermediates. REACH-aligned standards in EU-destined exports from Asia force reformulation of restricted azo dyes and formaldehyde-based finishers. Stakeholders must monitor regulatory divergence between domestic Asian standards and destination-market requirements to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Digital inkjet chemistries are compressing rotary screen print volumes across Bangladesh and Vietnam, forcing auxiliary suppliers to reformulate for low-liquor ratio bonding at 60°C instead of conventional 130°C exhaust dyeing cycles.
Growth Catalysts
- Automotive technical fabric demand:Airbag and seatbelt producers in China's Yangtze Delta are specifying flame-retardant polymer coatings that require specialized finishing agents with thermal stability above 200°C.
- MEE wastewater discharge limits:China's Ministry of Ecology and Environment mandates membrane bioreactor adoption, creating pull for biodegradable surfactant alternatives to alkylphenol ethoxylates in Zhejiang dyeing clusters.
- Digital printing ink chemistry:Reactive inkjet formulations for cotton and viscose are penetrating short-run apparel production in Vietnam's Dong Nai province, displacing rotary screen setup costs and reducing water consumption per linear meter.
Market Restraints
- Petrochemical intermediate volatility:Naphtha-derived ethylene oxide and propylene oxide feedstocks for surfactant production expose margin pools to crude price swings that dyehouses cannot pass through in fixed-price finishing contracts.
- Concentrated dye intermediate supply:China's Hubei and Jiangsu provinces control 70% of global anthraquinone disperse dye intermediates, creating geographic concentration risk for Thai and Indonesian compounders lacking backward integration.
- Formaldehyde-based finish substitution:Non-iron cotton treatments using DMDHEU resins face displacement by citric acid crosslinkers with inferior durability below 30 home laundering cycles, limiting adoption in mass-market shirting.
Strategic Opportunities
- India's PLI scheme for technical textiles:The production-linked incentive program for geotextiles and agrotextiles is redirecting formulation requirements toward UV-stabilized polypropylene coatings in Gujarat's Hazira belt.
- Medical nonwoven functionalization:Antimicrobial quaternary ammonium finishes for surgical gowns represent white space in Vietnam's emerging spunbond-meltblown-spunbond complexes near Ho Chi Minh City.
- Blockchain-enabled chemical provenance:ZDHC-compliant dyestuff tracking through supply chain transparency platforms opens channel innovation for premium European brand compliance verification.
Industry Challenges
- Colorimetric formulation expertise gap:Spectrophotometer-based recipe prediction for digital printing requires technicians trained in CIELAB color space mathematics, a skill scarce in Bangladesh's graduating textile chemistry programs.
- Legacy effluent infrastructure retrofit:Tamil Nadu's Tiruppur cluster faces capital intensity for anaerobic baffled reactor upgrades to meet zero liquid discharge mandates, straining working capital for mid-scale dyehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Textile Chemicals Market |
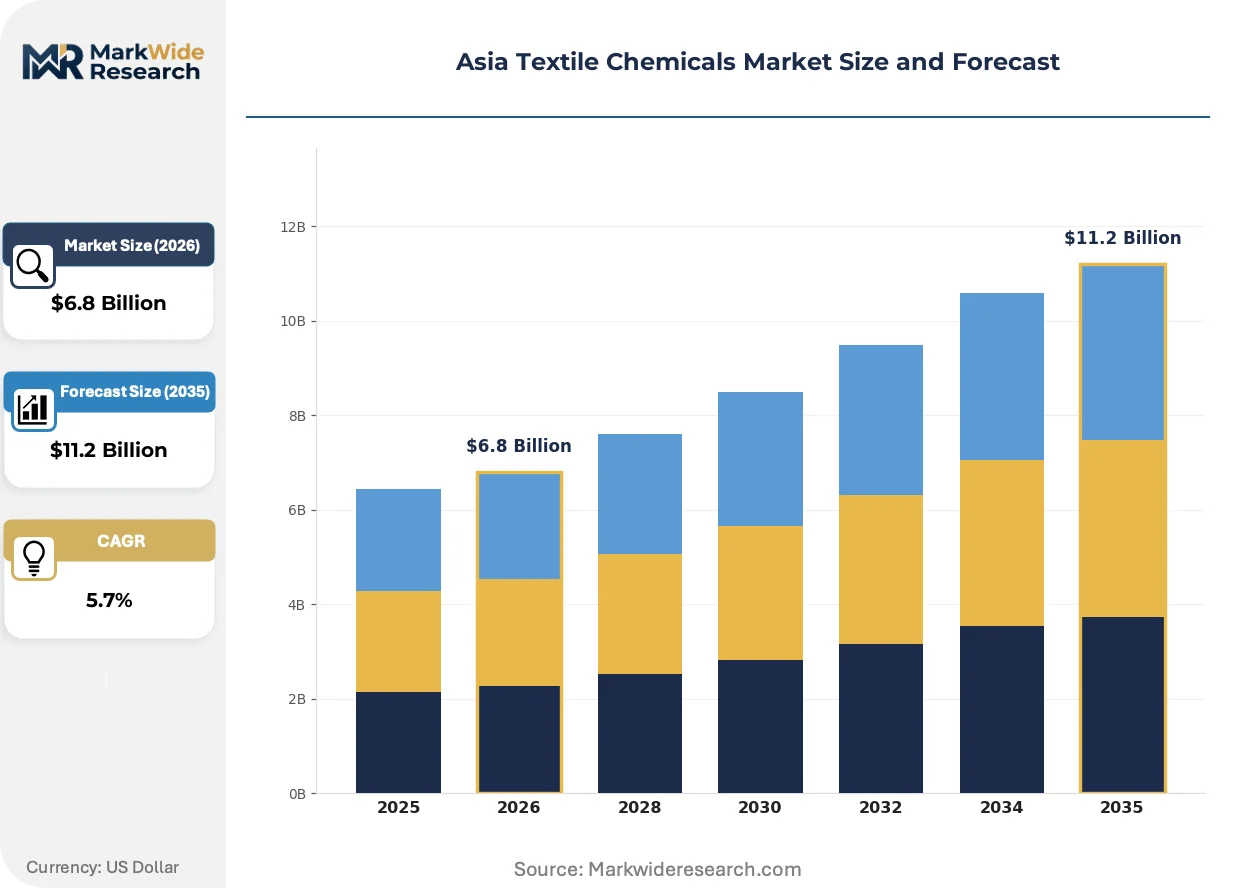
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Auxiliaries, Coatings, Surfactants Application: Home Textiles, Apparel, Technical Fabrics, Nonwovens End User: Manufacturers, Retailers, Wholesalers, Exporters Technology: Digital Printing, Conventional Dyeing, Finishing, Coating |
| Companies Covered | Huntsman Corporation, Archroma Management LLC, DyStar Group, BASF SE, Clariant AG, Solvay S.A., The Lubrizol Corporation, Fineotex Chemical Limited, Skychem Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Textile Chemicals Market Strategic Shifts
Formulation science is pivoting from commodity auxiliaries toward engineered systems that bond at lower temperatures with half the water volume, while regulatory chemistry compliance becomes a product differentiator rather than a cost center.
Supercritical CO2 dyeing technology is automating polyester coloration by eliminating water entirely from the exhaustion phase. Italian machinery licensors are installing pilot lines at Chinese filament producers in Sichuan province. The process is automating lead time compression from 72-hour batch cycles to 4-hour continuous processing, threatening conventional jet dyeing equipment suppliers.
India's BIS certification for textile colorants is restricting import pathways for uncertified reactive dye intermediates from Chinese suppliers. Domestic compounders in Ankleshwar and Vapi are accelerating local intermediate synthesis to maintain formulation continuity. The synthetic fiber segment faces the steepest compliance timeline, with certificate-of-origin documentation now mandatory for EU-destined exports.
Brand-led chemical management is consolidating supplier relationships around full-service color and compliance contracts rather than transactional dyestuff purchases. European fast-fashion retailers are auditing Asian mill partners against ZDHC Manufacturing Restricted Substances List conformance, replacing spot-buying with multi-year technical service agreements. Vietnam's integrated spinning-weaving-dyeing parks in Phu Yen province exhibit the most advanced adoption of this bundled procurement model.
Asia Textile Chemicals Market Segmentation
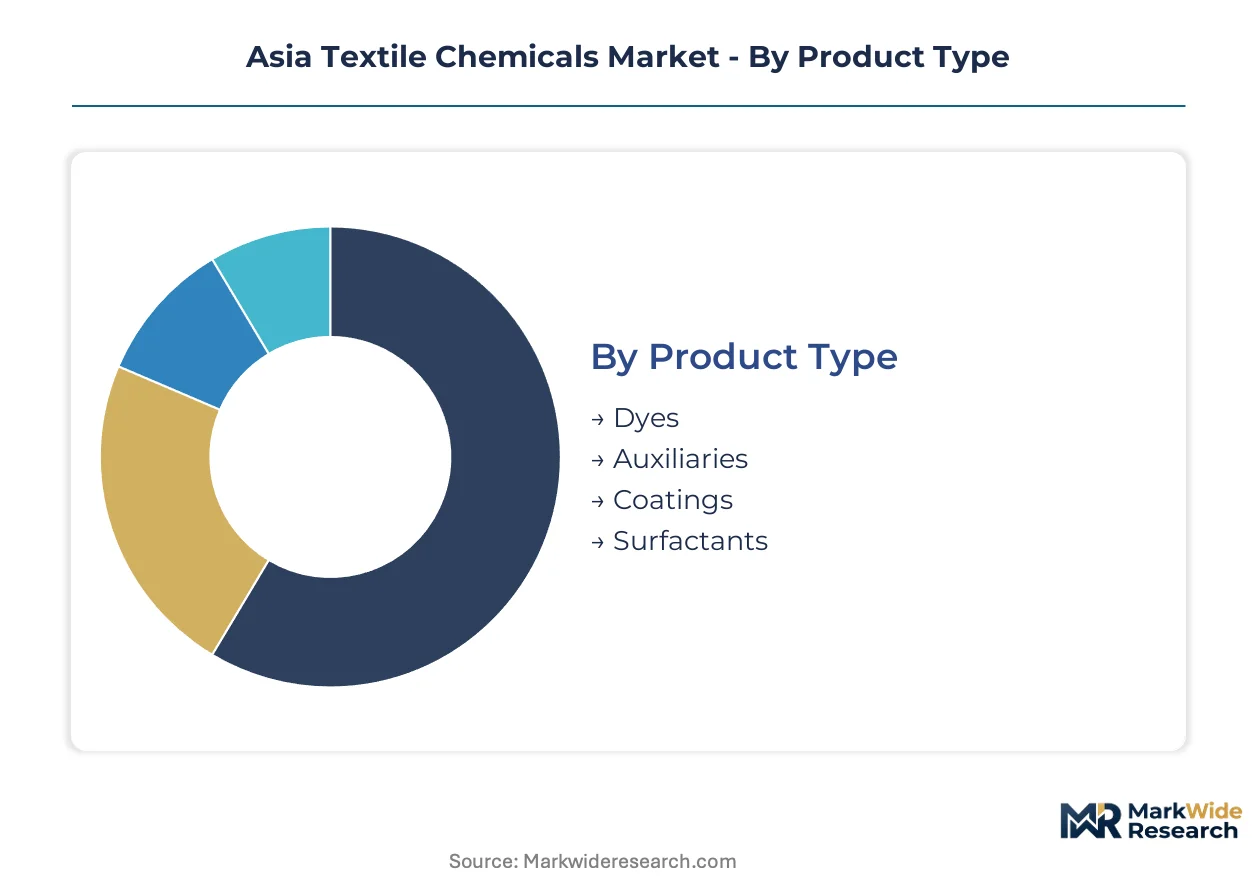
Segmentation in Asia textile chemicals reveals how formulation requirements diverge across fiber types, processing temperatures, and regulatory exposure zones. Understanding these splits allows suppliers to align R&D spend with margin pools and compliance trajectories.
Product Type:
Volume concentrates in commodity colorants while premium margin pools sit with proprietary auxiliaries engineered for low-impact processing.
- Dyes:Reactive formulations for cotton and viscose dominate Bangladesh's denim sector, where discharge limits from MEE-aligned buyers force migration to salt-reducing bifunctional variants. Disperse dyes for polyester face margin compression from Chinese intermediate concentration in Hubei and Jiangsu.
- Auxiliaries:Sequestering agents, wetting agents, and pH buffers command the deepest margins where proprietary formulations enable low-liquor ratio dyeing at 60°C versus conventional 130°C cycles. Tamil Nadu's Tiruppur cluster sources these through technical service contracts rather than spot purchasing.
- Coatings:Flame-retardant polymer systems for automotive airbag fabric in China's Yangtze Delta require thermal stability above 200°C.
- Surfactants:Biodegradable alternatives to alkylphenol ethoxylates gain traction in Zhejiang dyeing clusters under MEE wastewater mandates.
Today's leader: Auxiliaries. Tomorrow's challenger: Surfactants.
Application:
Technical fabrics command formulation premiums while apparel drives absolute volume through Bangladesh and Vietnam production bases.
- Home Textiles:Bedsheet and curtain producers in India's Panipat cluster specify softening silicone emulsions with durable press performance across 50 home laundering cycles.
- Apparel:Short-run fashion production in Vietnam's Dong Nai province is displacing rotary screen setups with reactive inkjet chemistries that bond at ambient temperature and eliminate steaming stages.
- Technical Fabrics:Geotextile manufacturers in Gujarat's Hazira belt source UV-stabilized polypropylene coatings through India's PLI scheme for technical textiles.
- Nonwovens:Antimicrobial quaternary ammonium finishes for surgical gowns represent white space in Vietnam's emerging spunbond-meltblown-spunbond complexes near Ho Chi Minh City.
Technical fabrics expand most quickly; apparel retains volume dominance.
End User:
Manufacturer relationships harden into multi-year technical service contracts while exporter compliance requirements fragment supplier bases.
- Manufacturers:Integrated spinning-weaving-dyeing parks in Vietnam's Phu Yen province bundle color management, effluent treatment, and chemical supply into single-source agreements audited against ZDHC Manufacturing Restricted Substances List conformance.
- Retailers:European fast-fashion retailers now mandate certificate-of-origin documentation for EU-destined exports, forcing reformulation of restricted azo dyes across their Asian mill networks.
- Wholesalers:Spot-buying persists in fragmented Tamil Nadu trading networks but faces displacement from direct mill procurement.
- Exporters:REACH-aligned standards force compounders in Ankleshwar and Vapi to accelerate local intermediate synthesis for reactive dye continuity.
Manufacturers capture the deepest supplier integration; exporters face the steepest compliance burden.
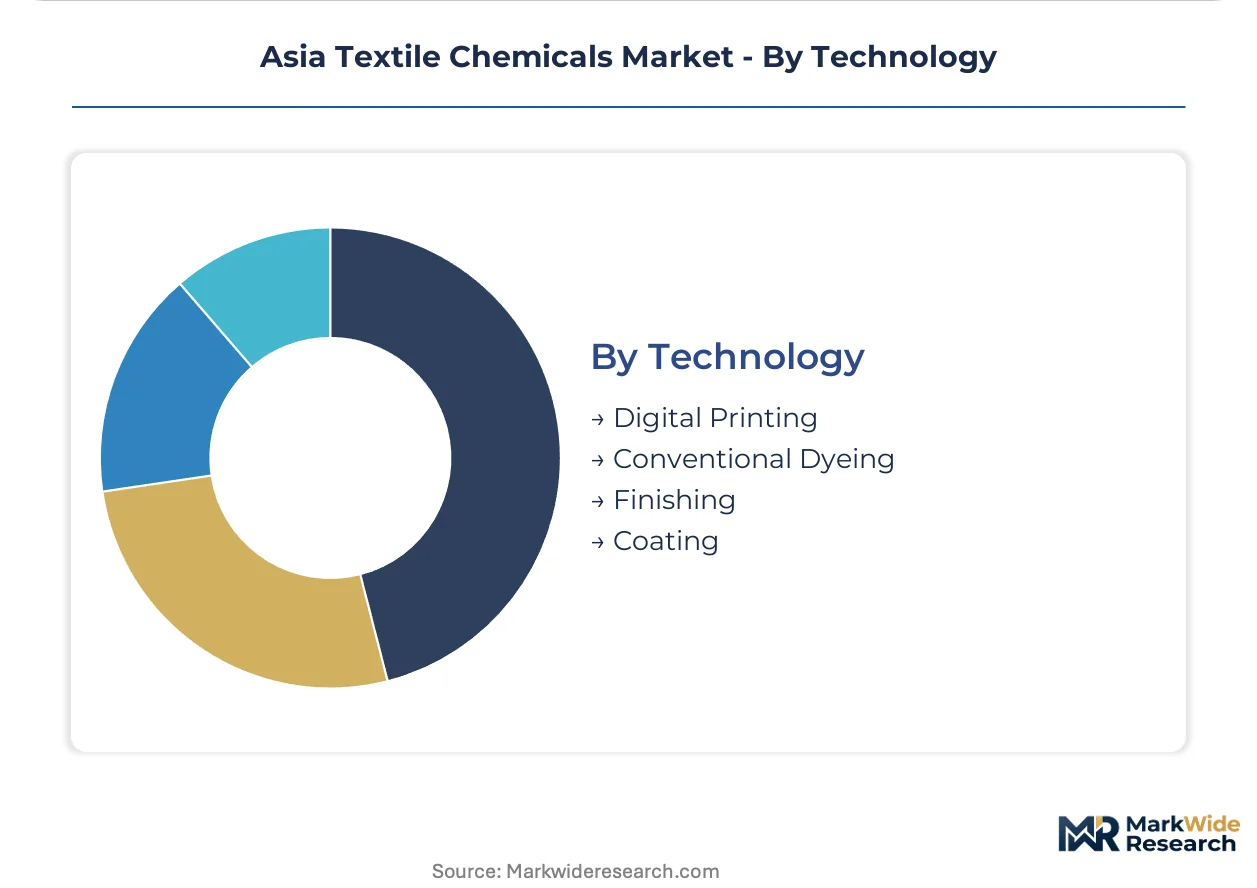
Technology:
Digital printing climbs fastest while conventional dyeing retains installed base dominance across Asian wet-processing capacity.
- Digital Printing:Inkjet-reactive chemistries for cotton and viscose penetrate short-run production in Vietnam, compressing lead times from 72-hour batch cycles to 4-hour continuous processing and eliminating water-intensive washing-off stages.
- Conventional Dyeing:Jet dyeing equipment in Sichuan polyester filament plants faces displacement threat from supercritical CO2 pilot lines that eliminate water entirely from exhaustion phases.
- Finishing:Non-iron cotton treatments using DMDHEU resins face substitution pressure from citric acid crosslinkers with inferior durability below 30 home laundering cycles.
- Coating:Knife-over-roll and dip-coating systems for automotive technical fabrics require solvent recovery infrastructure under China's MEE air emission standards.
Digital printing gains share fastest; conventional dyeing defends through capital depreciation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the deepest formulation demand while India redirects investment toward technical textile corridors under federal incentive programs.
China
Polyester filament producers in Sichuan province pilot supercritical CO2 dyeing lines that eliminate water from exhaustion phases entirely. MEE wastewater discharge limits compel Zhejiang dyeing clusters to adopt membrane bioreactor systems and biodegradable surfactant alternatives. Yangtze Delta automotive airbag fabricators specify flame-retardant polymer coatings requiring thermal stability above 200°C.
India
Tamil Nadu's Tiruppur cluster sources proprietary auxiliaries through technical service contracts rather than spot purchasing for low-liquor ratio dyeing. BIS certification mandates for textile colorants restrict import pathways for uncertified reactive dye intermediates. Gujarat's Hazira belt accelerates UV-stabilized polypropylene coating production under the PLI scheme for technical textiles.
Vietnam
Dong Nai province apparel producers displace rotary screen setups with reactive inkjet chemistries that bond at ambient temperature. Spunbond-meltblown-spunbond complexes near Ho Chi Minh City represent white space for antimicrobial quaternary ammonium finishes in surgical gown applications. Phu Yen province integrated parks bundle color management and chemical supply into ZDHC-audited single-source agreements.
Bangladesh
Denim sector reactive formulations for cotton and viscose face discharge limits from MEE-aligned buyers forcing migration to salt-reducing bifunctional variants. Spectrophotometer-based recipe prediction for digital printing requires technicians trained in CIELAB color space mathematics, a skill scarce in graduating textile chemistry programs. Short-run fashion production compresses lead times from 72-hour batch cycles to 4-hour continuous processing.
Thailand
Compounders lacking backward integration face geographic concentration risk from Chinese anthraquinone disperse dye intermediate suppliers in Hubei and Jiangsu provinces. REACH-aligned standards for EU-destined exports force reformulation of restricted azo dyes and formaldehyde-based finishers. Industrial clusters source through direct mill procurement that displaces fragmented spot-buying networks.
Asia Textile Chemicals Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation science capabilities determining margin capture in auxiliaries versus commodity positioning in base dyes. The market structure concentrates around multinational chemical conglomerates with captive R&D infrastructure and regional compounders serving discrete industrial corridors. Three archetypes dominate: integrated innovators with backward intermediate control, technical service bundlers, and specialty surfactant formulators. Competitive moves center on portfolio diversification into low-impact chemistries and geographic expansion through technical licensing partnerships.
Among multinational anchors, Huntsman Corporation, Archroma Management LLC, and DyStar Group occupy distinct positioning vectors. Huntsman exemplifies the integrated innovator archetype through captive R&D centers developing fiber-specific formulations. Archroma represents the technical service bundler model with sustainable chemistry portfolios aligned to compliance pathways. DyStar sits within the backward-integrated tier, controlling input costs through captive intermediate manufacturing. These three collectively illustrate how competitive advantage in Asian textile chemicals derives from either upstream supply control or downstream service integration rather than transactional commodity supply.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Archroma Management LLC |
| DyStar Group |
| BASF SE |
| Clariant AG |
| Solvay S.A. |
| The Lubrizol Corporation |
| Fineotex Chemical Limited |
| Skychem Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap compounders across India's Ankleshwar and Vapi industrial belts maintain pricing discipline through captive intermediate synthesis, insulating formulation margins from Chinese anthraquinone supply volatility while passing through only partial feedstock cost movements to Tamil Nadu dyehouse customers under technical service contracts.
Pricing Analysis
Capacity additions in Vietnam's Phu Yen integrated parks are reshaping price floors for bundled color management and chemical supply contracts. Three-tier pricing structure across ZDHC-compliant premium, BIS-certified standard, and uncertified economy levels differentiates dyestuff quotations, with European fast-fashion retailers occupying the least price-sensitive tier. Cost compression in commodity reactive dyes is intensifying because Chinese intermediate concentration in Hubei and Jiangsu provinces eliminates margin bargaining power for Thai compounders lacking backward integration.
Supply Chain Analysis
Regional distribution centers in Shanghai, Bangkok, and Mumbai anchor hub-and-spoke patterns for just-in-time auxiliary delivery to Zhejiang and Tiruppur dyeing clusters. Geographic supply concentration centers on China for polyester intermediates, India for cotton reactive dyes, and Germany for specialty surfactant feedstocks. Raw material dependencies rest on naphtha-derived ethylene oxide, propylene oxide, and imported anthraquinone intermediates. Single-source vulnerability from Hubei and Jiangsu anthraquinone control threatens Thai and Indonesian compounders. Distribution runs through direct mill procurement in Vietnam's integrated parks and fragmented trading networks in Tamil Nadu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia textile chemicals hinges on reformulation premiums for low-liquor ratio auxiliaries and ZDHC-compliant sustainable chemistry portfolios that command pricing power over commodity dyestuff supply.
For Market Incumbents: Anticipate displacement of conventional jet dyeing equipment by supercritical CO2 pilot lines in Sichuan polyester plants by deepening technical service bundling around effluent treatment and color management systems. Prioritize backward integration into reactive dye intermediates to defend formulation continuity against India's BIS certification mandates restricting Chinese import pathways. For New Entrants and Emerging Players: Enter via antimicrobial quaternary ammonium finishes for Vietnam's emerging spunbond-meltblown-spunbond surgical gown complexes near Ho Chi Minh City, the most penetrable white space in medical nonwoven functionalization. Target Gujarat's Hazira belt for UV-stabilized polypropylene coating supply under India's PLI scheme for technical textiles, leveraging technical licensing partnerships with Italian machinery licensors for supercritical CO2 dyeing know-how transfer. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders in Ankleshwar and Vapi accelerating local intermediate synthesis to circumvent BIS restrictions. Long-term viability over the next decade rests on formulation science capabilities in low-impact chemistries rather than transactional commodity positioning. Watch membrane bioreactor adoption rates in Zhejiang dyeing clusters as the inflection signal for biodegradable surfactant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Ankleshwar compounders secure formulation continuity against India's BIS certification import restrictions. |
| Technical Service Contract Expansion | Tamil Nadu dyehouse bundling of color management and effluent treatment hardens recurring revenue streams. |
| Low-Impact Chemistry R&D Investment | Shanghai captive centers develop polyester-specific dyestuffs aligned with China's dual carbon goals. |
| ZDHC Compliance Pathway Certification | European fast-fashion retailer auditing opens premium channel access for verified sustainable formulations. |
| Supercritical CO2 Technology Licensing | Italian machinery partnerships automate lead time compression from 72-hour batch cycles to 4-hour processing. |
Study Parameters
Coverage spans China, India, Vietnam, Bangladesh, and Thailand, with primary inputs from each market combining interviews with plant managers at Zhejiang dyeing clusters, procurement leads at Vietnam's integrated parks, technical R&D directors at multinational anchors, distribution channel partners in Tamil Nadu trading networks, and regulatory affairs specialists navigating BIS and MEE compliance. Secondary validation draws from customs and trade data, SEC 10-K filings of listed chemical conglomerates, ACC and Cefic regional reports, and ZDHC Manufacturing Restricted Substances List documentation. Bottom-up and top-down triangulation reconciles facility-level capacity assessments with macroeconomic demand modeling.
Granularity-level modeling operates at the intersection of fiber type, processing temperature band, and regulatory exposure zone across the projection horizon. Segmentation dimensions include product type tier, end-use application, technology platform, and regional production hub. CAGRs derive from trend extrapolation of digital printing penetration rates, automotive technical fabric specification growth, and wastewater treatment mandate enforcement intensity. Industry-specific forecast inputs incorporate PLI scheme disbursement trajectories for Gujarat technical textiles and MEE discharge limit compliance cost curves for Zhejiang clusters.
Inputs from plant managers and customs databases were available through the study window; gaps in real-time anthraquinone intermediate inventory levels and undisclosed technical service contract pricing introduce uncertainty bands around auxiliary margin estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and polymer feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market