
 Sun Protective Clothing Market | 2026-2036
Sun Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Protective Clothing Market Outlook
Market Overview
UPF 50+ certification under the ARPANSA/AS/NZS 4399 standard is reorganizing competitive entry, forcing smaller brands toward third-party lab validation. Columbia Sportswear Company leverages its wholesale relationships with outdoor retailers to sustain shelf presence across North American sporting goods chains. Coolibar Sun Protective Clothing anchors the medical-grade segment through dermatologist partnerships and clinic-based distribution. Solbari Sun Protection differentiates via direct-to-consumer digital channels that bypass traditional wholesale markups.
Technical Definition and Segment Structure
Sun protective clothing denotes engineered garments with ultraviolet protection factor ratings, typically constructed from tightly woven synthetic fibers or chemically treated textiles that block over 98 percent of UVA and UVB radiation for occupational and recreational skin safety. The primary commercial purpose centers on preventing cumulative solar damage in high-exposure demographics including agricultural laborers, maritime crews, and pediatric populations. Hats and swimsuits capture disproportionate margin pools due to seasonal scarcity and fashion-trend pricing power, while polyester dominates material volumes because of its inherent UV resistance and lower cost base than nylon alternatives. The online retail channel is accelerating fastest as telemedicine referrals and influencer dermatology content drive self-directed purchasing among melanoma-risk consumers.
Regulatory Environment and Outlook
The Australian Radiation Protection and Nuclear Safety Agency sets the world's most stringent UPF testing protocols, while the U.S. Federal Trade Commission polices anti-cancer marketing claims under its truth-in-advertising enforcement. The EU's REACH regulation governs chemical UV absorbers in textile treatments, creating compliance cost barriers for brands sourcing from non-European dye houses. Stakeholders must monitor emerging state-level occupational heat standards in the United States that could mandate employer-provisioned protective apparel for outdoor construction and agriculture crews.
Market Dynamics
Employer-mandated occupational sun protection mandates are restructuring procurement volumes across agricultural, maritime, and construction sectors, converting individual consumer purchases into enterprise contract flows.
Growth Catalysts
- Australian melanoma awareness infrastructure:ARPANSA's UPF 50+ certification protocols have normalized daily protective apparel wear, creating sustained baseline demand that other jurisdictions are beginning to emulate.
- EU ECHA chemical safety framework:Tighter certification requirements for UV-blocking textile treatments are accelerating third-party lab validation adoption among mid-tier manufacturers seeking market access.
- Polyester fiber engineering:Advances in inherent UV resistance without chemical treatments are reducing production costs and compliance burdens for high-volume outdoor workwear suppliers.
Market Restraints
- REACH chemical absorber restrictions:The EU's ban on certain benzotriazole-based UV stabilizers is forcing reformulation cycles that extend product development timelines by 12-18 months.
- Dye house geographic concentration:Seventy percent of specialized UV-treatment textile finishing capacity remains clustered in China's Zhejiang province, exposing supply chains to concentrated regulatory and logistics risk.
- Performance-perception gaps:Consumer skepticism about UPF ratings versus SPF lotions limits premium pricing capture in recreational segments despite superior protection metrics.
Strategic Opportunities
- Pediatric school uniform mandates:Australian state education departments are piloting compulsory UPF-rated uniform policies that could replicate across Queensland and New South Wales public systems.
- Telemedicine referral channels:Dermatology clinics in the United States are building direct-to-patient apparel recommendation workflows that bypass traditional retail markup structures.
- Occupational heat standard convergence:Emerging OSHA state-plan amendments in California and Washington may mandate employer-provisioned protective apparel for outdoor crews, institutionalizing bulk procurement.
Industry Challenges
- ARPANSA/AS/NZS 4399 testing bottlenecks:Limited accredited laboratory capacity in Australia is creating certification queues that delay product launches by 4-6 months.
- Cross-border chemical compliance:Brands sourcing from non-European dye houses face divergent REACH, TSCA, and state-level chemical disclosure requirements that fragment quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Protective Clothing Market |
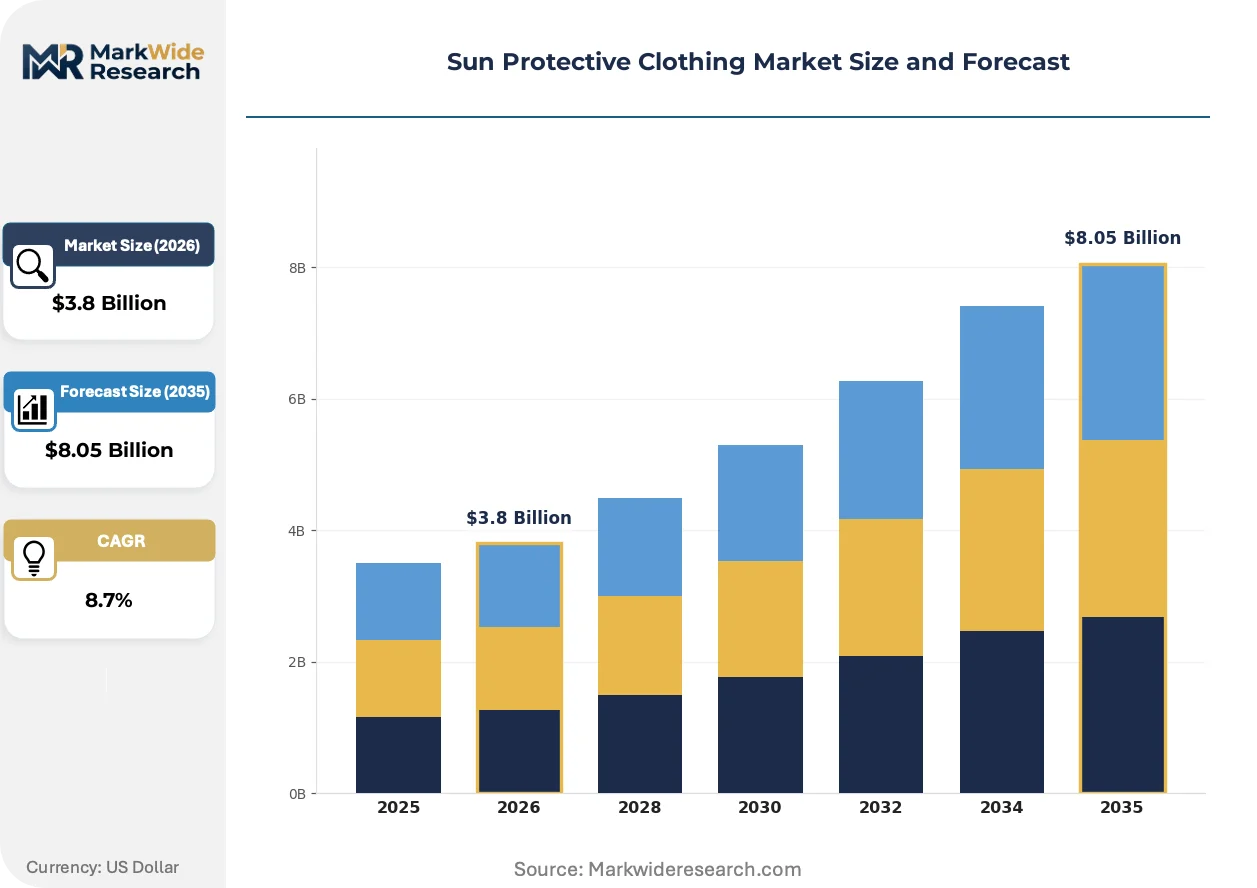
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Pants, Hats, Swimsuits Material: Polyester, Nylon, Cotton, Blends End User: Children, Adults, Athletes, Outdoor Workers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Brand Outlets |
| Companies Covered | Solbari Sun Protection, Solumbra, Columbia Sportswear Company, Little Leaves Clothing Company, SummerSkin, Coolibar Sun Protective Clothing, Cabana Life, IBKUL, UV Skinz, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Protective Clothing Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are compressing the competitive window for undifferentiated UV-protective apparel while elevating certified medical-grade positioning.
Mechanically woven high-density polyester microfibers with inherent UV-blocking properties are supplanting chemically treated cotton blends in base-layer production. Agricultural employers in Australia's Queensland region are specifying these materials in enterprise tenders to eliminate re-treatment compliance costs. The shift is compressing margins for suppliers dependent on recurring chemical finish application revenue streams.
REACH authorization requirements for benzophenone derivatives are forcing textile finishers to validate alternative UV absorber chemistries ahead of 2026 sunset dates. German chemical suppliers are accelerating bio-based triazine development programs to capture reformulation contracts from Asian dye houses. European brands with captive finishing capacity are securing first-mover advantage in premium certification tiers.
Self-directed purchasing through dermatologist-affiliated digital platforms is fragmenting traditional wholesale concentration among outdoor retailers. Melanoma-risk consumers in the United States are bypassing sporting goods channels entirely after telemedicine consultations. This channel rotation is most pronounced in coastal California and Florida markets where dermatology clinic density supports localized fulfillment networks.
Sun Protective Clothing Market Segmentation
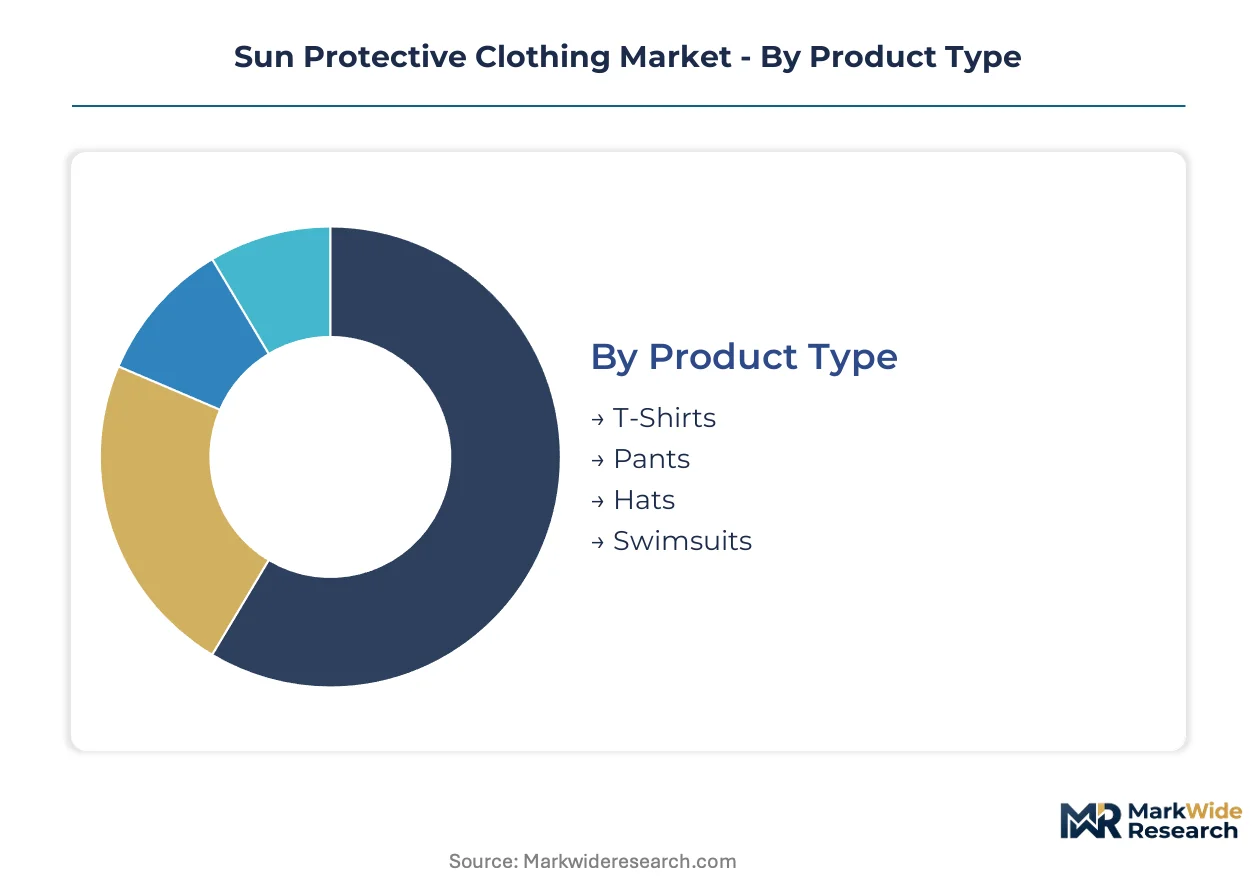
Segmentation in sun protective clothing reveals how protection requirements diverge across use cases, materials, and procurement channels. Margin capture varies dramatically between medical-grade positioning and mass-market recreational lines.
Product Type:
Hats and swimsuits command premium pricing power due to seasonal scarcity and fashion-trend velocity, while T-shirts and pants compete on volume and replacement frequency.
- Hats:Wide-brim and legionnaire designs incorporate UPF 50+ rated fabrics with adjustable neck flaps for agricultural laborers in Australia's Queensland region. ARPANSA certification mandates are converting employer procurement toward verified brim-width specifications, tightening supplier qualification.
- Swimsuits:One-piece and rash guard constructions utilize chlorine-resistant polyester with dense weave structures blocking over 98 percent of UVA/UVB radiation. Australian state education pilot programs for compulsory UPF-rated school uniforms are accelerating bulk tender volumes for youth competitive swim programs.
- T-Shirts:Long-sleeve base layers with inherent UV resistance dominate outdoor workwear contracts in California's Central Valley agricultural belt.
- Pants:Convertible zip-off designs serve maritime crews requiring adaptable coverage across variable exposure conditions.
The dominant share belongs to T-Shirts, while Swimsuits is closing the gap fastest.
Material:
Cost tiers separate chemically treated natural fibers from engineered synthetics with inherent UV-blocking properties, with compliance burden driving procurement preferences.
- Polyester:High-density microfiber constructions achieve UPF 50+ ratings without chemical finish applications, reducing REACH compliance costs for European market access. Queensland agricultural employers specify these materials in enterprise tenders to eliminate re-treatment documentation requirements.
- Nylon:Lighter weight and superior moisture-wicking performance command athletic segment premiums, though higher raw material costs limit penetration in price-sensitive occupational contracts.
- Cotton:Natural fiber preference among pediatric segments in Australian school uniform mandates requires benzotriazole-based UV absorber treatments facing ECHA authorization sunset pressures.
- Blends:Polyester-cotton combinations balance comfort perception with performance certification for recreational consumers in Florida's coastal dermatology referral networks.
Polyester holds the volume lead, though Nylon is gaining share fastest among performance athletic applications.
End User:
Application context determines whether procurement flows through individual self-directed purchasing or enterprise contract structures with compliance documentation requirements.
- Outdoor Workers:Agricultural, maritime, and construction employers in California and Washington state-plan jurisdictions are mandating employer-provisioned protective apparel under emerging occupational heat standards, institutionalizing bulk procurement with certified UPF documentation.
- Children:Pediatric populations in Australian public school systems face compulsory UPF-rated uniform policies piloting across Queensland and New South Wales, creating institutional demand detached from individual purchasing decisions.
- Adults:Melanoma-risk consumers in Florida and coastal California bypass traditional retail through dermatology clinic-affiliated digital fulfillment networks.
- Athletes:Competitive endurance segments prioritize moisture management and thermal regulation alongside UV protection, driving material specification toward premium nylon constructions.
Outdoor Workers represents the institutional anchor, while Children is expanding most quickly through education policy mandates.
Distribution Channel:
Channel selection fragments between wholesale concentration among outdoor retailers and direct-to-consumer bypass of traditional markup structures.
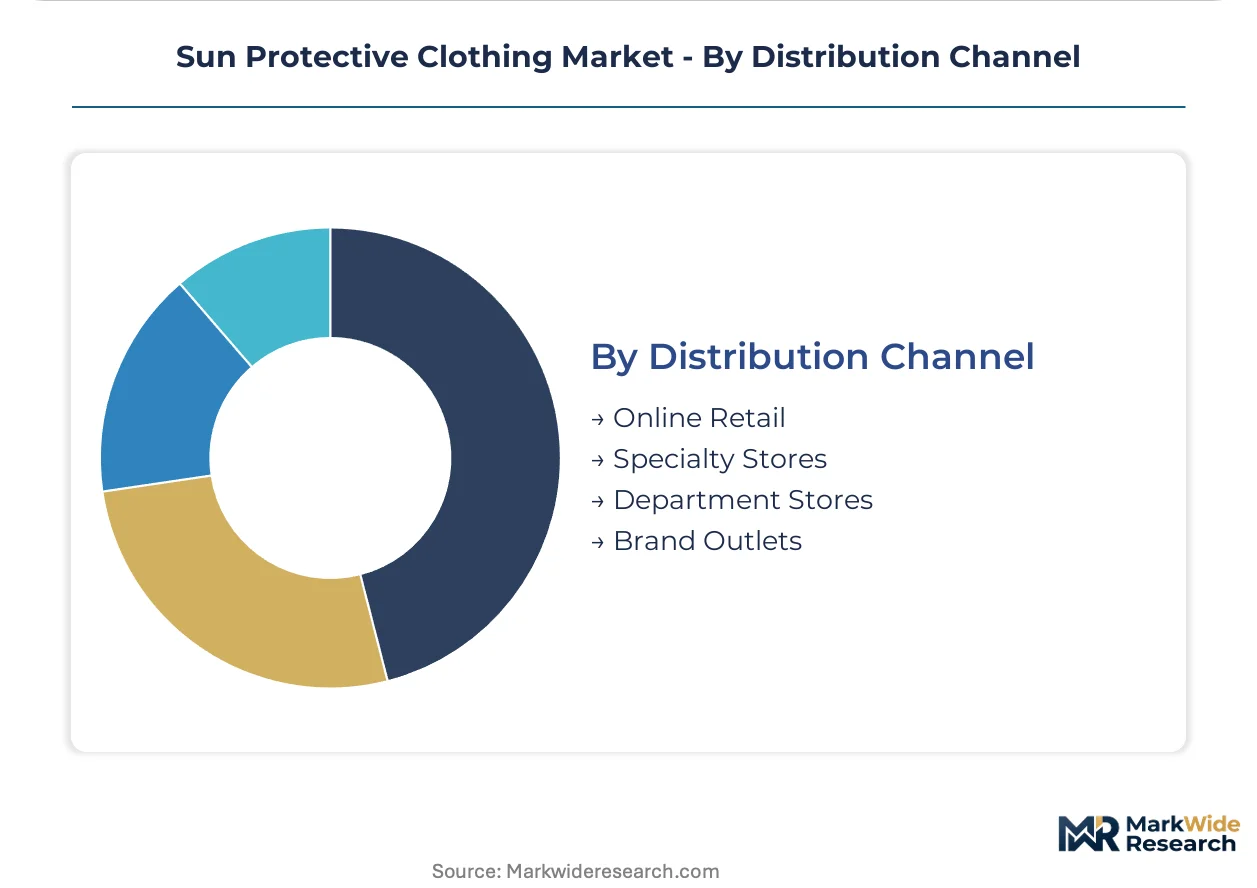
- Online Retail:Telemedicine referral workflows and influencer dermatology content drive self-directed purchasing among melanoma-risk consumers, with localized fulfillment networks emerging in high dermatology clinic density markets.
- Specialty Stores:Outdoor retailers in North American sporting goods chains maintain shelf presence for recreational segments through wholesale relationships with established apparel brands.
- Department Stores:Seasonal fashion-trend positioning captures swimsuit and casual hat volumes during peak UV exposure months.
- Brand Outlets:Medical-grade positioning through dermatologist partnerships and clinic-based distribution anchors premium certification tiers for high-risk patient populations.
Online Retail is capturing share fastest, though Specialty Stores retains the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-provisioned occupational apparel and institutional procurement programs concentrate demand across agricultural belts, maritime corridors, and pediatric education systems. Buyer archetypes split between enterprise contract flows and melanoma-risk consumer self-direction, with regulatory pressure accelerating certified UPF adoption.
Australia
Queensland agricultural employers specify ARPANSA-certified UPF 50+ apparel in enterprise tenders, eliminating re-treatment documentation burdens. State education departments in New South Wales pilot compulsory UPF-rated school uniform policies, creating institutional demand detached from individual purchasing. Melbourne and Sydney host dermatology clinic networks that normalize daily protective wear through patient education programs.
United States
California's Central Valley agricultural belt and Florida's coastal melanoma-risk populations drive divergent procurement channels. OSHA state-plan amendments in California and Washington mandate employer-provisioned protective apparel for outdoor construction crews, institutionalizing bulk contract flows. Miami and Los Angeles anchor dermatology-affiliated digital fulfillment networks that bypass traditional retail markups.
Germany
REACH authorization timelines for benzotriazole-based UV absorbers force textile finishers to validate alternative chemistries ahead of 2026 sunset dates. ECHA chemical safety framework compliance costs accelerate third-party lab validation adoption among mid-tier manufacturers. Bavaria-based chemical suppliers accelerate bio-based triazine development to capture reformulation contracts from Asian dye houses.
China
Zhejiang province concentrates seventy percent of specialized UV-treatment textile finishing capacity, exposing supply chains to regulatory and logistics risk. Domestic demand from outdoor workwear exporters faces divergent REACH, TSCA, and state-level chemical disclosure requirements. Shanghai and Guangzhou serve as export consolidation points for Australian and North American market access.
United Kingdom
NHS dermatology referral pathways increasingly incorporate UPF-rated apparel recommendations for melanoma-risk patients. The Medicines and Healthcare products Regulatory Agency aligns with EU chemical safety standards for textile treatments despite post-Brexit regulatory divergence. London anchors telemedicine platforms that drive self-directed purchasing among high-risk consumer segments.
Sun Protective Clothing Market Competitive Environment
Player mix skews toward specialty outdoor apparel manufacturers with wholesale retail relationships and direct-to-consumer medical-grade specialists with dermatology channel access. Market structure exhibits moderate concentration, with established sporting goods brands holding shelf presence while digital-native entrants fragment premium tiers. Two strategic archetypes dominate: wholesale-dependent outdoor retailers leveraging distribution scale, and clinic-affiliated direct sellers capturing margin through referral bypass. Competitive moves center on certification pre-emption and channel rotation toward telemedicine referral workflows.
Within the medical-grade tier, Coolibar Sun Protective Clothing and Solbari Sun Protection occupy positions anchored by dermatologist partnerships and clinic-based distribution. Columbia Sportswear Company represents the wholesale-dependent archetype, sustaining shelf presence across North American sporting goods chains through established retail relationships. These three exemplify the bifurcation between institutional healthcare channel access and mass-market outdoor retail concentration.
| Leading Market Players |
|---|
| Solbari Sun Protection |
| Solumbra |
| Columbia Sportswear Company |
| Little Leaves Clothing Company |
| SummerSkin |
| Coolibar Sun Protective Clothing |
| Cabana Life |
| IBKUL |
| UV Skinz, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term enterprise offtake contracts with Australian agricultural employers lock in ARPANSA-certified UPF 50+ supply access while fixing polyester microfiber pricing against raw material indices. These arrangements insulate high-volume workwear suppliers from spot market volatility while embedding compliance documentation costs into negotiated rates.
Pricing Analysis
Cost-plus contracts with benzotriazole price indexation dominate European procurement under REACH authorization timelines. Three-tier pricing structure across medical-grade certification, enterprise workwear, and recreational retail separates dermatologist-affiliated channels from sporting goods markups. Pricing pressure stems from REACH reformulation cycles extending development timelines. Enterprise buyers in California agricultural belts exhibit lowest price sensitivity due to OSHA mandate compliance requirements, while recreational consumers in Florida show highest elasticity.
Supply Chain Analysis
Inventory buffers for ARPANSA certification queues now stretch lead times for Australian market entry. Zhejiang province in China, Vietnam's textile belt, and Germany's chemical finishing corridor anchor global UV-treatment capacity. Polyester microfiber feedstock, benzotriazole UV absorbers, and bio-based triazine alternatives constitute critical input dependencies. Single-source vulnerability concentrates in Zhejiang's specialized finishing clusters. Distribution runs through dermatology clinic networks, outdoor retailer wholesale, and direct-to-consumer digital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of accredited ARPANSA testing capacity creates bottlenecks that favor incumbents with established certification relationships and capital reserves for queue management. This capability gap limits rapid scaling for new entrants lacking pre-qualified laboratory partnerships.
For Market Incumbents: Consolidate ARPANSA testing slot reservations through multi-year laboratory service agreements to block competitor access. Acquire Queensland-based agricultural workwear distributors to secure employer mandate procurement flows. Vertical integration into high-density polyester microfiber weaving reduces REACH compliance exposure from Asian dye house dependencies.
For New Entrants and Emerging Players: Differentiate on telemedicine referral channel integration with California and Florida dermatology clinic networks. Target pediatric school uniform mandates in Australian state education pilot programs as the most penetrable institutional segment. Pursue direct-to-consumer digital fulfillment with localized inventory positioning near high dermatology clinic density markets.
For Investors and Strategic Acquirers: Capital is best deployed toward clinic-affiliated direct sellers with established dermatologist recommendation workflows rather than wholesale-dependent outdoor retailers facing channel fragmentation. Long-term viability favors medical-grade positioning with recurring patient education touchpoints. Watch for OSHA state-plan amendment adoption velocity across additional jurisdictions as inflection signal for enterprise contract volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ARPANSA Certification Pre-emption | Multi-year laboratory slot reservations block competitor access during 4-6 month certification queues. |
| Backward Integration into Polyester Weaving | In-house high-density microfiber production eliminates REACH compliance exposure from Zhejiang dye houses. |
| Dermatology Clinic Network Partnership | Telemedicine referral workflows bypass traditional retail markups in California and Florida markets. |
| Pediatric School Uniform Tender Participation | Queensland and New South Wales education mandates create institutional demand detached from consumer purchasing cycles. |
| Bio-based Triazine Chemistry Investment | German chemical suppliers capture reformulation contracts ahead of benzotriazole REACH sunset dates. |
Study Parameters
Cross-validation between primary interviews with textile finishing plant managers, ARPANSA laboratory accreditation officers, agricultural employer procurement leads, and dermatology clinic distribution specialists anchors the qualitative findings against secondary validation. Trade customs data from Australian Bureau of Statistics, ECHA authorization databases, California OSHA state-plan filings, and SEC apparel manufacturer disclosures supplement field intelligence. Bottom-up segment sizing triangulates against top-down market reconstruction across product type, material, end user, and distribution channel dimensions.
Sensitivity analysis around REACH authorization timeline assumptions and OSHA state-plan adoption rates frames projection uncertainty. Segmentation modeling incorporates product type, material chemistry, end user procurement structure, and distribution channel concentration across the analysis window. CAGRs derive from volume trajectory analysis adjusted for regulatory inflection points. ARPANSA certification queue durations and employer mandate adoption curves constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and certification capacity assumptions; material deviation in REACH sunset dates or laboratory accreditation expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Uniforms and Workwears Market