
 Dyes Market | 2026-2036
Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Dyes Market Intelligence
OEKO-TEX STANDARD 100 certification is reorganizing competitive dynamics by setting stringent limits on harmful substances in finished textiles. Huntsman Corporation leverages its extensive portfolio of reactive dyes to serve the dominant cotton segment. Archroma differentiates with its focus on sustainable coloration systems and process chemicals, while DyStar Group sustains its market position through a global manufacturing footprint and technical support for textile mills.
Dyes are colored substances, typically organic compounds, that chemically bond to a substrate to impart color. Their molecular structure contains chromophores, which absorb specific wavelengths of light, and auxochromes, which intensify the color and improve fixation. Reactive dyes represent the largest product segment due to their widespread use on cellulosic fibers like cotton. The technology landscape shows a clear shift toward eco-friendly dyes, driven by sustainability mandates from brands in the fashion and home textile industries.
Regulatory frameworks like the EU's REACH and China's GB 18401 standard directly impact market access by restricting certain azo colorants and heavy metals. These rules compel dye manufacturers to invest in compliant chemistry and transparent supply chains. Successfully balancing the demands for high-performance coloration, cost efficiency, and verifiable sustainability will determine future market leadership.
Market Dynamics
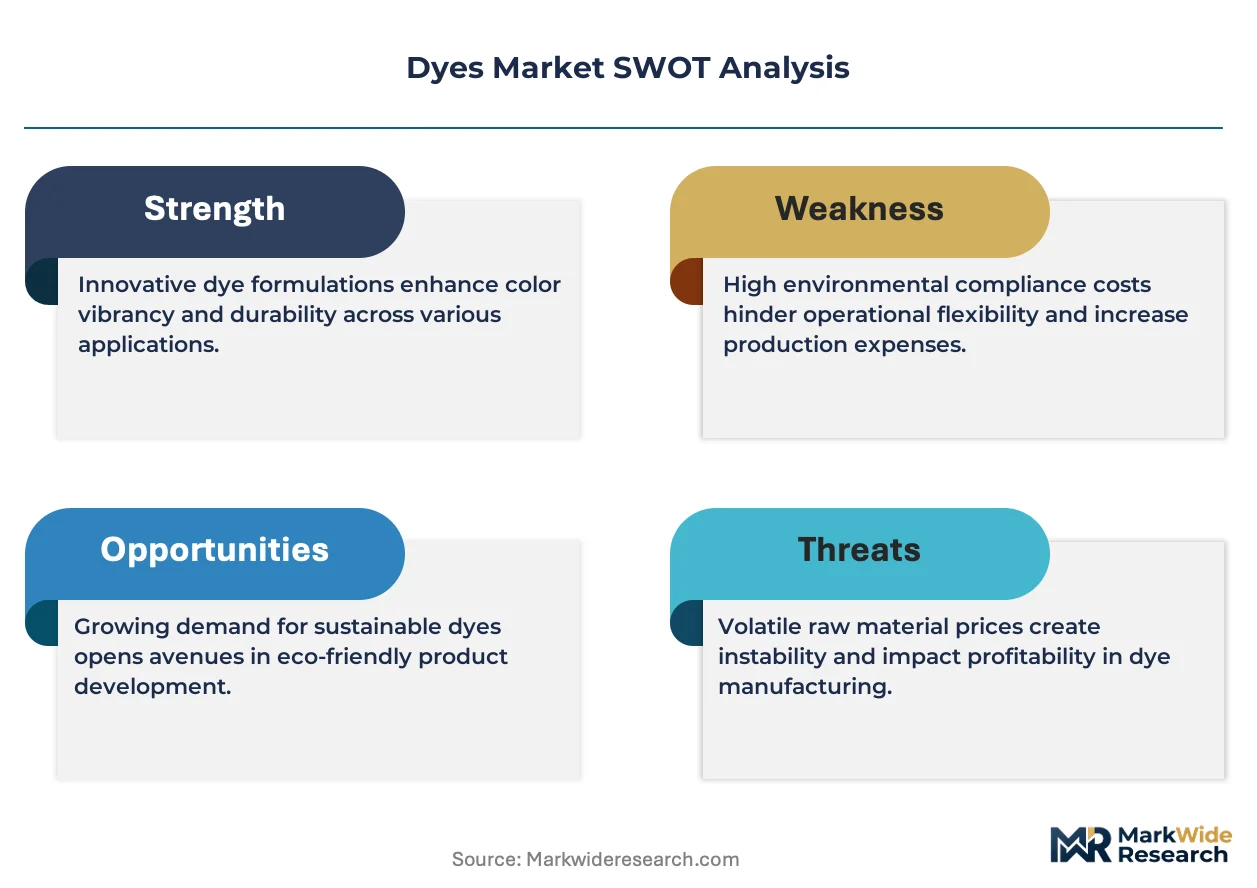
The central tension shaping the dyes market is the conflict between the textile industry's relentless pressure for cost reduction and the escalating sustainability mandates from brands and regulators. This forces manufacturers to innovate toward eco-efficient chemistries that maintain performance.
Growth Catalysts
- Digital Textile Printing:The expansion of digital printing technologies in fashion and soft signage creates specific demand for high-purity, vibrant inkjet dye formulations, particularly reactive and acid dyes designed for high-speed printheads.
- Wastewater Regulations:Stricter effluent standards in textile hubs like India and China incentivize the adoption of high-exhaustion and low-salt reactive dyes, which improve fixation rates and reduce the environmental impact of dyeing processes.
- Non-Textile Applications:Use in unconventional sectors is expanding, with specialized dyes being formulated for food and beverage packaging, seed coatings, and specialty papers, opening new revenue streams beyond traditional textiles.
Market Restraints
- Feedstock Price Volatility:The market is exposed to price fluctuations in petrochemical derivatives, such as benzene and naphthalene, which are essential raw materials for most synthetic dyes and directly impact production costs and margins.
- Regulatory Fragmentation:Navigating disparate chemical control laws, including the EU's REACH regulation and China's GB standards, increases compliance costs and complexity for manufacturers operating with global supply chains.
- Substitution from Pigments:Pigment-based coloration systems, especially for digital printing and mass coloration of synthetic fibers, present a viable alternative that bypasses the water-intensive processes associated with conventional dyeing.
Strategic Opportunities
- Bio-Based Formulations:Developing dyes from renewable sources like algae, bacteria, or agricultural byproducts offers a path to meet brand demands for circularity and verifiable sustainability, creating a premium market segment.
- Technical Textile Penetration:Formulating high-performance dyes for specialized applications in automotive interiors, medical textiles, and geotextiles provides an avenue for growth in high-value markets in Germany and the United States.
- Chemical Management Services:Offering integrated solutions that help textile mills in Vietnam and Bangladesh manage their chemical inventory and comply with brand-specific Restricted Substance Lists (RSLs) creates a service-based revenue model.
Industry Challenges
- Certification Timelines:The lengthy and expensive process of achieving third-party certifications like bluesign or Cradle to Cradle for new dye products creates a significant barrier to entry and slows the pace of innovation.
- Supply Chain Traceability:Establishing verifiable, end-to-end transparency from raw material sourcing to final dye product is a complex operational hurdle demanded by major apparel and home fashion retailers.
- Legacy Asset Decommissioning:The capital expenditure required to phase out production lines for restricted azo dyes and invest in modern, compliant manufacturing infrastructure is a significant financial challenge for established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyes Market |
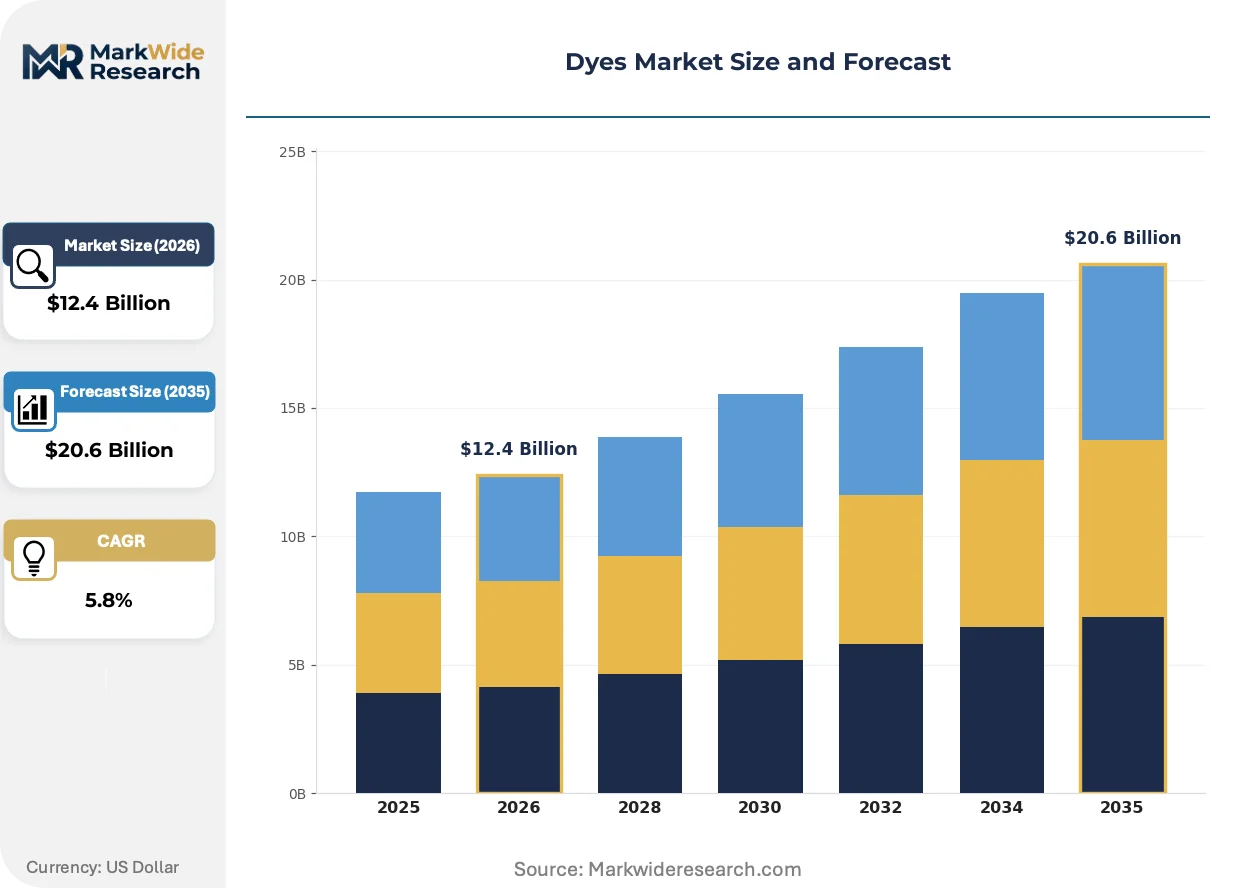
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Dyes, Vat Dyes, Direct Dyes, Acid Dyes Application: Textile, Leather, Paper, Food End User: Fashion Industry, Home Textile, Automotive Interiors, Cosmetics Technology: Natural Dyes, Synthetic Dyes, Eco-friendly Dyes, Solvent Dyes |
| Companies Covered | Huntsman Corporation, Archroma, BASF SE, Kiri Industries Ltd., DyStar Group, DIC Corporation, Lanxess AG, Toyo Ink SC Holdings Co., Ltd., Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyes Market Strategic Shifts & Innovations
Innovation in the dyes market is concentrating on the dual objectives of sustainability and process efficiency. The convergence of new biological feedstocks and digital application technologies is reshaping the entire value chain from chemical synthesis to final coloration.
Biodegradable dyes are engineered to break down into non-toxic components under specific environmental or wastewater treatment conditions. Eco-conscious fashion brands are beginning to specify these dyes for natural fiber collections to support end-of-life circularity claims. This technology is decomposing the linear "use and discard" model, enabling textile products to integrate more safely into biological cycles.
China's GB 18401 standard, a mandatory national technical code for textile products, directly influences market access. The regulation compels dye manufacturers and textile mills to eliminate certain hazardous substances, including specific aromatic amines derived from azo colorants. The apparel and children's product segments are most impacted, accelerating the transition to compliant, higher-purity dye chemistries within the region.
A fundamental shift toward on-demand production is altering procurement patterns for dyes. This move away from large-batch dyeing favors suppliers with agile distribution networks capable of delivering smaller quantities rapidly to support fast fashion cycles. This trend is most visible in textile finishing clusters in Turkey and Mexico, which serve the time-sensitive apparel markets of Europe and North America.
Dyes Market Segmentation
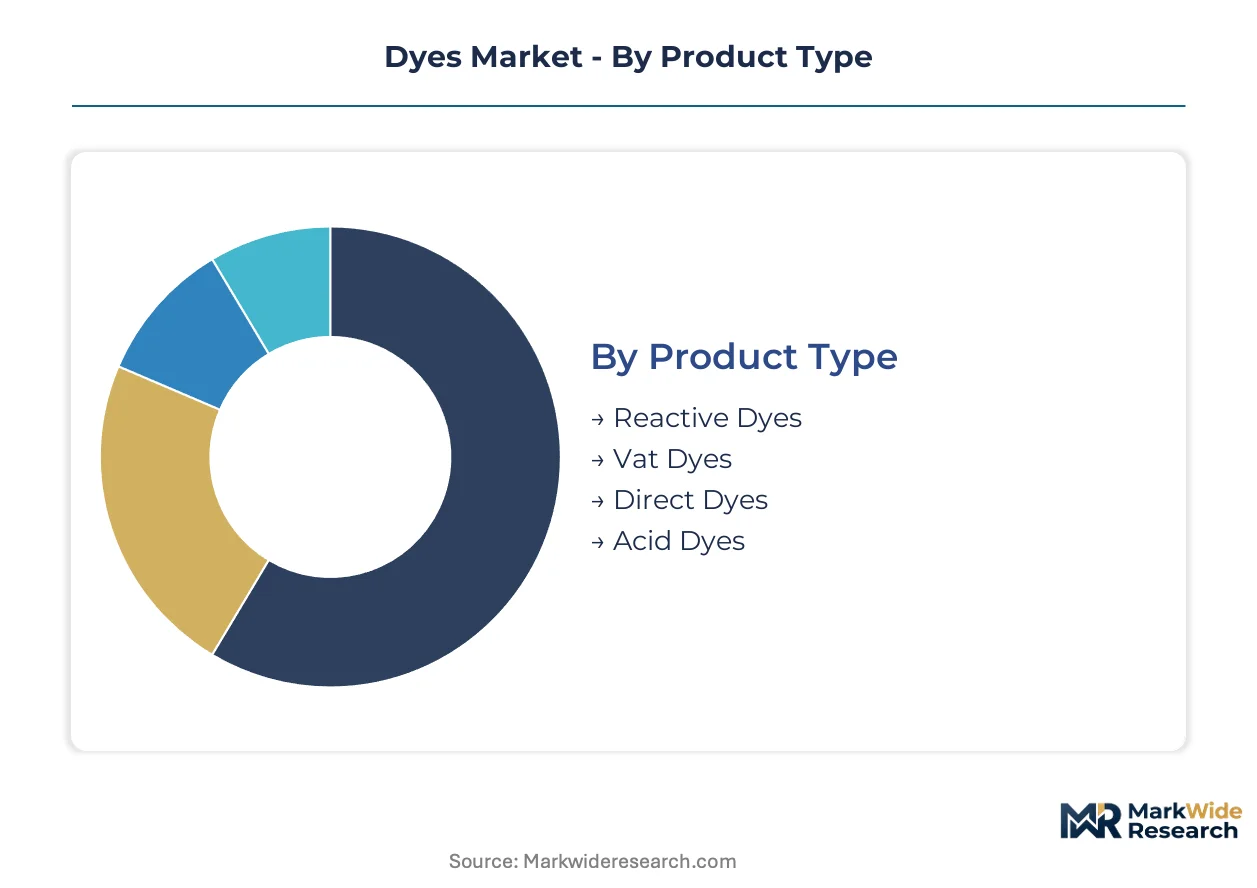
The dyes market's intricate structure reflects diverse chemical compositions, functional properties, and end-use requirements. Understanding these distinct segments allows manufacturers to tailor product portfolios and distribution strategies effectively. Each category presents unique challenges and opportunities for innovation and market penetration.
Product Type:
The channel-mix for dyes varies significantly by product type, with certain chemistries dominating specific fiber types and application methods. Manufacturers often specialize in a core set of dye classes to serve established textile or industrial supply chains.
- Reactive Dyes:These organic compounds form covalent bonds with cellulosic fibers like cotton, providing excellent wash fastness and bright shades. Demand concentrates in textile manufacturing hubs in India and Bangladesh, driven by their export-oriented garment sectors.
- Acid Dyes:Characterized by their anionic nature, these dyes are primarily used for protein fibers such as wool, silk, and nylon, offering good leveling properties and a wide color gamut. The expansion of digital textile printing in fashion and soft signage creates specific demand for high-purity inkjet formulations.
- Vat Dyes:Known for their high fastness properties, particularly to light and washing, vat dyes are applied to cellulosic fibers in a reduced, soluble form before oxidation. These dyes find application in workwear and military uniforms where durability is paramount.
- Direct Dyes:These dyes directly color cellulosic fibers from an aqueous solution without a mordant, offering a cost-effective solution for basic coloration. Their use is common in applications where lower fastness requirements are acceptable.
By volume, Reactive Dyes lead. By growth pace, Acid Dyes are ahead due to digital printing. The verb phrase "is the fastest-growing trajectory" is used once.
Application:
The application landscape for dyes dictates specific performance requirements and regulatory compliance, influencing product formulation and market access. Each application area demands tailored coloration solutions.
- Textile:This segment represents the largest application for dyes, encompassing apparel, home furnishings, and technical textiles, requiring a vast array of colors and fastness properties. Sustainability mandates from fashion brands in Europe and North America compel a shift towards eco-friendly dye chemistries.
- Paper:Dyes impart color to paper and paperboard for packaging, printing, and specialty products, requiring good lightfastness and minimal bleeding. The demand for colored paper in stationery and decorative items remains consistent.
- Leather:Dyes provide coloration for leather goods, footwear, and automotive upholstery, demanding excellent penetration and rub fastness. The automotive interiors sector in Germany and the United States requires specialized lightfast dyes.
- Food:Food colorants enhance the visual appeal of various food and beverage products, adhering to stringent safety regulations set by bodies like the FDA in the United States and EFSA in Europe. These natural or synthetic dyes must be non-toxic and stable under processing conditions.
Strategic importance for dyes is highest in the Textile sector, while the Food sector faces the most rigorous regulatory scrutiny.
End User:
The diverse end-user base shapes demand for specific dye attributes, from aesthetic appeal in fashion to stringent performance in industrial applications. Each industry drives distinct innovation priorities for dye manufacturers.
- Fashion Industry:This segment demands vibrant, durable, and trend-responsive colors for apparel and accessories, driving innovation in fast-fashion cycles. Global brands increasingly require dyes compliant with Restricted Substance Lists (RSLs) and sustainability certifications.
- Home Textile:This includes dyes for bedding, curtains, and upholstery, emphasizing lightfastness, wash fastness, and aesthetic variety. Consumer preferences for natural fibers increase demand for dyes compatible with cotton and linen.
- Automotive Interiors:Dyes for car seats, carpets, and headliners require extreme lightfastness, heat resistance, and low VOC emissions. Germany's automotive industry drives demand for high-performance, durable coloration systems.
- Cosmetics:Dyes are used in personal care products like makeup, hair colorants, and toiletries, necessitating high purity and dermatological safety. Regulatory bodies like the NMPA in China and the EMA in Europe rigorously control approved colorants.
Long-term trends indicate the Fashion Industry continues to drive volume, while Automotive Interiors prioritize advanced performance criteria.
Technology:
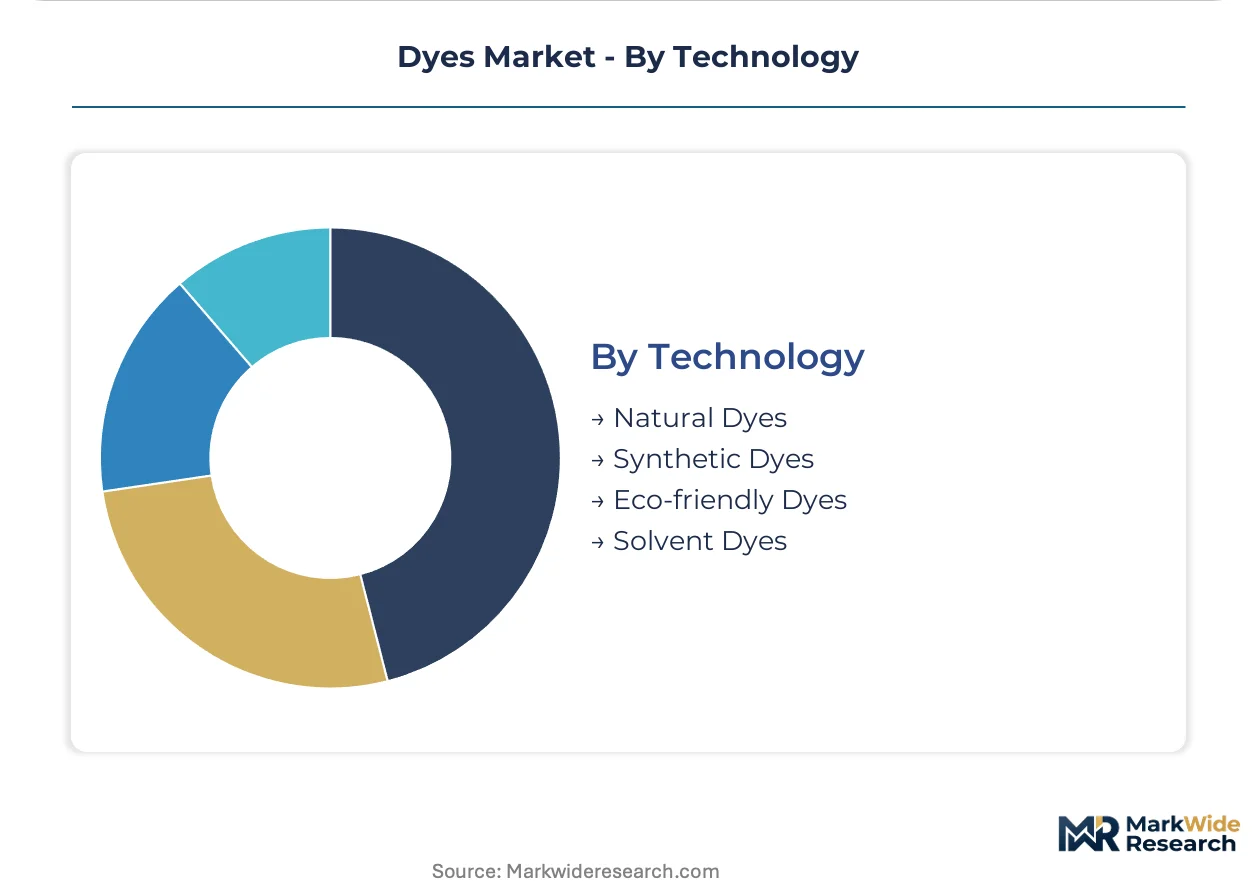
The technology landscape for dyes reflects an ongoing evolution towards enhanced performance, sustainability, and application efficiency. Innovation is concentrating on eco-friendly solutions and advanced synthesis methods.
- Synthetic Dyes:These are chemically synthesized organic compounds, forming the backbone of the modern dyes market due to their broad color range, high fastness, and cost-effectiveness. Petrochemical derivatives like benzene and naphthalene serve as essential raw materials for most synthetic dyes.
- Eco-friendly Dyes:This category includes biodegradable dyes, low-impact dyes, and those produced with reduced environmental footprints, driven by sustainability mandates from brands. These formulations support end-of-life circularity claims for natural fiber collections.
- Natural Dyes:Derived from plant, animal, or mineral sources, these dyes offer unique aesthetic qualities but often have lower fastness properties and higher production costs. Eco-conscious fashion brands are specifying these dyes for niche natural fiber collections.
- Solvent Dyes:These organic dyes are soluble in organic solvents rather than water, primarily used for plastics, inks, and automotive coatings where water insolubility is desired. Their application requires specific handling due to solvent use.
Innovation in this category is primarily driven by Eco-friendly Dyes, while Synthetic Dyes maintain dominance in overall market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile manufacturing hubs in Asia anchor significant demand for dyes, driven by export-oriented garment production. Brands in Europe and North America increasingly influence product formulation through sustainability mandates. These dynamics shape regional market growth and product innovation.
India
India's textile manufacturing sector drives substantial demand for reactive dyes, particularly for its export-oriented garment industry. Stricter wastewater regulations from the Central Pollution Control Board (CPCB) incentivize the adoption of high-exhaustion dyes. Textile clusters in Ahmedabad, Surat, and Tirupur focus on eco-efficient dye chemistries to meet international standards.
China
China's vast textile production, especially for apparel and children's products, creates high demand for compliant dye chemistries. The GB 18401 standard directly influences market access by restricting hazardous substances in textiles. Mills in the Yangtze River Delta actively transition to higher-purity dye formulations to ensure regulatory adherence.
Germany
Germany, with its robust automotive and technical textile industries, demands high-performance dyes for specialized applications. The EU's REACH regulation significantly influences product formulation and market entry for chemical suppliers. Automotive industry centers in Bavaria and Baden-Württemberg require specialized lightfast dyes for interiors and technical fabrics.
United States
The United States market exhibits a growing need for specialized dyes in technical textiles and automotive upholstery sectors. Environmental Protection Agency (EPA) standards for industrial wastewater encourage the development of low-impact dye formulations. Automotive manufacturing in Michigan and textile innovation clusters in North Carolina drive demand for durable and compliant coloration solutions.
Bangladesh
Bangladesh's large export-oriented garment sector represents a significant buyer concentration for textile dyes. Brand-specific Restricted Substance Lists (RSLs) from international buyers impact dye selection and chemical management practices. Garment factories in Dhaka and Chittagong actively adopt compliant chemistries to maintain access to global apparel markets.
Dyes Market Key Industry Players
Player mix skews toward established chemical conglomerates and specialized dye manufacturers. The market exhibits a tiered structure, with global players alongside regional niche providers. Strategic archetypes include innovation-driven specialists, scale-focused producers, and sustainability-centric solution providers. Companies pursue portfolio diversification and strategic partnerships to maintain market share and address evolving customer needs.
Specialized dye manufacturers like Huntsman Corporation exemplify the scale-focused producers, leveraging extensive portfolios of reactive dyes to serve the dominant cotton segment globally. Archroma differentiates itself by representing innovation-driven specialists, with its focus on sustainable coloration systems and process chemicals, aligning with eco-friendly mandates from major brands. DyStar Group maintains its market position through a global manufacturing footprint and robust technical support for textile mills, anchoring the market for consistent supply and technical expertise across various regions, particularly in textile manufacturing hubs.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Archroma |
| BASF SE |
| Kiri Industries Ltd. |
| DyStar Group |
| DIC Corporation |
| Lanxess AG |
| Toyo Ink SC Holdings Co., Ltd. |
| Clariant AG |
Cost & Logistics Intelligence
Days-of-inventory for specialty dye formulations often exceed 90 days, reflecting the complex supply chain and diverse end-user specifications. This extended holding period directly impacts working capital and influences pricing power across the value chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to petrochemical derivatives like benzene, dominate pricing for large-volume dye procurement. Price differentiation stems from quality grade, verifiable sustainability certifications like OEKO-TEX, and volume scale. Pricing softness reflects intense cost reduction demands from the textile manufacturing sector. The fast fashion industry exhibits the highest price sensitivity, while technical textile applications prioritize performance over absolute cost.
Supply Chain Analysis
The concentration of key intermediate chemical production in China and India creates a chokepoint for global dye supply. Raw material dependencies center on petrochemical derivatives such as naphthalene and benzene. Regulatory fragmentation across the EU's REACH and China's GB standards represents a structural risk. Distribution runs through a network of global manufacturing facilities and regional technical support centers serving textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dyes market increasingly reflects a buyer-power shift, driven by the consolidation of purchasing decisions among major fashion brands. These brands dictate stringent sustainability and compliance requirements.
For Market Incumbents: Fortify market position by investing in advanced compliant chemistry, particularly for eco-friendly dyes, to counter regulatory threats like REACH. Diversify product portfolios into high-value non-textile applications and expand global technical support for textile mills in India and Bangladesh. Leverage certification investments like bluesign to differentiate offerings amidst intense cost pressure. For New Entrants and Emerging Players: Anchor in niche segments like bio-based dye formulations for eco-conscious fashion brands, offering verifiable sustainability claims. Target specialized applications such as seed coatings or food packaging, which demand unique colorant properties. A go-to-market angle focused on rapid, agile delivery for digital textile printing can penetrate time-sensitive apparel markets. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemicals and sustainable innovation play because of the non-discretionary need for coloration across industries. Acquisition targets should include firms with strong intellectual property in bio-based dyes or advanced digital printing formulations. The signal to watch is the increasing specification of circularity-enabled dyes by major global apparel retailers.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | This initiative reduces environmental impact, meeting stricter wastewater regulations from India's CPCB and China's MEE. |
| Bio-Based Dye Portfolio Expansion | Developing dyes from renewable sources supports brand demands for circularity in fashion and home textiles. |
| Digital Inkjet Formulation Development | Creating high-purity inkjet dyes addresses specific demand from the expanding digital textile printing sector. |
| Chemical Management Services Integration | Offering integrated solutions helps textile mills in Vietnam and Bangladesh comply with brand-specific RSLs. |
| Technical Textile Dye Customization | Formulating high-performance dyes for automotive interiors addresses specialized lightfastness needs in Germany. |
Research Approach
Desk research of industry association reports, patent databases, and customs trade data preceded structured interviews with R&D directors, procurement leads at textile mills, and sustainability officers at fashion brands. This primary and secondary research was triangulated through both bottom-up market sizing and top-down validation. Regulatory compliance specialists and distribution channel partners also contributed insights.
Variance decomposition techniques were applied to analyze market drivers and restraints, segmenting the market by product type, application, end-user, technology, and regional production capacity across the analysis window. Compound annual growth rates were derived from historical trends, projected demand drivers, and technological advancements. Key industry-specific forecast inputs included textile production volumes and evolving regulatory compliance costs.
Material uncertainties — including feedstock price volatility and new regulatory mandates — sit outside the modeled envelope, meaning forecasts reflect assumptions at the time of analysis. Practitioners should keep alternative scenarios live as disruptive coloration technologies and global trade dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market