
 Global Textile Enzymes Market | 2026-2036
Global Textile Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Enzymes Market Foresight
Pharma-grade enzyme purity standards are rotating into textile manufacturing specifications as brands enforce restricted substance lists. Novozymes leverages its fermentation scale to supply high-activity cellulase concentrates to European denim laundries. AB Enzymes anchors its position through specialized pectinase formulations for natural fiber scouring. BESTZYME BIO-ENGINEERING CO., LTD. competes on cost-optimized amylase production for Asian desizing operations.
Textile enzymes are protein-based biocatalysts, typically operating at 40-60°C and pH 5-9, that accelerate specific chemical reactions in fiber processing without consuming themselves in the reaction. These biocatalysts enable denim bio-polishing, cotton desizing, and fabric scouring while reducing water and energy inputs compared to conventional chemical treatments. Cellulase commands the largest product type position due to its indispensability in cotton finishing and denim abrasion programs. Amylase growth is accelerating as warp sizing mills replace oxidative desizing with enzymatic processes to preserve fiber integrity. Bio-polishing applications concentrate margin pools because fashion brands pay premiums for surface-smoothed knit fabrics with reduced pilling.
EPA effluent guidelines in the United States restrict chemical oxygen load from textile wet processing, pushing finishers toward enzymatic alternatives that generate lower biological oxygen demand. REACH registration requirements in Europe force enzyme suppliers to document toxicological profiles, creating compliance barriers for unregistered biocatalyst imports. The EU Green Deal chemical sustainability targets are reshaping procurement specifications across Mediterranean garment hubs. Stakeholders must monitor how China's MEE wastewater discharge standards and India's CEA water consumption mandates alter regional enzyme formulation preferences.
Market Dynamics
EU Green Deal chemical discharge mandates are compressing the adoption window for enzymatic finishing processes, forcing denim laundries and integrated dyeing units to accelerate bio-polishing investments ahead of regulatory deadlines.
Growth Catalysts
- REACH registration compliance:European chemical sustainability frameworks are mandating toxicological documentation for biocatalyst imports, creating preferential demand for pre-registered enzyme formulations in Mediterranean garment hubs.
- Cellulase performance thresholds:High-activity concentrates are enabling water temperature reductions in cotton finishing lines, cutting energy inputs at Bangladeshi and Turkish denim processing facilities.
- Bangladesh cluster expansion:Denim laundries in the Chittagong region are scaling bio-polishing capacity to maintain EU export eligibility under tightening discharge rules.
Market Restraints
- Fermentation input volatility:Pharmaceutical-grade dextrose and yeast extract costs fluctuate with corn futures, squeezing margins for cellulase concentrate producers.
- Supplier concentration in Denmark:Industrial-scale fermentation capacity for high-activity enzymes remains concentrated among Northern European specialists, creating single-source vulnerability.
- Pectinase temperature limitations:Natural fiber scouring applications face performance ceilings above 60°C, restricting throughput at high-speed continuous processing lines.
Strategic Opportunities
- Indian desizing conversion:Warp sizing mills in Tamil Nadu and Gujarat remain underpenetrated by enzymatic processes, presenting volume expansion potential as CEA water consumption mandates tighten.
- Amylase-pectinase blends:Combined biocatalyst formulations for one-bath pre-treatment are opening technical specification wins at integrated South Asian dyeing units.
- China MEE discharge standards:Wastewater treatment upgrades in Zhejiang and Jiangsu provinces are creating regulatory pull for low-BOD enzymatic alternatives to caustic scouring.
Industry Challenges
- Fermentation technician scarcity:Industrial microbiology expertise for enzyme production scale-up remains concentrated in European and North American talent pools.
- ISO certification timelines:Textile chemical suppliers face 18-24 month validation cycles for pharma-grade purity standards demanded by restricted substance lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Enzymes Market |
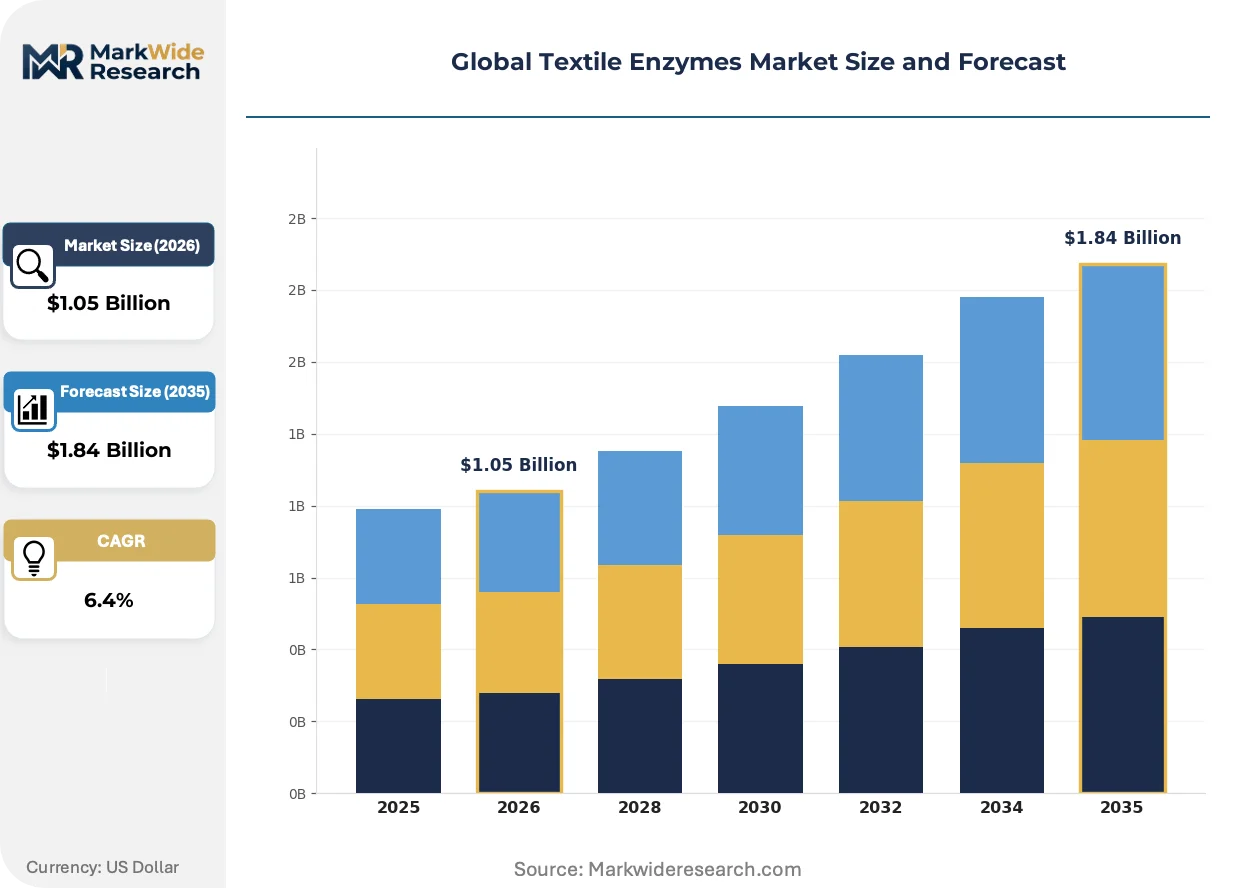
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Cellulase, Protease, Pectinase, Lipase, Catalase Application: Bio-polishing, Desizing, Scouring, Bleaching, Softening, Washing Fabric Type: Cotton, Wool, Silk, Nylon, Polyester, Blended Fabrics End User: Textile Manufacturers, Dyeing Units, Garment Producers, Technical Textile Producers, Exporters |
| Companies Covered | BASF, Kerry Group, Novozymes, Advanced Enzyme Technologies, Kemin Industries, Novonesis, Sunson, BESTZYME BIO-ENGINEERING CO., LTD., AB Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Enzymes Market Shifts & Advancements
Multi-enzyme synergistic formulations are displacing single-biocatalyst processes in pre-treatment lines, while regulatory pressure on chemical oxygen demand accelerates fermentation-derived alternatives across major textile producing clusters.
Low-temperature cellulase variants operating at 40-50°C are supplanting conventional 60°C processes in energy-conscious finishing lines. European denim laundries in Italy and Spain are adopting these concentrates to meet dual carbon reduction commitments. This temperature threshold compression is enabling heat-recovery system retrofits that were previously uneconomical.
EPA effluent guidelines in the United States are restricting chemical oxygen load discharge from textile wet processing facilities. Finishers in North Carolina and California are responding by substituting enzymatic desizing and bio-polishing for caustic and oxidative treatments. The biological oxygen demand differential is reshaping procurement specifications at regional dye houses serving domestic apparel brands.
Buyer concentration among vertically integrated garment exporters is compressing supplier qualification cycles. Large South Asian dyeing units in Bangladesh and Pakistan are consolidating enzyme procurement through direct fermentation partnerships rather than distributor networks. This channel consolidation is most visible in denim processing clusters where volume commitments justify dedicated technical service agreements.
Global Textile Enzymes Market Segmentation
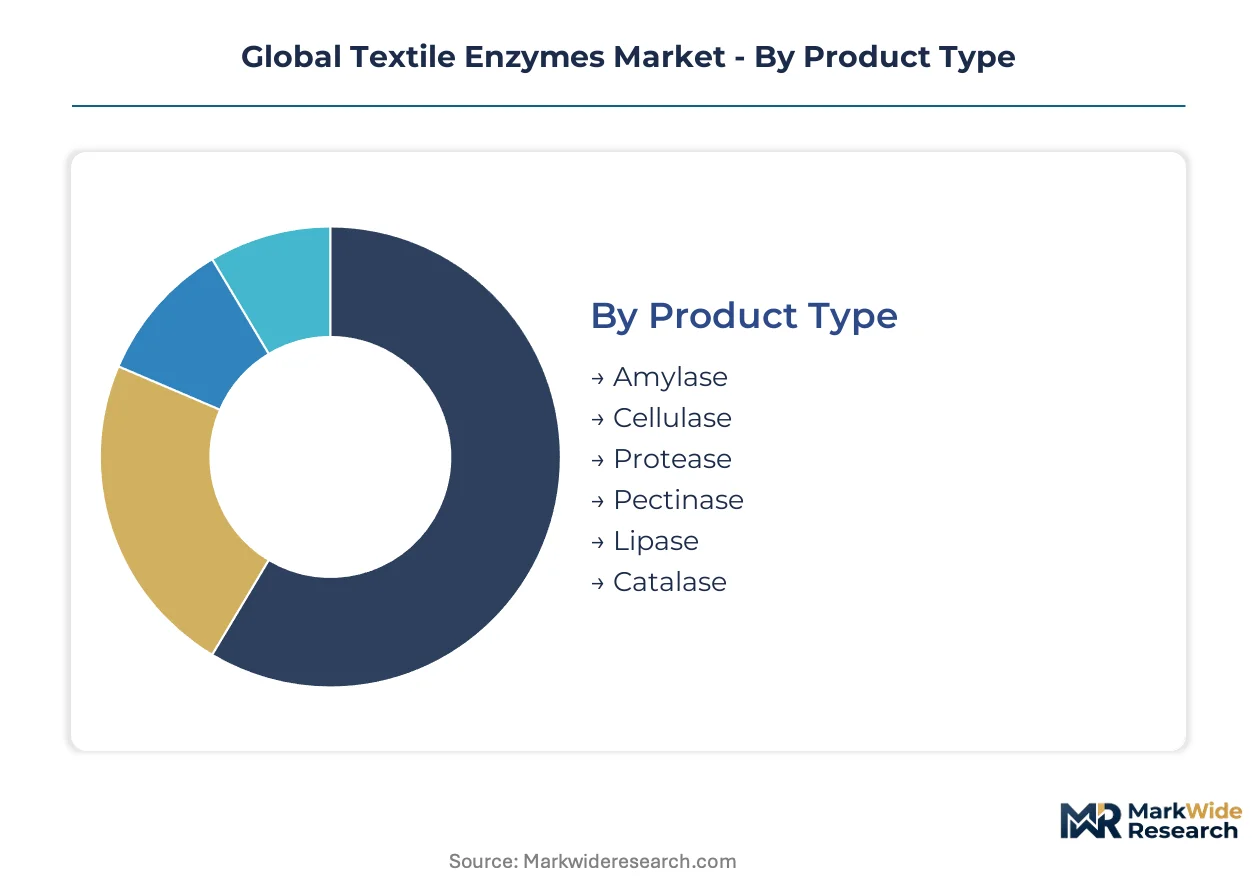
Enzyme procurement patterns diverge sharply across textile processing stages, with margin concentration shifting toward bio-polishing applications and high-activity cellulase formulations. Understanding how product specifications map to fabric types and end-user technical requirements illuminates where suppliers can capture premium positioning versus commodity volume plays.
Product Type:
Margin pools concentrate in cellulase concentrates and amylase blends where fermentation scale and activity purity create defendable differentiation.
- Cellulase:High-activity concentrates catalyze cotton fiber surface modification and denim abrasion programs. Demand clusters at Bangladeshi and Turkish denim laundries facing EU Green Deal discharge deadlines, with premium pricing tied to temperature reduction capabilities.
- Amylase:Thermostable variants hydrolyze starch-based warp sizes without oxidative fiber damage. South Asian desizing mills in Tamil Nadu and Gujarat are converting from chemical processes as CEA water consumption mandates tighten, driving volume expansion.
- Protease:Protein-specific hydrolysis for wool and silk processing, deployed at European specialty fiber finishers.
- Pectinase:Natural fiber scouring applications in Mediterranean cotton processing hubs, constrained by temperature ceilings above 60°C.
- Lipase:Grease removal in raw wool scouring, niche positioning in Australian and New Zealand fiber preparation.
- Catalase:Residual peroxide decomposition in bleaching sequences, standard inclusion in integrated dyehouse chemical programs.
The dominant share belongs to Cellulase, while Amylase is closing the gap fastest.
Application:
Cost tier stratification separates premium bio-polishing contracts from commodity desizing volume plays.
- Bio-polishing:Surface fiber removal from cotton knits creates pilling-resistant fabrics commanding brand premiums. Fashion label restricted substance lists are rotating pharma-grade purity specifications into procurement tenders at Italian and Spanish finishing houses.
- Desizing:Starch size removal from woven warps preserves cotton fiber strength versus oxidative alternatives. Bangladeshi integrated dyeing units are consolidating enzymatic procurement through direct fermentation partnerships rather than distributor channels.
- Scouring:Pectin and impurity removal from raw cotton, with low-BOD enzymatic alternatives displacing caustic soda in Zhejiang and Jiangsu province facilities under MEE discharge upgrades.
- Bleaching:Peroxide stabilization and decomposition sequences, increasingly bundled with catalase in chemical supply contracts.
- Softening:Secondary finishing application for cellulosic fiber surface modification, lower specificity requirements compressing margins.
- Washing:Garment processing stage for denim abrasion and finish effects, labor-intensive operations in Pakistani and Egyptian export facilities.
Bio-polishing commands the premium pricing tier, with Desizing generating the highest absolute volume throughput.
Fabric Type:
Application complexity varies with natural fiber processing demanding higher enzyme specificity than synthetic substrates.
- Cotton:Dominant cellulosic substrate requiring cellulase bio-polishing, amylase desizing, and pectinase scouring in sequence. Bangladeshi and Turkish processing clusters anchor global enzyme consumption for this fiber.
- Wool:Protein fiber processing employs protease and lipase combinations for grease removal and anti-felting treatments, concentrated in Australian and Chinese scouring facilities.
- Silk:Specialty degumming applications with sericin-specific protease formulations, limited to Italian and Indian luxury textile producers.
- Nylon:Synthetic fiber with minimal enzymatic processing relevance, occasional peroxide bleaching support.
- Polyester:Hydrophobic substrate largely bypassing enzymatic finishing, marginal catalase use in bleaching sequences.
- Blended Fabrics:Cotton-polyester combinations requiring adapted cellulase formulations to prevent synthetic fiber damage, growing specification complexity in South Asian knitwear exports.
Cotton retains the largest enzyme absorption by fabric type, while Blended Fabrics are expanding specification requirements most quickly.
End User:
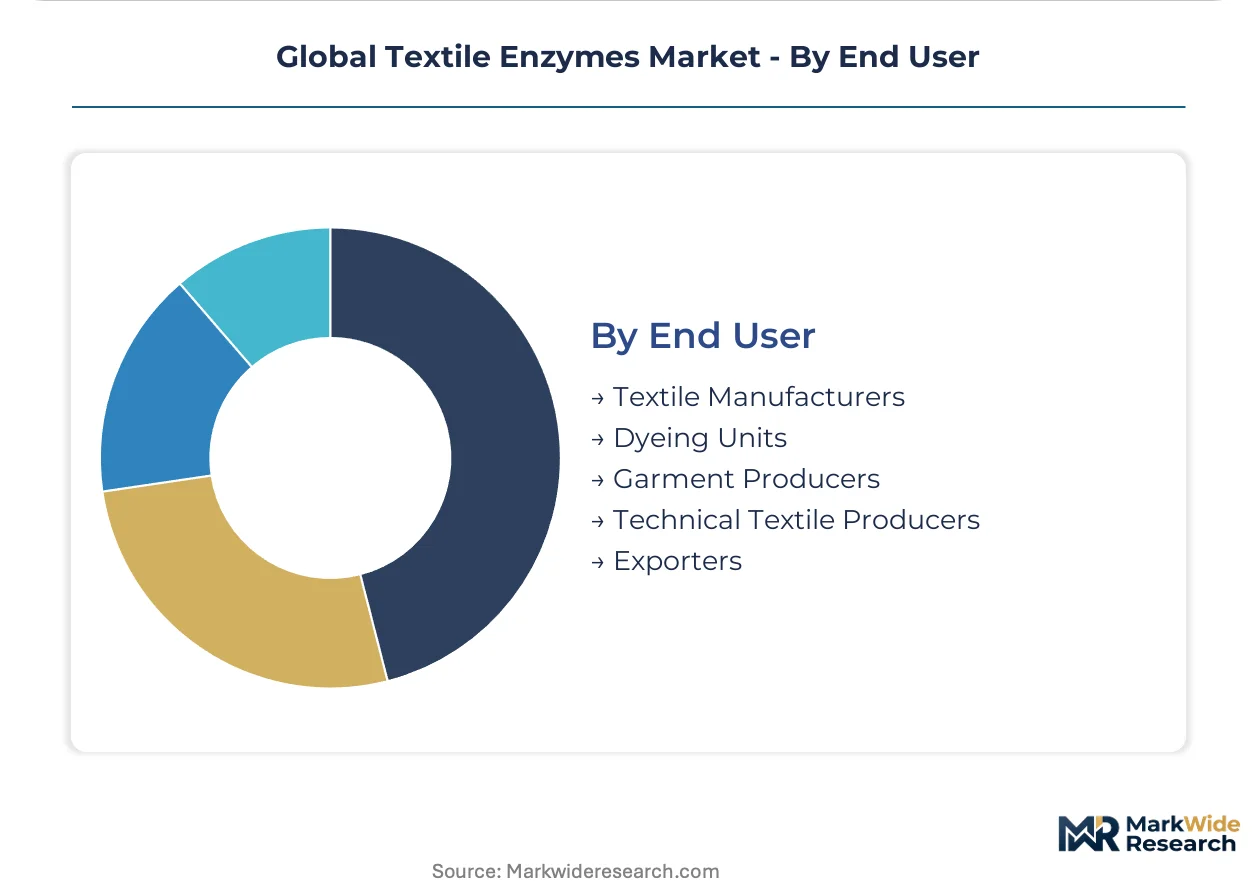
Customer scale and technical capability determine whether procurement flows through distributor networks or direct fermentation partnerships.
- Textile Manufacturers:Integrated spinning-weaving-dyeing operations with captive finishing capacity, consolidating enzyme supply through volume commitments and dedicated technical service agreements.
- Dyeing Units:Independent wet processing specialists in Bangladesh, Pakistan, and India, price-sensitive procurement shifting toward amylase-pectinase blend formulations for one-bath pre-treatment.
- Garment Producers:Denim laundries and wash houses in Chittagong and Istanbul, scaling bio-polishing investments ahead of regulatory deadlines to maintain EU export eligibility.
- Technical Textile Producers:Industrial fabric finishers with specialized performance requirements, smaller volume but higher specification stringency.
- Exporters:Vertically integrated garment exporters consolidating chemical procurement across supplier bases, compressing qualification cycles for enzyme vendors.
Textile Manufacturers consume the largest enzyme volumes, while Garment Producers are driving the steepest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented textile manufacturing clusters in Bangladesh, Turkey, and Vietnam are driving enzymatic process adoption to maintain EU and US market access under tightening chemical discharge rules. Import-dependent finishing chemical markets in Europe and North America are consolidating procurement around REACH-registered and EPA-compliant biocatalyst suppliers.
Bangladesh
Denim laundries in the Chittagong region are scaling bio-polishing capacity to preserve EU export eligibility under EU Green Deal chemical discharge mandates. The Bangladesh Department of Environment enforces effluent standards aligned with European buyer requirements. Integrated dyeing units in Gazipur and Narayanganj are converting from caustic scouring to enzymatic alternatives to reduce biological oxygen demand in wastewater.
Turkey
Denim processing facilities in Istanbul and Bursa are adopting high-activity cellulase concentrates to meet dual carbon reduction commitments under EU accession-aligned environmental frameworks. The Turkish Ministry of Environment, Urbanization and Climate Change implements wastewater discharge regulations that mirror REACH substance restrictions. Aegean region textile hubs in Denizli and Izmir are consolidating enzyme procurement through direct technical service agreements with fermentation specialists.
China
Textile finishers in Zhejiang and Jiangsu provinces are upgrading wastewater treatment infrastructure to comply with MEE discharge standards that restrict chemical oxygen load from wet processing. The Ministry of Ecology and Environment mandates biological oxygen demand reductions that favor enzymatic scouring over caustic soda. Shaoxing and Shengze dyeing clusters are converting desizing lines to amylase-based processes to meet provincial water consumption targets.
India
Warp sizing mills in Tamil Nadu and Gujarat remain underpenetrated by enzymatic desizing, presenting conversion potential as CEA water consumption mandates tighten enforcement. The Central Electricity Authority regulates industrial water use in textile processing zones. Tiruppur and Surat dyeing clusters are piloting combined amylase-pectinase formulations for one-bath pre-treatment to reduce processing stages and effluent volume.
United States
Textile finishers in North Carolina and California are substituting enzymatic desizing and bio-polishing for caustic treatments to comply with EPA effluent guidelines restricting chemical oxygen load discharge. The Environmental Protection Agency enforces biological oxygen demand limits that reshape procurement specifications at regional dye houses. Los Angeles garment wash facilities and North Carolina technical textile producers are consolidating chemical supply contracts around low-BOD enzymatic alternatives.
Global Textile Enzymes Market Competitive Landscape
Listed leaders compete with private specialists across fermentation scale and geographic coverage dimensions. The supplier base concentrates around Northern European fermentation houses with industrial-scale capacity, while Asian specialists compete on cost-optimized production for regional desizing markets. Three archetypes dominate: pharma-grade purity suppliers serving restricted substance list requirements, high-activity concentrate producers enabling temperature reduction claims, and regional blend formulators optimizing for local water chemistry. Competitive moves center on direct technical service partnerships with large dyeing units and fermentation capacity expansion to secure volume commitments.
Among the named players, Novozymes occupies a position exemplifying the pharma-grade purity tier, while AB Enzymes represents specialized formulation capabilities. BESTZYME BIO-ENGINEERING CO., LTD. anchors the cost-optimized regional production archetype for Asian desizing operations. These three illustrate how competitive positioning stratifies across certification grade, performance specification, and geographic supply chain configuration rather than converging on a single dominant model.
| Leading Market Players |
|---|
| BASF |
| Kerry Group |
| Novozymes |
| Advanced Enzyme Technologies |
| Kemin Industries |
| Novonesis |
| Sunson |
| BESTZYME BIO-ENGINEERING CO., LTD. |
| AB Enzymes |
| Others |
Supply & Pricing Matrix
Fermentation scale economies in Denmark and Germany concentrate high-activity cellulase production among Northern European specialists, compressing price floors for pharma-grade purity tiers while elevating premiums for REACH-registered formulations. This capacity concentration forces Asian desizing mills toward cost-optimized regional suppliers, fragmenting procurement patterns across certification grades.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharma-grade purity certifications and REACH registration status as the primary differentiation drivers. Price erosion runs through the economy tier as BESTZYME BIO-ENGINEERING CO., LTD. and regional Chinese producers expand amylase capacity for South Asian desizing mills. Dyeing units in Bangladesh and Pakistan exhibit the highest price sensitivity, while Italian and Spanish denim laundries serving luxury brands accept premium positioning for bio-polishing concentrates with temperature reduction claims.
Supply Chain Analysis
Strait of Hormuz transit risks concentrate attention on Middle East feedstock flows for pharmaceutical-grade dextrose and yeast extract inputs. Industrial-scale fermentation capacity draws from Denmark, Germany, and the Netherlands, with corn futures volatility in the US Midwest feeding through to cellulase concentrate production costs. Single-source vulnerability persists for high-activity enzyme strains held by Northern European specialists. Distribution runs through direct technical service partnerships with large South Asian dyeing units, bypassing traditional distributor networks in volume-intensive denim processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal chemical discharge mandates are compressing adoption windows for enzymatic finishing, creating high-growth disruption as denim laundries face binary compliance deadlines. This regulatory inflection favors suppliers with pre-registered fermentation capacity and documented toxicological profiles.
For Market Incumbents: Consolidate fermentation capacity utilization through dedicated technical service agreements with Bangladeshi integrated dyeing units facing EU export eligibility deadlines. Expand backward integration into pharmaceutical-grade dextrose sourcing to buffer corn futures volatility squeezing cellulase margins. Lock in multi-year volume commitments from Chittagong denim laundries scaling bio-polishing investments ahead of regulatory enforcement. For New Entrants and Emerging Players: Anchor in Tamil Nadu and Gujarat warp sizing mills where CEA water consumption mandates are tightening enforcement against underpenetrated enzymatic desizing. Target combined amylase-pectinase blend formulations for one-bath pre-treatment wins at South Asian integrated dyeing units seeking processing stage reduction. Lead with cost-optimized production positioned below Northern European pharma-grade purity tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with REACH-registered strain libraries and established technical service infrastructures in Mediterranean garment hubs. Long-term viability hinges on regulatory compliance moats deepening as EU Green Deal chemical sustainability targets cascade through buyer specifications. Watch for MEE wastewater discharge standard enforcement in Zhejiang and Jiangsu provinces as the signal for Chinese enzymatic scouring conversion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Expansion | Pre-registered biocatalyst formulations capture preferential demand at EU-facing Mediterranean garment hubs. |
| Direct Technical Service Partnerships | Volume commitments from Bangladeshi denim laundries justify dedicated fermentation capacity allocation. |
| Low-Temperature Cellulase R&D | 40-50°C variants enable carbon reduction claims at Italian and Spanish energy-conscious finishing lines. |
| Combined Enzyme Blend Development | Amylase-pectinase formulations win specification at South Asian integrated dyeing units. |
| Pharma-Grade Purity Certification | ISO validation cycles open restricted substance list procurement at luxury brand suppliers. |
Research Methodology
Operator-level perspectives from fermentation plant managers, procurement leads at Bangladeshi dyeing units, technical directors at European denim laundries, and regulatory affairs specialists at enzyme suppliers anchored the qualitative base. Primary interviews triangulated with secondary validation from REACH registration databases, EPA effluent guideline filings, EU Green Deal implementation documents, and Central Electricity Authority water consumption notifications. Customs data on fermentation equipment imports and SEC disclosures from listed suppliers provided volume calibration. Bottom-up segment sizing across cellulase, amylase, and pectinase product lines reconciled with top-down market value estimates.
Sensitivity analysis tested forecast robustness against corn futures volatility, MEE enforcement timing in Chinese provinces, and CEA mandate tightening in Indian textile zones. The analytical framework modeled enzyme demand across the projection horizon by product type, application stage, fabric substrate, and end-user scale tier. CAGR derivation incorporated fermentation capacity expansion timelines, regulatory deadline phasing, and conversion rates from chemical to enzymatic processes in underpenetrated desizing and scouring lines. Input assumptions included EU Green Deal implementation pace and buyer consolidation trends among vertically integrated garment exporters.
Material uncertainties — fermentation input cost spikes, regulatory enforcement delays, and substitution by alternative fiber processing technologies — sit outside the modeled envelope. Forecasts reflect documented assumptions about REACH registration compliance rates and bio-polishing adoption curves. Practitioners should keep alternative scenarios live as China's MEE wastewater discharge standards and India's CEA water consumption mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market