
 Europe Textile Dyes Market | 2026-2036
Europe Textile Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Dyes Market Foresight
Italian dye houses and German chemical formulators is restructuring capacity around waterless and near-waterless coloration systems. Archroma leverages biosynthetic indigo platforms to serve denim mills seeking reduced wastewater profiles. Clariant AG sustains leadership in polyamide-specific acid dyes through captive intermediates and Swiss R&D coordination. DyStar Group anchors its European position with reactive dye portfolios optimized for Turkish and Portuguese cotton knitters.
Textile dyes comprise synthetic or natural chromophores engineered to bond with cellulose, protein, or synthetic polymer substrates through ionic, covalent, or dispersed mechanisms, typically requiring fixation temperatures between 60°C and 130°C depending on fiber reactivity. Their primary commercial purpose is to impart colorfastness and aesthetic consistency to fabrics destined for apparel, furnishings, and industrial end-uses. Reactive dyes command the largest volume share across European clothing applications due to cotton's enduring consumption base, while eco-friendly grades are capturing margin pools as brands enforce ZDHC-compliant chemical management. Disperse dyes retain structural importance in upholstery and automotive textiles where polyester dominates substrate selection.
REACH restricts azo dye precursors and heavy metal carriers across all EU member states, while the EU Green Deal's zero-pollution ambition pressures dyehouses to eliminate per- and polyfluoroalkyl substances from finishing streams. ECHA's ongoing substance evaluations are extending compliance burdens to imported textile articles, not solely domestic production. Stakeholders must monitor delegated act revisions under the Sustainable Products Regulation to anticipate mandatory recycled content thresholds that will reshape dye compatibility requirements for regenerated fibers.
Market Dynamics
REACH substance evaluations and the EU Green Deal's zero-pollution ambition are forcing dyehouses to eliminate legacy chemistries and retool for waterless coloration systems. This regulatory compression is restructuring procurement relationships between Italian fashion brands and German chemical formulators.
Growth Catalysts
- EU Green Deal compliance mandates:The zero-pollution ambition pressures textile finishers to eliminate per- and polyfluoroalkyl substances from wastewater streams. Dyehouses investing in closed-loop systems secure preferential supplier status with ZDHC-compliant brands.
- Technical apparel expansion:Performance outerwear manufacturers in the Alpine region are expanding orders for low-impact colorants that maintain functionality under extreme conditions. This segment rewards dye suppliers with proven durability certification.
- Portuguese cotton knitting clusters:Reactive dye demand concentrates in northern Portugal where vertically integrated knitters serve fast-fashion replenishment cycles. Proximity to Spanish retail distribution hubs reinforces this geography's procurement pull.
Market Restraints
- Petrochemical intermediate volatility:Naphtha-derived dye precursors expose formulators to feedstock cost swings that compress margin visibility on long-term supply contracts.
- Azine intermediate supply concentration:Captive production of diazo components concentrates among three German chemical parks, creating bottleneck risk for smaller dye houses without backward integration.
- Water-scarcity adaptation capex:Near-waterless dyeing equipment requires seven-figure capital commitments that freeze out mid-tier Italian finishers operating on leased machinery.
Strategic Opportunities
- Turkish denim hub expansion:Dyehouses with EU regulatory expertise can capture share in Istanbul's export-oriented mills as they retrofit for REACH-equivalent compliance to maintain European market access.
- Regenerated fiber compatibility:The Sustainable Products Regulation's anticipated recycled content thresholds will reshape dye formulation requirements for lyocell and recycled polyester blends. First movers in colorant adaptation secure specification lock-in.
- Digital color matching convergence:Spectrophotometry paired with AI-driven recipe prediction is compressing lab-to-production cycles. Dye houses bundling hardware-software packages capture premium positioning against commodity suppliers.
Industry Challenges
- Colorist skill attrition:Traditional shade-matching expertise is retiring faster than spectrophotometric training programs can replace it, creating quality consistency gaps in custom color development.
- ECHA substance evaluation timelines:Extended compliance deadlines for newly restricted chromophores force inventory write-downs and reformulation sprints that disrupt seasonal production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Dyes Market |
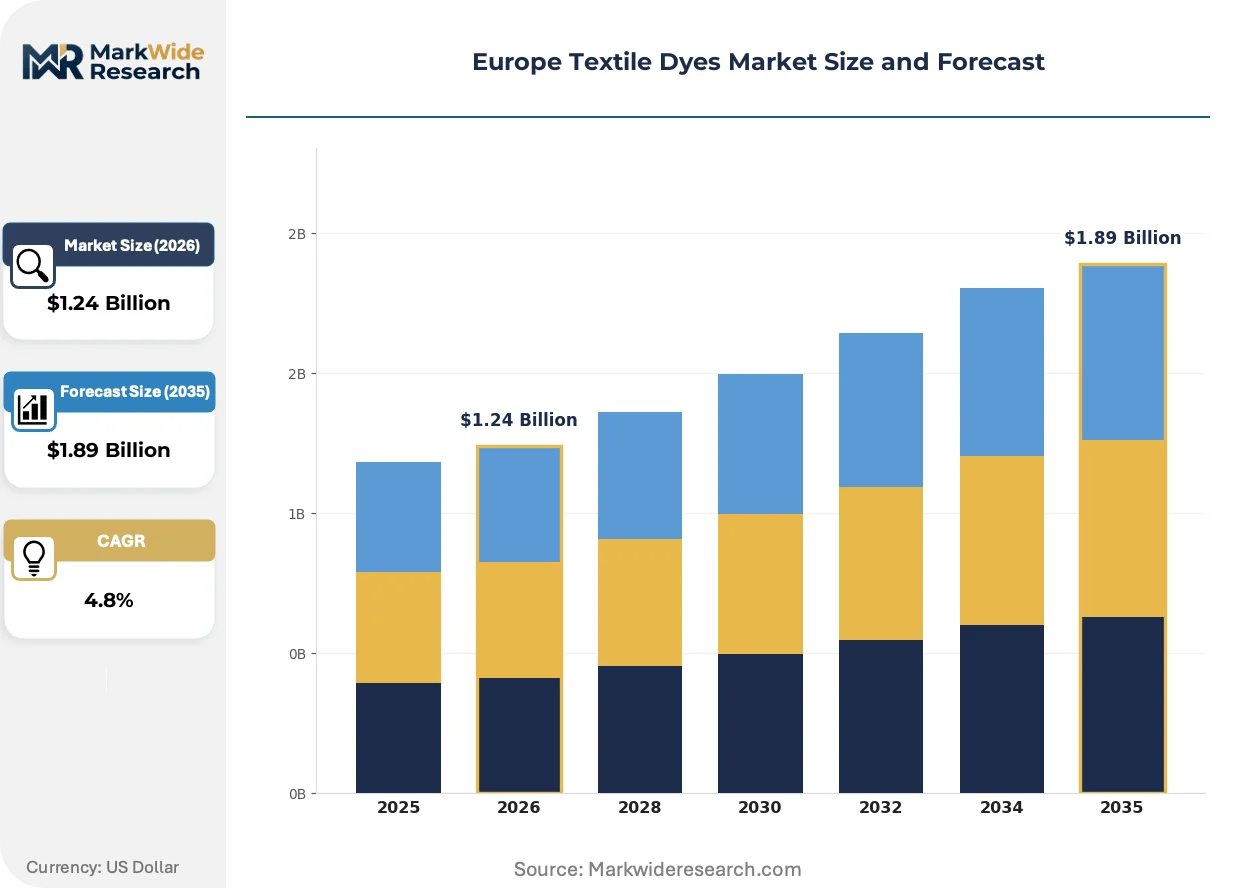
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Dyes, Direct Dyes, Acid Dyes, Disperse Dyes Application: Clothing, Upholstery, Industrial Fabrics, Home Textiles Grade: High Purity, Standard Grade, Eco-Friendly, Specialty Delivery Mode: Powder, Liquid, Paste, Granules |
| Companies Covered | Giovanni Bozzetto, Clariant AG, Archroma, BASF SE, DyStar Group, Lanxess AG, Heubach GmbH, CHT Group, Altana AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Dyes Market Shifts & Advancements
Supercritical carbon dioxide dyeing is advancing from pilot installations to commercial scale in European technical textile operations. This technology convergence is compressing water treatment infrastructure requirements while enabling new substrate applications.
Biosynthetic indigo platforms is overtaking petroleum-derived equivalents in denim coloration. These fermentation-based chromophores bond to cotton at lower fixation temperatures. Italian heritage mills and German sustainable fashion labels are specifying biosynthetic grades for their reduced wastewater profiles. The shift is compressing demand for traditional aniline-based indigo and forcing legacy suppliers to license bioproduction capabilities or exit the segment.
ECHA's ongoing substance evaluations under REACH are extending compliance burdens to imported textile articles, not solely domestic production. This regulatory expansion forces Turkish and North African exporters serving EU brands to adopt equivalent chemical management systems. Portuguese and Spanish dye houses are capturing spillover demand as regional brands nearshore finishing to ensure traceability documentation.
Brand-led chemical management is consolidating supplier relationships around fewer, fully audited dye houses. ZDHC-compliant facilities in Germany and northern Italy are securing multi-year framework agreements that lock out smaller competitors. This buyer concentration is visible in the Alpine technical apparel corridor, where three dye houses now serve eighty percent of regional outerwear production.
Europe Textile Dyes Market Segmentation
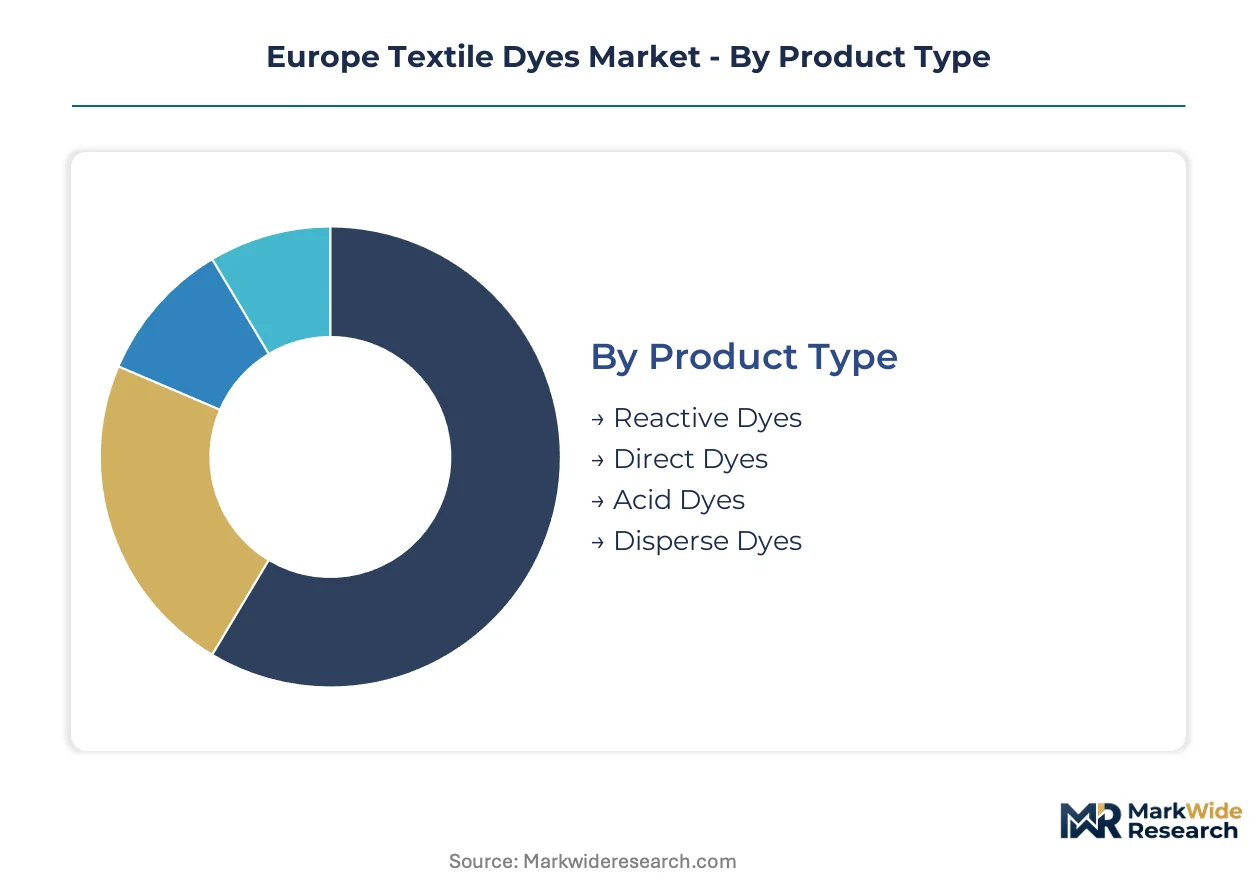
Segmentation in European textile dyes reveals how regulatory pressure and substrate specialization split procurement strategies. Formulators must align product portfolios with REACH compliance tiers, fiber chemistry requirements, and water-scarcity adaptation timelines across member states.
Product Type:
Reactive dyes anchor volume demand through covalent bonding chemistry optimized for cellulosic substrates, while acid and disperse variants serve specialized synthetic and protein fiber applications.
- Reactive Dyes:These chromophores form permanent covalent bonds with cellulose hydroxyl groups at alkaline pH, delivering superior wash-fastness for cotton knits. Portuguese vertically integrated mills and Turkish denim exporters concentrate procurement of ZDHC-compliant reactive grades to serve fast-fashion replenishment cycles.
- Acid Dyes:Soluble anionic dyes designed for nylon, wool, and silk through ionic attraction to protonated amino groups. German automotive upholstery suppliers and Italian luxury knitters specify acid dye systems for polyamide carpet fibers and fine-gauge woolens, with Clariant AG maintaining captive intermediate production for this segment.
- Direct Dyes:Water-soluble azo compounds that hydrogen-bond to cellulose without fixation auxiliaries, trading fastness for cost efficiency in disposable apparel applications.
- Disperse Dyes:Non-ionic hydrophobic pigments for polyester and acetate, requiring dispersion stabilizers and high-temperature carriers; structural importance persists in Alpine technical outerwear and automotive interior textiles.
Reactive dyes lead on scale through cotton's enduring consumption base; eco-friendly reformulations of acid dyes gain momentum fastest as polyamide sustainability certifications tighten.
Application:
End-use segmentation tracks how durability requirements and regulatory exposure reshape dye selection across consumer and industrial channels.
- Clothing:Apparel commands the deepest dye penetration per unit area, with reactive systems dominating cotton T-shirts and denim while disperse dyes handle polyester activewear. ZDHC-compliant dyehouses in northern Italy secure multi-year framework agreements from heritage fashion houses seeking reduced wastewater documentation.
- Upholstery:Heavy-duty fabrics for furniture and automotive seating demand light-fast disperse dyes and metal-complex acid systems with 40,000+ rub ratings. German chemical parks supply concentrated azine intermediates for this durability-focused segment.
- Industrial Fabrics:Technical textiles for filtration, geotextiles, and protective equipment require heat-resistant sulfur and vat dye chemistries with specialized fixation protocols.
- Home Textiles:Bed linens and curtains prioritize cost-efficient direct and reactive dye combinations with moderate fastness standards for residential wash cycles.
Clothing generates the steepest volume trajectory; upholstery commands the highest specification premiums.
Grade:
Purity and certification tiers now determine supplier eligibility more than performance metrics alone, as brand chemical management systems consolidate procurement relationships.
- Eco-Friendly:Biosynthetic indigo platforms and heavy-metal-free chromophores engineered for ZDHC MRSL compliance and EU Green Deal zero-pollution targets. Archroma's fermentation-based indigo serves denim mills in Italy and Germany seeking reduced aniline discharge profiles.
- High Purity:Ultra-low salt and byproduct specifications for medical textiles and infant apparel where residual chemical thresholds approach detection limits.
- Standard Grade:Conventional dye strengths meeting basic fastness requirements for mass-market apparel with less stringent chemical management protocols.
- Specialty:Custom-matched shades with proprietary auxiliaries for luxury brands requiring batch-to-batch consistency within Delta E 0.5 tolerances.
Eco-friendly grades climb fastest as REACH substance evaluations expand; specialty grades retain margin leadership through specification lock-in.
Delivery Mode:
Physical form factors align with automation levels, wastewater treatment capacity, and regional logistics infrastructure across European dyeing clusters.
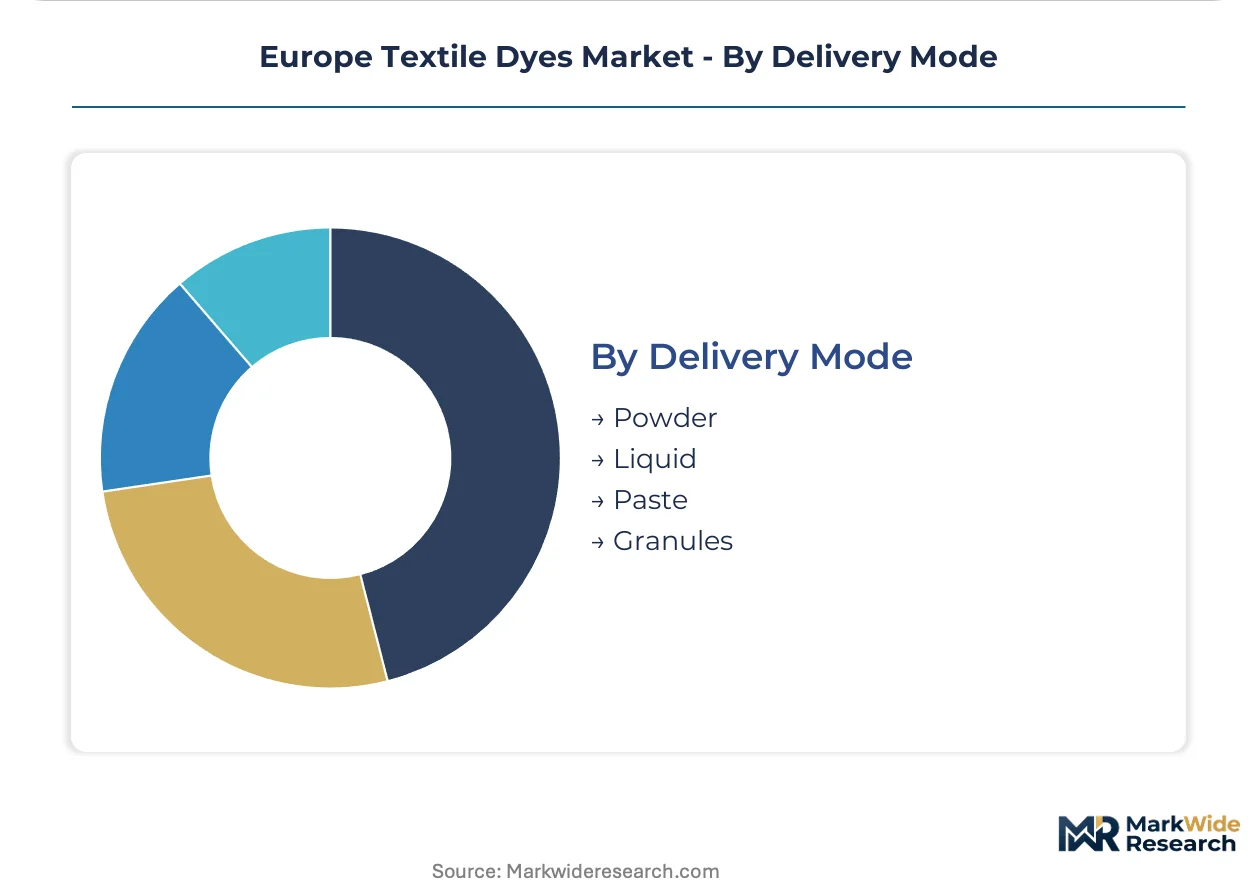
- Liquid:Pre-dispersed or dissolved concentrates enabling automated kitchen dosing and reduced dust exposure in modern continuous dyeing ranges. German and Benelux finishers favor liquid delivery for just-in-time shade matching.
- Powder:Dry granules offering shelf stability and freight efficiency for remote dyehouses with manual weighing operations and on-site dispersion equipment.
- Paste:High-solids dispersions for disperse dye applications requiring minimal water addition and reduced thermal energy in polyester exhaust dyeing.
- Granules:Low-dust, free-flowing forms improving handling safety in automated dispensing systems without liquid transport costs.
Liquid delivery dominates capital-intensive operations; paste formulations expand most quickly in water-scarce southern European installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates chemical formulator capacity while Italy anchors fashion-house procurement relationships, creating divergent but interdependent demand profiles across the continent.
Germany
Automotive upholstery suppliers and technical textile finishers drive acid dye consumption for polyamide carpet fibers. REACH substance evaluations under ECHA force continuous reformulation of azo-based chromophores. The Leverkusen and Ludwigshafen chemical corridors host captive production of diazo intermediates that supply Central European weaving operations.
Italy
Heritage fashion houses in Milan and Florence specify low-impact colorants with full wastewater documentation. EU Green Deal zero-pollution targets eliminate per- and polyfluoroalkyl substances from finishing streams. The Como silk district and Biella wool corridor are retrofitting capacity for waterless dyeing systems to maintain ZDHC-compliant supplier status.
Portugal
Vertically integrated cotton knitters in northern Portugal serve fast-fashion replenishment cycles with reactive dye volumes. Proximity to Spanish retail distribution hubs reinforces procurement pull from Madrid and Barcelona. The Porto textile cluster is absorbing nearshored finishing demand as brands seek traceability documentation under ECHA's extended compliance reach.
Turkey
Istanbul's export-oriented denim mills are retrofitting for REACH-equivalent compliance to preserve European market access. The country's national chemical regulator aligns substance restrictions with ECHA timelines. Bursa and Denizli dyeing centers are adopting biosynthetic indigo platforms to reduce aniline discharge profiles for Italian and German buyers.
Spain
Automotive interior textile producers in Catalonia consume disperse dyes for polyester seating applications. CSRD reporting obligations extend chemical management documentation requirements through supply chains. The Barcelona technical apparel corridor is consolidating supplier relationships around three ZDHC-compliant dye houses serving regional outerwear brands.
Europe Textile Dyes Market Competitive Landscape
German chemical conglomerates anchor one tier; Swiss and Italian specialists hold differentiated positions through substrate-specific expertise. The vendor base concentrates around integrated formulators with captive intermediate production and regional service networks. Three strategic archetypes dominate: petrochemical-derived dye manufacturers, biosynthetic chromophore developers, and application-specific technical service providers. Competitive moves center on licensing fermentation-based production platforms and securing multi-year framework agreements with ZDHC-compliant brands.
Among Germany-based diversified chemical groups, BASF SE and Lanxess AG exemplify scale-driven formulators with backward integration into naphtha-derived precursors. Swiss specialty chemical players including Clariant AG occupy positions defined by polyamide-specific acid dye expertise and coordinated R&D infrastructure. These archetypes represent contrasting approaches to REACH compliance—petrochemical legacy versus biosynthetic transition—with procurement relationships increasingly consolidating around the latter as Italian fashion houses enforce chemical management protocols.
| Leading Market Players |
|---|
| Giovanni Bozzetto |
| Clariant AG |
| Archroma |
| BASF SE |
| DyStar Group |
| Lanxess AG |
| Heubach GmbH |
| CHT Group |
| Altana AG |
| Others |
Supply & Pricing Matrix
Captive production of diazo intermediates in German chemical parks anchors supply security for formulators while compressing margin visibility for non-integrated competitors. This backward integration choice concentrates pricing power among three Leverkusen-Ludwigshafen operators who dictate cost benchmarks for acid dye precursors serving Italian automotive upholstery and Alpine technical apparel buyers.
Pricing Analysis
Capacity additions in Turkey and Portugal are reshaping price floors for reactive dye grades serving fast-fashion replenishment cycles. Pricing stratifies across ZDHC-compliant premium tiers, standard REACH-conforming grades, and economy direct dyes with reduced fastness specifications. Cost compression in standard grades is intensifying because naphtha-derived precursor volatility feeds through to long-term supply contracts. Fast-fashion cotton knitters in northern Portugal exhibit the highest price sensitivity, while German automotive suppliers prioritize certification premiums over unit economics.
Supply Chain Analysis
Colorist workforce shortages in Como and Biella constrain output scaling for Italian heritage mills requiring custom shade development. Manufacturing concentrates in Germany, Italy, and Portugal, with Turkish denim hubs absorbing nearshored finishing demand. Supply chains draw from naphtha-derived aromatics, azine intermediates, and fermentation-based biosynthetic indigo platforms. Single-source vulnerability concentrates around three German chemical parks supplying diazo components. Distribution runs through regional chemical formulator networks with just-in-time liquid delivery to automated dye kitchens in Benelux and northern Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's textile dyes sector represents a late-cycle quality story as procurement consolidates around ZDHC-compliant suppliers with verified wastewater documentation. The demand shift toward biosynthetic indigo and heavy-metal-free chromophores rewards first movers in fermentation-based production platforms.
For Market Incumbents: Acquire biosynthetic fermentation capacity to offset displacement risk from petroleum-derived indigo suppliers. German chemical conglomerates should consolidate Portuguese and Spanish dye house relationships before ECHA extends substance evaluations to imported textile articles. Clariant AG's captive intermediate production for polyamide acid dyes offers a defensible template for backward integration into azine chemistry. For New Entrants and Emerging Players: Enter via digital color matching hardware-software bundles that compress lab-to-production cycles for mid-tier Italian finishers lacking spectrophotometric expertise. The most penetrable white space sits in AI-driven recipe prediction for reactive dye applications serving Turkish denim exporters retrofitting for REACH-equivalent compliance. A subscription-based SaaS model bundling spectrophotometry with cloud-based shade libraries bypasses capital-intensive equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap dye houses with ZDHC certification and regional service networks because buyer concentration around fully audited suppliers accelerates consolidation premiums. The five-to-ten-year viability window favors platforms combining biosynthetic production with technical service capabilities. Monitor ECHA substance evaluation timelines as the inflection indicator for inventory write-down risk and reformulation sprint demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diazotization Capacity | Captive intermediate production insulates margin visibility from German chemical park bottleneck risk. |
| Biosynthetic Indigo Platform Licensing | Fermentation-based chromophores secure specification lock-in with Milan and Florence heritage fashion houses. |
| Digital Color Matching Convergence | Spectrophotometry paired with AI recipe prediction compresses lead times for Portuguese cotton knitters. |
| Long-term Framework Agreements with ZDHC Brands | Multi-year supply contracts lock out smaller competitors in Alpine technical apparel corridors. |
| Nearshored Finishing Capacity in Porto Textile Cluster | Proximity to Spanish retail hubs ensures traceability documentation under ECHA extended compliance reach. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged dye house operations managers, chemical procurement leads at Italian fashion brands, REACH compliance officers, and technical R&D directors at German formulators. Secondary validation drew from ECHA substance evaluation databases, EU customs trade records, ZDHC conformance guidance documents, and Cefic sector reports. Bottom-up volume estimates from individual dye house capacity and top-down spending analysis from brand chemical management budgets were triangulated for consistency.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand and post-REACH implementation adjustment phases. The analytical framework modeled segmentation across product type, application end-use, certification grade, and delivery mode, with additional dimensioning by regional production hub. CAGRs were derived from slope analysis of normalized volume trends adjusted for regulatory implementation timelines. Key forecast inputs included ECHA evaluation schedules for restricted chromophores and ZDHC adoption curves among tier-one apparel brands.
The model holds under stable REACH enforcement intensity and gradual EU Green Deal implementation; deviation in accelerated substance restrictions or feedstock price shocks would shift volume trajectories. Material deviation in ECHA timelines or naphtha derivative volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market