
 Lining Fabric Market | 2026-2036
Lining Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Lining Fabric Market Analytics
Buyer concentration among multinational apparel houses is recalibrating procurement volumes for lining fabrics. Toray Industries leverages its polyester filament expertise to anchor supply relationships with performancewear labels across Asia. Freudenberg competes through specialized nonwoven interlining technologies that integrate thermal bonding with breathability control. Edmund Bell sustains its position in European formalwear through deep inventory of cupro and viscose lining grades.
Lining fabric denotes a secondary textile layer sewn into garments, footwear, and upholstered goods to provide structure, comfort, and finished aesthetics, typically ranging from 60 to 120 grams per square meter in weight depending on end-use requirements. Cotton linings dominate formalwear applications where moisture absorption and skin contact comfort remain critical, while polyester linings lead in casual and sportswear segments due to dimensional stability and lower unit cost. Nylon linings occupy the premium technical niche for cold-weather outerwear where abrasion resistance and down-proof construction justify material premiums.
REACH in Europe, OEKO-TEX Standard 100, and China's GB national standards collectively govern chemical residue limits, fiber traceability, and labeling accuracy across the lining fabric value chain. These frameworks elevate compliance costs for smaller mills while creating certification barriers that favor vertically integrated producers with in-house testing laboratories. Stakeholders must monitor evolving restricted substance lists and regional enforcement intensity to anticipate which material categories will face accelerated substitution pressure.
Market Dynamics
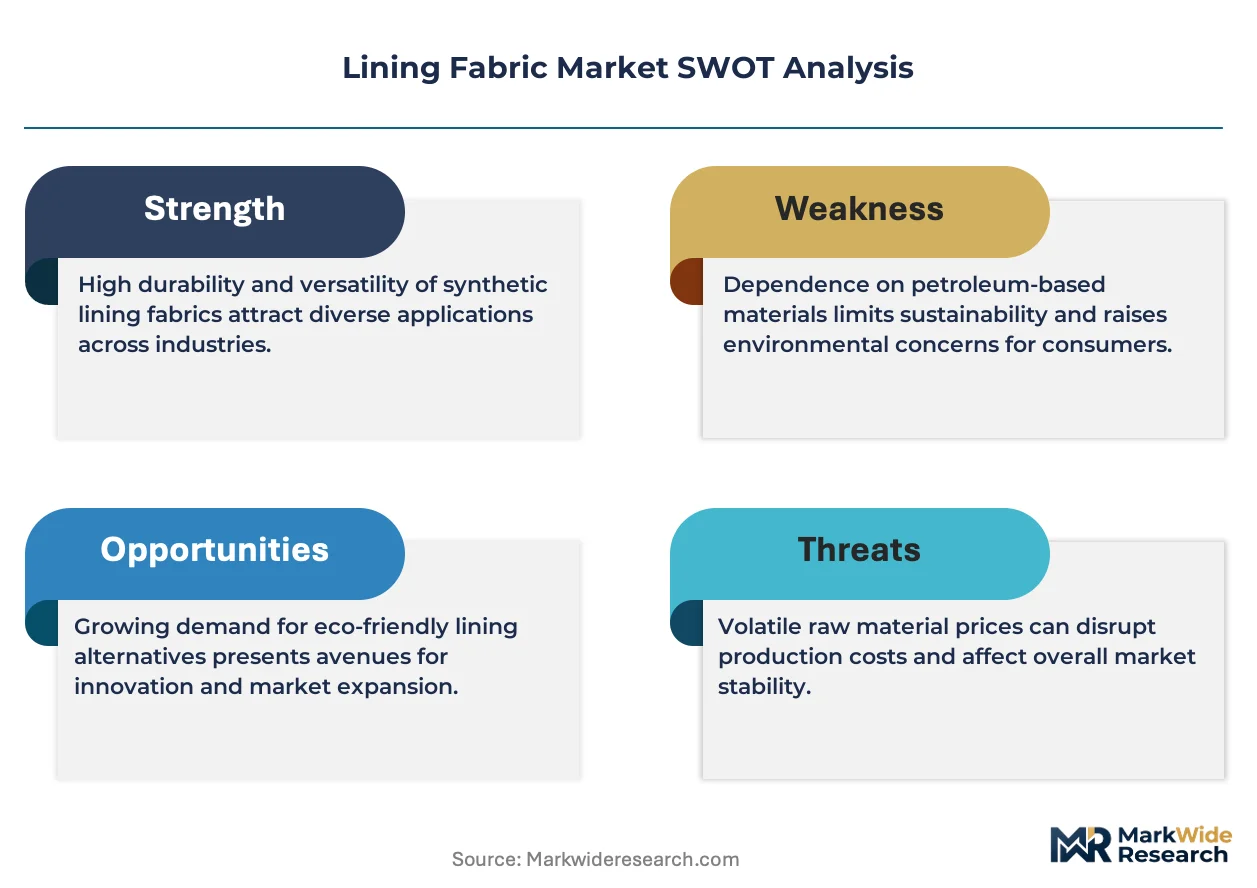
REACH compliance in Europe and China's GB standards are compressing supplier margins while concentrating procurement among vertically integrated mills with captive testing laboratories. This regulatory tightening is reshaping competitive positioning by elevating certification costs for smaller producers.
Growth Catalysts
- Performance outerwear expansion:Apparel manufacturers are expanding lining specifications for technical garments requiring moisture management and thermal regulation. Polyester filament technologies enable multi-layer constructions that meet these functional demands.
- Domestic fashion brand upgrading:Chinese fashion houses are investing in premium garment interiors, driving cupro and viscose lining demand for mid-market collections. This elevates material specifications across domestic supply chains.
- OEKO-TEX Standard 100 certification:European retailers are mandating certified chemical-free substrates, creating procurement pull for compliant mills. Certification is becoming a non-negotiable entry ticket for Western brand supply lists.
Market Restraints
- Petrochemical input volatility:Polyester and nylon filament prices track crude oil derivatives, compressing margin predictability for converters. Mills lack pricing power to pass through raw material swings.
- Supplier concentration in East Asia:Filament yarn production clusters in coastal China and South Korea, creating geographic risk exposure for European and North American converters. Single-source dependencies amplify disruption vulnerability.
- Natural fiber substitution ceiling:Cotton linings face acreage constraints and water intensity that limit scale expansion. Premium cupro supply depends on cotton linter byproduct availability.
Strategic Opportunities
- India technical textile penetration:The PLI scheme is incentivizing domestic lining production for export-oriented garment units. Mills can capture share in a market historically dependent on Chinese imports.
- Bio-based polymer development:Polylactic acid and bio-polyester filaments are approaching performance parity for casualwear applications. Early movers can establish specification relationships before scale economics mature.
- Direct-to-brand digital sampling:Virtual prototyping and AI-assisted color matching are compressing development cycles. Mills can bypass traditional agent networks and capture margin from shortened lead times.
Industry Challenges
- Colorimetric specialist scarcity:Precise shade matching for luxury brand palettes requires experienced technicians. Training pipelines have atrophied as automation displaced manual dye house roles.
- Multi-certification compliance burden:Simultaneous OEKO-TEX, REACH, and GB standard adherence requires redundant testing protocols. Smaller mills face six-month certification timelines that freeze new customer acquisition.
- Legacy ERP integration friction:Traceability mandates require blockchain or cloud-based chain-of-custody systems. Brownfield facilities struggle to retrofit digital infrastructure without production disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lining Fabric Market |
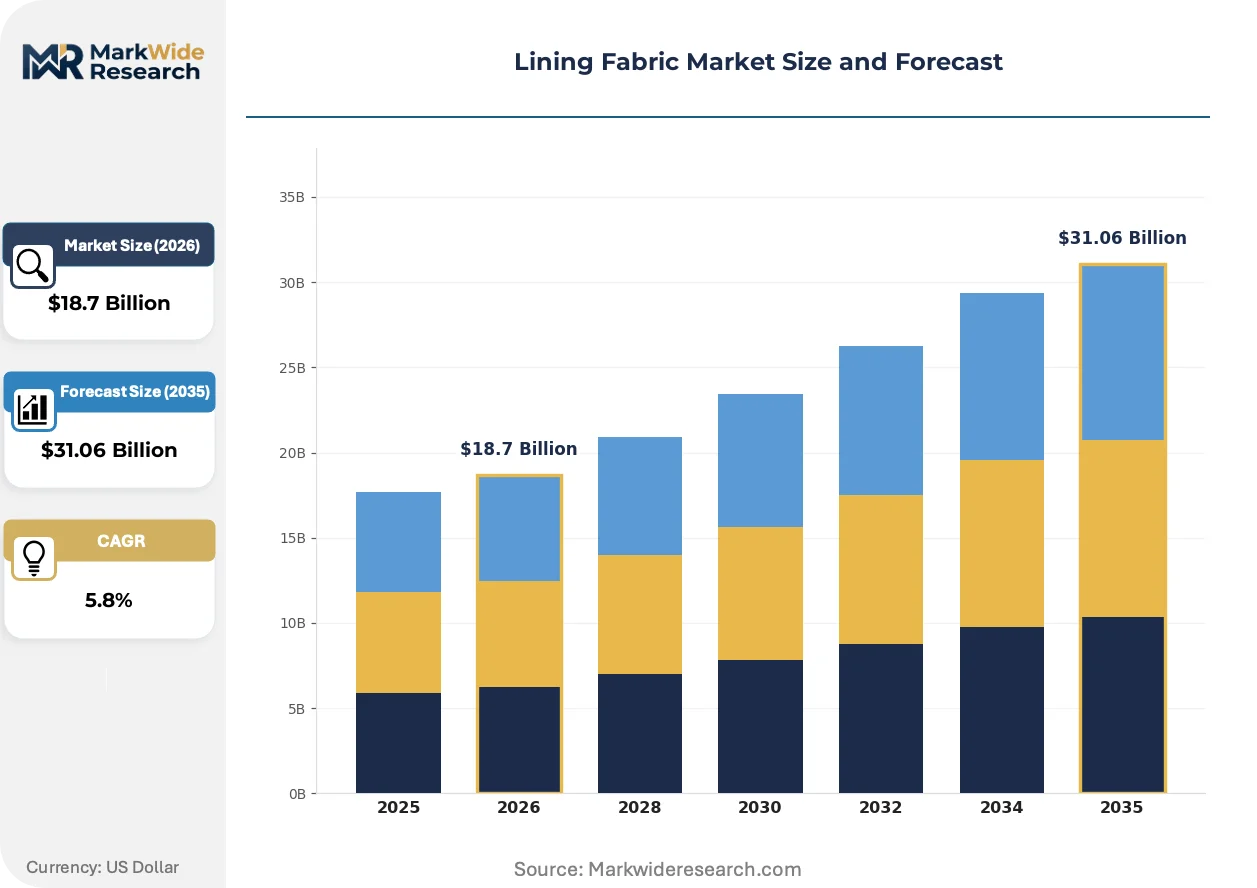
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cotton, Polyester, Silk, Nylon End Use: Apparel, Upholstery, Accessories, Home Textiles Application: Cold Weather, Casual Wear, Formal Wear, Sportswear Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Toray Industries, Asahi Kasei, BASF SE, Freudenberg, Chargeur, Zhejiang Huafon Group, Sankei, Edmund Bell, QST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lining Fabric Market Evolving Landscape
Digital traceability systems and bio-based material platforms are converging to reshape how lining fabric specifications are verified and sourced. These shifts are compressing traditional quality assurance timelines while elevating transparency requirements.
Recycled polyester filament produced through chemical depolymerization is overtaking mechanically recycled alternatives in premium outerwear applications. European performancewear labels are specifying chemically recycled content for down-proof linings where fiber integrity is critical. This technology is enabling closed-loop claims that command material premiums from sustainability-focused buyers.
ECHA's expanding SVHC candidate list is forcing reformulation of dye carriers and finishing agents used in viscose lining production. Mills serving EU markets are substituting formaldehyde-free crosslinkers and heavy metal-free pigments to maintain market access. The formalwear segment faces accelerated substitution pressure as restricted substance thresholds tighten.
Consolidated buying desks at multinational apparel houses are compressing supplier rosters and demanding volume commitments that favor scaled producers. Direct mill relationships are displacing traditional textile trading houses in sourcing channels. This concentration is most visible in Germany and France where luxury conglomerates have centralized procurement functions.
Lining Fabric Market Segmentation
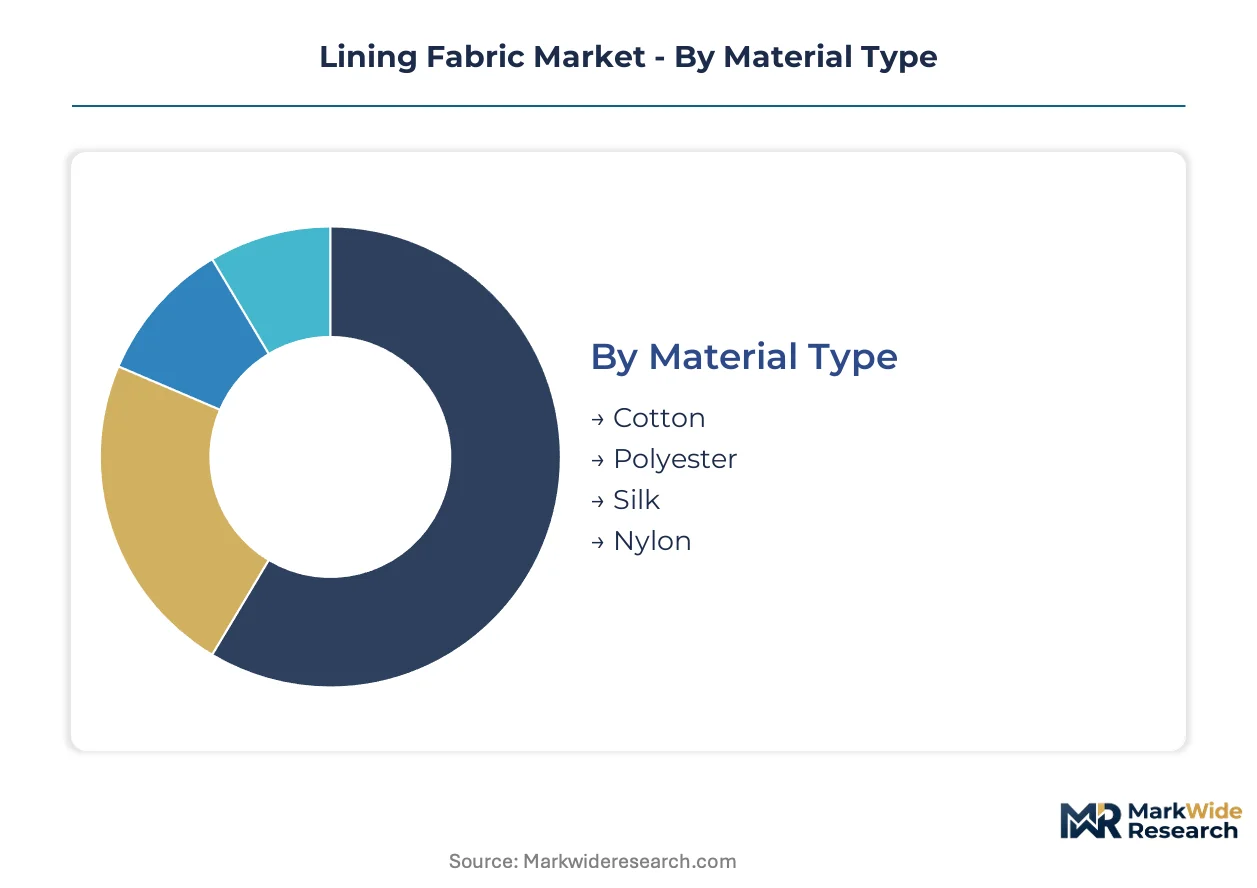
Lining fabric procurement is fragmenting along certification boundaries, with OEKO-TEX and REACH compliance creating tiered supply eligibility. Material specifications diverge sharply across end-use applications, forcing mills to maintain parallel production lines. Understanding these segment boundaries reveals where margin compression and premium capture occur.
Material Type:
Cotton and polyester face divergent certification burdens—natural fibers carry pesticide residue testing under GB standards, while synthetics trigger SVHC scrutiny under REACH for antimony catalyst traces.
- Cotton:Cellulosic staple fiber prized for moisture absorption and skin-contact comfort in formalwear applications. European luxury houses specify long-staple Egyptian or Pima grades that require OEKO-TEX Standard 100 certification for chemical-free claims. Acreage constraints and water intensity limit scale expansion.
- Polyester:Petroleum-derived filament dominating casual and sportswear segments through dimensional stability and cost efficiency. Chinese mills produce the majority of global filament supply, with REACH compliance forcing reformulation of antimony catalyst systems. Chemical recycling technologies are gaining specification share in premium outerwear.
- Silk:Protein fiber reserved for luxury accessories and high-end formalwear where drape and luster justify material premiums. Mulberry silk from Zhejiang province faces heavy metal testing under EU regulations.
- Nylon:Polyamide filament engineered for abrasion resistance in cold-weather technical applications. Down-proof constructions for performance outerwear require specialized filament deniers and heat-set finishes.
Polyester sits at the top of the volume ranking, with recycled polyester variants climbing the fastest.
End Use:
Customer procurement scale varies dramatically—multinational apparel houses negotiate multi-year volume commitments, while upholstery converters purchase on spot markets with 90-day horizons.
- Apparel:Garment interior applications spanning formal suits, outerwear shells, and performance jackets. Brand specifications increasingly mandate traceable fiber content and closed-loop recycling claims. Chinese domestic fashion houses are upgrading lining grades for mid-market collections.
- Upholstery:Furniture and automotive seating applications requiring flame-retardant finishes and abrasion resistance. Automotive OEMs impose IATF quality systems that exclude smaller mills from qualification.
- Accessories:Handbag interiors, luggage compartments, and small leather goods. Luxury brands specify cupro or silk linings that command material premiums.
- Home Textiles:Curtain linings, bedding, and decorative applications. Thermal insulation properties drive specification for blackout curtain interlinings.
Apparel commands the largest procurement volumes, though upholstery is expanding most quickly as automotive seating specifications tighten.
Application:
Performance requirements stratify material selection—thermal regulation specifications in sportswear demand moisture-wicking finishes absent from formalwear grades.
- Cold Weather:Technical outerwear requiring down-proof construction, wind resistance, and thermal retention. Nylon filament dominates with specialized calendering treatments. European performancewear labels specify chemically recycled content for fiber integrity.
- Casual Wear:Everyday garments prioritizing cost efficiency and wash durability. Polyester taffeta and plain weaves serve mass-market denim and jacket applications.
- Formal Wear:Suits and occasionwear where drape and static control matter. Bemberg cupro and viscose satins face formaldehyde-free crosslinker mandates under tightening ECHA restrictions.
- Sportswear:Active garments requiring moisture management and stretch recovery. Polyester filament with wicking finishes and mechanical stretch constructions.
Casual Wear maintains volume leadership, while Cold Weather applications are gaining share fastest on technical outerwear expansion.
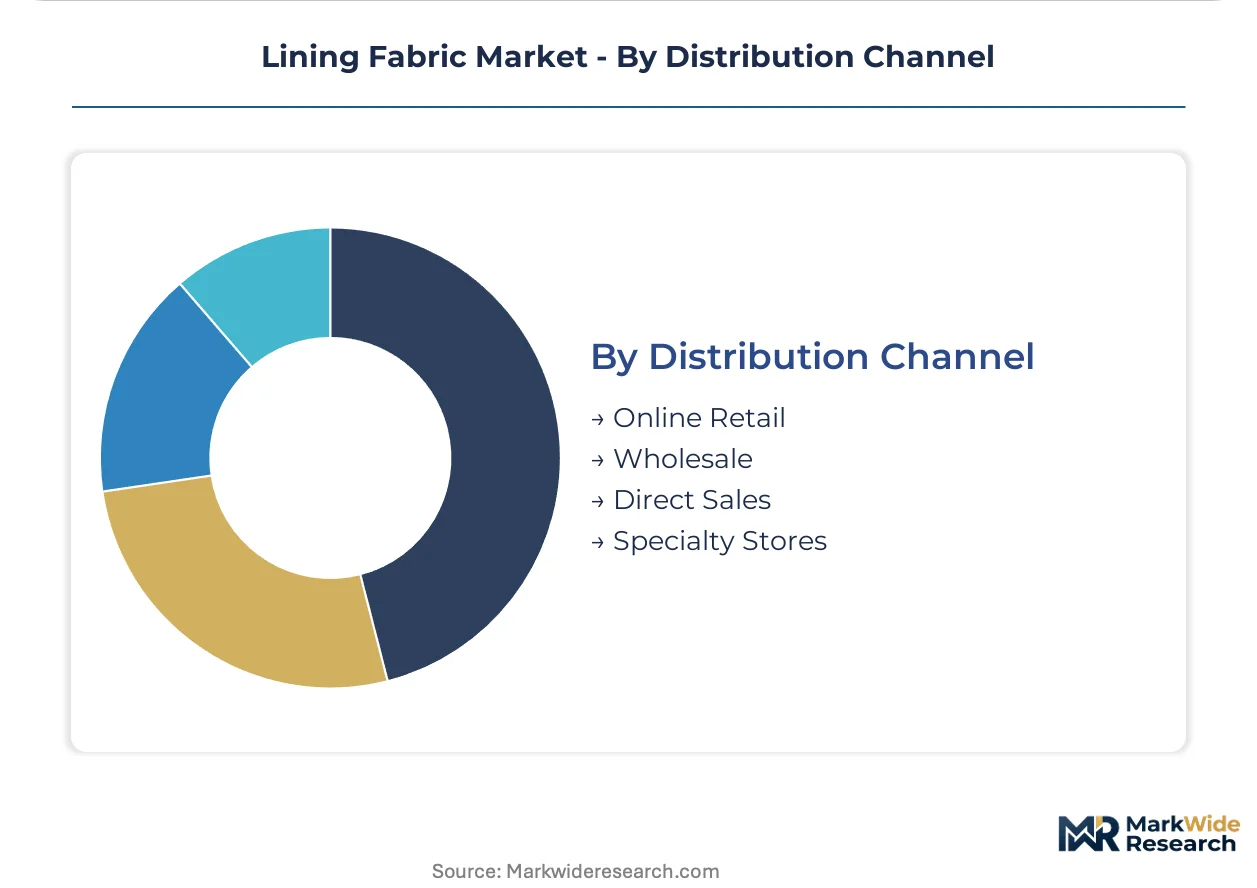
Distribution Channel:
Channel selection determines margin capture—direct sales bypass agent commissions but require dedicated technical service teams.
- Online Retail:Digital platforms serving small-batch designers and independent makers. Sampling logistics and color matching complexity limit scaling.
- Wholesale:Traditional textile trading houses aggregating mill production for converter access. Consolidating buying desks at multinational houses are compressing this channel's relevance.
- Direct Sales:Mill-brand relationships eliminating intermediary margins. Requires in-house technical service and colorimetric laboratories.
- Specialty Stores:Regional distributors serving niche applications like theatrical costuming or heritage tailoring.
Wholesale retains the highest transaction volumes, with Direct Sales channels expanding most rapidly as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest procurement volumes for lining fabrics, while European markets impose the strictest chemical disclosure regimes. India is emerging as an alternative production base under industrial policy incentives. Regional regulatory divergence is fragmenting supplier certification requirements across major demand centers.
China
Domestic fashion houses in Shanghai and Shenzhen are upgrading garment interiors for mid-market collections, driving cupro and viscose lining specifications. GB national standards govern chemical residue limits and fiber traceability with tightening enforcement. The Yangtze River Delta filament cluster around Shaoxing and Suzhou supplies the majority of global polyester lining substrate.
Germany
Luxury conglomerates headquartered in Munich and Düsseldorf have centralized procurement functions, compressing supplier rosters. REACH compliance through ECHA mandates reformulation of dye carriers and finishing agents. The Stuttgart industrial corridor hosts specialized mills serving automotive upholstery applications with IATF quality certification.
United States
Performance outerwear labels in Portland and Denver specify moisture-wicking polyester linings for technical cold-weather gear. EPA oversight intersects with state-level chemical disclosure laws in California. The Southeast textile belt maintains conversion capacity for apparel brands seeking reduced lead times from Asian filament imports.
India
Export-oriented garment units in Tiruppur and Bengaluru are sourcing linings domestically under the PLI scheme for technical textiles. BIS standards apply to fiber content labeling and quality assurance. The Gujarat chemical textile cluster is expanding filament yarn capacity to reduce import dependence from Chinese suppliers.
Japan
Technical textile demand from Osaka-based sportswear manufacturers emphasizes dimensional stability and thermal regulation. METI guidelines promote sustainable material innovation and closed-loop recycling claims. The Nagoya industrial region maintains precision weaving capabilities for premium nylon lining applications.
Lining Fabric Market Competitive Landscape
East Asian producers anchor the volume tier through integrated filament-to-fabric operations; European specialists hold premium positioning through certification depth and colorimetric precision. The vendor base stratifies across three tiers: multinational chemical conglomerates with polymer science capabilities, mid-scale regional converters with captive testing laboratories, and niche artisan mills serving heritage tailoring. Consolidated buying desks at apparel houses are compressing intermediary channels. Backward integration into polymer production and direct-to-brand digital sampling represent the dominant competitive vectors reshaping supplier relationships.
Among Japanese industrial conglomerates, Toray Industries and Asahi Kasei exemplify the polymer-science tier with integrated filament expertise. Freudenberg represents European specialization in nonwoven interlining technologies. These three anchors illustrate how geographic origin and corporate structure correlate with competitive archetype: the Japanese pair occupy positions defined by scale and materials science depth, while the German entity sits within a tier distinguished by application-specific engineering.
| Leading Market Players |
|---|
| Toray Industries |
| Asahi Kasei |
| BASF SE |
| Freudenberg |
| Chargeur |
| Zhejiang Huafon Group |
| Sankei |
| Edmund Bell |
| QST |
| Others |
Value Network & Pricing Analysis
Consolidated buying desks at multinational apparel houses are compressing supplier margins and enforcing volume-commitment pricing models that favor scaled polyester filament producers. This buyer concentration is reshaping how mills structure tiered pricing across certification grades and geographic delivery zones.
Pricing Analysis
Capacity additions in Shaoxing and Suzhou are reshaping price floors for standard-grade polyester taffeta. Three-tier pricing structure across OEKO-TEX certified premium, REACH-compliant standard, and uncertified economy levels separates procurement eligibility for Western brands from spot-market converters. Cost compression in economy-grade cupro is intensifying because cotton linter byproduct supply constrains raw material availability. Fast-fashion houses in Bangladesh and Vietnam exhibit highest price sensitivity, while European luxury conglomerates prioritize certification depth over unit cost.
Supply Chain Analysis
Regional distribution centers in Antwerp and Rotterdam serve as consolidation hubs for European garment converters sourcing filament from East Asian mills. Production gravity centers on coastal China, South Korea, and emerging Gujarat-based capacity in India. Filament yarn supply rests on purified terephthalic acid and monoethylene glycol feedstocks tracking crude oil derivative movements. Single-source dependencies on Zhejiang province filament clusters amplify disruption vulnerability from logistics chokepoints. Distribution runs through direct mill-brand relationships displacing traditional textile trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where REACH and OEKO-TEX certification depth is displacing undifferentiated volume competition. Chinese domestic fashion brands upgrading mid-market collections are pulling premium cupro and viscose specifications.
For Market Incumbents: Anchor supply relationships through captive testing laboratories that compress certification timelines for multinational apparel houses. Defend margin position by securing long-staple cotton linter offtake agreements before bio-based polyester scales. Threat substitution from chemically recycled filament demands immediate specification relationships with European performancewear labels. For New Entrants and Emerging Players: The price-point gap between Bemberg cupro and standard viscose creates entry space for mid-tier mills investing in formaldehyde-free crosslinker capabilities. Target India's PLI-incentivized technical textile segment where domestic lining demand from Tiruppur garment units outpaces local filament supply. Go-to-market angle: direct digital sampling platforms that bypass agent networks and capture development-cycle margin. For Investors and Strategic Acquirers: Chemical conglomerates with polymer science capabilities are the most active acquirer in this space, consolidating mid-scale converters to secure backward integration into filament production. Five-to-ten-year viability hinges on bio-based polymer performance parity and closed-loop recycling infrastructure deployment. Acquisition target archetype: regional converters with captive GB-standard certification serving Chinese domestic brands. Signal to watch: ECHA SVHC list expansion accelerating formaldehyde-free reformulation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filament Production | Captive PTA/MEG supply secures margin against petrochemical volatility for polyester specialists. |
| OEKO-TEX Standard 100 Certification Investment | European retailer mandates make certification non-negotiable for Western brand supply lists. |
| Bio-based Polymer Pilot Scale-Up | Polylactic acid filament approaching performance parity creates first-mover specification relationships. |
| Direct-to-Brand Digital Sampling Platform | AI-assisted color matching compresses development cycles and displaces traditional agent commissions. |
| India PLI Scheme Capacity Expansion | Domestic filament production captures share in export-oriented garment units historically dependent on Chinese imports. |
Research Methodology
Multiple input streams — technical textile procurement managers, dye house operations directors, regulatory compliance officers, and brand sustainability leads — were reconciled against customs trade data, GB standard enforcement records, and SEC filings from listed chemical conglomerates. Bottom-up mill capacity estimates and top-down apparel production forecasts were cross-validated through triangulation.
Historical shipment volumes from Shaoxing and Suzhou filament clusters were cross-referenced against panel input from European luxury house procurement heads. Segmentation dimensions modeled include material type, end-use application, certification tier, and regional regulatory cluster. CAGR derivation incorporated filament price elasticity coefficients and substitution rates for recycled content specifications across the analysis window.
Caveats apply where ECHA SVHC list expansion, crude oil derivative volatility, or PLI scheme implementation delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market