
 Cationic Dyes Market | 2026-2036
Cationic Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Cationic Dyes Market Analysis
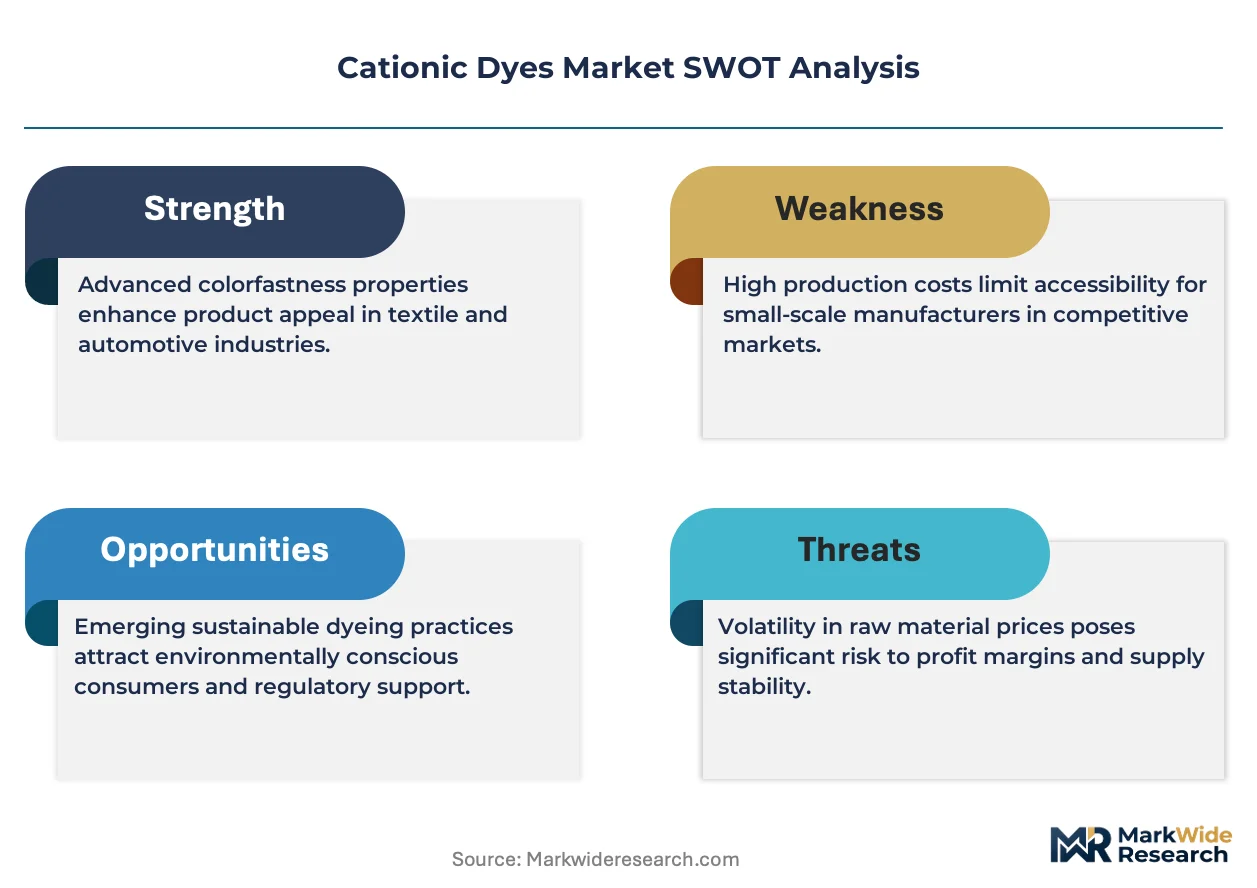
ISO 14001 environmental management certification is rotating the competitive set toward suppliers with verified lifecycle credentials. Zhejiang Longsheng Group leverages captive intermediates and salt-field backward integration to control input volatility. LANXESS AG anchors its position through European REACH pre-registration and specialty azo-free product lines. Huntsman Corporation differentiates via reactive-cationic hybrid platforms that reduce water intensity in exhaust dyeing.
Cationic dyes are quaternary ammonium salt-based colorants that ionically bond with anionic sites on acrylic, modacrylic, and cationic-dyeable polyester fibers, typically applied in acidic baths at temperatures between 80°C and 100°C with specific pH control. Their primary commercial purpose is to deliver brilliant, wash-fast shades on synthetic substrates where conventional direct or reactive chemistries achieve poor fixation. Within product type segmentation, basic dyes occupy the dominant volume position due to established acrylic fiber compatibility, while reactive dyes represent the fastest-expanding margin pool as textile mills pursue combined shade brilliance and reduced effluent load. Application segmentation shows textiles commanding the largest share, though plastic coloration for automotive interior components is gaining traction as OEMs specify cationic-compatible polymer grades.
EPA effluent guidelines under the Clean Water Act constrain US-based dyehouse operations, while ECHA REACH restrictions on aromatic amine releases shape formulation chemistry across European supply chains. China's MEE enforcement of GB 4287 textile wastewater standards is forcing capacity consolidation in Shandong and Zhejiang provinces, raising compliance costs for smaller compounders. Stakeholders must monitor how regional enforcement variance between these frameworks redirects production geography and procurement qualification requirements.
Market Dynamics
REACH pre-registration and China's GB 4287 wastewater enforcement are compressing supplier margins while accelerating consolidation among compounders with captive intermediate production. The regulatory divergence between European aromatic amine restrictions and US EPA effluent guidelines is fragmenting formulation strategies across Atlantic and Pacific supply chains.
Growth Catalysts
- Acrylic sportswear expansion:Polyester and modacrylic fiber uptake in athletic apparel manufacturing is expanding the addressable substrate base for cationic dye formulations, particularly in moisture-wicking fabric categories.
- ECHA REACH aromatic amine protocols:European restrictions on hazardous discharge are redirecting procurement toward certified low-impact chemistries with verified lifecycle credentials.
- Zhejiang-Jiangsu cluster concentration:Integrated dyeing and finishing complexes in these provinces anchor regional supply chains with backward integration into salt-field intermediates.
Market Restraints
- Crude oil derivative volatility:Petrochemical feedstock fluctuations compress margin predictability for quaternary ammonium salt production, forcing hedging costs onto smaller compounders.
- Shandong capacity consolidation:China's MEE enforcement is eliminating sub-scale dyehouses, reducing spot-market liquidity and concentrating bargaining power among surviving integrated producers.
- Reactive dye substitution:Hybrid reactive-cationic platforms achieve comparable brilliance with lower water intensity, threatening pure cationic volumes in exhaust dyeing applications.
Strategic Opportunities
- Automotive interior plastics:OEM specification of cationic-compatible polymer grades for dashboard and trim components opens non-textile volume channels with higher formulation premiums.
- ISO 14001 certification arbitrage:Verified environmental management credentials command procurement preference from multinational textile brands with Scope 3 disclosure obligations.
- Digital textile printing convergence:Inkjet-compatible cationic dispersions enable on-demand coloration for acrylic-based technical textiles, bypassing conventional bath dyeing infrastructure.
Industry Challenges
- Effluent treatment capex burdens:Zero-liquid discharge installation requirements for GB 4287 compliance demand capital allocations that strain compounders below 5,000-ton annual capacity.
- Cross-regulatory formulation complexity:Maintaining parallel product lines for EPA, ECHA, and MEE compliance regimes extends R&D cycle times and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cationic Dyes Market |
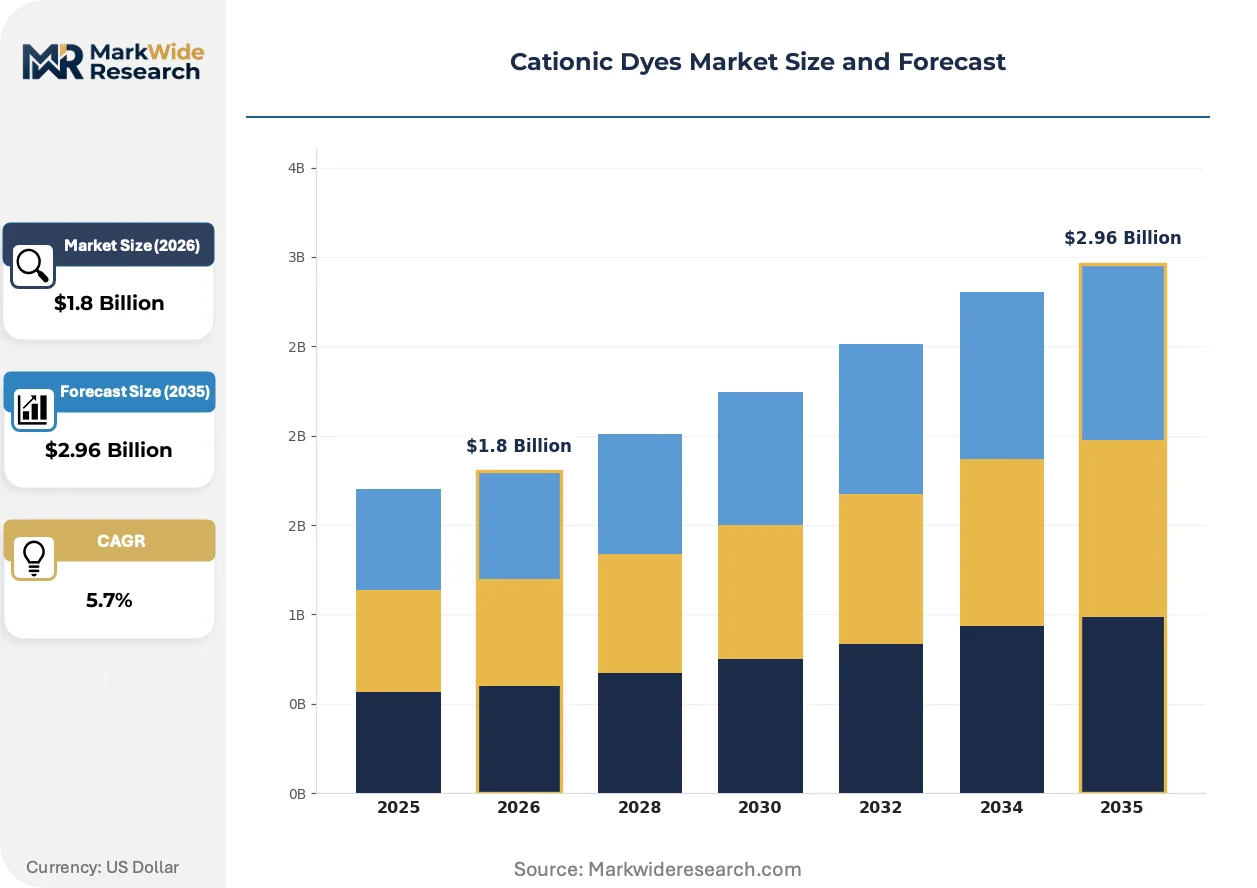
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Dyes, Acid Dyes, Direct Dyes, Reactive Dyes Application: Textiles, Paper, Leather, Plastic End User: Apparel Manufacturers, Home Furnishing, Automotive, Coatings Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Tianjin Tianshun Chemical Dyestuff, Zhejiang Longsheng Group, LANXESS AG, Atul Limited, Huntsman Corporation, BASF SE, Archroma, Runtu, Jin-Jiang Chemical Dyestuff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cationic Dyes Market Emerging Trajectories
Formulation chemistry is pivoting toward waterless and low-temperature application methods as energy costs and discharge regulations tighten simultaneously. The convergence of digital coloration with traditional exhaust processes is compressing batch sizes and accelerating shade-matching cycles.
Micro-encapsulated cationic dye systems are miniaturizing particle size distributions to enable sublimation transfer onto synthetic substrates without aqueous processing. Automotive textile suppliers in Germany and Japan are adopting these systems for interior component coloration, reducing wastewater generation by eliminating conventional acidic bath stages. The technology is compressing minimum order quantities and enabling just-in-time shade customization for tier-2 upholstery suppliers.
ECHA REACH restrictions on aromatic amine releases are forcing reformulation of legacy azo-based cationic chromophores across European supply chains. Dyehouses in Italy and Portugal are qualifying metal-free alternatives with comparable wash-fastness profiles, absorbing higher raw material costs to maintain market access. The regulatory pressure is accelerating substitution timelines for basic dye categories previously dominant in acrylic fiber applications.
Certification-driven procurement is displacing spot-market purchasing among multinational apparel brands with Science Based Targets initiative commitments. Buyers are consolidating supplier panels to those with ISO 14001 and ZDHC MRSL conformance, funneling volume toward integrated compounders with verified chemical management systems. This pattern is most visible in Nordic and Benelux markets where brand sustainability disclosure requirements are most stringent.
Cationic Dyes Market Segmentation
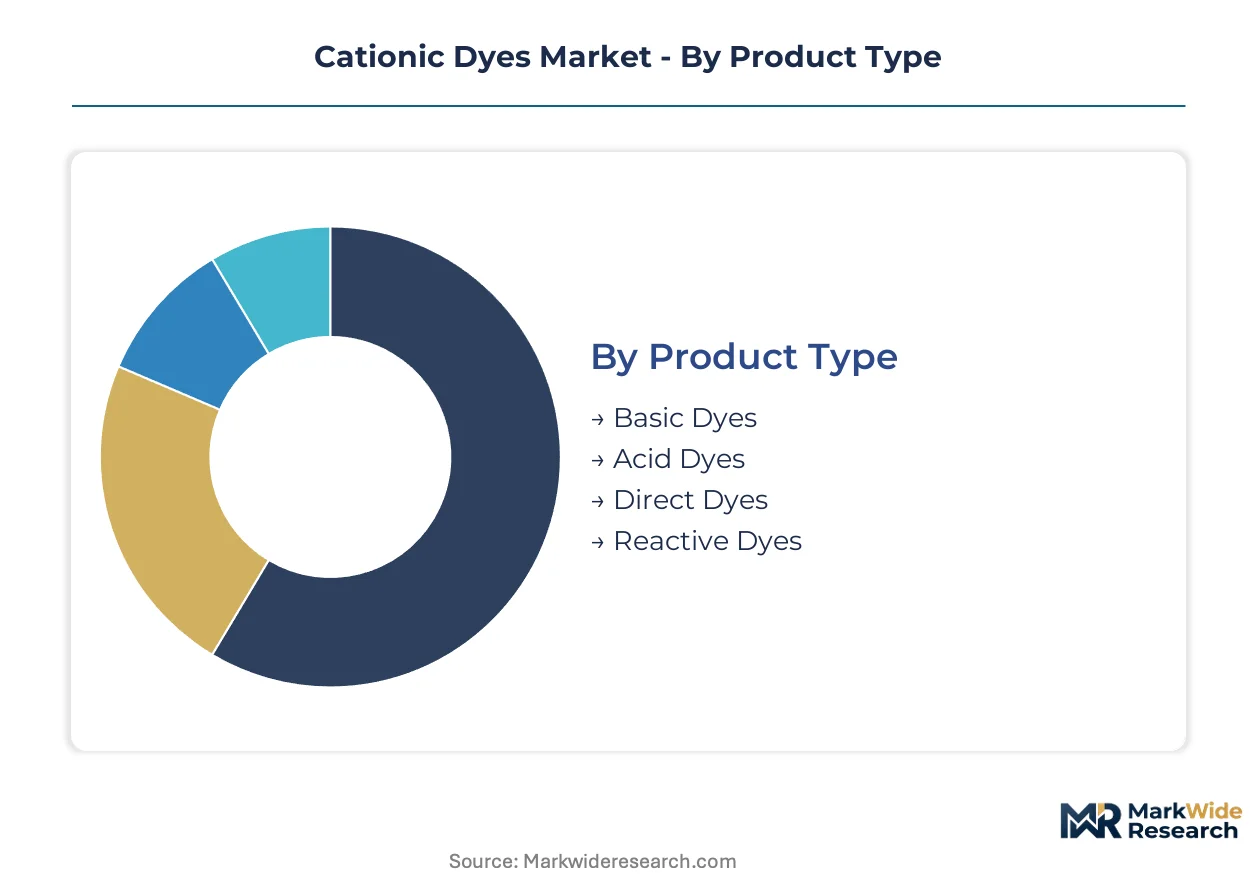
Cationic dye procurement splits across formulation chemistry, substrate compatibility, and channel economics. Each segmentation axis reveals distinct margin pressures and substitution vulnerabilities that reshape supplier priorities.
Product Type:
Reactive dye platforms are exerting the strongest substitution pressure on legacy cationic chemistries, particularly in water-intensive exhaust dyeing applications where hybrid systems claim comparable brilliance with reduced effluent loads.
- Basic Dyes:Quaternary ammonium salt chromophores deliver maximum tinctorial strength on acrylic and modacrylic fibers through ionic bonding in acidic baths. Demand concentrates in China's Zhejiang province, where integrated dyeing complexes process bulk acrylic sportswear orders for export markets facing REACH aromatic amine restrictions.
- Reactive Dyes:Covalent-bonding formulations achieve superior wash-fastness on cellulosic-cationic fiber blends while reducing water intensity versus pure cationic exhaust processes. Automotive textile suppliers in Germany and Japan are qualifying these systems for interior component coloration to meet OEM sustainability disclosure requirements.
- Acid Dyes:Anionic formulations for protein and polyamide substrates with limited cationic compatibility.
- Direct Dyes:Water-soluble alternatives for cotton-polyester blends where cationic fixation remains suboptimal.
Basic dyes anchor the volume base while reactive dyes gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity textile coloration from specialized polymer grades commanding formulation premiums.
- Textiles:Acrylic, modacrylic, and cationic-dyeable polyester fiber processing dominates commercial uptake, with moisture-wicking athletic apparel driving specification volumes. Shandong province capacity consolidation under China's MEE GB 4287 enforcement is eliminating sub-scale dyehouses and concentrating orders among surviving integrated producers with captive intermediate supply.
- Plastic:Cationic-compatible polymer grades for dashboard and trim components enable non-textile volume channels with higher margin structures. OEM specification in Germany and Japan requires metal-free chromophore alternatives absorbing elevated raw material costs to maintain market access.
- Paper:Specialty packaging and decorative applications with limited cationic dye penetration.
- Leather:Niche coloration for synthetic leather substrates in footwear and accessories.
Textiles command the dominant revenue position while plastic applications expand most quickly as automotive interior specifications proliferate.
End User:
Customer type segmentation tracks procurement consolidation toward multinational brands with verified chemical management systems.
- Apparel Manufacturers:Polyester sportswear producers in China's Jiangsu province anchor regional demand, with ISO 14001 certification now a baseline qualification for panel inclusion. Nordic and Benelux brand sustainability disclosure requirements are funneling volume toward compounders with ZDHC MRSL conformance.
- Automotive:Tier-1 and tier-2 upholstery suppliers specify cationic-compatible polymer grades for just-in-time shade customization, with micro-encapsulated dye systems compressing minimum order quantities.
- Home Furnishing:Curtain, carpet, and upholstery textile producers with moderate cationic penetration.
- Coatings:Industrial and decorative coating formulators with limited cationic dye adoption.
Apparel manufacturers anchor the volume base while automotive gains share at the steepest rate.
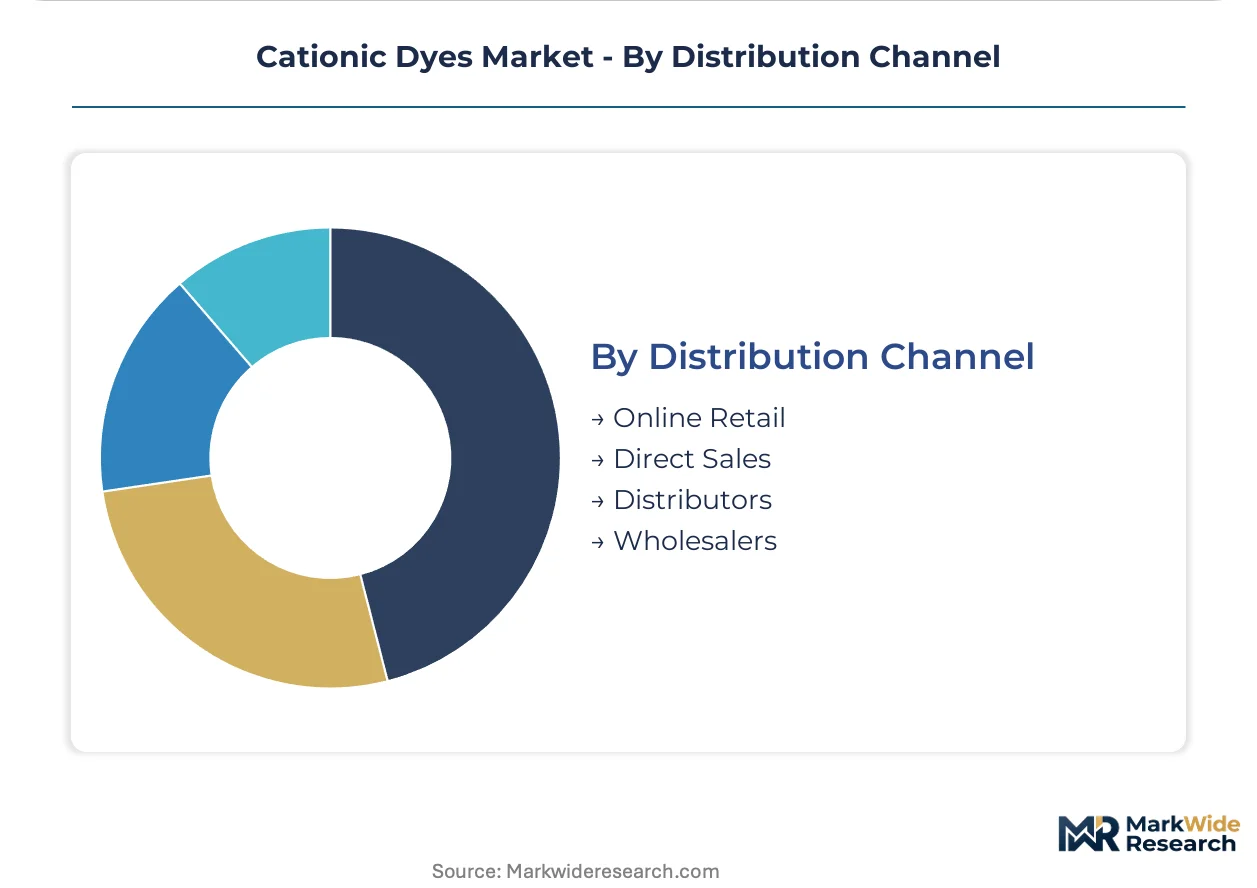
Distribution Channel:
Supply concentration dynamics favor direct relationships with integrated compounders possessing captive intermediate production.
- Direct Sales:Large-volume textile mills and automotive tier-1 suppliers negotiate directly with Zhejiang Longsheng Group and LANXESS AG for certified low-impact chemistries with verified lifecycle credentials. REACH pre-registration and salt-field backward integration provide procurement security against feedstock volatility.
- Distributors:Regional chemical distributors serve mid-scale dyehouses in Portugal and Italy qualifying metal-free alternatives to maintain European market access.
- Online Retail:Limited cationic dye penetration due to technical specification requirements and hazardous material shipping constraints.
- Wholesalers:Spot-market liquidity declining as China's MEE enforcement eliminates sub-scale compounders.
Direct sales anchor the volume base while distributor relationships gain share at the steepest rate among mid-scale European dyehouses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apparel manufacturers with Science Based Targets initiative commitments concentrate procurement among ISO 14001-certified compounders. This buyer archetype consolidation redirects volume toward integrated producers with verified chemical management systems and captive intermediate supply.
China
Acrylic sportswear exports and cationic-dyeable polyester fiber production dominate demand. MEE enforcement of GB 4287 wastewater standards eliminates sub-scale dyehouses in Shandong province. Zhejiang and Jiangsu provinces anchor integrated dyeing complexes with backward integration into salt-field intermediates.
Germany
Automotive interior specifications and tier-1 upholstery suppliers drive cationic-compatible polymer grade demand. ECHA REACH aromatic amine restrictions force reformulation of legacy azo-based chromophores. Dyehouses in southern Germany qualify metal-free alternatives to maintain OEM market access.
United States
Moisture-wicking athletic apparel manufacturing and polyester sportswear production expand substrate applications. EPA effluent guidelines under the Clean Water Act constrain dyehouse operations. Southeast textile clusters face compliance cost pressures from zero-liquid discharge installation requirements.
India
Acrylic fiber processing for domestic apparel and export-oriented garment manufacturing anchors volume demand. BIS certification requirements and state-level pollution control board enforcement tighten discharge standards. Gujarat and Tamil Nadu textile clusters consolidate procurement toward compounders with verified environmental credentials.
Japan
Automotive interior component coloration and technical textile applications specify low-water-intensity formulations. METI chemical substance regulations and JIS standards shape formulation chemistry. Nagoya-area suppliers adopt micro-encapsulated dye systems for just-in-time shade customization.
Cationic Dyes Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive intermediate production and specialty dye houses with formulation expertise. The competitive set rotates around three structural tiers: salt-field backward-integrated Asian producers, European REACH-pre-registered specialty houses, and hybrid reactive-cationic technology developers. Consolidation accelerates through capacity expansion in Zhejiang province and strategic partnerships for automotive polymer grade qualification.
Among China-based integrated producers, Zhejiang Longsheng Group exemplifies the backward-integrated archetype with captive control over input volatility. LANXESS AG and Huntsman Corporation represent the European and transnational specialty tiers respectively, anchoring positions through regulatory pre-registration and hybrid platform development. These three entities occupy the core competitive terrain where certification credentials and verified lifecycle management determine procurement access.
| Leading Market Players |
|---|
| Tianjin Tianshun Chemical Dyestuff |
| Zhejiang Longsheng Group |
| LANXESS AG |
| Atul Limited |
| Huntsman Corporation |
| BASF SE |
| Archroma |
| Runtu |
| Jin-Jiang Chemical Dyestuff |
| Others |
Supply Flow & Price Mechanics
Captive salt-field backward integration among Zhejiang province compounders compresses input cost variance and establishes price floors that sub-scale Shandong producers cannot match under GB 4287 compliance burdens. Scale advantages in quaternary ammonium salt production concentrate bargaining power among integrated dye houses while spot-market liquidity erodes.
Pricing Analysis
Cost-plus contracts indexed to benzene and aniline derivatives dominate procurement between large-volume textile mills and integrated compounders. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified formulations from conventional basic dye grades. Pricing pressure stems from reactive dye substitution in exhaust dyeing applications. Small-scale dyehouses in Portugal and Italy exhibit highest price sensitivity due to metal-free reformulation cost absorption.
Supply Chain Analysis
Inventory cycles stretching 6-8 weeks for aromatic amine intermediates expose compounders to petrochemical feedstock volatility. Manufacturing concentrates in China, Germany, and India, with Zhejiang province anchoring global basic dye capacity. Quaternary ammonium salt production draws from benzene, aniline, and nitrobenzene derivatives. Single-source vulnerability runs through Chinese salt-field intermediate supply. Distribution runs through direct sales relationships with automotive tier-1 suppliers and regional chemical distributors serving mid-scale European dyehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Verified lifecycle credentialing and captive intermediate production constitute scarce capabilities that determine procurement access in a consolidating supplier base. Compounders lacking backward integration face elimination under tightening wastewater enforcement.
For Market Incumbents: Consolidate capacity in Zhejiang province to capture GB 4287-driven Shandong exit volume. Deepen captive salt-field integration to hedge aniline derivative volatility. Defend against reactive-cationic hybrid substitution by accelerating low-temperature formulation R&D. For New Entrants and Emerging Players: Lead with ISO 14001 certification arbitrage to penetrate Nordic and Benelux brand supply chains with Science Based Targets initiative commitments. Target automotive interior plastics specifications in Germany and Japan where OEM sustainability disclosure requirements command formulation premiums. Deploy digital textile printing convergence as go-to-market angle for on-demand acrylic technical textile coloration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated compounders with long-term direct sales contracts to multinational apparel manufacturers. Five-to-ten year viability favors backward-integrated Asian producers with verified ZDHC MRSL conformance. Monitor ECHA REACH aromatic amine restriction expansion as inflection signal for metal-free chromophore substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt-Field Intermediates | Zhejiang Longsheng Group's captive aniline supply hedges input cost volatility against Shandong competitor exit. |
| ISO 14001 Certification Investment | Verified environmental management credentials unlock procurement panels with multinational brands facing Scope 3 disclosure obligations. |
| Reactive-Cationic Hybrid Platform Development | Huntsman Corporation's water-intensity reduction technology defends share against pure cationic volume erosion in exhaust dyeing. |
| Automotive Polymer Grade Qualification | Metal-free chromophore approval for dashboard and trim components opens non-textile volume channels with premium pricing. |
| Micro-Encapsulated Dye System Scale-Up | Nagoya-area suppliers' sublimation transfer technology eliminates aqueous processing for just-in-time shade customization. |
Methodological Framework
Operator-level perspectives from dyehouse plant managers, textile procurement leads at apparel manufacturers, automotive tier-1 supplier technical directors, and European chemical distribution channel partners anchored the qualitative base. Secondary validation drew from MEE GB 4287 enforcement records, ECHA REACH pre-registration databases, customs trade data for quaternary ammonium salt flows, and SEC filings of listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional production hub segmentation.
Sensitivity analysis tested forecast outputs against crude oil derivative volatility scenarios and regulatory enforcement variance between EPA, ECHA, and MEE regimes. The analytical framework modeled basic dye, reactive dye, acid dye, and direct dye chemistry segments alongside textile, plastic, paper, and leather applications across the projection horizon. CAGRs derived from regression analysis of historical acrylic fiber demand correlation and polyester sportswear production indices.
The analysis sits within stated boundaries; outcomes outside sustained synthetic fiber uptake or accelerated REACH restriction expansion would require recalibration. Forecasts reflect documented assumptions regarding Shandong capacity consolidation pace and automotive interior specification adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market