
 PVC Tarpaulin Sheets Market | 2026-2036
PVC Tarpaulin Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Tarpaulin Sheets Market Analytics
Direct-to-fleet distribution is fragmenting as logistics operators in North America and Asia bypass traditional distributors to source PVC tarpaulin sheets through contracted converters. Sioen Industries leverages in-house coating lines across Belgium and Vietnam to sustain margin control on heavy-duty grades for European truck OEMs. HeytexBrandenburger GmbH anchors its position through technical textile R&D intensity, while Shur-Co LLC competes on automated cover-system integration for flatbed fleets.
PVC tarpaulin sheets are woven polyester or nylon substrates coated with polyvinyl chloride resin, typically calendered to weights between 400 and 900 grams per square meter to achieve tear resistance above 200 N and weldable seams for weatherproof enclosures. Their primary industrial purpose spans cargo protection, temporary shelter, and agricultural coverage where UV stability and chemical resistance exceed polyethylene alternatives. Coated tarpaulin dominates value pools in logistics and military procurement due to repairability and extended service life, while laminated tarpaulin is gaining share in event management and tent manufacturing where printability and lighter handling matter. Heavyweight grades remain the mature profit center for construction site enclosures, though extra heavyweight variants for offshore and mining applications are expanding fastest in absolute volume terms.
REACH in Europe and GB standards under China's SAMR framework are restricting certain plasticizer chemistries, compelling reformulation toward DINCH or bio-based alternatives that alter cost structures and supplier qualification timelines. The EPA in the United States monitors vinyl chloride emissions from coating operations, shaping plant location decisions and capital allocation for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance with multiple standards simultaneously will determine which manufacturers retain access to premium logistics and defense contracts.
Market Dynamics
Logistics fleet operators are consolidating procurement authority and demanding weldable, repairable tarpaulin grades that outlast polyethylene alternatives in open-deck and refrigerated transport cycles.
Growth Catalysts
- Cold-chain logistics expansion:Temperature-controlled freight operators in India and Southeast Asia are specifying coated PVC tarpaulin for insulated truck curtains and trailer bulkheads that withstand repeated thermal cycling.
- REACH phthalate restrictions:European formulators are accelerating DINCH and bio-based plasticizer adoption to maintain access to logistics and defense contracts under tightening ECHA thresholds.
- Technical textile incentives:India's PLI scheme for technical textiles is pulling laminated tarpaulin capacity toward domestic truck cover and highway infrastructure applications.
Market Restraints
- Plasticizer cost volatility:DINCH and citrate-based alternatives trade at premiums to conventional phthalates, compressing margin on mid-weight grades for price-sensitive agricultural buyers.
- Coating capacity concentration:Heavy-duty calendering lines cluster in Belgium, Vietnam, and eastern China, exposing buyers to freight cost spikes and extended lead times during regional disruptions.
- Polyethylene substitution in temporary shelter:Disaster relief and short-term event applications are migrating to woven HDPE where UV exposure duration falls below 18 months.
Strategic Opportunities
- Offshore and mining extra-heavyweight grades:Oil platform maintenance shelters and bulk ore covers in Brazil and West Africa require 900+ gsm weldable fabrics with flame-retardant certification gaps currently served by limited suppliers.
- Digital print compatibility:Event management and retail branding buyers are specifying laminated tarpaulin with solvent-free ink adhesion for short-run custom wraps.
- Automated cover system integration:North American flatbed fleets are retrofitting electric rolling tarp systems that demand precision-cut panel dimensions and reinforced edge webbing.
Industry Challenges
- Multi-jurisdiction certification timelines:Suppliers seeking simultaneous REACH, EPA, and GB standard compliance face 14-18 month qualification cycles that delay contract awards.
- Welding technician scarcity:Field repair networks for fleet operators lack certified hot-air and RF welding specialists, extending equipment downtime and eroding life-cycle cost advantages.
- Legacy coating line reconfiguration:Capital requirements for plasticizer-handling system upgrades are stranding mid-tier producers without access to project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Tarpaulin Sheets Market |
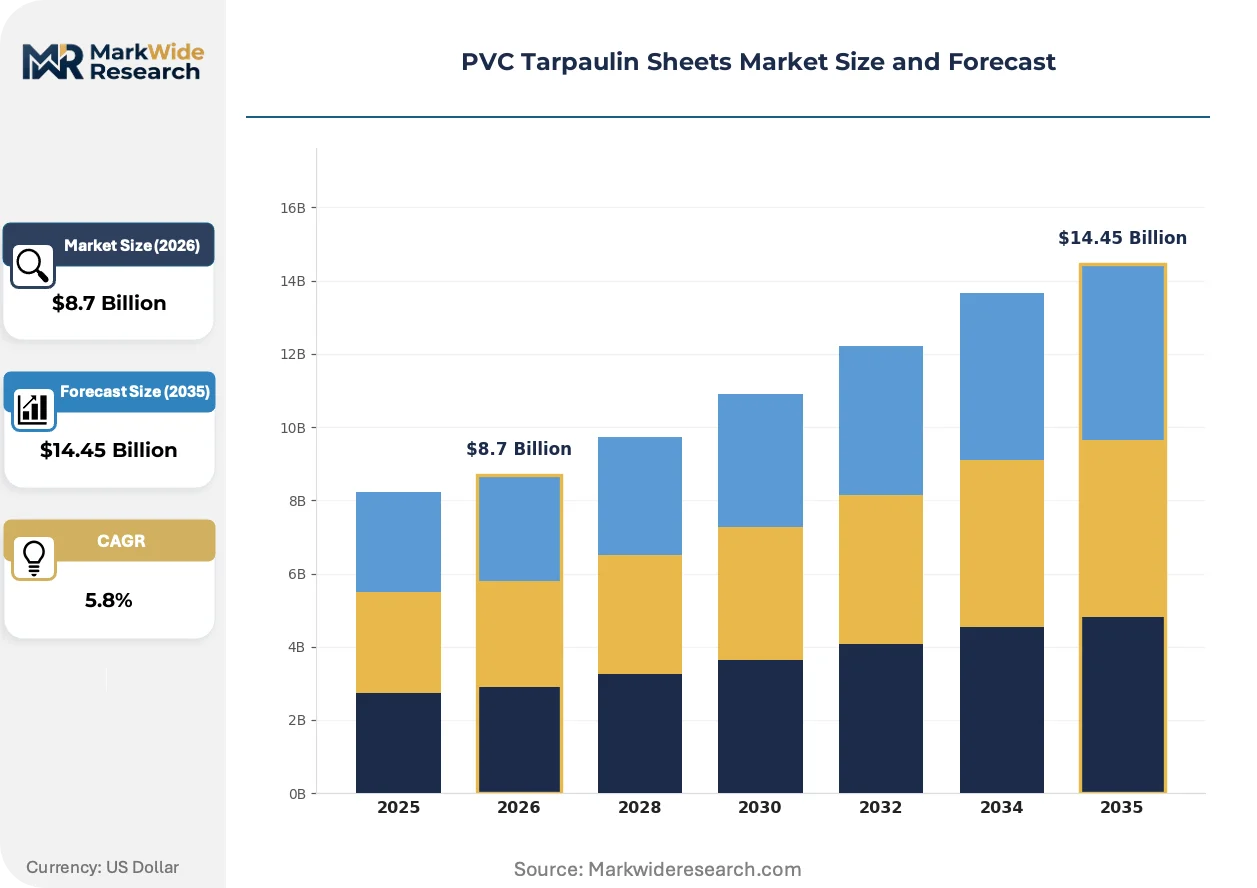
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
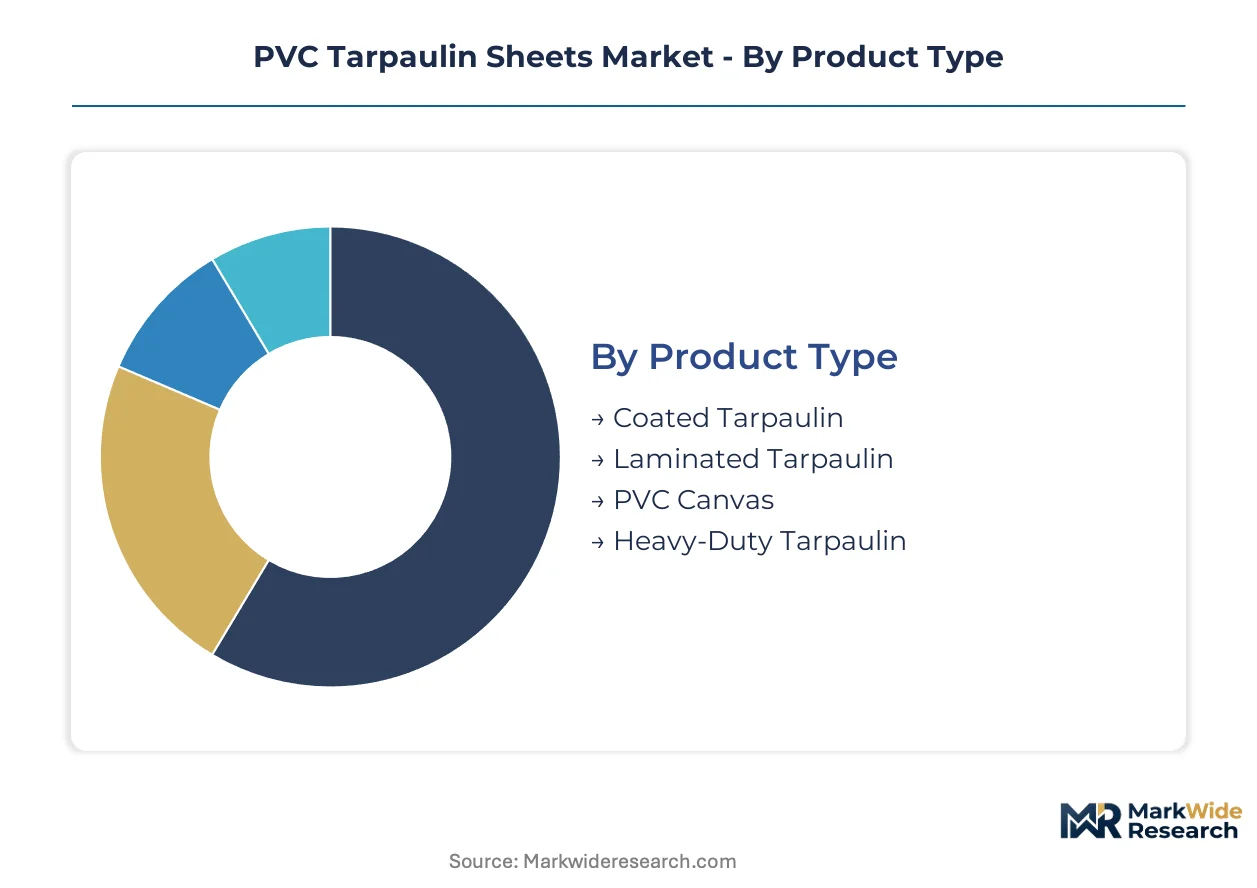
| Segmentation | Product Type: Coated Tarpaulin, Laminated Tarpaulin, PVC Canvas, Heavy-Duty Tarpaulin Application: Agricultural Cover, Industrial Use, Truck Cover, Tent Manufacturing Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight End User: Logistics Companies, Construction, Agriculture, Event Management |
| Companies Covered | Sioen Industries, HeytexBrandenburger GmbH, Naizil Canada Inc., Shur-Co LLC, SRF Limited, Seaman Corporation, Canadian Tarpaulin Manufacturers Ltd, Tan Dai Hung Plastic JSC, Cunningham Covers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Tarpaulin Sheets Market Evolving Landscape
Reformulation chemistry and procurement centralization are compressing supplier qualification windows while opening technical specification gaps for specialized fabricators.
Non-phthalate plasticizer technology is migrating from European defense and medical packaging origins into logistics-grade PVC tarpaulin. German and Belgian coaters are qualifying DINCH and bio-based ester formulations for 450-650 gsm truck curtain applications. This migration from phthalate-dependent supply chains is enabling qualified suppliers to command 8-12 point margin premiums on contracted fleet volumes.
REACH Annex XVII restrictions on specific plasticizer chemistries are forcing simultaneous reformulation across European coating operations. The industrial consequence is extended supplier audit timelines as ECHA compliance documentation replaces legacy material safety data sheets. Logistics procurement teams in Germany and the Netherlands are responding by consolidating qualified supplier lists to three to five approved coaters per specification grade.
Fleet procurement departments are centralizing tarpaulin specification authority and bypassing traditional distributor networks. Direct contracting with certified converters is displacing multi-tier distribution in North American flatbed and refrigerated segments. This concentration is most visible in the Upper Midwest and Texas corridor, where large fleet operators now issue annual volume commitments tied to welding certification and field service response time guarantees.
PVC Tarpaulin Sheets Market Segmentation
PVC tarpaulin procurement cycles vary dramatically by product grade and end-use intensity. Fleet operators replace truck curtains on 18-24 month intervals, while construction site enclosures run 5-7 years. Understanding these replacement rhythms shapes inventory planning and margin capture across the value chain.
Product Type:
Coated tarpaulin turns over fastest in logistics fleets where abrasion and thermal cycling accelerate wear. Laminated grades enjoy longer replacement cycles in semi-permanent installations.
- Coated Tarpaulin:Polyester or nylon substrates receive liquid PVC coating through direct or transfer methods, yielding 450-650 gsm fabrics with tear resistance exceeding 250 N. European refrigerated fleet operators in Germany and the Netherlands specify these grades for trailer curtains that withstand daily temperature swings from -25°C to ambient. REACH-compliant DINCH plasticizer formulations now command premium positioning in these contracts.
- Laminated Tarpaulin:Multi-layer construction bonds PVC film to woven substrate through heat and pressure without full coating saturation. Indian highway infrastructure projects under the PLI scheme for technical textiles are absorbing laminated volumes for truck covers and temporary site enclosures where printability and lighter handling reduce labor costs.
- PVC Canvas:Tighter weave density with heavier yarn counts produces artist-grade and architectural membrane surfaces. Belgian coaters supply museum restoration and tension structure architects requiring dimensional stability across humidity ranges.
- Heavy-Duty Tarpaulin:Calendered weights above 750 gsm target mining and offshore maintenance shelters. Brazilian oil platform contractors specify flame-retardant certified grades for platform module weatherproofing.
Heavy-duty tarpaulin dominates installed base value. Coated tarpaulin is where expansion concentrates.
Application:
Cost tiers separate commodity agricultural covers from specification-driven industrial procurement. Military and cold-chain logistics sit at the premium extreme.
- Truck Cover:Open-deck and refrigerated transport operators specify weldable, repairable grades that outlast polyethylene alternatives through repeated loading cycles. North American flatbed fleets in the Upper Midwest and Texas corridor now contract directly with certified converters, bypassing distributor markups.
- Industrial Use:Manufacturing facility weatherproofing, equipment covers, and bulk material containment demand chemical resistance and UV stability exceeding 5-year service life. Vietnamese coating lines supply Japanese automotive parts manufacturers with just-in-time panel delivery.
- Agricultural Cover:Grain storage, livestock shelter, and greenhouse cladding represent price-sensitive volume. Woven HDPE substitutes capture disaster relief and short-cycle applications where UV exposure falls below 18 months.
- Tent Manufacturing:Event management and disaster relief shelter production favor laminated grades for digital print compatibility and rapid deployment handling. Solvent-free ink adhesion specifications are emerging from European event contractors.
Industrial use commands highest per-square-meter pricing. Truck cover applications are climbing the fastest.
Thickness:
Volume concentration sits in medium and heavyweight grades, while margin pools deepen at specification extremes.
- Heavyweight:600-900 gsm calendered construction serves construction site enclosures and military field shelters. Chinese GB standard compliance timelines of 14-18 months restrict qualified supplier pools, supporting price premiums.
- Extra Heavyweight:Above 900 gsm with specialized flame-retardant or anti-static certification targets offshore oil platforms and mining bulk ore covers. West African iron ore exporters and Brazilian pre-salt maintenance contractors drive specification intensity.
- Medium:400-600 gsm balances durability and handling for general logistics and agricultural applications. Price competition from Southeast Asian coaters compresses margin on standard grades.
- Lightweight:Below 400 gsm serves temporary event signage and short-duration shelter where portability outweighs longevity. Polyethylene substitution pressure is most acute in this tier.
Medium thickness holds largest shipment volumes. Extra heavyweight grades are gaining share fastest.
End User:
Customer type determines procurement sophistication, from centralized fleet specification authority to fragmented agricultural dealer networks.
- Logistics Companies:Consolidated procurement departments issue annual volume commitments tied to welding certification and field service response guarantees. Direct-to-converter contracting displaces traditional distribution in North America and Western Europe.
- Construction:Project-based purchasing for site enclosures and temporary weatherproofing runs through general contractors and rental equipment providers. Belgian and Vietnamese coating clusters serve European and Asian construction cycles respectively.
- Agriculture:Dealer-mediated sales to individual farms and cooperatives face polyethylene substitution in price-sensitive segments. Indian technical textile incentives are pulling some laminated capacity toward commercial farming operations.
- Event Management:Short-run custom wraps and rapid-deployment shelters demand digital print compatibility and precision-cut panel dimensions. Automated cutting and RF welding capabilities differentiate suppliers in this segment.
Logistics companies concentrate specification authority. Event management is where supplier qualification windows are compressing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH Annex XVII restrictions on phthalate plasticizers anchor European procurement patterns, while India's PLI scheme for technical textiles and China's evolving GB standards under SAMR reshape supplier qualification timelines across Asia.
Germany
Cold-chain logistics operators in the Rhine-Ruhr corridor specify DINCH-plasticized coated tarpaulin for refrigerated trailer curtains. ECHA compliance documentation requirements extend supplier audit cycles to 14-18 months. Belgian coating clusters near Ghent serve German OEM demand through just-in-time panel delivery networks.
India
Highway infrastructure build-out and commercial fleet expansion drive laminated tarpaulin procurement for truck covers and construction site enclosures. The PLI scheme for technical textiles pulls domestic coating capacity toward logistics applications. Gujarat and Maharashtra industrial corridors concentrate new calendering line investments.
China
GB standards under SAMR tighten phthalate-content thresholds for domestic and export-bound production. Yangtze River Delta coating operations reconfigure plasticizer-handling systems to maintain access to European logistics contracts. Qingdao and Ningbo ports anchor heavy-duty grade export volumes.
United States
EPA vinyl chloride emission monitoring shapes plant location decisions for domestic coaters. Upper Midwest and Texas corridor fleet operators centralize procurement authority and contract directly with certified converters. Chicago and Dallas-Fort Worth logistics hubs drive specification intensity for weldable repairable grades.
Brazil
Pre-salt oil platform maintenance contractors specify flame-retardant certified extra-heavyweight grades for offshore module weatherproofing. ANVISA industrial chemical oversight intersects with import qualification requirements for European-sourced formulations. Rio de Janeiro and São Paulo anchor procurement decision-making for mining and energy sector buyers.
PVC Tarpaulin Sheets Market Competitive Landscape
Vertically integrated European coaters and Asia-Pacific volume fabricators split the market between specification-driven premium tiers and cost-optimized standard grades. Market structure concentrates around three strategic archetypes: integrated coating-to-converter operators controlling heavy-duty formulation expertise, regional laminators serving price-sensitive agricultural and event management demand, and automated cover system integrators capturing fleet retrofit contracts. Competitive moves cluster on multi-jurisdiction certification stacking and direct-to-fleet distribution bypass.
Among European integrated operators, Sioen Industries and HeytexBrandenburger GmbH exemplify the coating-capability archetype with in-house calendering lines and REACH-compliant formulation portfolios. Shur-Co LLC occupies a position on the system integration vector, representing the North American fleet-solution specialist tier that contracts directly with logistics operators for precision-cut panel dimensions and field service guarantees. These three anchors illustrate how geographic clustering and regulatory qualification depth stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Sioen Industries |
| HeytexBrandenburger GmbH |
| Naizil Canada Inc. |
| Shur-Co LLC |
| SRF Limited |
| Seaman Corporation |
| Canadian Tarpaulin Manufacturers Ltd |
| Tan Dai Hung Plastic JSC |
| Cunningham Covers |
| Others |
Value Network & Pricing Analysis
Belgian coating clusters near Ghent anchor heavy-duty calendering capacity that feeds directly into German refrigerated fleet procurement, translating geographic supply concentration into sustained pricing power for DINCH-compliant formulations. This tight coupling between upstream capacity location and downstream contract terms shapes margin capture across the value chain.
Pricing Analysis
Price spreads between Belgian REACH-compliant grades and Southeast Asian standard formulations run wide enough to stratify buyer tiers. Three-tier pricing structure across premium, standard, and economy levels separates logistics fleet operators willing to pay for certification documentation from agricultural buyers facing polyethylene substitution pressure. Pricing pressure stems from DINCH and citrate-based plasticizer premiums compressing margins on mid-weight agricultural grades. Logistics companies show least price sensitivity due to total-cost-of-ownership calculations, while grain storage cooperatives represent the most price-vulnerable segment.
Supply Chain Analysis
Export-control regimes on flame-retardant chemical precursors limit qualified supplier pools for extra-heavyweight offshore grades. Heavy-duty calendering lines cluster in Belgium, Vietnam, and eastern China, drawing from woven polyester substrate networks and specialized plasticizer formulation channels. Single-source vulnerability concentrates in Belgian DINCH supply for European defense contracts. Distribution runs through direct-to-fleet contracting in North America and Western Europe, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-phthalate plasticizer migration is reshaping supplier qualification windows, compressing competitive access for unprepared manufacturers while opening margin premiums for qualified coaters.
For Market Incumbents: Harden DINCH and bio-based formulation portfolios against REACH Annex XVII enforcement timelines. Belgian and German coaters should deepen captive supply of compliant plasticizers to defend against Asian competitors still reconfiguring handling systems. Certification documentation depth becomes the priority lever for retaining logistics fleet contracts. For New Entrants and Emerging Players: Establish a beachhead in Indian laminated tarpaulin demand under the PLI scheme for technical textiles, where domestic capacity gaps persist for highway infrastructure applications. Target event management segments requiring solvent-free digital print compatibility, as qualification windows compress fastest here. Go-to-market through precision-cut panel capabilities and RF welding certification. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance arbitrage play because multi-jurisdiction certification stacking creates durable moats for qualified suppliers. Acquisition targets should display REACH-EPA-GB triple compliance or automated cover system integration capabilities. Watch ECHA threshold tightening announcements as the signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Formulation | DINCH captive supply secures margin control against volatile alternative chemistry costs. |
| Multi-Jurisdiction Certification Stacking | REACH-EPA-GB compliance opens access to premium logistics and defense contract pools. |
| Automated Cover System Integration | Precision-cut panel capabilities capture North American flatbed fleet retrofit demand. |
| Direct-to-Fleet Distribution Buildout | Bypassing distributor networks captures specification authority in Upper Midwest and Texas corridors. |
| Flame-Retardant Grade Capacity Addition | Extra-heavyweight certification gaps in Brazilian offshore and West African mining demand premium positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with logistics fleet procurement managers, coating plant technical directors, chemical formulation specialists, and technical textile distributors. Secondary validation drew from ECHA regulatory filings, SAMR GB standard updates, Indian PLI scheme technical textile notifications, and customs trade flow records. Bottom-up volume estimates from calendering line capacity assessments were triangulated against top-down demand projections from end-use industry consumption patterns.
Calibration against historical replacement cycle data and fleet procurement centralization trends anchored the analytical framework across the projection horizon. Segmentation modeling spanned product grade tiers, application intensity levels, thickness specifications, and end-user procurement sophistication. CAGRs were derived from regression analysis of volume trajectories against regulatory inflection points and infrastructure investment cycles. Plasticizer reformulation timelines and welding technician availability constraints served as industry-specific forecast modifiers.
Stress conditions across DINCH supply disruption scenarios, REACH enforcement acceleration, and polyethylene substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet procurement centralization rates and certification timeline standardization. Material shifts in ECHA Annex XVII scope expansion or SAMR GB standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market