
 Textile Wax Market | 2026-2036
Textile Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Wax Market Analysis
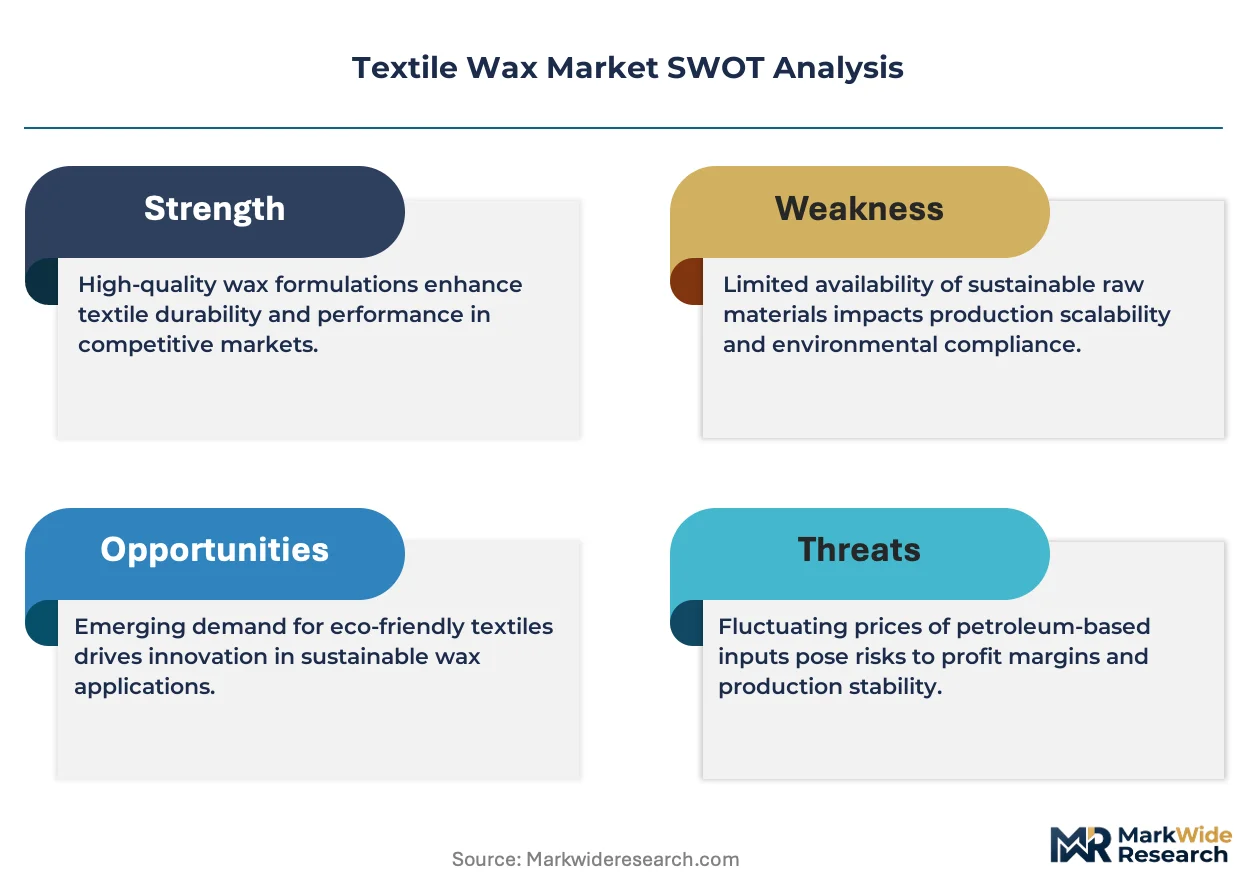
Skilled wax-compounding technicians in South Asia are unwinding as automation spreads across textile-finishing lines. BASF leverages its polymer-wax hybrid R&D to sustain premium positioning in European coating formulations. American Wax, Inc. anchors North American supply through backward integration into petroleum-derived feedstock refining. MM INTERNATIONAL competes on volume scale across Indian home-textile export corridors.
Textile wax encompasses hydrocarbon and natural-origin formulations applied to yarns and fabrics to impart water repellency, lubricity, and surface finish, typically melting between 46°C and 68°C depending on carbon-chain distribution. Paraffin wax dominates volume throughput in commodity coating lines where cost minimization governs procurement, while soy wax captures margin pools in sustainability-certified apparel programs. Beeswax occupies a narrow premium tier serving organic-labeled home textiles and artisanal embellishment segments where natural-origin claims command price premiums.
EPA oversight of petroleum-processing emissions shapes American Wax, Inc.'s refinery compliance costs, while REACH restrictions on polycyclic aromatic hydrocarbons in Europe redirect paraffin demand toward refined grades. India's BIS wax-quality standards for textile exports create certification friction for ungraded suppliers. Stakeholders must monitor bio-based wax scale-up economics against fossil-feedstock price volatility to calibrate portfolio exposure.
Market Dynamics
REACH restrictions on polycyclic aromatic hydrocarbons are compressing paraffin wax demand in Europe while redirecting procurement toward refined petroleum grades and bio-based alternatives. This regulatory pivot is fragmenting supplier tiers between compliance-ready refiners and commodity-grade producers.
Growth Catalysts
- Bio-based formulation advances:Soy and beeswax alternatives are capturing sustainability-certified apparel programs as outdoor brands tighten water-repellent finishing specifications.
- South Asian garment-exporting clusters:Bangladesh and Vietnam manufacturers are expanding wax-coated fabric output for performance outerwear, concentrating demand in high-volume coating corridors.
- REACH compliance deadlines:ECHA restrictions on PAH content in textile-contact materials are accelerating refinery investment in hydrotreated paraffin streams.
Market Restraints
- Crude oil price volatility:Petroleum-derived feedstock costs swing with Brent crude movements, compressing margin predictability for hydrocarbon wax producers.
- Indian BIS certification friction:Ungraded suppliers face rejection at export gates due to mandatory wax-quality standards for textile shipments.
- Natural wax supply concentration:Beeswax availability clusters with apiary regions in Turkey, Argentina, and Ethiopia, creating geographic single-source risk.
Strategic Opportunities
- Underpenetrated Vietnamese technical textiles:Industrial fabric finishing for automotive and filtration applications remains below saturation, opening volume expansion corridors.
- EU Green Deal procurement incentives:Public-sector textile purchasing guidelines now weight bio-based content, creating preferential access for soy wax compounders.
- Polymer-wax hybrid convergence:Polyethylene-wax blends with controlled crystallinity are enabling single-bath finishing lines that cut water and energy use.
Industry Challenges
- Skilled wax-compounding technician scarcity:Automation spreads across textile-finishing lines faster than workforce retraining programs in Bangladesh and Vietnam can replenish technical depth.
- Multi-standard certification timelines:Simultaneous pursuit of OEKO-TEX, GOTS, and ZDHC MRSL approvals extends product launch cycles by 8-14 months for bio-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Wax Market |
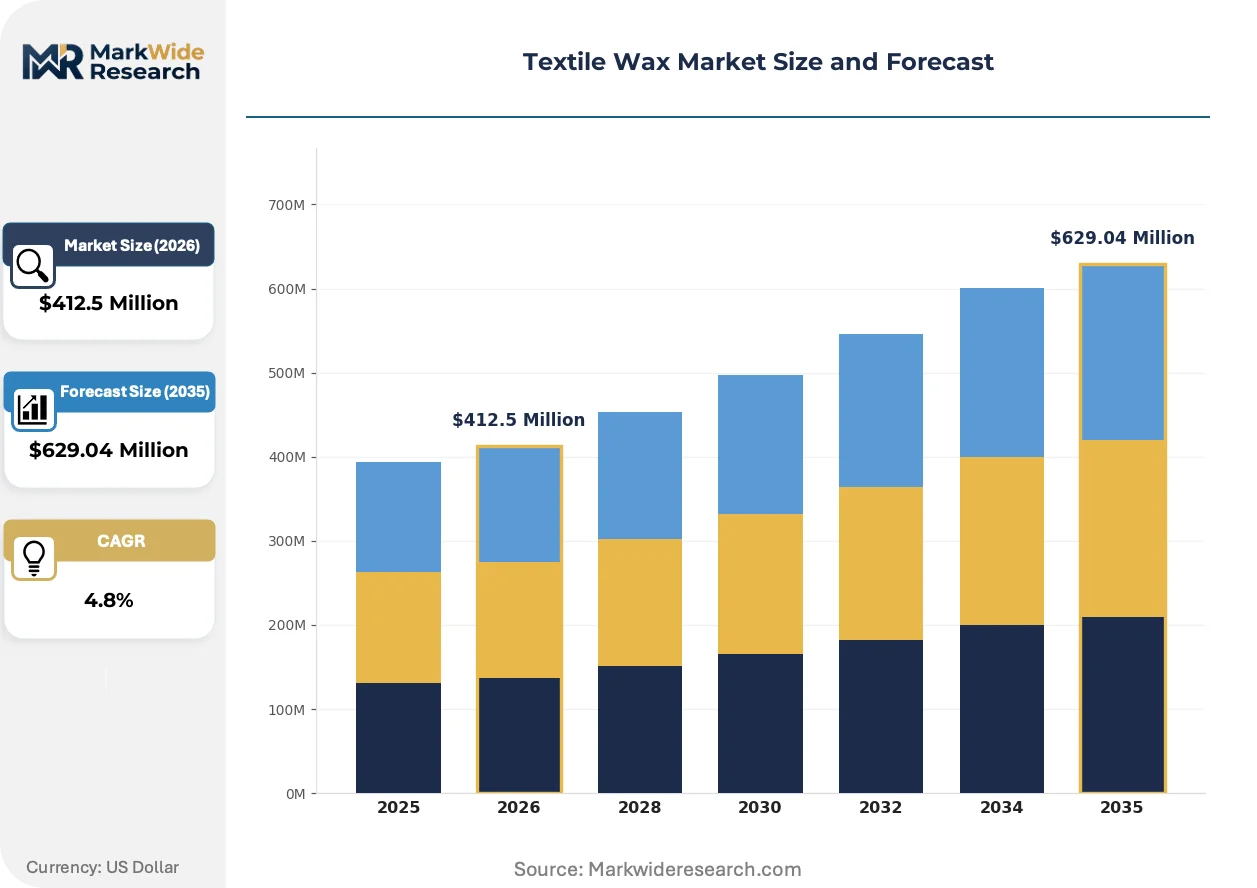
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Soy Wax, Beeswax Application: Coating, Finishing, Embellishment, Water Repellent End User: Apparel Manufacturers, Home Textiles, Industrial Textiles, Automotive Textiles Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Ghazi Trading Company, Roger A. Reed, Inc, MM INTERNATIONAL, BASF, The Seydel Companies, Inc, American Wax, Inc, CHEMAX MULTIKOTES (INDIA) PVT.LTD, The International Group, Inc., Sri Amman Wax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Wax Market Emerging Trajectories
Polymer-wax hybrid chemistry is fragmenting traditional petroleum-paraffin supply relationships while automation reconfigures finishing-line labor economics. Three developments are compressing incumbent positioning.
Encapsulated phase-change wax microspheres are decomposing the thermal-regulation segment previously served by bulk paraffin padding. Outdoor apparel brands in Germany and Switzerland are piloting these materials for alpine outerwear. The technology is decomposing volume-based procurement contracts by enabling gram-level functional dosing rather than kilogram-scale coating baths.
ECHA's 2025 update to REACH Annex XVII PAH limits is forcing textile wax importers to document hydrotreatment certificates for every petroleum-derived batch. German coating houses are absorbing 12-18% input cost premiums for certified-refined grades. Italian home-textile exporters are accelerating beeswax and rice-bran wax trials to bypass petroleum documentation entirely.
Direct mill-brand contracting is displacing trader-mediated procurement in Bangladesh's Dhaka-Tongi corridor. Large garment exporters now negotiate wax supply terms separately from chemical distributor bundles, compressing intermediary margins. This pattern is most visible in water-repellent finishing for North American outdoor brand programs where audit transparency requirements穿透 traditional supply tiers.
Textile Wax Market Segmentation
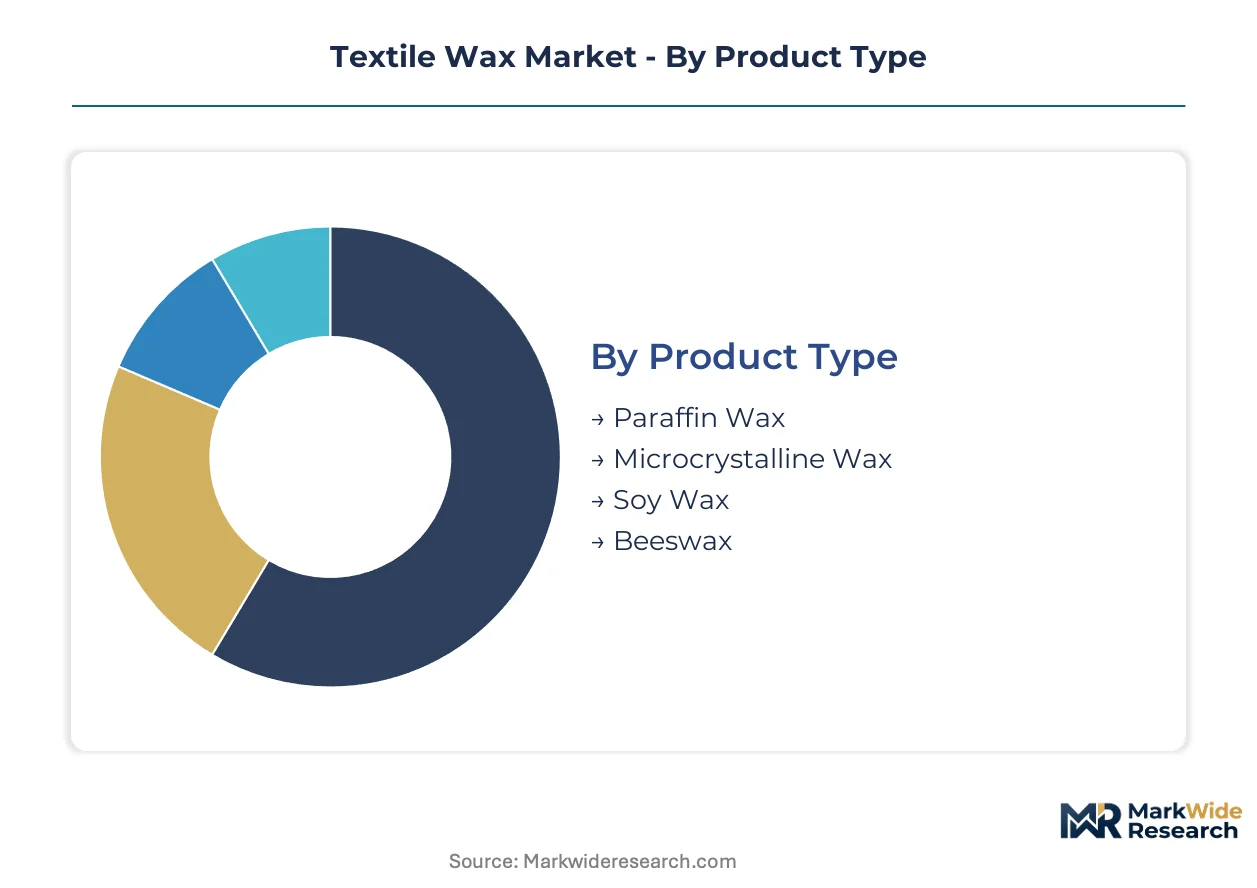
Textile wax procurement splits along regulatory compliance tiers and application performance requirements. Wax selection determines certification eligibility for export markets and finishing-line compatibility with water-repellent specifications.
Product Type:
REACH and EPA emission standards differentiate petroleum-derived grades from bio-based alternatives in procurement decisions.
- Paraffin Wax:Straight-chain alkanes refined from slack wax feedstock dominate commodity coating lines. Bangladeshi apparel exporters consume substantial volumes for cost-sensitive water-repellent finishing on performance outerwear bound for North American brands.
- Soy Wax:Triglyceride-based formulations from hydrogenated soybean oil capture sustainability-certified programs. German outdoor apparel manufacturers specify soy wax for EU Green Deal-compliant procurement where bio-based content thresholds apply.
- Microcrystalline Wax:Branched hydrocarbon structures from heavy residual oil fractions provide enhanced adhesion for home textile embellishment.
- Beeswax:Ester-rich secretions from Apis mellifera colonies serve organic-labeled artisanal segments in Turkey and Argentina.
Paraffin wax handles the majority of throughput; soy wax is gaining share fastest on sustainability certification requirements.
Application:
Functional performance requirements stratify demand across coating bath specifications and surface finish durability.
- Water Repellent:Fluorocarbon-free paraffin and polymer-wax hybrid formulations create durable water-repellent finishes. Vietnamese manufacturers expand coating capacity for alpine outerwear brands requiring hydrostatic head ratings above 10,000mm.
- Coating:Bulk wax applications provide yarn lubricity and fabric body in high-speed finishing lines. Indian home textile exporters in Tamil Nadu and Gujarat deploy paraffin coatings for quilted bedspread exports to European retailers.
- Finishing:Surface sheen and hand-feel modifications for fashion apparel.
- Embellishment:Artisanal wax-resist techniques and decorative surface treatments.
Water repellent applications absorb the largest coating volumes; coating is expanding most quickly on South Asian garment export growth.
End User:
Customer scale and certification sophistication determine wax grade selection and supplier relationship intensity.
- Apparel Manufacturers:Large garment exporters in Bangladesh's Dhaka-Tongi corridor negotiate direct wax supply contracts. Water-repellent finishing requirements from North American outdoor brands drive specification of hydrotreated paraffin grades with documented PAH compliance.
- Home Textiles:Quilted bedding and upholstery producers in India's Panipat cluster specify microcrystalline wax for enhanced stitch lubricity and fabric drape.
- Industrial Textiles:Filtration and geotextile fabric finishers.
- Automotive Textiles:Technical fabric producers for vehicle interior applications.
Apparel manufacturers represent the dominant demand concentration; home textiles show the steepest expansion trajectory on Indian export growth.
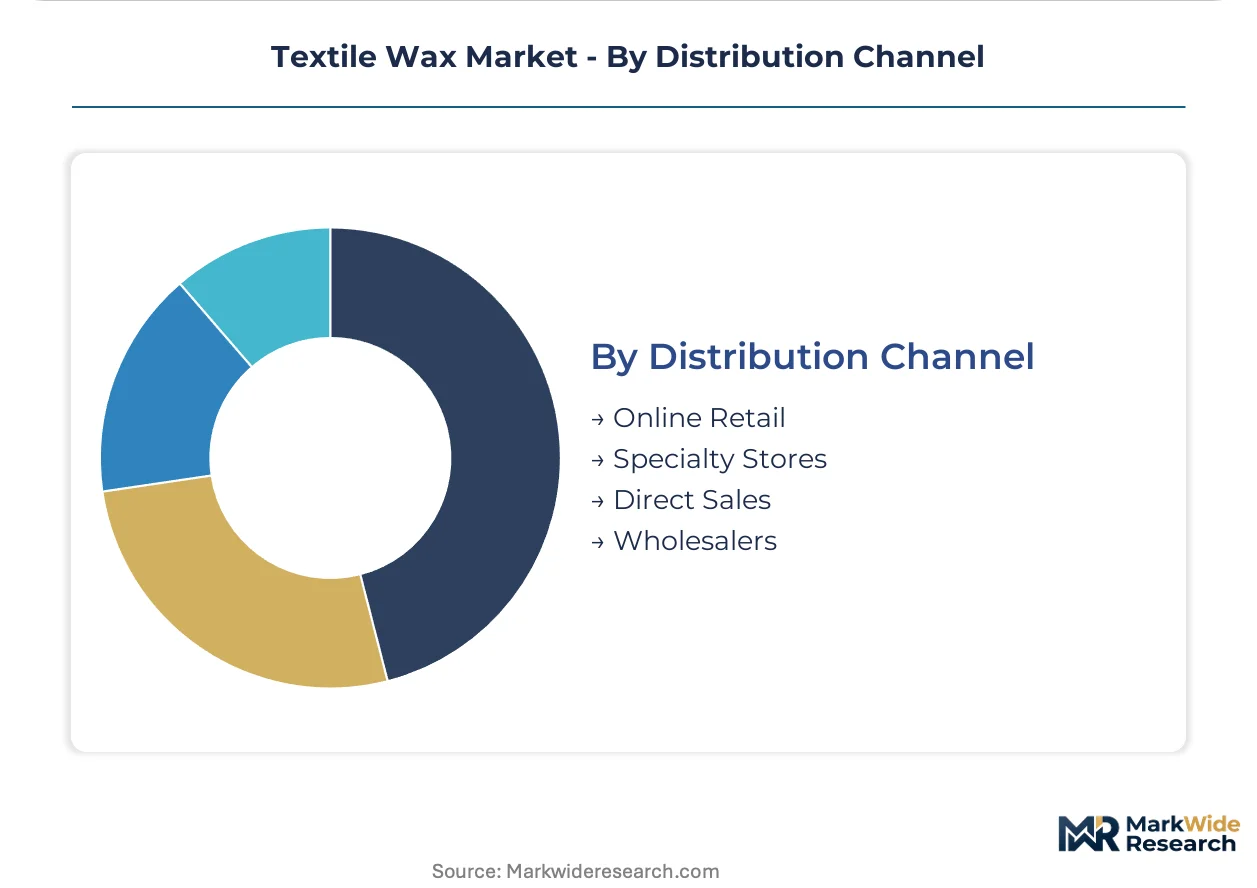
Distribution Channel:
Supply chain transparency requirements are restructuring procurement relationships between mills and wax suppliers.
- Direct Sales:Large coating houses in Vietnam and Bangladesh negotiate volume contracts with refiners and compounders. Audit transparency requirements from North American brands penetrate traditional distributor tiers.
- Wholesalers:Regional chemical distributors serve mid-scale finishers with bundled procurement across multiple textile chemicals.
- Online Retail:Small-lot specialty wax sourcing for artisanal and prototype applications.
- Specialty Stores:Local chemical supply outlets for immediate replenishment.
Direct sales capture the largest transaction volumes; wholesalers are losing share fastest to mill-brand contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH restrictions on polycyclic aromatic hydrocarbons anchor European procurement redirection, while South Asian garment-exporting clusters concentrate volume demand for water-repellent finishing. Bangladesh and Vietnam manufacturers expand wax-coated fabric output for performance outerwear. Indian home-textile exporters in Tamil Nadu and Gujarat drive coating demand for quilted bedding shipments.
Bangladesh
Apparel manufacturers in the Dhaka-Tongi corridor negotiate direct wax supply contracts with refiners, bypassing traditional chemical distributors. Water-repellent finishing requirements from North American outdoor brands specify hydrotreated paraffin grades with documented compliance. Large garment exporters now source wax separately from bundled chemical procurement, compressing intermediary margins.
Vietnam
Manufacturers expand coating capacity for alpine outerwear brands requiring hydrostatic head ratings above 10,000mm. Technical textile finishing for automotive and filtration applications remains below saturation, opening volume expansion corridors. Direct mill-brand contracting is displacing trader-mediated procurement in Ho Chi Minh City industrial zones.
Germany
Outdoor apparel manufacturers specify soy wax for EU Green Deal-compliant procurement where bio-based content thresholds apply. German coating houses absorb input cost premiums for certified-refined paraffin grades with hydrotreatment documentation. ECHA's REACH Annex XVII updates force textile wax importers to document batch-level compliance certificates.
India
Home textile exporters in Panipat and Karur deploy paraffin coatings for quilted bedspread exports to European retailers. BIS wax-quality standards for textile exports create certification friction for ungraded suppliers at export gates. Microcrystalline wax demand concentrates in Tamil Nadu for enhanced stitch lubricity and fabric drape.
United States
EPA oversight of petroleum-processing emissions shapes refinery compliance costs for hydrocarbon wax producers. American Wax, Inc. anchors North American supply through backward integration into petroleum-derived feedstock refining. The domestic market sources substantial paraffin volumes for commodity coating lines serving industrial textile finishers.
Textile Wax Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the textile wax market. Specialty compounders with polymer-wax hybrid R&D capabilities command premium positioning in European coating formulations, while volume-scale refiners compete on throughput in South Asian garment-exporting corridors. Three strategic archetypes dominate: integrated petroleum refiners with captive feedstock supply, bio-based formulation specialists capturing sustainability-certified programs, and regional compounders serving mid-scale finishing houses. Competitive moves concentrate on backward integration into feedstock refining and direct mill-brand contracting that displaces distributor intermediaries.
Within the integrated refiner archetype, American Wax, Inc. and The International Group, Inc. exemplify upstream control over petroleum-derived feedstock supply. BASF occupies a position among polymer-wax hybrid specialists, leveraging R&D capabilities for premium European coating formulations. MM INTERNATIONAL represents the volume-scale regional compounder model, competing across Indian home-textile export corridors with paraffin and microcrystalline wax offerings.
| Leading Market Players |
|---|
| Ghazi Trading Company |
| Roger A. Reed, Inc |
| MM INTERNATIONAL |
| BASF |
| The Seydel Companies, Inc |
| American Wax, Inc |
| CHEMAX MULTIKOTES (INDIA) PVT.LTD |
| The International Group, Inc. |
| Sri Amman Wax |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Bangladeshi garment exporters and Southeast Asian refiners lock in paraffin supply access while capping price volatility exposure for water-repellent finishing programs. These arrangements compress spot-market liquidity for commodity-grade wax as direct mill-brand contracting displaces trader intermediation.
Pricing Analysis
German coating houses absorb 12-18% input cost premiums over Southeast Asian benchmarks for hydrotreated paraffin grades with REACH-compliant PAH documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EU Green Deal-compliant bio-based formulations commanding the top tier. Cost compression in commodity paraffin is intensifying because Bangladeshi exporters negotiate direct refinery contracts that bypass distributor markups. Mid-scale Indian home-textile finishers show the highest price sensitivity, while German outdoor apparel brands prioritize certification compliance over unit economics.
Supply Chain Analysis
Inventory cycles stretch 8-14 weeks for beeswax sourced from Turkish and Argentine apiary regions, creating working capital pressure for organic-labeled home-textile programs. Feedstock supply concentrates in the United States, India, and Germany, with petroleum-derived slack wax drawing from Gulf Coast refineries and soybean oil feedstock anchored in Midwestern crushing facilities. Single-source vulnerability clusters in Turkish beeswax availability, where apiary concentration creates geographic concentration risk. Distribution runs through direct mill-brand contracts in Bangladesh and Vietnam, with regional chemical distributors retaining relevance only for mid-scale finishers lacking audit transparency capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile wax market is recovering from cyclical feedstock cost compression as crude oil volatility moderates and bio-based formulation scale economics improve. This cyclical upturn favors suppliers with backward integration and certification-ready product portfolios.
For Market Incumbents: Secure hydrotreatment capacity investments to preempt REACH Annex XVII compliance deadlines and lock in European coating house relationships before bio-based alternatives capture additional share. Deepen captive supply of petroleum-derived feedstock through refinery integration to defend margin position against spot-market volatility. Prioritize polymer-wax hybrid R&D to sustain premium positioning as single-bath finishing lines displace conventional coating baths. For New Entrants and Emerging Players: Differentiate on bio-based content certification to capture EU Green Deal procurement incentives and sustainability-certified apparel programs where incumbent petroleum refiners lack formulation flexibility. Target Vietnamese technical textile finishing for automotive and filtration applications, where coating capacity remains below saturation and direct mill-brand contracting patterns are less entrenched. Pursue joint development agreements with German outdoor apparel brands to establish reference accounts for alpine outerwear specifications. For Investors and Strategic Acquirers: Regional compounders with established BIS certification capabilities and relationships across Indian home-textile export corridors represent the most defensible acquisition profile for medium-term value creation. These targets offer exposure to Panipat and Karur cluster growth without the capital intensity of greenfield refinery investment. Watch for inflection in ECHA enforcement intensity around hydrotreatment documentation requirements as a signal for compliance-ready asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Refining | American Wax, Inc. anchors North American supply through captive petroleum-derived wax production. |
| Bio-based Formulation Scale-Up | Soy wax compounders capture EU Green Deal procurement incentives with sustainability-certified offerings. |
| Direct Mill-Brand Contracting | Bangladeshi garment exporters negotiate wax supply separately from chemical distributor bundles. |
| Polymer-Wax Hybrid R&D Investment | BASF leverages controlled crystallinity blends for single-bath finishing lines that cut water use. |
| REACH Compliance Certification | German coating houses absorb input cost premiums for hydrotreated paraffin with PAH documentation. |
Methodological Framework
A standing panel of textile finishing plant managers, garment exporter procurement leads, wax refinery technical directors, and chemical distributor account executives provided ongoing calibration across primary interview rounds. Secondary validation drew from customs and trade data, BIS export certification records, ECHA regulatory filings, and SEC 10-K disclosures from petroleum refining companies. Bottom-up volume estimates from coating line throughput assumptions were triangulated against top-down market size benchmarks derived from feedstock consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including wax grade tier, end-use application, certification requirement level, and regional production hub. CAGRs were derived from compound growth trajectory analysis applied to base-year sizing and terminal-year demand projections. Industry-specific forecast inputs incorporated REACH compliance deadline schedules and South Asian garment export order flow patterns.
Material uncertainties — crude oil price volatility, ECHA enforcement intensity, and bio-based wax scale-up economics — sit outside the modeled envelope and could revise trajectory assumptions. Forecasts reflect documented assumptions about regulatory implementation timing and substitution elasticity between petroleum-derived and natural-origin formulations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market