
 Mesh Fabric Market | 2026-2036
Mesh Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Mesh Fabric Market Intelligence
The divergence between high-performance technical textiles and mass-market commodity fabrics is rebalancing the mesh fabric market. This split separates materials engineered for specific industrial filtration or medical uses from general-purpose apparel and furnishing textiles. Sefar AG specializes in precision woven meshes for demanding industrial processes. W.L. Gore & Associates leverages its material science leadership in breathable, weather-resistant membranes integrated into performance sportswear.
Mesh fabric is a textile defined by its open, net-like structure, created through knitting, weaving, or nonwoven processes. Its primary function is to provide breathability, lightweight structure, and filtration, with performance often measured by its open area percentage. Polyester materials dominate the high-volume sportswear and footwear applications due to their cost-effectiveness and durability. In contrast, specialized nylon and other polymers command higher margins in the industrial filters segment where chemical resistance is critical.
Product standards and market access are shaped by a complex regulatory environment. The EU's REACH regulation governs chemical substances used in textile production, impacting material choices for European markets. In the United States, EPA standards for air and water quality influence the specifications for industrial filtration meshes. Consequently, manufacturers must navigate these divergent requirements to ensure compliance and marketability across different regions.
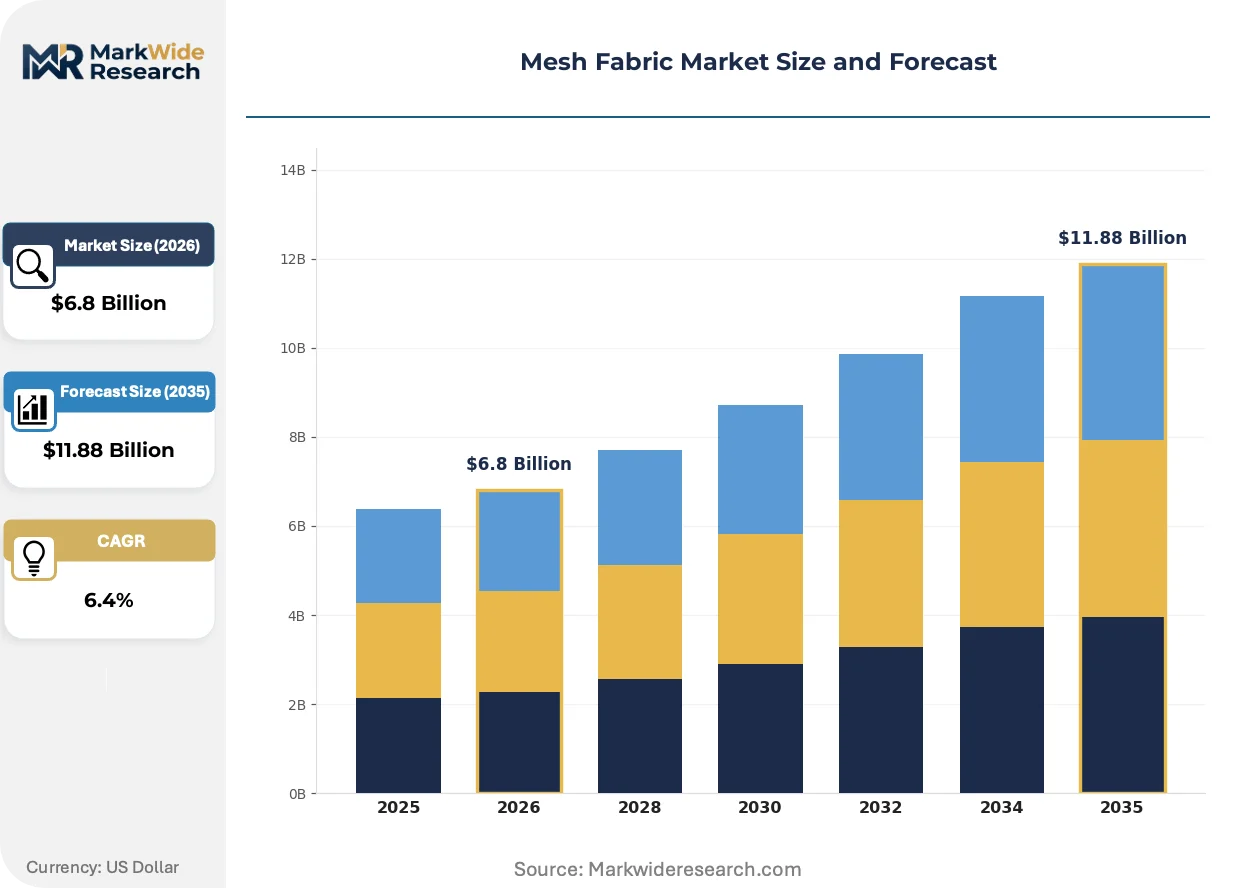
Market Dynamics
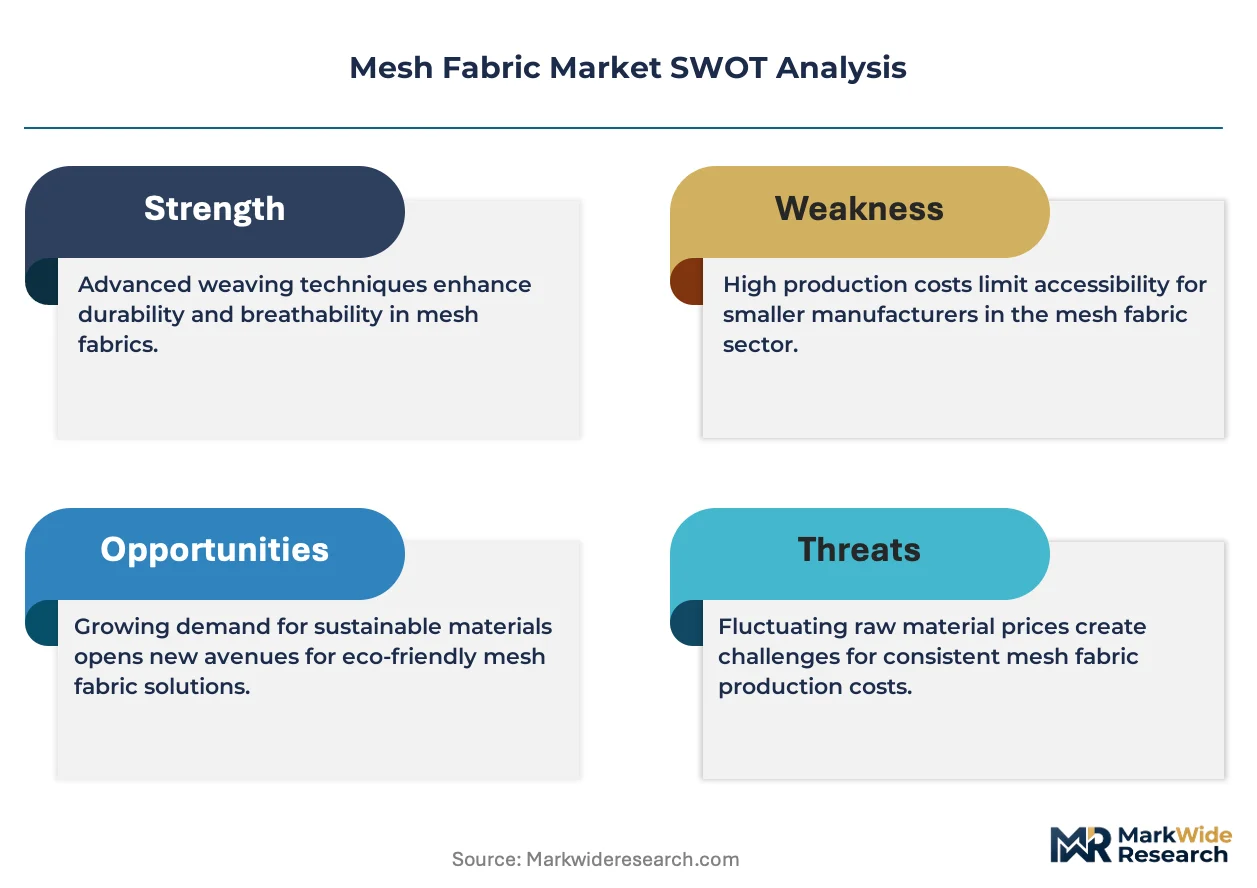
The primary structural force governing the mesh fabric market is the bifurcation between high-performance technical textiles and mass-market commodity fabrics. This split is driven by regulatory pressures, such as the EU's REACH standards, which influence material science innovation in specialized polymers.
Growth Catalysts
- Performance Sportswear Demand:Expansion of the sportswear and athleisure segments, particularly in China and India, creates consistent volume demand for polyester and nylon meshes used in footwear uppers and apparel panels.
- Industrial Filtration Standards:Stricter air and water quality regulations from bodies like the United States EPA propel demand for precision-engineered meshes in industrial processes, including liquid-solid separation and emissions control.
- Recycled Material Innovation:Corporate sustainability mandates and consumer preference are accelerating the development and adoption of meshes made from recycled polymers, opening new sourcing pathways and product categories.
Market Restraints
- Petrochemical Price Volatility:The cost structure for dominant materials like polyester and nylon is directly linked to volatile crude oil and natural gas feedstock prices, creating margin pressure for manufacturers.
- Substitution from Nonwovens:In lower-performance applications like disposable filters or packaging, cheaper spun-bond and melt-blown nonwoven fabrics can substitute for knitted or woven mesh, capping market potential.
- Technical Performance Ceilings:Certain applications in aerospace and advanced medical devices require material properties that exceed the current capabilities of textile-based meshes, limiting penetration into ultra-high-performance sectors.
Strategic Opportunities
- Medical and Healthcare Textiles:The development of biocompatible and antimicrobial meshes for hernia repair, wound care, and tissue engineering presents a high-margin opportunity for specialized producers.
- Geotextile Applications:Growing infrastructure investment in regions like Southeast Asia and Africa creates demand for durable mesh fabrics in soil stabilization, erosion control, and drainage systems.
- Smart Textile Integration:Incorporating conductive fibers into mesh structures to create flexible sensors for apparel or industrial monitoring opens a new frontier for value-added products.
Industry Challenges
- Regulatory Divergence:Manufacturers must navigate conflicting chemical substance regulations, such as the EU's REACH and China's GB standards, which complicates global supply chain management and product compliance.
- Standardization Deficits:A lack of universally accepted standards for measuring key performance metrics like pore size distribution and airflow resistance creates ambiguity and complicates material specification for buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesh Fabric Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Nylon, Cotton, Spandex, Acrylic, Olefin Application: Sportswear, Footwear, Home Furnishings, Industrial Filters, Packaging, Outdoor Gear End User: Apparel Manufacturers, Footwear Companies, Furniture Producers, Industrial Plants, Package Suppliers Product Form: Warp Knit, Weft Knit, Woven, Nonwoven, Spacer Fabrics |
| Companies Covered | The Chemours Company, Sefar AG, Daikin Industries, TEIJIN FRONTIER, Taconic, W.L. Gore & Associates, DuPont de Nemours, Apex Mills, Fiberflon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesh Fabric Market Strategic Shifts & Innovations
Material circularity and advanced manufacturing processes are actively defining the competitive landscape. These shifts compel producers to invest in new capabilities, from recycled polymer processing to digital knitting technologies that enable mass customization and reduce waste.
Digital knitting technology allows for the creation of engineered mesh structures with variable density and porosity in a single process. Sportswear and automotive upholstery segments are adopting this technology to create components with tailored support, breathability, and aesthetic features. This innovation is consolidating production with manufacturers who possess advanced 3D knitting machinery and the software expertise to program complex designs.
The European Union's Ecodesign for Sustainable Products Regulation (ESPR) is a significant policy driver. It introduces requirements for durability, reusability, and recycled content, effectively designing waste out of the product lifecycle. The textile industry, a primary target of this regulation, is responding by redesigning mesh products and supply chains to comply with forthcoming Digital Product Passport mandates.
Consumer demand for product traceability is altering sourcing behavior. Brands are increasingly required to provide evidence of their supply chain's ethical and environmental credentials, moving beyond simple supplier declarations. This is most prominent in the direct-to-consumer apparel segment, where QR codes linking to supply chain data are becoming a key marketing and trust-building tool, especially in European and North American markets.
Mesh Fabric Market Segmentation
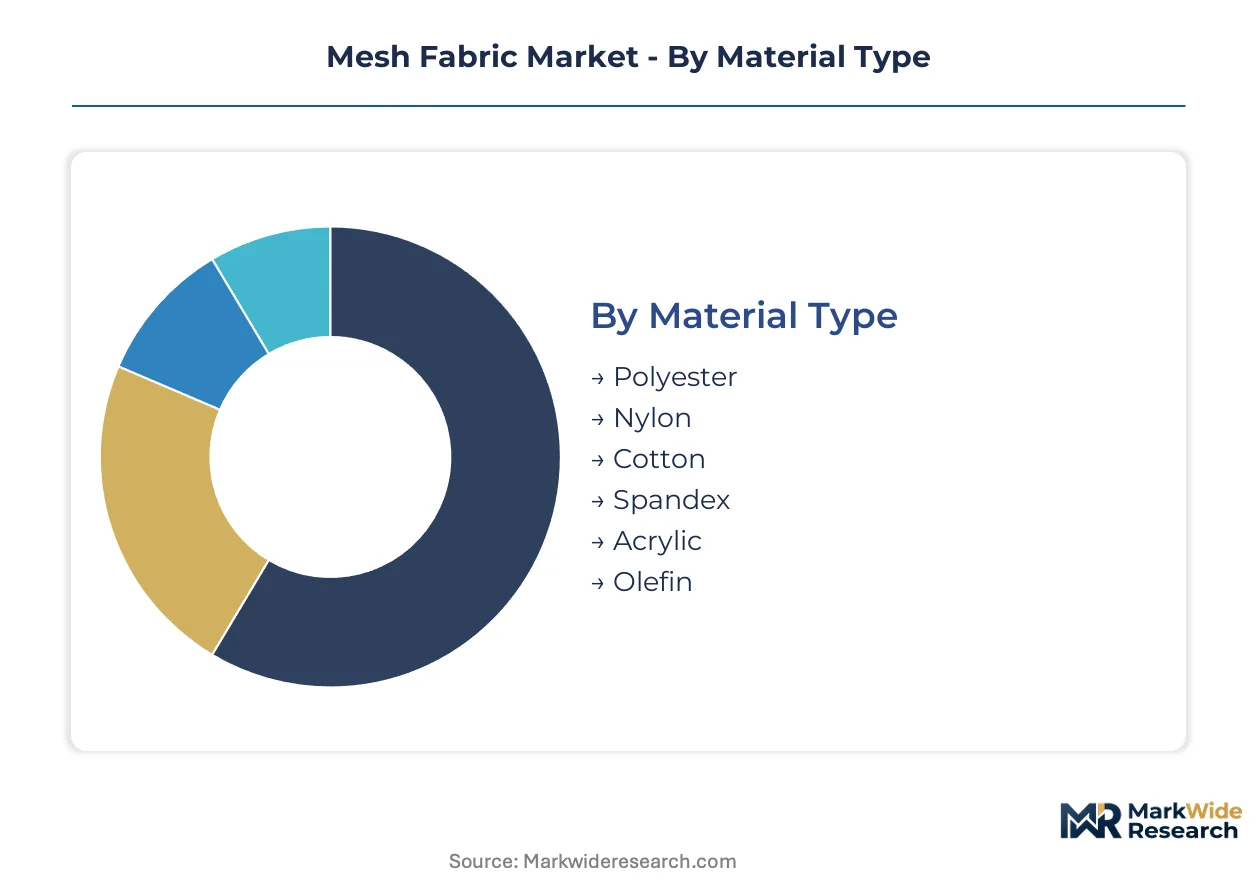
The mesh fabric market's segmentation highlights the diverse material science requirements and end-use applications driving demand. Understanding these distinct segments is crucial for manufacturers to align product development with specific performance needs and regulatory landscapes. This analysis differentiates between high-volume commodity fabrics and specialized technical textiles, reflecting varied market dynamics.
Material Type:
Buyers in this category differentiate based on the specific performance characteristics required for their end products.
- Polyester:This synthetic polymer offers cost-effectiveness, durability, and moisture-wicking properties, making it highly versatile. Demand concentrates in high-volume sportswear and footwear applications across China and India, driven by its balance of performance and affordability.
- Nylon:A strong, abrasion-resistant synthetic polyamide, nylon also provides excellent chemical resistance for demanding environments. Demand for nylon meshes is significant in industrial filters and specialized medical uses, where its robust properties command higher margins.
- Cotton:Natural fiber mesh offers softness and breathability, often used in apparel and home textiles.
- Spandex:Elastomeric fiber provides high stretch and recovery, essential for form-fitting sportswear and activewear.
- Acrylic:Synthetic fiber known for its wool-like feel and resistance to sunlight, applicable in outdoor textiles and furnishings.
- Olefin:Lightweight, moisture-resistant polymer mesh finds use in geotextiles and outdoor furniture.
Polyester leads volumes today; Nylon is gaining share fastest.
Application:
Application segments are defined by the functional purpose and environmental conditions the mesh fabric must withstand.
- Sportswear:This segment demands breathable, lightweight, and often moisture-wicking meshes for athletic apparel and athleisure wear. Demand concentrates in the expanding athleisure market across China and India, driven by consumer preference for comfort and performance.
- Industrial Filters:Precision-engineered meshes are required for separation, filtration, and emissions control in various industrial processes. Demand is strong in facilities adhering to stringent air and water quality regulations from the United States EPA and European environmental bodies.
- Footwear:Mesh provides breathability and structural support for shoe uppers, particularly in athletic and casual designs.
- Home Furnishings:Fabrics are used in upholstery, window treatments, and bedding for aesthetic and ventilation properties.
- Packaging:Lightweight mesh materials secure products or create breathable bags for produce and other goods.
- Outdoor Gear:Durable, weather-resistant meshes are crucial for tents, backpacks, and protective apparel.
Sportswear applications drive significant volume; industrial filtration exhibits the steepest expansion trajectory.
End User:
End-user segments reflect the distinct purchasing patterns and supply chain requirements of different manufacturing sectors.
- Apparel Manufacturers:These entities require diverse mesh types for breathability, stretch, and aesthetic appeal in their clothing lines. Demand concentrates within the global fashion industry, particularly from athleisure brands responding to rapid trend cycles.
- Industrial Plants:These facilities procure high-performance meshes for specific filtration, separation, and process control applications. Demand concentration includes chemical processing and wastewater treatment facilities in Germany and Japan, driven by operational efficiency and regulatory compliance.
- Footwear Companies:These enterprises procure mesh for shoe uppers and linings, prioritizing durability and ventilation.
- Furniture Producers:They integrate mesh into seating, outdoor furniture, and decorative elements for comfort and design.
- Package Suppliers:These companies utilize mesh for breathable packaging solutions, often for agricultural or consumer goods.
Apparel manufacturers generate the largest demand; industrial plants are climbing the fastest in specialized procurement.
Product Form:
Product form segmentation highlights the manufacturing techniques influencing mesh fabric properties and cost structures.
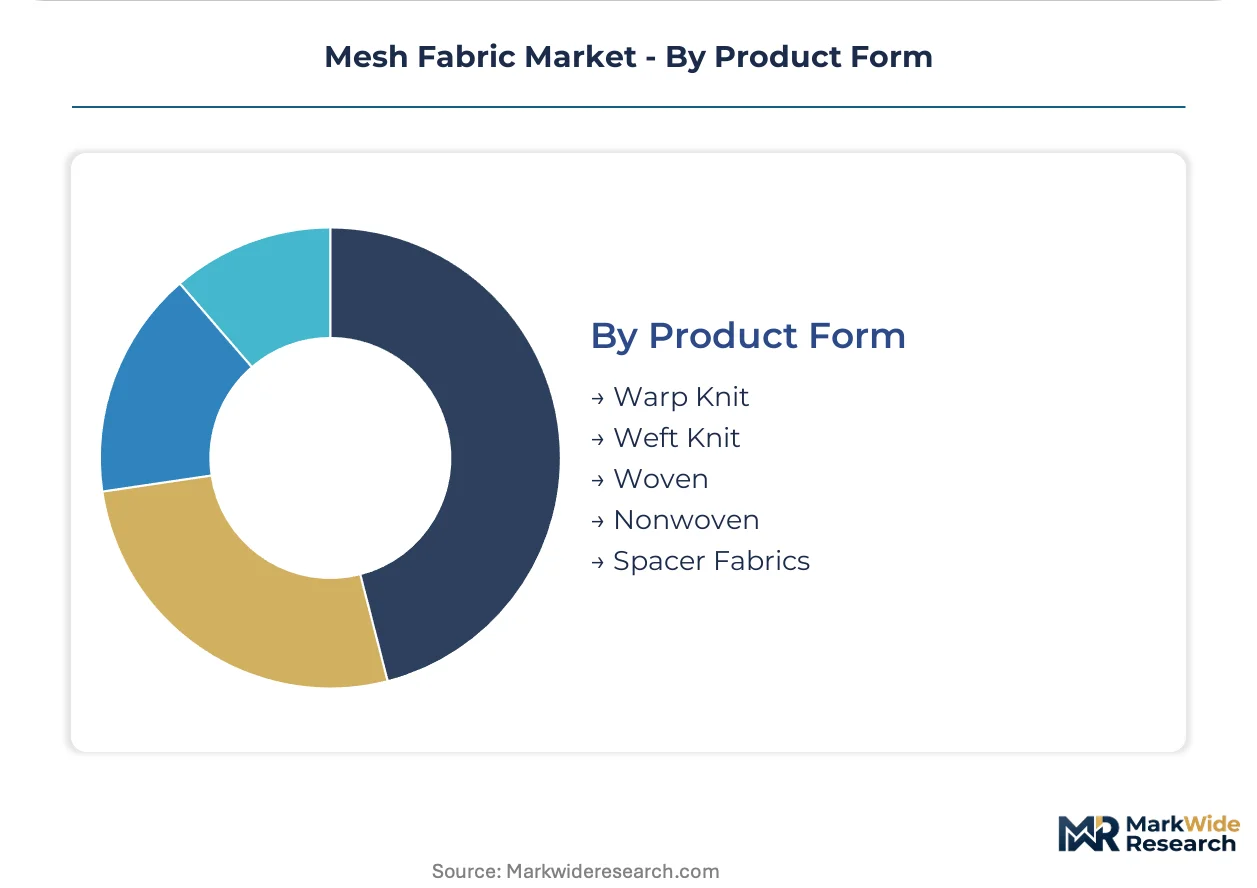
- Woven:This form involves interlaced yarns creating stable, strong mesh structures with precise open areas and high dimensional stability. Demand concentrates in industrial filtration and geotextile applications across Southeast Asia, driven by its tensile strength.
- Warp Knit:Loops are formed vertically, offering elasticity, drape, and often lighter weight compared to woven structures. Demand concentrates in performance sportswear and advanced medical textiles in Germany, valued for breathability and comfort.
- Weft Knit:This form creates stretchable, soft meshes, frequently used in apparel linings and casual wear.
- Nonwoven:Bonded fibers form a mesh-like structure, offering cost-effective solutions for disposable filters and packaging.
- Spacer Fabrics:Three-dimensional structures provide cushioning, breathability, and pressure distribution in footwear and medical devices.
Woven forms hold substantial market share; spacer fabrics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled manufacturing workforce and robust research infrastructure anchor regional mesh fabric markets. These regions often drive innovation in material science and advanced textile production. Demand for specialized mesh fabrics concentrates in areas with strong industrial bases and consumer markets.
China
Demand for mesh fabrics in China is substantial, fueled by its massive sportswear and footwear manufacturing sectors. The government's dual carbon goals promote sustainable textile production and recycled polymer use. Production hubs in the Yangtze River Delta actively integrate digital knitting technologies for mass customization.
United States
The United States market sees strong demand for industrial filtration meshes, driven by stringent EPA standards for air and water quality. Corporate sustainability mandates also accelerate the adoption of recycled content in textiles. Textile innovation clusters in North Carolina focus on developing high-performance technical meshes for diverse applications.
Germany
Germany's advanced manufacturing sector and focus on high-performance textiles create consistent demand for precision woven meshes. The EU's REACH regulation heavily influences material selection and chemical safety standards for textiles. Industrial centers in Bavaria specialize in warp knit fabrics for medical and automotive applications.
India
India's expanding athleisure market fuels significant volume demand for polyester and nylon meshes in sportswear. The country's PLI scheme encourages domestic textile manufacturing and value addition. Textile clusters in Gujarat and Tamil Nadu are rapidly expanding capacity for cost-effective mesh fabric production.
Japan
Precision engineering and advanced material science drive demand for specialized mesh fabrics in Japan, particularly for industrial filters. METI initiatives support research into smart textiles and functional materials. Manufacturing facilities in the Kansai region focus on developing innovative meshes for medical devices and aerospace.
Mesh Fabric Market Key Industry Players
Top-tier vendors anchor the high-performance technical textile segment, while mid-sized specialists and commodity producers compete in mass-market applications. The market structure bifurcates between precision engineering firms and high-volume textile manufacturers. Strategic archetypes include material science innovators, application-specific specialists, and cost-efficient volume producers. Capacity expansion and strategic partnerships are dominant competitive moves among mesh fabric manufacturers.
Among the material science innovators, Chemours Company and DuPont de Nemours exemplify firms leveraging advanced polymer expertise to develop specialized mesh fabrics for demanding industrial and medical applications. Sefar AG represents a precision engineering specialist, focusing on highly technical woven meshes for filtration and separation processes. W.L. Gore & Associates occupies a position as a leader in performance membranes, integrating breathable, weather-resistant materials into high-end sportswear and outdoor gear. These companies often anchor their competitive positioning in intellectual property and application-specific performance.
| Leading Market Players |
|---|
| The Chemours Company |
| Sefar AG |
| Daikin Industries |
| TEIJIN FRONTIER |
| Taconic |
| W.L. Gore & Associates |
| DuPont de Nemours |
| Apex Mills |
| Fiberflon |
| Others |
Cost & Logistics Intelligence
Vertical integration into advanced polymer production anchors supply positions for technical mesh manufacturers, influencing their pricing power in specialized industrial and medical applications.
Pricing Analysis
Bundled service offerings characterize high-performance mesh pricing, integrating material science expertise with application-specific engineering. The pricing model is predominantly contract-based long-term offtake for industrial filters. Price differentiation stems from certification levels, such as specific ISO standards, and customization requirements. Cost compression in commodity polyester meshes intensifies due to feedstock price volatility, making apparel manufacturers highly price-sensitive for general-purpose fabrics.
Supply Chain Analysis
Regional distribution centers facilitate the movement of mesh fabrics, particularly for high-volume apparel and footwear markets. Geographic supply concentration centers in China and India for mass-market textiles, while Germany and Japan specialize in technical meshes. Raw material dependencies include polyester, nylon polymers, and specialized chemical additives. Logistics chokepoints in global shipping lanes present a structural supply chain risk, with commodity fabrics distributing through large-scale textile distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a geographic-arbitrage play, leveraging lower production costs in Southeast Asia for high-volume fabrics against premium pricing for technical textiles in Europe.
For Market Incumbents:Anticipate increased regulatory scrutiny on chemical inputs, particularly from the EU's REACH standards, by investing in sustainable polymer R&D. Consolidate market share in technical textiles through strategic acquisitions of specialized manufacturers. A key threat emerges from cheaper nonwoven substitutes in lower-performance applications. Control over specialized polymer sourcing provides a significant lever against margin erosion.
For New Entrants and Emerging Players:Begin with targeted penetration into niche applications where existing performance ceilings limit incumbent offerings. The medical and healthcare textiles segment, especially for biocompatible meshes, presents a highly penetrable white space. Focus on developing specialized nylon meshes for demanding industrial filtration processes. A strong go-to-market angle involves offering traceable, recycled polymer solutions aligned with consumer sustainability preferences.
For Investors and Strategic Acquirers:Roll-up economics work for specialized technical textile producers because structural fragmentation across niche applications allows for consolidation gains. Long-term viability rests on manufacturers who can navigate complex regulatory environments and secure high-margin medical or industrial contracts. Acquisition targets should be mid-sized firms with proprietary material science or advanced digital knitting capabilities. The signal to watch is the increasing adoption rate of Digital Product Passports in European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polymer Processing Investment | Ensures compliance with Ecodesign for Sustainable Products Regulation and meets corporate sustainability mandates. |
| Digital Knitting Technology Adoption | Enables mass customization and reduces material waste in sportswear and automotive upholstery production. |
| Biocompatible Mesh R&D | Unlocks high-margin opportunities in medical and healthcare textiles for specialized producers. |
| Global Regulatory Compliance Office | Navigates divergent chemical safety standards, ensuring market access across regions like the EU and China. |
| Strategic Partnerships for Traceability | Builds consumer trust and meets brand requirements for ethical and environmental supply chain credentials. |
Research Approach
Direct dialogue with material scientists, procurement managers at apparel brands, industrial plant operators, and textile engineers grounds primary insights. Secondary validation draws from customs data, regulatory filings with the EPA and ECHA, and industry association reports. This approach integrates both bottom-up market intelligence and top-down macroeconomic analysis for comprehensive understanding.
Forecasted volume and value outputs across the analysis window establish the market trajectory. Segmentation dimensions modeled include material type, application, end user, product form, and regional regulatory frameworks. Compound annual growth rates derive from historical trends, projected technological advancements, and anticipated shifts in consumer demand. Key forecast inputs include petrochemical feedstock price projections and infrastructure investment trends.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or rapid shifts in global trade policies. Forecasts reflect assumptions regarding regulatory stability and sustained economic growth in key regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Silk Yarn Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Europe Cotton Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market
Yarn and Fabric Manufacturing
Canvas and Muslin Bags Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Fiberglass Fabric Market
Yarn and Fabric Manufacturing
Printed Textiles Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Knitted Fabric Market