
 Industrial Dyes Market | 2026-2036
Industrial Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Dyes Market Analysis
Color formulation as a subscription service is hardening into a standard commercial layer, with mills paying recurring fees for shade-matching databases and cloud-based color management. Archroma leverages its Color Atlas digital platform to lock in long-term textile mill relationships. Lanxess AG anchors its industrial dyes portfolio on leather and coatings specialization, competing away from commodity textile segments. Huntsman Corporation dominates reactive dye chemistry through sustained investment in low-salt, low-fixation formulations for water-stressed regions.
Industrial dyes are synthetic organic compounds engineered for substrate-specific affinity, typically formulated with chromophores (azo, anthraquinone, or phthalocyanine structures) and auxiliaries that control solubility, fastness, and migration behavior during exhaustion or padding processes. Their primary commercial purpose is to impart permanent coloration to textiles, leather, coatings, and plastics under specified light, wash, and rub-fastness standards. Reactive dyes command the largest value pool in textile applications because covalent fiber bonding delivers superior wash fastness on cellulosic substrates, while disperse dyes occupy the fastest-growing position through polyester expansion in sportswear and automotive interiors. Powder formulations sustain the highest volume share in bulk textile processing, though liquid dispersions are gaining ground in automated dosing systems where viscosity control and dust reduction carry operational premiums.
REACH in Europe and ZDHC MRSL guidelines constrain aromatic amine thresholds and heavy metal content, redirecting R&D budgets toward bio-based precursors and metal-free catalyst systems. India's Central Pollution Control Board enforces zero-liquid-discharge mandates on dye house clusters in Gujarat and Tamil Nadu, raising capital requirements for effluent treatment and membrane recovery systems. China's MEE has tightened wastewater discharge standards across the Yangtze River Economic Belt, compressing margins for smaller azo dye manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned certification investments.
Market Dynamics
Reactive dye chemistry is restructuring competitive advantage around water efficiency, as textile mills in water-stressed basins prioritize low-salt formulations that reduce effluent treatment burden and compliance cost.
Growth Catalysts
- REACH aromatic amine limits:European chemical safety rules are redirecting R&D spending toward bio-based chromophore synthesis and metal-free catalyst systems, opening substitution windows for compliant suppliers.
- Polyester sportswear expansion:Disperse dye demand is accelerating from performance apparel manufacturers seeking sublimation-compatible formulations for moisture-wicking fabrics.
- Gujarat chemical belt concentration:India's dye intermediate production clusters are capturing procurement gravity from South Asian textile mills through integrated naphthalene-to-dye supply chains.
Market Restraints
- Crude oil derivative volatility:Naphthalene and benzene feedstock costs swing with petrochemical refining margins, compressing formulation economics for azo and anthraquinone dye families.
- Single-basin supply risk:Concentrated intermediate production in Gujarat's chemical corridor creates geographic vulnerability to monsoon flooding and state-level environmental shutdowns.
- Natural dye substitution:Indigoid and flavonoid extracts from agricultural waste streams are penetrating premium organic cotton segments with lower regulatory compliance burdens.
Strategic Opportunities
- Zero-liquid-discharge mandates:India's Central Pollution Control Board enforcement in Tamil Nadu dye house clusters is creating equipment-and-chemistry bundled service contracts for effluent recovery.
- Cloud-based color matching:Subscription shade databases are displacing per-batch formulation fees, locking mill relationships through digital color management platform dependency.
- Automotive interior polyester:Disperse dye penetration into vehicle seating and trim is expanding beyond traditional textile applications as cabin customization demands multiply.
Industry Challenges
- Chromatographic analysis talent scarcity:Dye houses struggle to recruit spectrophotometrists capable of operating benchtop color measurement systems for shade-matching precision.
- Membrane recovery capex burden:Zero-liquid-discharge compliance requires reverse osmosis and nanofiltration installations that strain balance sheets of mid-scale dye processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Dyes Market |
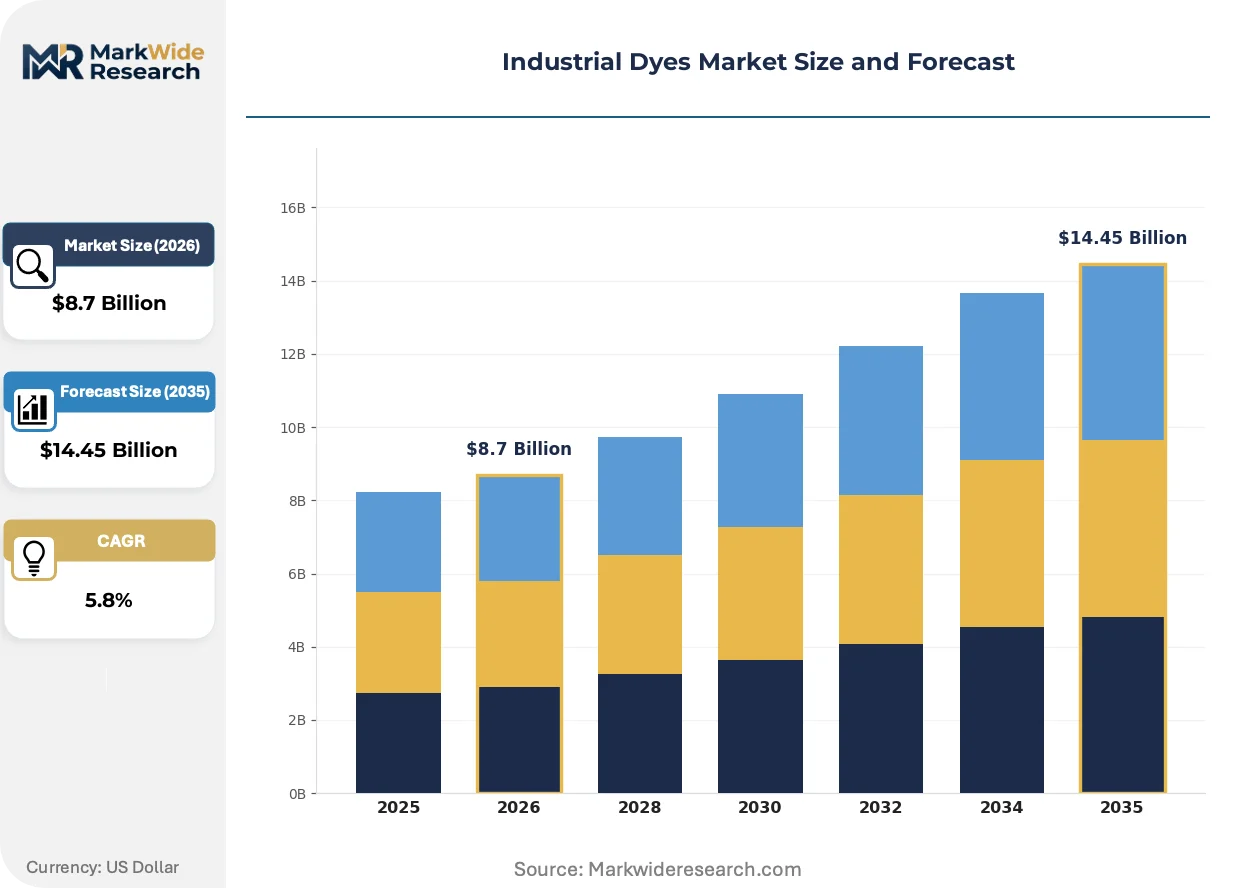
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Dyes, Basic Dyes, Reactive Dyes, Disperse Dyes Application: Textile, Leather, Coatings, Plastics End User: Textile Manufacturers, Leather Producers, Paint Manufacturers, Plastic Fabricators Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Archroma, Lanxess AG, BASF SE, Clariant AG, Huntsman Corporation, Atul Ltd., Kiri Industries Ltd., DIC Corporation, DyStar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Dyes Market Emerging Trajectories
Liquid dispersion formulations are capturing share from powder grades as automated dosing systems penetrate textile processing facilities, while regulatory chemistry restrictions and digital color management platforms simultaneously reshape product development priorities.
Digital color management platforms are overtaking traditional shade-matching workflows. Archroma's Color Atlas and comparable cloud databases now anchor mill procurement decisions through subscription access to formulation libraries. Large-scale dye houses in Bangladesh and Vietnam are adopting these systems fastest, compressing the market for independent color matching services and concentrating supplier influence with platform-owning chemical majors.
China's MEE wastewater discharge standards across the Yangtze River Economic Belt are forcing azo dye manufacturers toward closed-loop processing. The tightened COD and heavy metal limits have triggered facility consolidation, with smaller producers exiting rather than upgrading effluent infrastructure. Reactive dye output in Jiangsu and Zhejiang provinces is migrating toward integrated producers with captive treatment capacity.
Subscription color services are displacing per-batch formulation fees among South Asian textile mills. Mills now pay recurring access charges for shade databases rather than transaction-based color development costs, shifting supplier revenue toward predictable annuity streams. This model concentrates most rapidly in Tiruppur and Surat processing clusters where mill procurement functions have centralized under professional management.
Industrial Dyes Market Segmentation
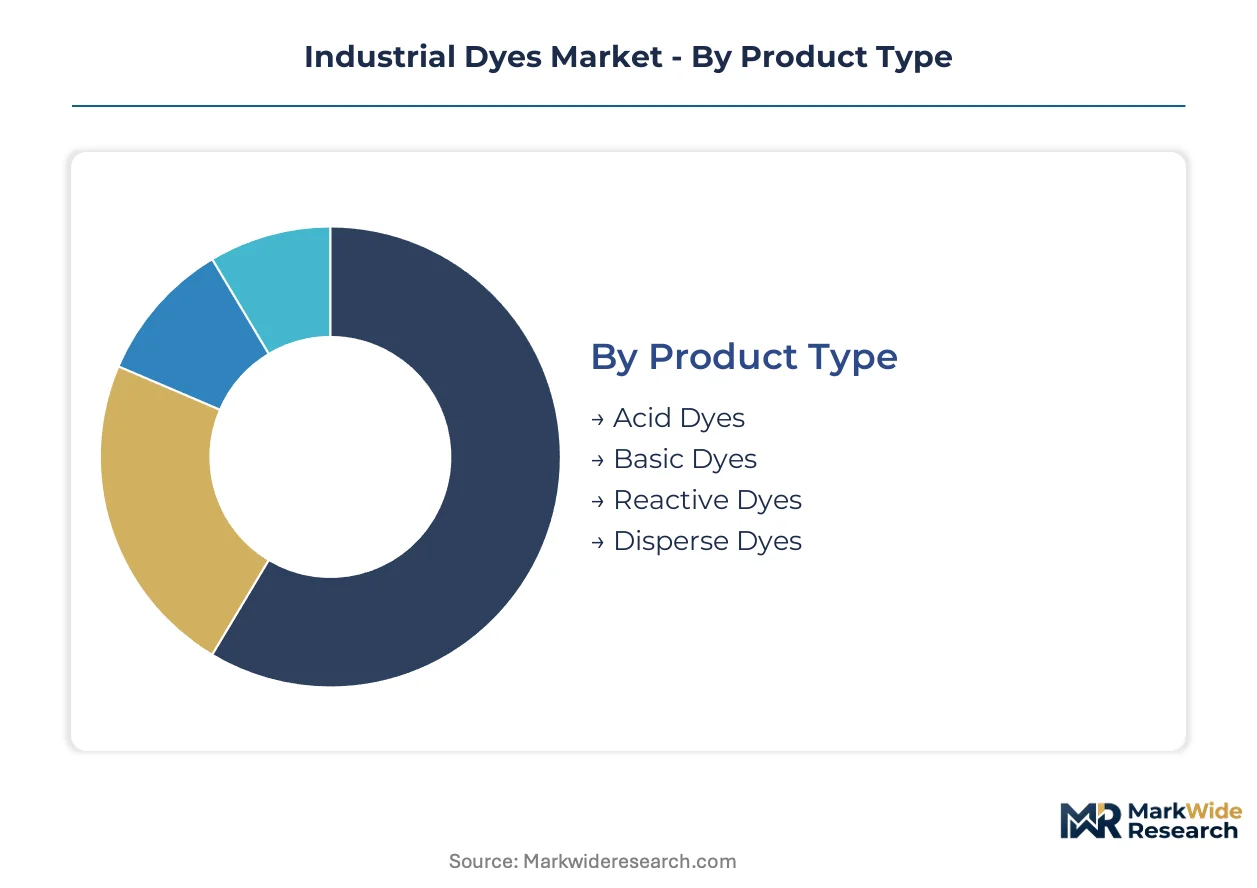
Industrial dye procurement decisions cascade through multiple technical and commercial dimensions. Substrate chemistry, application method, and regulatory compliance requirements each filter the viable formulation set differently. Understanding these segment boundaries clarifies where formulation premiums concentrate and where commodity competition dominates.
Product Type:
Volume concentration sits with reactive formulations, while premium capture gravitates toward specialized chemistries for synthetic fibers and leather.
- Reactive Dyes:Covalent bonding with cellulosic fibers delivers superior wash fastness through chlorotriazine or vinylsulfone anchor groups. Cotton processors in Bangladesh and Vietnam prioritize these formulations for export garment compliance with European retail standards. REACH aromatic amine limits are redirecting R&D toward bio-based chromophore precursors.
- Disperse Dyes:Non-ionic anthraquinone and azo structures sublimate into polyester fiber amorphous regions under heat and pressure. Sportswear manufacturers in South Korea and Taiwan drive demand for high-temperature stable variants compatible with recycled PET feedstocks. ZDHC MRSL compliance is tightening permissible heavy metal content in disperse dye carriers.
- Acid Dyes:Sulfonated azo and anthraquinone structures bond ionically to protonated wool and nylon fibers. Carpet mills in Turkey and Iran represent concentrated demand for metal-complex variants with enhanced light fastness.
- Basic Dyes:Cationic chromophores exhibit high tinctorial strength on acrylic and modified polyester substrates. Automotive interior fabric producers in Germany specify these for deep shade penetration in solution-dyed applications.
Mature deployment sits with reactive dyes on cotton substrates. Newer deployment is concentrated in disperse dye formulations for recycled polyester and technical sportswear.
Application:
Textile processing absorbs the majority of dye volume, though coatings and leather command formulation premiums through specialized fastness requirements.
- Textile:Exhaust, padding, and continuous dyeing of woven and knitted fabrics. Tiruppur and Surat processing clusters in India concentrate procurement gravity for cotton, polyester, and blended substrates.
- Leather:Anionic and metal-complex dyes penetrate collagen fiber structures through drum application. Italian tanneries in Arzignano and Santa Croce sull'Arno specify acid and direct dyes for automotive and luxury footwear grades.
- Coatings:Solvent-based and waterborne dispersions for architectural and industrial paint systems. German automotive OEMs drive demand for high-performance organic pigments with weathering resistance.
- Plastics:Masterbatch incorporation and solution coloring of engineering polymers. Japanese electronics housings manufacturers in Chiba and Osaka prefectures specify heat-stable formulations for ABS and polycarbonate.
Textile applications retain the deepest supplier relationships through integrated color management platforms. Coatings and plastics are expanding fastest through migration from inorganic pigment substitution.
End User:
Procurement sophistication divides between vertically integrated textile groups with captive dye houses and independent processors purchasing on specification.
- Textile Manufacturers:Integrated spinning-weaving-dyeing operations and commission processors. Bangladesh's woven garment exporters and Vietnam's knitwear specialists represent contrasting procurement scale profiles.
- Leather Producers:Tannery clusters processing hides through wet-blue to finished leather stages. Tamil Nadu's Vaniyambadi and Ranipet belts concentrate beamhouse and finishing operations with captive effluent treatment.
- Paint Manufacturers:Architectural and industrial coating formulators with in-house dispersion capabilities. AkzoNobel's European operations and Asian Paints' Indian facilities exemplify divergent regional specification standards.
- Plastic Fabricators:Injection molders and extruders incorporating color concentrates. German automotive tier suppliers and Chinese appliance manufacturers drive distinct performance certification requirements.
Textile manufacturers command the deepest formulation partnerships through recurring color service subscriptions. Plastic fabricators are adopting automated dosing fastest, shifting preference toward liquid dispersions.
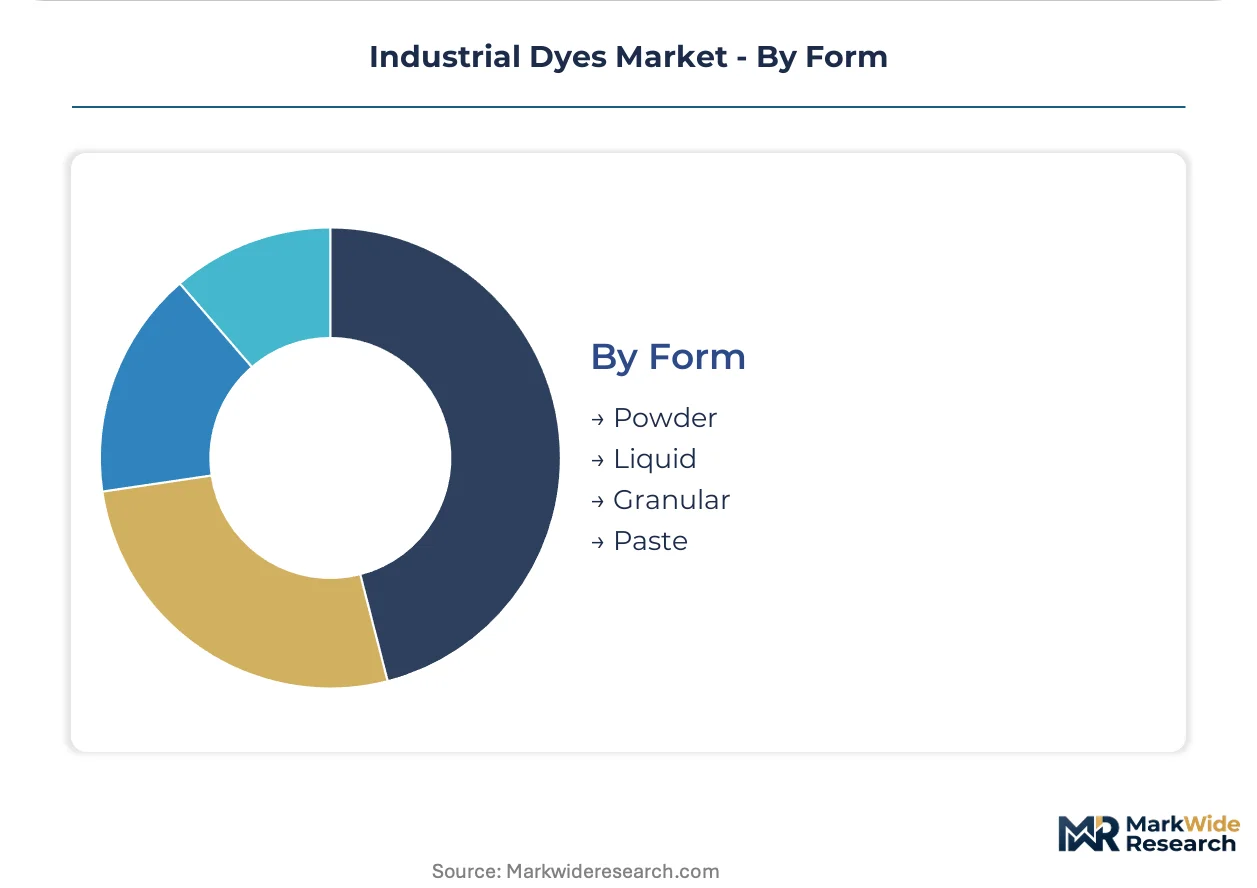
Form:
Powder formulations sustain volume leadership in bulk textile processing, while liquid and granular forms capture share through automation and dust control premiums.
- Powder:Spray-dried granules with standardized particle size distribution for dissolution in pad or exhaust baths. Bulk commodity textile processors in India and Pakistan favor powder for cost efficiency in manual handling environments.
- Liquid:Aqueous dispersions with controlled viscosity for automated dosing and reduced airborne exposure. European and North American dye houses specify liquid for closed-system transfer compliance with occupational exposure limits.
- Granular:Low-dust agglomerated forms for intermediate handling between powder and liquid. Japanese textile processors prefer granular for compatibility with existing dissolution equipment and reduced respiratory hazard.
- Paste:High-concentration aqueous or solvent-based preparations for direct incorporation into coating and printing systems. Screen printing operations in Turkey and Egypt specify paste for thickener compatibility and rheology control.
Powder forms dominate established cotton processing infrastructure. Liquid forms are penetrating fastest where ZDHC MRSL compliance and automated color kitchens coincide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of dye intermediates while India and Bangladesh consume the bulk of finished formulations. This production-consumption split shapes regional competitive dynamics and regulatory compliance strategies.
China
Jiangsu and Zhejiang provinces host concentrated azo and reactive dye manufacturing serving export markets. MEE wastewater discharge standards across the Yangtze River Economic Belt now mandate closed-loop processing, forcing smaller producers toward consolidation or exit.
India
Gujarat's chemical belt anchors naphthalene-to-dye supply chains feeding South Asian textile mills. Central Pollution Control Board zero-liquid-discharge mandates in Tamil Nadu dye house clusters are raising capital requirements for effluent recovery infrastructure.
Bangladesh
Woven garment exporters in Dhaka and Chittagong drive reactive dye procurement for European retail compliance. Mills here are adopting cloud-based color management platforms fastest among South Asian processors, shifting supplier relationships toward subscription models.
Germany
Automotive interior fabric producers specify basic dyes for solution-dyed polyester applications. REACH aromatic amine limits and ZDHC MRSL guidelines constrain formulation chemistry, redirecting R&D spending toward bio-based chromophore precursors and metal-free catalyst systems.
Vietnam
Knitwear specialists in Ho Chi Minh City and Hanoi processing zones concentrate disperse dye demand for polyester sportswear exports. Water stress in the Mekong Delta basin is prioritizing low-salt reactive formulations that reduce effluent treatment burden.
Industrial Dyes Market Vendor Landscape
Top-tier vendors anchor integrated color management platforms, while mid-scale specialists compete on formulation customization and regional compliance expertise. The vendor base stratifies across three tiers: multinational chemical majors with digital platform ecosystems, regional producers with captive intermediate supply, and niche specialists serving leather or coatings segments. Two strategic archetypes dominate competitive positioning: platform-owners locking mill relationships through subscription shade databases, and integrated manufacturers controlling naphthalene-to-dye supply chains. M&A activity concentrates on effluent treatment technology bundling, while capacity expansion targets low-salt reactive chemistry for water-stressed basins.
Within the platform-owner archetype, Archroma leverages its Color Atlas digital infrastructure to secure recurring revenue from textile mill subscriptions. Lanxess AG occupies a position anchored on leather and coatings specialization, competing away from commodity textile segments where price pressure intensifies. Huntsman Corporation exemplifies the integrated chemistry path, with sustained investment in low-salt, low-fixation formulations targeting water-stressed processing regions. These three Swiss, German, and US-based entities respectively represent the subscription-service, specialization-driven, and efficiency-optimized competitive vectors reshaping procurement relationships.
| Leading Market Players |
|---|
| Archroma |
| Lanxess AG |
| BASF SE |
| Clariant AG |
| Huntsman Corporation |
| Atul Ltd. |
| Kiri Industries Ltd. |
| DIC Corporation |
| DyStar Group |
| Others |
Supply Flow & Price Mechanics
Zero-liquid-discharge mandates from India's Central Pollution Control Board gate qualified supply for premium-tier pricing access, as dye houses lacking membrane recovery infrastructure face exclusion from European retail compliance chains while compliant processors command formulation premiums.
Pricing Analysis
Margin tightening in commodity reactive grades reflects naphthalene feedstock volatility and oversupply from Gujarat's chemical belt. Three-tier pricing structure across REACH-compliant premium, standard export-grade, and domestic economy levels separates certified suppliers from uncertified competitors. Price differentiation hinges on ZDHC MRSL certification status and volume scale commitments. Small-scale Tiruppur processors exhibit acute price sensitivity, while German automotive fabric producers prioritize fastness performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with China's Jiangsu and Zhejiang provinces for azo intermediate production, compounded by India's Gujarat corridor for naphthalene derivatives. Raw material dependencies center on benzene, naphthalene, and ethylene-based chromophore precursors. Tariff exposure looms from EU carbon border adjustments on imported dye formulations. Distribution runs through regional chemical distributors serving Tiruppur, Surat, and Bangladesh's Dhaka-Chittagong processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial dyes constitute a vertical-integration race where upstream control over naphthalene-to-dye supply chains and downstream capture of mill color management platforms determine margin sustainability.
For Market Incumbents: Anchor platform stickiness through deeper Color Atlas subscription penetration in Vietnamese knitwear clusters, while securing captive naphthalene supply from Gujarat's expanding intermediate capacity to defend against feedstock cost spikes. Counter natural dye substitution threats by accelerating bio-based chromophore R&D pipelines. For New Entrants and Emerging Players: REACH aromatic amine limits in Europe open a window for compliant bio-based formulation specialists to capture premium garment brand contracts. Target Tamil Nadu's zero-liquid-discharge retrofit wave with bundled effluent recovery-and-chemistry service models. Lead with ZDHC MRSL certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Consolidation of Jiangsu azo dye manufacturers below MEE wastewater thresholds is the leading indicator that integrated treatment-chemistry platforms will command scarcity premiums. Prioritize targets with captive membrane recovery infrastructure and established mill subscription revenue. Watch for India's Central Pollution Control Board extending zero-liquid-discharge mandates to Gujarat as the inflection signal for regional capacity shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthalene Intermediates | Gujarat chemical belt producers secure feedstock cost stability against petrochemical volatility. |
| Zero-Liquid-Discharge Compliance Bundling | Tamil Nadu dye houses lock in long-term chemistry contracts through captive effluent recovery. |
| Cloud-Based Color Management Platform Expansion | Bangladeshi woven garment exporters reduce shade-matching cycle times for European retail compliance. |
| Bio-Based Chromophore Synthesis Scale-Up | German automotive fabric suppliers meet REACH aromatic amine limits without performance trade-offs. |
| Low-Salt Reactive Formulation Capacity Addition | Vietnamese knitwear processors in Mekong Delta basins reduce effluent treatment burden. |
Methodological Framework
Independent corroboration across customs trade data, SEC 10-K filings from listed chemical majors, and European Chemicals Agency REACH registration databases underwrites the qualitative findings. Primary interviews with dye house plant managers, textile mill procurement leads, and distribution channel partners in India, Bangladesh, and Vietnam combined with secondary validation from Cefic sector reports and Indian Customs export records. Bottom-up volume estimates from regional processing cluster capacities triangulate against top-down value projections from disclosed segment revenues.
Comparable-period anchoring to historical production and trade flows across the analysis window informs the projection framework. Segmentation modeling spans dye chemistry family, substrate application, formulation form, and regional production hub. CAGRs derive from regression-adjusted growth rates applied to baseline volume and value estimates. Forecast inputs incorporate MEE wastewater enforcement timelines and ZDHC MRSL version updates as regulatory trajectory drivers.
Caveats apply where monsoon disruption to Gujarat's chemical corridor or abrupt REACH aromatic amine threshold revisions could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and polyester demand elasticity in sportswear applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market