
 Fiberglass Coated Fabric Market | 2026-2036
Fiberglass Coated Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Coated Fabric Market Analytics
The capital-intensity divergence between integrated fiber producers and downstream coating specialists is collapsing as raw material volatility squeezes mid-tier operators. Owens Corning leverages captive glass-melting capacity to anchor cost structures across North American supply chains. Saint-Gobain competes through its Performance Fabrics division, which controls specialized silicone-coating technology for aerospace thermal barriers. China Jushi Co., Ltd. dominates E-glass yarn supply, extending its position into coated fabric exports for marine and electrical applications.
Fiberglass coated fabric consists of woven or non-woven glass fiber substrates impregnated with polymers such as silicone, PVC, or polyurethane, typically rated for continuous service temperatures from minus 70°C to over 260°C depending on coating chemistry. These materials function primarily as thermal barriers, electrical insulators, and flame-resistant membranes in environments where organic textiles degrade. Fiberglass cloth commands the largest volume share across insulation and fire protection applications, while silicone-coated variants capture premium margin pools in aerospace and marine end uses. PVC-coated fiberglass tape maintains mature demand in construction flooring systems, whereas aluminum-coated film segments are gaining traction in electrical shielding as substrate thinness improves.
The EPA regulates VOC emissions from coating operations under Clean Air Act standards, compelling fabricators to shift toward water-based and low-solvent formulation technologies. REACH restrictions on phthalate plasticizers directly reshape PVC coating specifications for European export-bound production. China's GB standards for building fire safety, enforced by the Ministry of Emergency Management, mandate specific flame-spread ratings that elevate certified fiberglass fabric specifications in commercial construction. Stakeholders must monitor evolving coating chemistry compliance costs against the pace of substitution toward bio-based polymer alternatives.
Market Dynamics
Coating chemistry compliance costs are compressing mid-tier fabricators while integrated glass-melting operations capture margin through captive E-glass supply. The divergence between specialty silicone-coating capacity and commodity PVC operations is accelerating competitive stratification across aerospace, marine, and construction end uses.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH phthalate limits on PVC plasticizers are forcing reformulation investments that favor silicone-coated alternatives in European export markets.
- Aerospace thermal barrier procurement:Commercial aircraft OEMs are expanding specifications for silicone-impregnated fiberglass fabrics rated above 260°C continuous service.
- China infrastructure fire safety mandates:GB standards enforced by the Ministry of Emergency Management mandate certified flame-spread ratings in commercial construction.
Market Restraints
- Borosilicate and soda-lime glass input volatility:Energy-intensive melting operations face natural gas and electricity cost swings that transmit directly to substrate pricing.
- China Jushi E-glass yarn concentration:Downstream coaters remain exposed to single-source supply risk for high-tensile warp threads.
- Aramid and ceramic fiber substitution:Lightweight thermal barriers in aerospace are displacing fiberglass in weight-critical applications above 300°C.
Strategic Opportunities
- India electrical infrastructure buildout:Transmission grid expansion under CEA mandates creates demand for PVC-coated insulation tapes in substation and cable tray applications.
- Water-based coating technology convergence:EPA Clean Air Act compliance is driving solvent-to-aqueous formulation shifts that reduce VOC abatement capex.
- Direct OEM supply contracts:Bypassing distributor layers in marine and aerospace channels captures margin and specification control.
Industry Challenges
- Silicone polymer formulation chemistry expertise:Coatings engineers capable of balancing adhesion, flexibility, and thermal stability across cure profiles remain scarce.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and GB flame-resistance testing extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Coated Fabric Market |
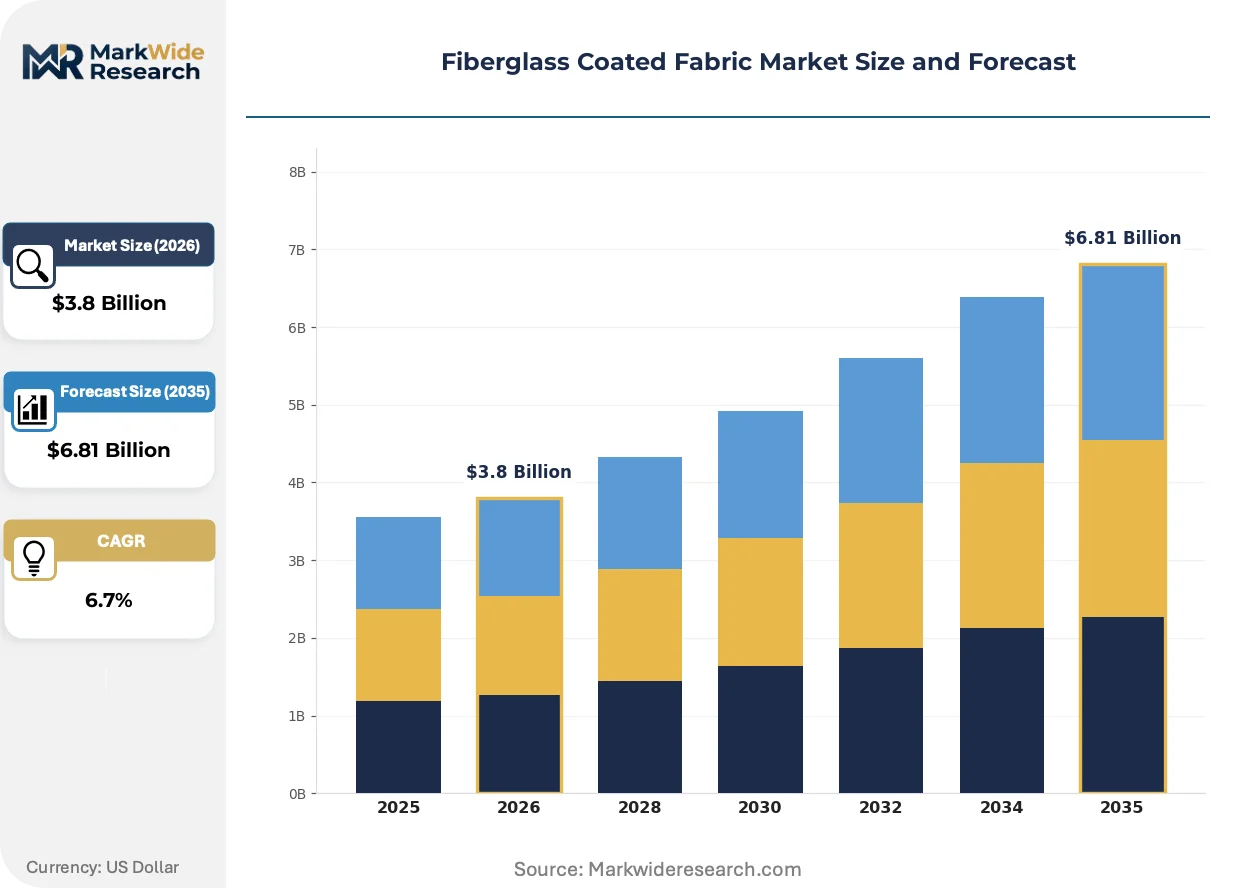
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass Cloth, Fiberglass Tape, Fiberglass Film, Fiberglass Mat Application: Insulation, Fire Protection, Industrial Flooring, Automotive End User: Aerospace, Construction, Marine, Electrical Coating Type: PVC, Silicone, Polyurethane, Aluminum |
| Companies Covered | Owens Corning, China Jushi Co., Ltd., Saint-Gobain, Johns Manville, Chongqing Polycomp International (CPIC), Hexcel Corporation, PPG Industries, Seaman Corporation, Saint-Gobain Performance Fabrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Coated Fabric Market Evolving Landscape
Coating substrate thinness is enabling new electrical shielding applications while regulatory pressure on solvent emissions accelerates aqueous formulation R&D. These forces are compressing traditional equipment depreciation cycles and rewiring procurement criteria toward certified thermal performance.
Aluminum-metallized fiberglass film is fragmenting the electrical shielding segment as substrate gauge drops below 50 microns. EV battery pack manufacturers are qualifying these laminates for electromagnetic interference containment at cell-to-pack scale. The technology is fragmenting established copper-foil supply relationships and compressing shielding material cost structures by 30-40 percent in high-volume programs.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from European-bound production by 2025. Fabricators are pivoting toward silicone and hybrid ceramic-polymer formulations that maintain hydrophobicity without PFAS chemistry. Marine and outdoor textile segments are absorbing the highest compliance costs as re-certification cycles compress.
Specification-driven procurement is consolidating buyer power among aerospace and automotive OEMs. Tier-2 fabricators face direct material qualification requirements that bypass traditional distributor relationships. Germany and Japan exhibit the tightest supplier consolidation as KBA and METI vehicle safety regulations mandate traceable coating chemistry documentation.
Fiberglass Coated Fabric Market Segmentation
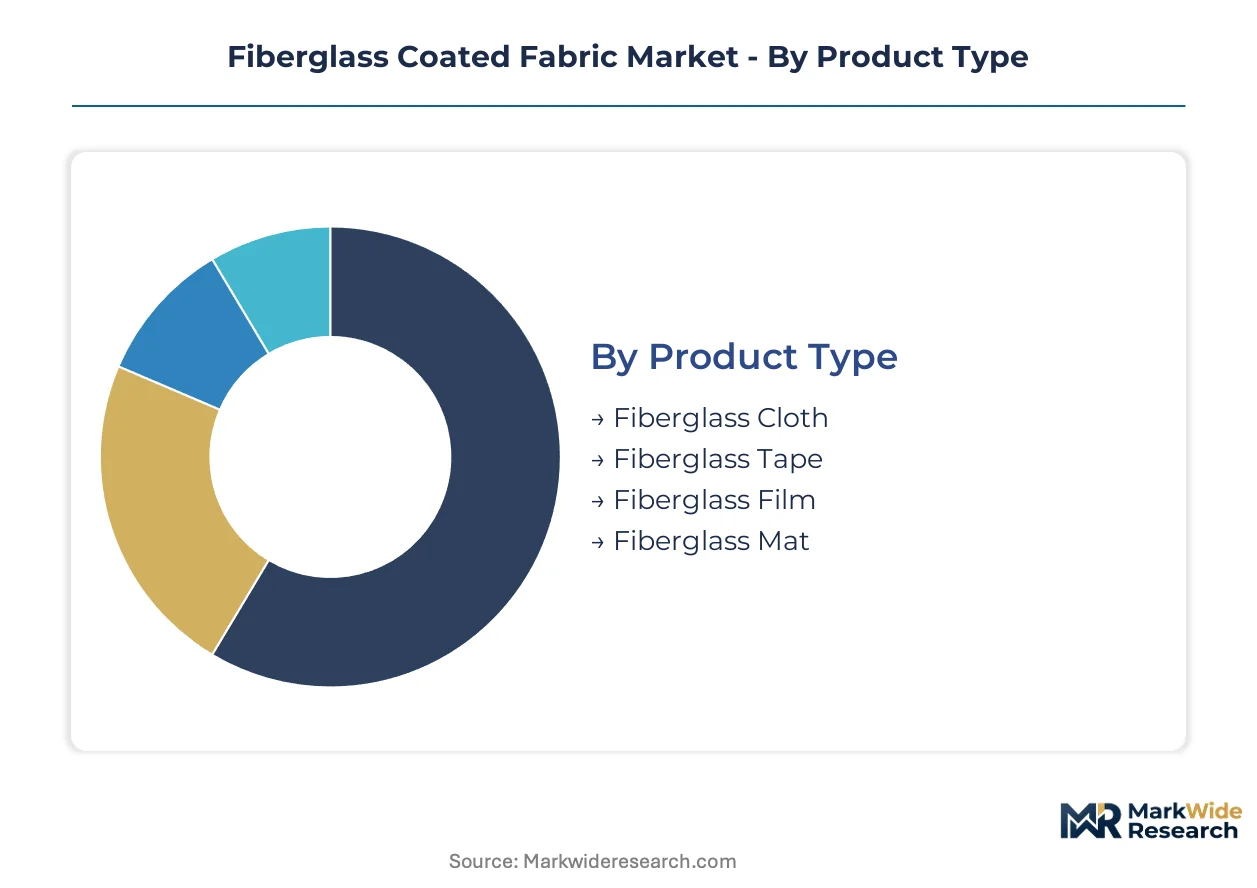
Segmentation in fiberglass coated fabric markets reveals how coating chemistry and substrate geometry determine substitution vulnerability across thermal management applications. Product form factor and coating polymer selection dictate whether segments defend against aramid, ceramic fiber, or metallized film alternatives.
Product Type:
Substitution pressure intensifies as substrate thickness decreases, with thin-gauge films facing the steepest displacement from aluminum-metallized alternatives in electrical shielding.
- Fiberglass Cloth:Woven E-glass or S-glass fiber construction in plain, twill, or satin weaves delivers the baseline mechanical strength for thermal insulation systems. Demand concentrates in construction fire barriers across China and India where GB and BIS standards mandate certified flame-spread ratings. The segment defends position through cost efficiency against aramid alternatives below 300°C service thresholds.
- Fiberglass Tape:Narrow-width woven or knitted strips, typically 25-100mm, serve cable wrapping and joint sealing in electrical infrastructure. Procurement from India's CEA-mandated transmission expansion drives volume, though PVC-coated variants face REACH phthalate reformulation costs in European export channels.
- Fiberglass Film:Calendered or cast thin-gauge substrates below 100 microns enable flexible thermal barriers and dielectric layers. EV battery pack manufacturers in Germany and Japan are qualifying these for cell-to-pack electromagnetic interference containment.
- Fiberglass Mat:Chopped-strand or continuous-filament non-woven structures provide bulk insulation and composite reinforcement. Marine applications in Nordic waters absorb volume for hull and deck thermal management where moisture resistance trumps weight constraints.
Fiberglass cloth anchors the volume base while fiberglass film gains share at the steepest rate.
Application:
Margin stratification follows temperature rating, with continuous service above 260°C commanding silicone-coating premiums against commodity PVC formulations.
- Insulation:Thermal barriers for industrial equipment, HVAC ductwork, and cryogenic systems span minus 70°C to over 260°C depending on coating selection. China's dual carbon goals accelerate industrial efficiency retrofits, pulling E-glass substrate demand through state-owned energy enterprises.
- Fire Protection:Passive fire containment membranes for commercial construction, tunnels, and transportation infrastructure. EU Green Deal chemical restrictions are forcing PFAS-free coating migrations that elevate silicone and ceramic-polymer hybrid costs.
- Industrial Flooring:PVC-coated fiberglass grids and sheets provide chemical-resistant walking surfaces in processing plants. Mature demand in US Gulf Coast petrochemical clusters faces limited growth as epoxy-concrete composites capture refurbishment cycles.
- Automotive:Heat shields, exhaust insulation, and battery thermal management for conventional and electric powertrains. KBA and METI traceability mandates in Germany and Japan are consolidating supplier qualification toward direct OEM contracts.
Insulation commands the widest installed base while automotive climbs fastest on electrification-driven thermal management requirements.
End User:
Certification complexity fragments the supplier base, with aerospace and marine segments demanding 12-18 month multi-jurisdiction approval cycles that exclude mid-tier coaters.
- Aerospace:Silicone-impregnated fabrics for engine nacelles, auxiliary power units, and cabin insulation must meet FAA and EASA flame-resistance specifications. OEMs in Toulouse, Hamburg, and Seattle are expanding procurement of 260°C-plus continuous service materials.
- Construction:Fire-rated membranes for curtain walls, atrium smoke barriers, and structural steel protection. China's Ministry of Emergency Management enforces GB standard compliance that elevates certified fabric specifications in commercial high-rise development.
- Marine:Engine room insulation, bulkhead fire barriers, and deck coverings for commercial and naval vessels. Nordic and Mediterranean shipyards face the steepest REACH PFAS transition costs as fluoropolymer coatings lose European market access.
- Electrical:Transformer insulation, cable wrapping, and substation fire barriers for grid infrastructure. India's Central Electricity Authority mandates drive PVC-coated tape demand in 400kV and 765kV transmission expansion projects.
Construction provides the deepest volume foundation while electrical expands most quickly on developing economy grid buildouts.
Coating Type:
Regulatory chemistry bans are collapsing the fluoropolymer segment while aqueous formulation R&D redistributes competitive advantage toward integrated polymer compounders.
- PVC:Phthalate-plasticized or bio-based plasticizer formulations deliver cost-efficient flexibility for construction and electrical tapes. REACH restrictions are forcing reformulation investments that compress margins for European-exporting fabricators.
- Silicone:Heat-cured polydimethylsiloxane coatings provide hydrophobicity, UV stability, and continuous service to 260°C-plus. Aerospace thermal barrier specifications in Germany, France, and the US concentrate demand among coating specialists with captive silicone compounding expertise.
- Polyurethane:Aliphatic and aromatic formulations balance abrasion resistance with moderate thermal limits for industrial flooring and marine textiles. Water-based technology convergence under EPA Clean Air Act standards is accelerating solvent-to-aqueous line conversions.
- Aluminum:Vacuum-metallized or laminated aluminum films enable electromagnetic interference shielding below 50 micron gauges. EV battery manufacturers in Japan and South Korea are displacing copper foil in high-volume cell-to-pack programs.
PVC retains the broadest volume footprint while aluminum demonstrates the steepest expansion trajectory on electrification shielding demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows favor integrated producers with captive glass-melting capacity, tilting regional advantage toward manufacturing clusters with energy cost discipline and coating chemistry expertise. Trade patterns concentrate in jurisdictions with aligned fire safety certification and polymer formulation capabilities.
China
Domestic construction and electrical infrastructure investment accelerates uptake of fire-rated fiberglass materials. GB standards enforced by the Ministry of Emergency Management mandate certified flame-spread ratings in commercial high-rise development. Jiangsu and Zhejiang provinces host downstream coating operations serving marine and electrical export channels.
United States
EPA Clean Air Act standards compel fabricators toward water-based and low-solvent formulation technologies. Aerospace manufacturers in Seattle and Wichita expand procurement of silicone-coated fabrics for thermal insulation barriers. Gulf Coast petrochemical clusters sustain mature demand for PVC-coated industrial flooring systems.
Germany
KBA vehicle safety regulations mandate traceable coating chemistry documentation for automotive thermal management applications. REACH phthalate limits on PVC plasticizers force reformulation investments favoring silicone-coated alternatives. Stuttgart and Hamburg anchor supplier qualification toward direct OEM contracts in aerospace and automotive channels.
India
Central Electricity Authority mandates drive PVC-coated tape demand in 400kV and 765kV transmission expansion projects. BIS certification requirements elevate fabric specifications for grid infrastructure fire barriers. Gujarat and Maharashtra concentrate electrical insulation manufacturing serving substation and cable tray applications.
Japan
METI regulations consolidate supplier qualification toward certified thermal performance documentation. EV battery pack manufacturers qualify aluminum-metallized fiberglass laminates for electromagnetic interference containment. Nagoya and Osaka industrial corridors displace copper foil in high-volume cell-to-pack programs.
Fiberglass Coated Fabric Market Competitive Landscape
Concentration sits with integrated glass-melting operations that anchor cost structures through captive E-glass supply. Mid-tier coating specialists face margin compression from raw material volatility and multi-jurisdiction certification timelines. Three archetypes dominate: captive fiber producers with downstream coating capabilities, specialized silicone-coating technology holders, and regional fabricators serving construction and electrical infrastructure. Capacity expansion and direct OEM supply contracting represent the dominant competitive moves as distributor layers face disintermediation.
Among integrated fiber producers, Owens Corning exemplifies the captive glass-melting archetype with North American supply chain anchoring. Saint-Gobain occupies a position within specialized coating technology for high-temperature applications. China Jushi Co., Ltd. represents the upstream concentration risk for downstream coaters dependent on high-tensile E-glass yarn supply. These three entities illustrate how vertical control over substrate production separates margin-stable operators from exposed mid-tier fabricators.
| Leading Market Players |
|---|
| Owens Corning |
| China Jushi Co., Ltd. |
| Saint-Gobain |
| Johns Manville |
| Chongqing Polycomp International (CPIC) |
| Hexcel Corporation |
| PPG Industries |
| Seaman Corporation |
| Saint-Gobain Performance Fabrics |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day E-glass yarn lead times concentrate pricing power with integrated melters possessing captive fiber supply, while spot-market coaters absorb volatility through inventory carrying costs that compress working-capital efficiency. This temporal asymmetry rewards backward integration into glass-melting operations and punishes mid-tier fabricators dependent on China Jushi spot purchases.
Pricing Analysis
Configured-to-order silicone-coated aerospace fabrics command premium spreads of forty to sixty percent above standard PVC construction tapes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL/CE flame-resistance tiers anchor aerospace premiums while commodity construction rolls compete on volume scale. Pricing pressure stems from REACH phthalate reformulation costs that squeeze PVC margins in European export channels. Electrical infrastructure buyers in India exhibit highest price sensitivity due to CEA-mandated procurement volumes, whereas aerospace OEMs in Toulouse and Seattle prioritize thermal performance over unit cost.
Supply Chain Analysis
The Yangtze River Delta port complex functions as the critical chokepoint through which seventy percent of global E-glass yarn transits before downstream coating. Supply concentrates in China, the United States, and Germany, with borosilicate batch ingredients drawing from soda ash deposits in Wyoming and natural gas feedstock from Gulf Coast petrochemical clusters. Single-source vulnerability sits with high-tensile warp thread supply from Jiangsu-based fiber operations. Distribution runs through direct OEM contracting in aerospace and marine channels, bypassing traditional distributor layers that once controlled specification access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as aramid and ceramic fiber alternatives displace fiberglass above three-hundred-degree service thresholds in weight-critical aerospace applications. Incumbents must navigate material science competition while preserving cost advantages below thermal crossover points.
For Market Incumbents: Compound silicone-coating formulation expertise through captive polymer compounding investments that lock in aerospace thermal barrier specifications. Acquire aqueous coating technology assets to preempt EPA Clean Air Act compliance costs. Backward integration into E-glass melting secures margin stability against China Jushi supply volatility.
For New Entrants and Emerging Players: Lead with aluminum-metallized film production for EV battery electromagnetic interference containment, targeting Japanese and South Korean cell-to-pack manufacturers. India's CEA-mandated transmission expansion offers penetrable white-space for PVC-coated tape qualification. Pursue direct utility contracting rather than distributor channel dependence.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because coating chemistry expertise scarcity and multi-jurisdiction certification barriers protect qualified supplier margins. Target mid-tier fabricators possessing UL/CE flame-resistance approvals but lacking captive fiber supply. Watch aluminum-metallized film adoption curves in German and Japanese EV battery programs as inflection signal for shielding segment displacement of copper foil.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into E-Glass Melting | Captive fiber supply anchors cost structures against China Jushi spot price volatility. |
| Aqueous Coating Technology Conversion | EPA Clean Air Act compliance reduces VOC abatement capital expenditure for fabricators. |
| Direct OEM Supply Contracting | Bypassing distributor layers captures margin and specification control in aerospace channels. |
| Multi-Jurisdiction Certification Investment | Simultaneous UL, CE, and GB flame-resistance testing accelerates product launch cycles. |
| Aluminum-Metallized Film Capacity Buildout | EV battery manufacturers in Japan and South Korea displace copper foil shielding materials. |
Research Methodology
Cross-validation between primary interviews with coating technology directors and secondary trade data anchors the qualitative findings on supply chain concentration. Plant managers at integrated glass-melting operations, procurement leads at aerospace OEMs, distribution channel partners serving electrical infrastructure, and technical R&D directors at polymer compounders provided operational perspective. Customs records, SEC filings from publicly traded fiber producers, ECHA REACH substance registrations, and GB standard enforcement disclosures supplied quantitative validation. Bottom-up segment sizing triangulates against top-down macroeconomic elasticity estimates.
Sensitivity analysis across coating chemistry substitution scenarios and raw material price bands tests forecast robustness throughout the projection horizon. Segmentation dimensions include product form factor, coating polymer type, end-use application, and regional regulatory cluster. CAGRs derive from elasticity-weighted demand modeling across construction, aerospace, automotive, and electrical infrastructure verticals. E-glass yarn pricing volatility and REACH compliance cost trajectories function as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment in China and India or accelerated aramid fiber cost reduction would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and coating technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market