
 Tendon Repair Market | 2026-2036
Tendon Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Tendon Repair Market Intelligence
Specialty clinics and ambulatory surgical centers are redrawing procurement patterns in tendon repair, pulling volume away from traditional hospital inpatient settings as minimally invasive techniques mature. Stryker leverages its integrated sports medicine portfolio to control channel access across arthroscopic delivery modes. Arthrex, Inc. anchors its position through relentless R&D intensity in suture anchor design and surgeon training infrastructure. Zimmer Biomet competes by extending its orthopedic footprint into biodegradable polymer-based fixation devices.
Tendon repair encompasses the surgical restoration of torn or degenerated tendons through mechanical fixation, biologic augmentation, or tissue reconstruction using implants with tensile strengths exceeding native tendon properties. Suture-based repair remains the dominant product category due to its versatility across anatomical sites and cost accessibility, though scaffold segments are capturing margin pools as biologic adoption advances. Arthroscopic surgery leads delivery mode preference because it reduces perioperative morbidity and accelerates rehabilitation timelines, while percutaneous techniques are gaining traction in Achilles and rotator cuff procedures where tissue preservation matters most.
The FDA regulates tendon repair devices as Class II medical products requiring 510(k) clearance, while the EU Medical Device Regulation imposes stricter clinical evidence standards for biologic scaffolds entering European markets. ISO 13485 certification shapes manufacturer quality systems and determines supplier eligibility for hospital procurement contracts across multiple geographies. Stakeholders must monitor how evolving biologics classification pathways in the United States and Europe will reshape competitive access and reimbursement for next-generation tendon augmentation products.
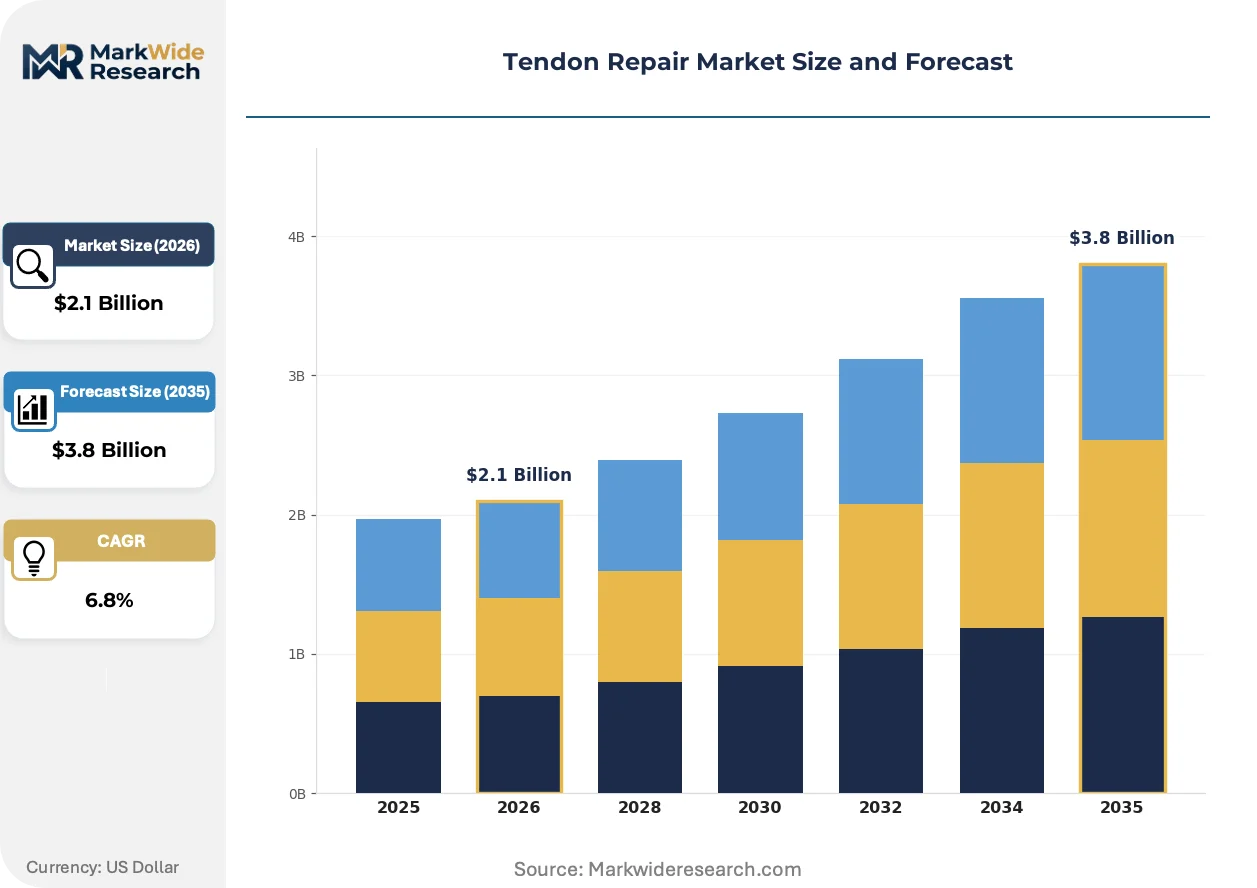
Market Dynamics
The migration of tendon repair procedures from inpatient to ambulatory settings is compressing device procurement cycles and forcing manufacturers to reconfigure distribution networks around same-day discharge protocols.
Growth Catalysts
- Ambulatory Surgery Center Expansion:CMS reimbursement policies in the United States now cover arthroscopic rotator cuff repairs in outpatient settings, accelerating procedural volume shifts away from hospital campuses.
- Biologic Scaffold Innovation:Collagen-based augmentation matrices are penetrating rotator cuff and Achilles repair protocols as surgeons seek improved healing rates in degenerative tissue.
- Aging Athlete Demographics:Recreational sports participation among adults over 50 in the United States sustains demand for minimally invasive tendon restoration procedures.
Market Restraints
- Biologic Material Cost Volatility:Purified collagen and decellularized tissue inputs face pricing pressure from limited donor tissue availability and complex processing requirements.
- European Regulatory Friction:The EU Medical Device Regulation imposes extended clinical evidence timelines for biologic scaffolds, delaying market entry relative to 510(k) pathways.
- Suture Anchor Commoditization:Metal and PEEK-based fixation devices face margin compression from low-cost polymer alternatives manufactured in India and China.
Strategic Opportunities
- Percutaneous Technique Adoption:Ultrasound-guided minimally invasive approaches in Achilles repair create white space for specialized instrumentation and training ecosystems.
- Workers' Compensation Channel Penetration:Employer-funded occupational injury protocols in the United States represent an underpenetrated procurement channel distinct from traditional hospital contracting.
- Resorbable Polymer Innovation:Magnesium and polylactic acid-based fixation devices align with FDA priorities for implantable device biocompatibility and reduced revision surgery rates.
Industry Challenges
- Arthroscopic Skill Pipeline Constraints:Fellowship-trained sports medicine surgeons remain concentrated in metropolitan academic centers, limiting procedure accessibility in secondary markets.
- ISO 13485 Certification Timelines:Quality system implementation for biologic-device combination products extends supplier qualification periods beyond traditional mechanical implant categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tendon Repair Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Anchors, Grafts, Scaffolds Delivery Mode: Open Surgery, Arthroscopic Surgery, Percutaneous Surgery, Endoscopic Surgery End User: Hospitals, Specialty Clinics, Surgical Centers, Rehabilitation Facilities Material: Biodegradable Polymers, Metal, Biological Tissues, Synthetic Fibers |
| Companies Covered | Stryker, Arthrex, Inc., CONMED Corporation, Integra LifeSciences, Smith+Nephew, DePuy Synthes, Inc., Zimmer Biomet, MiMedx, TendoMend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tendon Repair Market Strategic Shifts & Innovations
Biologic augmentation and point-of-care tissue processing are converging to redefine standard-of-care protocols across sports medicine and orthopedic trauma segments.
Knotless suture anchor systems are displacing traditional knotted fixation in rotator cuff repairs. Ambulatory surgical centers in the United States are adopting these devices at accelerated rates due to reduced operative time and elimination of knot-tying technical failure modes. This transition is compressing revenue per procedure for conventional anchor manufacturers while expanding addressable volume.
REACH chemical registration requirements in Europe are reshaping raw material sourcing for polymer-based implants. Manufacturers must now document full supply chain substance compliance for PEEK and resorbable polymers used in suture anchors and interference screws. Biodegradable fixation segments face the steepest compliance cost increases as they rely on complex polymer formulations.
Surgeon-owned distributorships are fragmenting procurement authority in the United States. Hospital supply chain managers now negotiate alongside physician investors who control case volume routing to preferred vendors. This bifurcation is most pronounced in Texas and Florida markets where ambulatory center joint ventures concentrate decision-making power outside traditional materials management departments.
Tendon Repair Market Segmentation
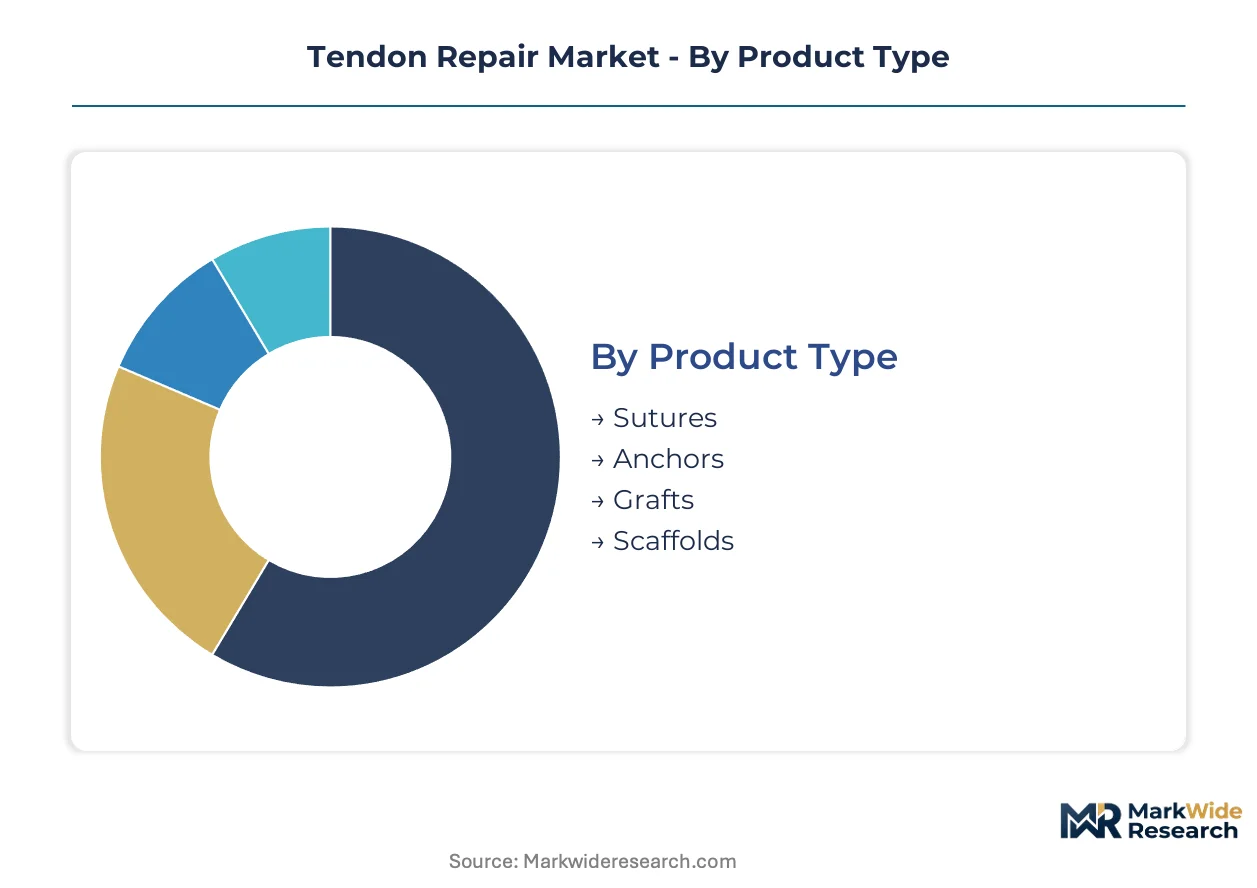
Tendon repair manufacturers configure product portfolios around distinct clinical workflows and procurement hierarchies. Segment boundaries determine pricing power, regulatory pathways, and channel access across hospital and ambulatory settings.
Product Type:
Sutures and anchors generate concentrated domestic demand from United States hospital systems, while grafts and scaffolds depend on export-led biologics supply chains from European and Asian tissue processors.
- Sutures:Braided polyester, polyethylene, and high-strength suture materials provide mechanical fixation across rotator cuff, Achilles, and hand tendon repairs. United States ambulatory surgical centers are standardizing on knotless braided configurations to reduce operative time and technical failure modes in high-volume settings.
- Anchors:Metal, PEEK, and biocomposite fixation devices secure suture-to-bone interfaces in arthroscopic procedures. United States metropolitan academic centers drive specification authority for next-generation knotless systems, though price compression from polymer alternatives manufactured in India and China is eroding margin pools in standard anchor categories.
- Grafts:Allograft and autograft tissue replacements address massive rotator cuff tears and chronic tendon degeneration.
- Scaffolds:Collagen-based augmentation matrices and synthetic ECM substitutes support biologic healing in compromised tissue beds.
Sutures command the established base. The steepest expansion runs through scaffolds.
Delivery Mode:
Cost tier stratification separates capital-intensive arthroscopic platforms from lower-infrastructure open and percutaneous alternatives.
- Open Surgery:Traditional tendon repair through full surgical exposure remains necessary for complex revision cases and massive tears requiring extensive mobilization. United States workers' compensation channels sustain procedural volume for open techniques in occupational hand and flexor tendon injuries where tissue quality demands direct visualization.
- Arthroscopic Surgery:Minimally invasive joint access through fiberoptic visualization systems dominates rotator cuff and hip labral repairs. United States CMS reimbursement expansion into outpatient settings is accelerating capital equipment placement in ambulatory surgical centers, compressing hospital inpatient volumes.
- Percutaneous Surgery:Ultrasound-guided minimally invasive approaches reduce soft tissue disruption in Achilles and selected rotator cuff repairs.
- Endoscopic Surgery:Specialized visualization systems address carpal tunnel and peripheral tendon pathologies outside major joints.
Open surgery retains the trauma and revision base. Arthroscopic surgery is climbing the fastest through outpatient channel migration.
End User:
Customer type determines procurement authority concentration versus fragmentation across integrated delivery networks and physician-owned ventures.
- Hospitals:Academic medical centers and community hospital systems maintain bulk purchasing leverage through centralized materials management. United States health system consolidation is narrowing vendor panels to integrated sports medicine portfolios that span implants, instruments, and capital equipment.
- Specialty Clinics:Orthopedic and sports medicine-focused outpatient facilities concentrate high-volume tendon repair expertise outside hospital campuses. United States metropolitan markets in Texas and Florida exhibit pronounced surgeon-owned distributorship influence over vendor selection.
- Surgical Centers:Ambulatory facilities optimized for same-day discharge protocols.
- Rehabilitation Facilities:Post-acute settings managing non-operative and post-surgical tendon recovery protocols.
Hospitals retain the high-complexity case base. Specialty clinics are gaining share fastest through physician ownership structures.
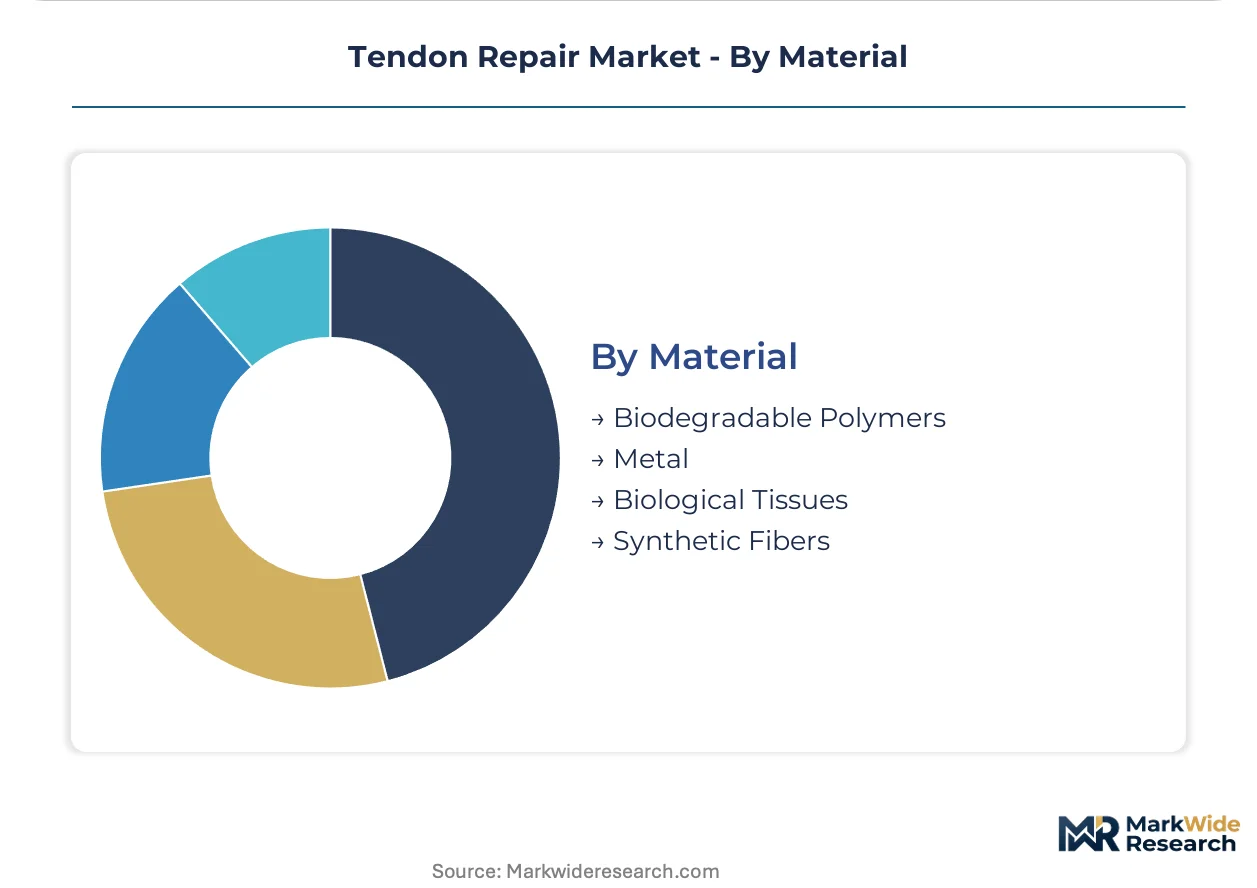
Material:
Supply concentration varies sharply between commodity metal feedstocks and constrained biological tissue inputs.
- Biodegradable Polymers:Polylactic acid, polyglycolic acid, and magnesium-based resorbable materials eliminate implant removal surgeries. FDA biocompatibility priorities are accelerating 510(k) clearance timelines for resorbable fixation devices that align with reduced revision rate objectives.
- Metal:Titanium and stainless steel suture anchors provide permanent fixation with established mechanical performance. United States hospital procurement contracts favor metal anchors in high-load applications where long-term durability outweighs bioresorption benefits.
- Biological Tissues:Decellularized allografts and xenografts supply scaffold and graft segments.
- Synthetic Fibers:Ultra-high molecular weight polyethylene and polyester suture materials.
Metal anchors command the established base. Biodegradable polymers are expanding most quickly through FDA alignment and surgeon demand for reduced secondary procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's biologics distribution capacity for decellularized tendon scaffolds. United States airport hubs in Memphis and Louisville anchor North American next-day implant logistics. Shanghai Pudong's pharmaceutical free trade zone accelerates Asian market access for multinational device manufacturers.
United States
Workers' compensation channels and aging recreational athletes sustain procedural volume growth across Texas and Florida metropolitan markets. FDA 510(k) clearance pathways for Class II medical devices compress product development timelines relative to European alternatives. Surgeon-owned ambulatory surgical centers in Dallas-Fort Worth and Miami concentrate procurement authority outside traditional hospital materials management departments.
Germany
REACH chemical registration requirements reshape raw material sourcing for PEEK and resorbable polymer implants manufactured in Baden-Württemberg industrial clusters. The EU Medical Device Regulation imposes extended clinical evidence timelines for biologic scaffolds entering European markets. Stuttgart-based precision engineering networks supply arthroscopic instrumentation to domestic and export markets.
Japan
PMDA regulatory frameworks prioritize biocompatibility documentation for magnesium-based resorbable fixation devices. METI industrial policy supports domestic production of high-tensile suture materials for rotator cuff applications. Osaka-Kobe manufacturing corridors concentrate polymer processing expertise for next-generation biodegradable anchors.
United Kingdom
NHS procurement frameworks favor cost-accessible suture-based repair systems over premium biologic augmentation matrices. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines for London-based medical device distributors. Cambridge-Oxford research corridors host scaffold innovation partnerships between university hospitals and biotech ventures.
Switzerland
Swissmedic certification requirements for biologic-device combination products extend supplier qualification periods beyond mechanical implant categories. Basel-Zurich pharmaceutical clusters leverage existing biologics manufacturing infrastructure for collagen-based tendon augmentation matrices. Precision polymer processing capabilities in the Jura region support specialized fixation device component supply.
Tendon Repair Market Key Industry Players
Concentration sits with diversified orthopedic conglomerates controlling integrated sports medicine portfolios across implants, instruments, and capital equipment. The vendor base stratifies into three tiers: multinational device manufacturers with hospital system contracting leverage, mid-cap biologics specialists focused on scaffold innovation, and regional polymer processors supplying commoditized anchor components. Dominant competitive moves include strategic partnerships with ambulatory surgical center joint ventures and backward integration into biologic tissue processing capabilities.
Among United States-based diversified manufacturers, Stryker and Zimmer Biomet exemplify the integrated portfolio archetype spanning arthroscopic delivery modes. Arthrex, Inc. occupies a specialist position concentrated on suture anchor design intensity and surgeon training infrastructure. These three entities represent distinct strategic postures: conglomerate scale advantages, biologics-focused R&D intensity, and channel control through physician education ecosystems.
| Leading Market Players |
|---|
| Stryker |
| Arthrex, Inc. |
| CONMED Corporation |
| Integra LifeSciences |
| Smith+Nephew |
| DePuy Synthes, Inc. |
| Zimmer Biomet |
| MiMedx |
| TendoMend |
| Others |
Cost & Logistics Intelligence
Biodegradable polymer substitution for metal and PEEK fixation devices is redrawing procurement geography toward Baden-Württemberg and Osaka-Kobe manufacturing corridors while compressing margin pools in legacy anchor categories. This material transition simultaneously elevates REACH compliance costs for European suppliers and creates tiered pricing separation between resorbable premium tiers and commoditized metal alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs suture anchor procurement, with knotless biocomposite systems commanding specification authority at academic medical centers while Indian and Chinese polymer alternatives capture ambulatory surgical center volume. Price differentiation hinges on FDA 510(k) clearance tier and surgeon training certification bundled with device purchase. Margins are tightening in standard metal anchor categories due to low-cost polymer substitution. Workers' compensation channels exhibit lowest price sensitivity; hospital GPO contracts face greatest cost compression pressure.
Supply Chain Analysis
Inventory lead times for decellularized allograft scaffolds extend beyond mechanical implant categories due to donor tissue screening protocols and cold chain preservation requirements. Raw material sourcing draws from United States tissue banks, German collagen processors, and Japanese magnesium alloy foundries. Single-source vulnerability concentrates in purified collagen supply from limited donor pools. Distribution runs through surgeon-owned distributorships in Texas and Florida metropolitan markets alongside traditional hospital materials management channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in percutaneous technique instrumentation and workers' compensation channel penetration, as ambulatory migration splinters procurement authority away from consolidated hospital systems.
For Market Incumbents: Secure arthroscopic platform dominance through backward integration into biologic tissue processing capabilities, eliminating third-party scaffold margin extraction. Lock in ambulatory surgical center joint venture equity stakes in Dallas-Fort Worth and Miami corridors before physician ownership structures crystallize competitor access. Anchor portfolio positioning against FDA biocompatibility priorities for resorbable fixation devices. For New Entrants and Emerging Players: Anchor in ultrasound-guided percutaneous Achilles repair instrumentation, a white-space segment lacking established training ecosystems. Target workers' compensation occupational injury protocols as a channel distinct from hospital GPO contracting. Pursue ISO 13485 certification early to compress supplier qualification timelines for biologic-device combination products. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap biologics specialists holding collagen-based augmentation matrices and European tissue processing infrastructure. Five-to-ten year viability favors scaffold innovators with captive supply of decellularized matrices over commoditized anchor manufacturers facing polymer substitution. Watch FDA guidance evolution on biologic-based medical devices as inflection signal for reimbursement access and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Surgeon Training Infrastructure Investment | Physician education ecosystems in Texas and Florida determine vendor selection authority outside hospital procurement. |
| Biologic Tissue Processing Integration | Captive collagen supply from United States tissue banks eliminates third-party margin extraction in scaffold manufacturing. |
| Resorbable Polymer R&D Expansion | Magnesium and polylactic acid formulations align with FDA biocompatibility priorities for reduced revision surgery rates. |
| Ambulatory Surgical Center Partnership | Equity stakes in surgeon-owned ventures concentrate case volume routing away from traditional hospital contracting. |
| REACH Compliance Certification | Full supply chain substance documentation for PEEK and resorbable polymers determines European market access eligibility. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and ambulatory surgical center administrators; and secondary validation through FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement contract registries, and EU MDR submission records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across the analysis window.
Across the projection horizon, forecasts incorporate segmentation by product type, delivery mode, end user, and material composition alongside geographic regulatory cluster differentiation. CAGRs derive from procedure volume elasticity to ambulatory reimbursement expansion, surgeon supply constraints, and biologic scaffold adoption curves. Industry-specific inputs include workers' compensation claim frequency patterns and arthroscopic fellowship training pipeline data.
Material uncertainties — FDA biologics classification pathway revisions, EU MDR clinical evidence timeline extensions, and donor tissue availability volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding CMS outpatient reimbursement stability and ISO 13485 certification standard continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Podiatry Services Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Kyphosis Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Orthopedic Repair Market