
 Middle East and Africa Lung Cancer Screening Software Market | 2026-2036
Middle East and Africa Lung Cancer Screening Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lung Cancer Screening Software Market Foresight
The gap between premium AI-native platforms and legacy workstation-integrated tools is repositioning procurement criteria across Middle East and Africa healthcare systems. Siemens Healthineers leverages its installed base of CT and PET imaging hardware to bundle screening analytics directly into radiology workflows. GE Healthcare anchors its regional presence through localized service networks and compliance support for Gulf state medical device registrations. Optellum Ltd. differentiates via proprietary lung nodule malignancy risk scoring that integrates with existing hospital information systems.
Lung cancer screening software encompasses algorithmic systems that analyze thoracic medical images—primarily low-dose CT scans with slice thickness below 2.5mm—to identify pulmonary nodules, quantify growth rates, and stratify malignancy probability for clinical decision support. These platforms deploy convolutional neural networks trained on annotated lesion datasets to reduce false-positive rates and standardize inter-reader variability in radiological interpretation. CT Screening dominates current deployment volumes across the region's hospital networks, while Cloud-Based delivery modes are gaining fastest traction as Gulf health systems modernize IT infrastructure and seek scalable subscription economics. Diagnostic Support applications capture concentrated margin pools where software outputs directly influence biopsy referral pathways and staging decisions.
South Africa's SAHPRA enforces software-as-medical-device oversight that mandates clinical validation for AI diagnostic tools, while Saudi Arabia's SFDA aligns with Gulf Central Committee for Drug Registration technical guidelines for standalone screening algorithms. The UAE's MOHAP operates parallel federal and emirate-level approval tracks that create compliance complexity for vendors entering Dubai and Abu Dhabi markets. Stakeholders must monitor how harmonization between Gulf regulatory frameworks and broader African national medicine agencies reshapes market access requirements and localization obligations.
Market Dynamics
AI-assisted nodule detection algorithms are compressing radiologist interpretation cycles across tertiary hospital networks, forcing procurement departments to reevaluate workstation-integrated tools against standalone cloud-native platforms.
Growth Catalysts
- Gulf Central Committee alignment:Saudi Arabia's SFDA harmonization with Gulf technical guidelines accelerates cross-border software registrations, reducing vendor entry friction across GCC states.
- Cloud infrastructure modernization:UAE and Saudi health ministries are retiring on-premise PACS systems, creating immediate demand for scalable subscription-based screening analytics.
- Radiologist workforce constraints:South Africa's oncology departments face specialist shortages, driving automated triage tool adoption to manage LD-CT scan volumes.
Market Restraints
- Validation cost burden:SAHPRA's clinical evidence requirements for software-as-medical-device classification impose six-figure validation study costs on AI algorithm vendors.
- Hardware dependency:Thin-slice CT scanner availability concentrates in Johannesburg, Cape Town, Riyadh, and Dubai, excluding secondary cities from screening program participation.
- Interoperability friction:Legacy hospital information systems across Nigerian and Kenyan facilities lack HL7 FHIR compatibility, blocking seamless AI tool integration.
Strategic Opportunities
- Emirate-level regulatory arbitrage:Dubai Health Authority's accelerated approval track offers faster market access than federal MOHAP pathways for vendors with European CE marking.
- Mobile screening units:South Africa's public health expansion into Eastern Cape and Limpopo provinces creates demand for edge-computing diagnostic tools operating offline.
- AI-radiomics convergence:Integration of volumetric nodule analysis with genomic risk scoring opens premium pricing tiers for comprehensive patient stratification platforms.
Industry Challenges
- Annotation labor scarcity:Curated thoracic CT datasets require board-certified radiologist labeling, with fewer than 200 qualified specialists across the entire Middle East and Africa region.
- Dual-track compliance complexity:Vendors must simultaneously satisfy UAE federal MOHAP requirements and emirate-specific Dubai or Abu Dhabi health authority protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lung Cancer Screening Software Market |
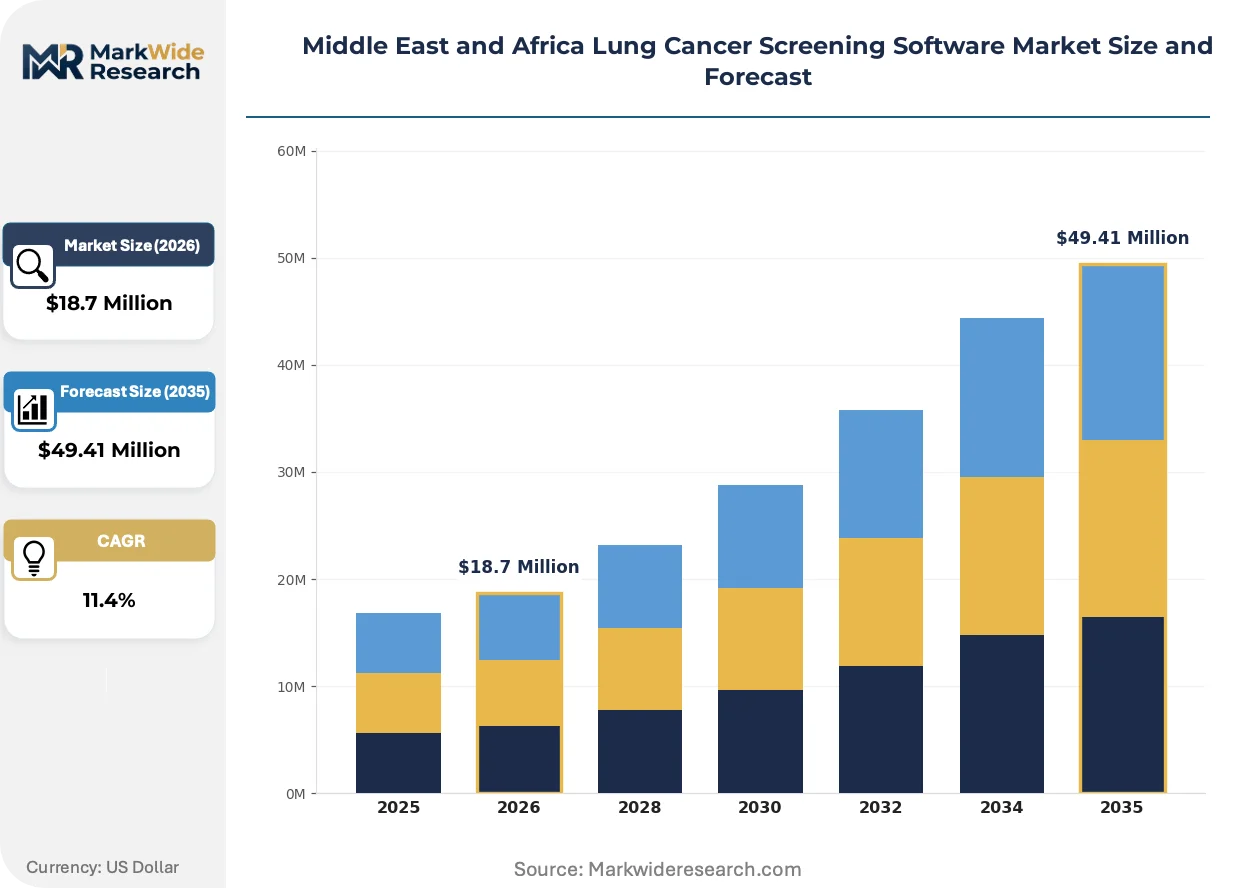
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Screening, Chest X-ray, MRI Screening, PET Scan Application: Early Detection, Risk Assessment, Patient Management, Diagnostic Support Delivery Mode: Cloud-Based, On-Premise, Hybrid, Software as a Service End User: Hospitals, Imaging Centers, Research Institutions, Clinics |
| Companies Covered | Koninklijke Philips N.V., Lunit Inc., Siemens Healthineers, Viz.ai Inc., Optellum Ltd., Philips Healthcare, Infervision Medical Technology, Zebra Medical Vision Ltd., GE Healthcare, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lung Cancer Screening Software Market Shifts & Advancements
Federated learning architectures and regulatory sandbox programs are redrawing competitive boundaries between hardware-anchored incumbents and pure-play AI developers.
Convolutional neural networks trained on multi-institutional nodule datasets are consolidating radiology workflow standardization across Gulf hospital networks. Saudi Arabia's King Faisal Specialist Hospital and Research Centre deployed vendor-agnostic AI overlays that normalize inter-reader variability across its six regional campuses. This consolidation is compressing the addressable market for standalone workstation tools by embedding analytics directly into PACS infrastructure.
SAHPRA's 2023 software-as-medical-device guidance mandates prospective clinical validation for AI diagnostic algorithms, eliminating retrospective study acceptance. South African developers now face eighteen-month approval timelines versus six-month historical averages. Tertiary hospitals in Johannesburg and Cape Town are responding by prioritizing CE-marked European platforms with existing clinical evidence packages.
Radiology departments across GCC states are unbundling AI screening tools from comprehensive imaging equipment service contracts. Procurement teams in Abu Dhabi and Riyadh now issue separate RFPs for nodule detection algorithms, volumetric measurement modules, and malignancy risk calculators. This unbundling is most visible in Saudi Arabia's National Transformation Program hospitals, where competitive tendering for software components has reduced per-seat licensing costs by forcing modular pricing disclosure.
Middle East and Africa Lung Cancer Screening Software Market Segmentation
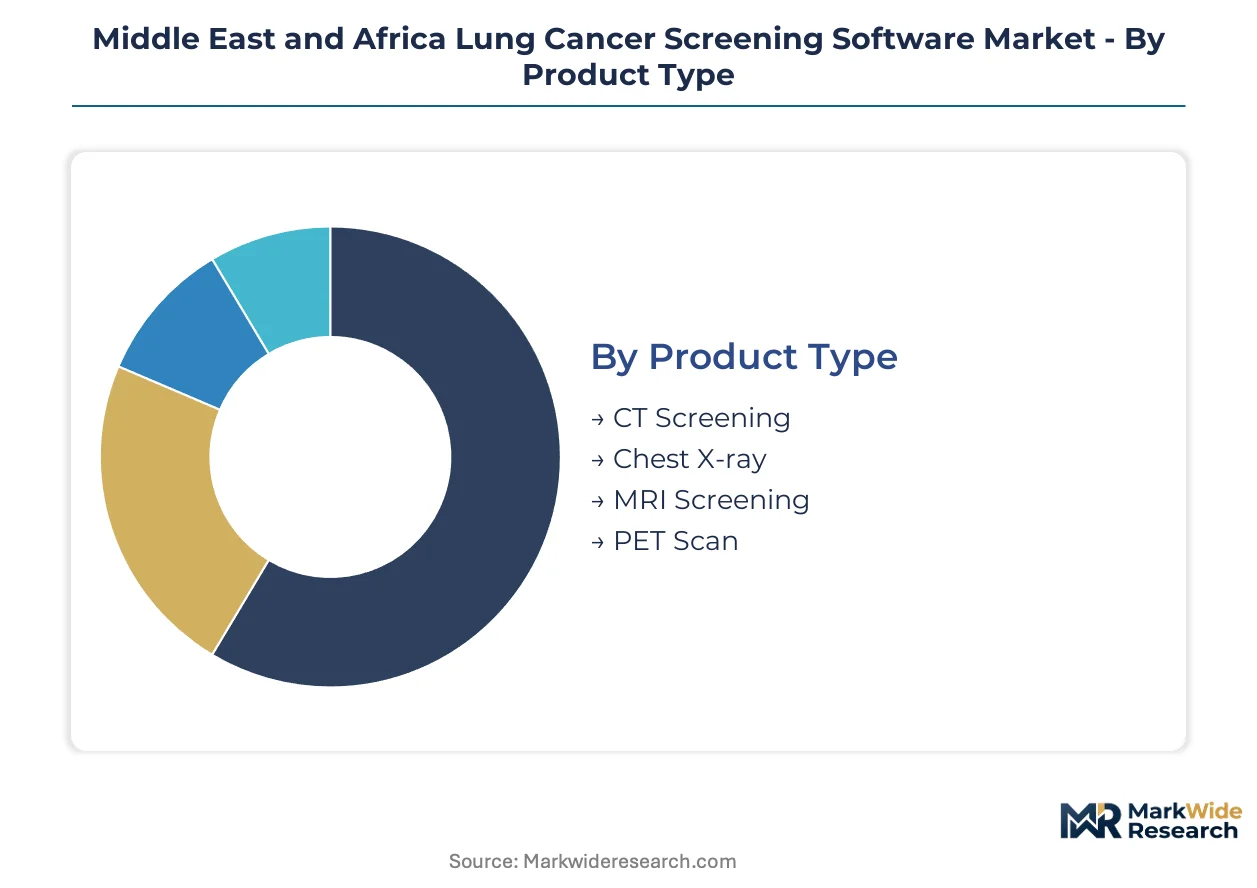
Segmentation in lung cancer screening software reveals distinct procurement patterns across Middle East and Africa healthcare systems. Hospital IT departments prioritize integration depth while radiology heads weigh algorithmic performance against total cost of ownership.
Product Type:
Procurement departments in tertiary hospitals anchor vendor selection on scanner compatibility and slice-thickness requirements rather than algorithm sophistication alone.
- CT Screening:Low-dose CT with sub-2.5mm slice thickness forms the clinical backbone of regional screening programs. Saudi Arabia's National Transformation Program hospitals and South Africa's Groote Schuur Hospital in Cape Town concentrate procurement here, driven by LD-CT protocol standardization in national cancer control frameworks.
- Chest X-ray:Legacy digital radiography systems with computer-aided detection overlays dominate secondary city deployments where CT scanner density remains insufficient. Nigerian federal medical centers and Kenyan county hospitals prioritize this modality for initial triage given capital constraints.
- MRI Screening:Contrast-enhanced thoracic MRI serves niche applications for patients with renal impairment or radiation exposure concerns. Johannesburg's private oncology networks deploy this for high-risk patient stratification.
- PET Scan:FDG-PET metabolic imaging integrates with staging workflows rather than primary screening. UAE's Dubai Health Authority facilities utilize this for nodule characterization following positive LD-CT findings.
CT Screening leads on scale; Chest X-ray leads on momentum across capital-constrained health systems.
Application:
Workflow integration depth determines software valuation, with radiology departments paying premiums for tools that compress interpretation-to-biopsy timelines.
- Early Detection:Automated pulmonary nodule identification on initial LD-CT scans. Abu Dhabi's Cleveland Clinic and Riyadh's King Faisal Specialist Hospital prioritize this application to reduce interval cancers in high-risk cohorts.
- Diagnostic Support:Malignancy probability scoring directly influences biopsy referral pathways. This application captures concentrated margin pools where algorithm outputs carry legal liability and clinical accountability.
- Risk Assessment:Volumetric growth rate analysis and smoking history integration for patient stratification. South Africa's public health expansion programs emphasize this for resource allocation across Eastern Cape provinces.
- Patient Management:Longitudinal tracking modules for surveillance scheduling and adherence monitoring. Gulf Cooperation Council national screening registries require this functionality for program outcome reporting.
Diagnostic Support commands premium pricing; Early Detection is expanding most quickly through government tender programs.
Delivery Mode:
IT infrastructure maturity and data sovereignty requirements partition procurement between subscription economics and capital expenditure models.
- Cloud-Based:Scalable analytics platforms hosted on regional cloud infrastructure with HL7 FHIR interoperability. UAE and Saudi health ministries drive fastest adoption as legacy PACS retirement accelerates.
- Software as a Service:Per-seat licensing with automatic algorithm updates and shared validation liability. South African private hospital groups favor this model to transfer regulatory compliance burden to vendors.
- On-Premise:Air-gapped installations for facilities with strict data localization mandates. Certain Dubai Health Authority facilities require this for patient data protection compliance.
- Hybrid:Edge-computing diagnostics with cloud synchronization for mobile screening units. South Africa's Eastern Cape and Limpopo province deployments utilize this for offline operation in connectivity-limited settings.
Cloud-Based leads on scale; Software as a Service is gaining share fastest among risk-averse procurement teams.
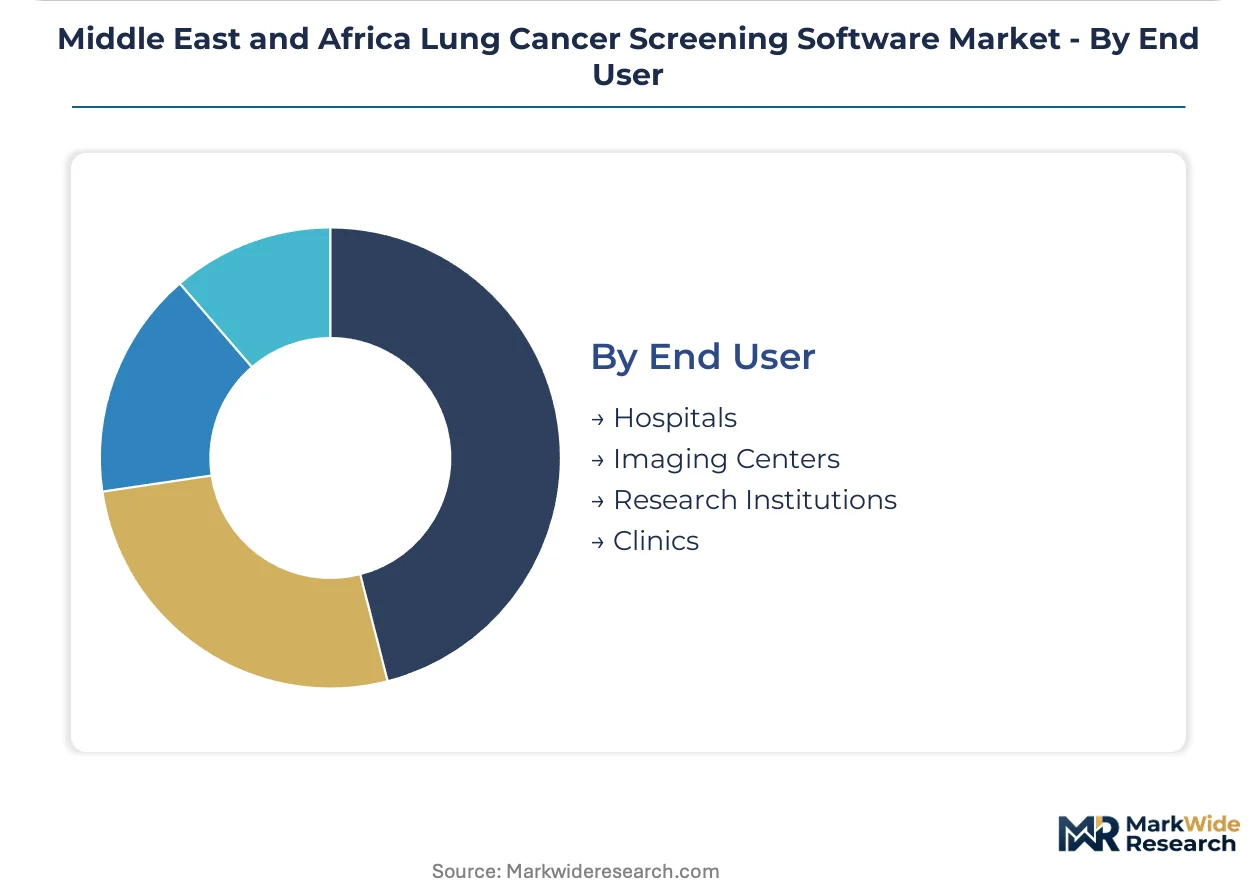
End User:
Capital availability and case volume concentration determine software sophistication thresholds across facility types.
- Hospitals:Tertiary oncology departments with dedicated thoracic surgery units. Johannesburg, Cape Town, Riyadh, and Dubai hospital networks anchor regional demand through comprehensive cancer center designations.
- Imaging Centers:Independent radiology groups performing outsourced LD-CT interpretation for referring physicians. Abu Dhabi and Jeddah see concentrated private investment in standalone screening facilities.
- Research Institutions:Academic medical centers with prospective validation study requirements. King Faisal Specialist Hospital and Research Centre and University of Cape Town drive algorithm development partnerships.
- Clinics:Primary care integration points for risk-based screening referrals. South Africa's public health clinic network and UAE's primary healthcare centers represent emerging deployment channels.
Hospitals lead on scale; Imaging Centers show steepest expansion trajectory as screening privatization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist workforce shortages and national cancer control programs anchor demand across Middle East and Africa healthcare systems. Gulf Cooperation Council states deploy cloud-native screening platforms while South African oncology departments prioritize CE-marked European tools. Regulatory fragmentation between federal and emirate-level authorities shapes vendor market access strategies.
Saudi Arabia
King Faisal Specialist Hospital and Research Centre drives AI overlay deployment across six regional campuses. The Saudi Food and Drug Authority harmonizes with Gulf Central Committee technical guidelines for standalone screening algorithms. Riyadh's National Transformation Program hospitals issue separate RFPs for nodule detection and malignancy risk modules.
United Arab Emirates
Dubai Health Authority operates accelerated approval tracks for vendors with European CE marking. The Ministry of Health and Prevention maintains parallel federal and emirate-level protocols that complicate compliance. Abu Dhabi's Cleveland Clinic and Sheikh Khalifa Medical City anchor premium-tier procurement for automated pulmonary nodule identification.
South Africa
Groote Schuur Hospital in Cape Town and Johannesburg tertiary oncology departments concentrate CT screening adoption. The South African Health Products Regulatory Authority enforces eighteen-month approval timelines through prospective clinical validation mandates. Eastern Cape and Limpopo province expansions create demand for edge-computing diagnostic tools in connectivity-limited settings.
Nigeria
Federal medical centers prioritize chest X-ray computer-aided detection for initial triage given capital constraints. The country's national pharmaceutical regulator imposes software-as-medical-device classification requirements that extend validation timelines. Lagos and Abuja hospital networks lack HL7 FHIR compatibility with legacy hospital information systems.
Kenya
County hospitals deploy digital radiography systems with computer-aided detection overlays for screening access. The national medicines regulatory agency aligns with broader East African Community harmonization efforts for medical device oversight. Nairobi's private oncology networks and Mombasa referral hospitals concentrate thin-slice CT scanner availability.
Middle East and Africa Lung Cancer Screening Software Market Competitive Landscape
Top-tier vendors anchor hardware-integrated bundles, while pure-play AI developers compete on algorithmic differentiation. Imaging equipment manufacturers leverage installed CT and PET scanner bases to embed analytics directly into radiology workflows. Two strategic archetypes dominate: hardware-anchored incumbents bundling screening tools into service contracts, and standalone algorithm specialists offering vendor-agnostic overlays. Competitive moves center on modular pricing disclosure and cloud infrastructure partnerships.
Among hardware-integrated incumbents, Siemens Healthineers and GE Healthcare exemplify the equipment-manufacturer archetype through service network localization and Gulf state registration support. Optellum Ltd. occupies a position within the standalone AI specialist tier, differentiated by proprietary malignancy risk scoring that integrates with existing hospital information systems. These three companies represent the competitive spectrum from bundled hardware-software contracts to modular cloud-native platforms.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Lunit Inc. |
| Siemens Healthineers |
| Viz.ai Inc. |
| Optellum Ltd. |
| Philips Healthcare |
| Infervision Medical Technology |
| Zebra Medical Vision Ltd. |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Cloud-native algorithm delivery is displacing on-premise installations across Gulf hospital networks, simultaneously collapsing deployment costs and redistributing pricing power from hardware-anchored vendors to modular AI specialists. This transition compresses legacy service contract premiums while elevating subscription transparency as the dominant procurement criterion.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across Middle East and Africa procurement channels. SaaS-tiered subscription models dominate cloud-based deployments, with pricing differentiation driven by CE marking tier and after-sales validation support. Cost compression in standard-tier offerings is intensifying because Saudi Arabia's National Transformation Program hospitals now mandate modular pricing disclosure. Public hospital procurement committees exhibit highest price sensitivity, while Dubai's private oncology networks prioritize algorithm performance over licensing cost.
Supply Chain Analysis
Curated thoracic CT datasets rest on annotation labor pools concentrated in South Africa, India, and select European academic medical centers. The supply chain draws from board-certified radiologist labeling services, cloud infrastructure provisioning, and HL7 FHIR interoperability middleware. Single-source vulnerability sits with the fewer than 200 qualified thoracic radiologists across the entire Middle East and Africa region. Distribution runs through direct enterprise sales to hospital procurement committees and imaging equipment service contract bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with SAHPRA's eighteen-month prospective validation mandate and Gulf Central Committee harmonization creating accelerating compliance barriers that concentrate demand among validated vendors.
For Market Incumbents: Acquire cloud infrastructure partnerships to defend against pure-play AI specialists unbundling analytics from CT scanner service contracts. Siemens Healthineers and GE Healthcare should deepen backward integration into edge-computing diagnostics for South Africa's mobile screening expansions, while accelerating CE marking reciprocity to exploit Dubai Health Authority's accelerated approval tracks. For New Entrants and Emerging Players: Enter via South Africa's Eastern Cape and Limpopo province public health expansions, where connectivity limitations and radiologist shortages create immediate demand for offline-capable diagnostic tools. Target hybrid delivery mode deployments in Nigerian federal medical centers lacking HL7 FHIR compatibility, positioning edge-computing solutions as bypass infrastructure for legacy hospital information systems. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone AI developers with proprietary malignancy risk scoring but limited Gulf state regulatory registrations. Long-term viability hinges on clinical validation asset accumulation rather than algorithm sophistication alone. The signal to watch is SAHPRA approval timeline compression or extension, which would immediately re-rate vendors with existing South African clinical evidence packages.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | European certification unlocks Dubai Health Authority's accelerated approval track for Gulf market entry. |
| Hospital System Partnership | King Faisal Specialist Hospital's six-campus AI overlay deployment creates reference architecture for regional expansion. |
| Software Companion Development | Volumetric nodule analysis integration with genomic risk scoring opens premium pricing tiers for comprehensive platforms. |
| Reimbursement Strategy | National cancer control program integration in Saudi Arabia and UAE anchors sustainable procurement budgets. |
| Platform Integration | HL7 FHIR interoperability with legacy PACS systems determines vendor shortlist inclusion across Nigerian and Kenyan facilities. |
Research Methodology
Multiple input streams — primary interviews with radiology department heads, hospital procurement managers, and biomedical engineers; secondary validation through SAHPRA guidance documents, Gulf Central Committee technical guidelines, and hospital procurement databases; plus regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Cross-referencing algorithm vendor licensing disclosures with tertiary hospital IT expenditure patterns anchored volume estimates.
Historical adoption curves were cross-referenced against panel input from health ministry officials and GPO contracts managers across the analysis window. Segmentation dimensions modeled include delivery mode, end-user facility type, application workflow depth, and regional regulatory cluster. CAGRs were derived from algorithm deployment velocity trajectories, with cloud infrastructure modernization timelines and radiologist workforce growth projections serving as key forecast inputs.
Inputs from SAHPRA, SFDA, and MOHAP regulatory filings were available through the study window; gaps in real-time procurement transaction data introduce uncertainty bands around pricing tier estimates. Forecasts reflect documented assumptions regarding Gulf state IT infrastructure retirement schedules and South African public health expansion timelines. A small set of triggers — harmonization between Gulf regulatory frameworks and broader African national medicine agencies, plus federated learning architecture regulatory acceptance — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Global Lung Cancer Screening Software Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Global Ioversol Market