
 United States Minimally Invasive Surgery Device Market | 2026-2036
United States Minimally Invasive Surgery Device Market Size, Share, and Industry Trends Forecast 2026-2036
United States Minimally Invasive Surgery Device Market Insights
Pay-per-procedure leasing and asset-light service models is reconfiguring capital deployment across the United States minimally invasive surgery device landscape. Medtronic leverages its end-to-end surgical ecosystem to sustain installed base loyalty across hospital networks. Intuitive Surgical dominates the robotic-assisted segment through proprietary instrument-software integration that locks recurring revenue streams.
Minimally invasive surgery devices encompass laparoscopic instruments, endoscopic visualization systems, robotic surgical platforms, and powered surgical tools engineered for reduced incision profiles and tissue trauma. These systems integrate high-definition optics, electromechanical articulation, and disposable consumables to enable precision intervention through natural orifices or ports under 15 millimeters. Robotic surgical systems command premium positioning due to capital intensity and proprietary ecosystem economics, while laparoscopic devices occupy mature volume tiers with consolidated supply chains. Endoscopic devices compete on optical resolution and single-use sterility transitions that reshape replacement cycles and margin pools.
FDA 510(k) clearance pathways and CMS National Coverage Determinations shape product commercialization timelines and reimbursement access for novel minimally invasive platforms in the United States. OSHA workplace safety standards and state-level ASC licensure requirements further constrain site-of-care expansion and capital equipment placement. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled surgical navigation and real-time CMS procedural code valuations that will determine platform economics and site-of-care migration trajectories.
Market Dynamics
Pay-per-procedure leasing models are restructuring capital deployment across ambulatory surgical centers, compressing traditional equipment ownership cycles and favoring asset-light service architectures that reduce upfront commitment thresholds for mid-tier facilities.
Growth Catalysts
- CMS Procedural Code Expansion:National Coverage Determinations for robotic-assisted procedures are unlocking reimbursement pathways for outpatient settings. Texas and Florida ASC networks are accelerating platform adoption under revised fee schedules.
- FDA 510(k) Streamlining:Artificial intelligence-enabled surgical navigation systems are clearing premarket notification pathways faster than predicate-based submissions. Device manufacturers are prioritizing real-time tissue characterization algorithms.
- Single-Use Device Transition:Sterility assurance requirements are displacing reprocessed laparoscopic instruments. California hospital systems are mandating disposable trocar and seal configurations to reduce surgical site infection liability.
Market Restraints
- Capital Intensity Concentration:Robotic platform procurement requires $1.5-2.5 million per unit plus annual service contracts. Smaller ASCs in rural Georgia and Alabama markets face exclusion from da Vinci ecosystem participation.
- Supply Chain Bottleneck:Electromechanical articulation components rely on precision machining clusters in Massachusetts and Connecticut. Disruption risks concentrate in single-source instrument sterilization packaging suppliers.
- Technical Limitation:Haptic feedback latency in current robotic architectures constrains fine tissue manipulation in microsurgical applications. Open procedures persist in complex oncologic resections where tactile sensation remains critical.
Strategic Opportunities
- Underpenetrated Geography:Rural hospital networks in Montana, Wyoming, and North Dakota operate below 15% laparoscopic adoption rates. Mobile surgical platform leasing could bridge infrastructure gaps without fixed capital deployment.
- Technology Convergence:Augmented reality visualization is integrating with preoperative imaging datasets. Teaching hospitals in Ohio and Pennsylvania are piloting holographic anatomical overlay systems for resident training programs.
- Regulatory Tailwind:OSHA workplace injury prevention mandates are accelerating powered surgical tool adoption to reduce repetitive strain disorders. Ambulatory centers are retrofitting ergonomic instrument suites to comply with updated ergonomic standards.
Industry Challenges
- Specialized Workforce Scarcity:Robotic surgery credentialing requires 200+ proctored cases for privileging. Arizona and Nevada markets report 18-month backlogs for certified first assistant training programs.
- Interoperability Friction:Proprietary instrument-software lock-in prevents cross-platform standardization. Health systems operating mixed vendor environments face workflow fragmentation and inventory duplication costs.
- Reimbursement Compression:Site-neutral payment policies are narrowing margin spreads between hospital outpatient departments and freestanding ASCs. Facilities must renegotiate managed care contracts to preserve robotic procedure profitability.
Report Scope
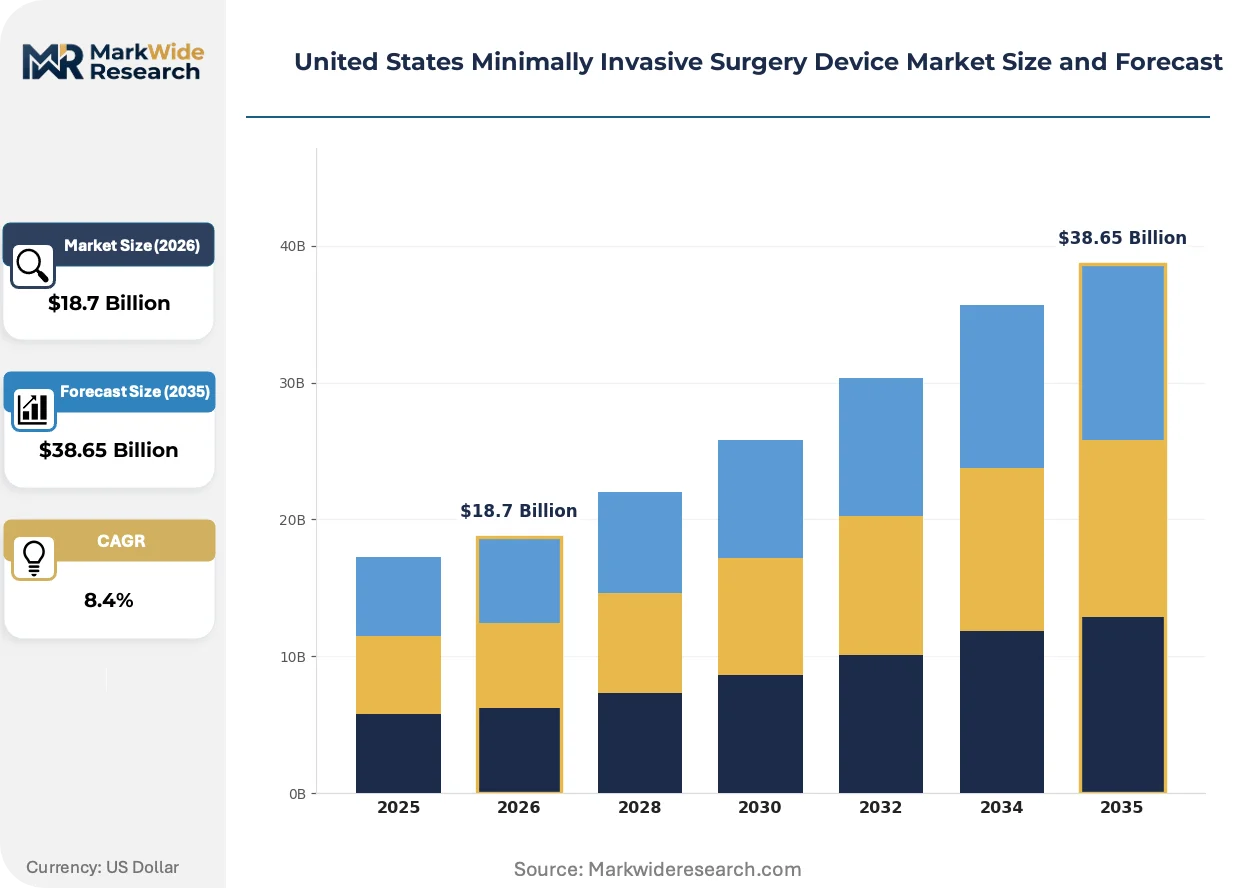
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Minimally Invasive Surgery Device Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Devices, Endoscopic Devices, Robotic Surgical Systems, Surgical Instruments Application: Gynecology, Gastroenterology, Orthopedics, Urology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Medtronic, Intuitive Surgical, Stryker, Johnson & Johnson, Olympus Corporation, Boston Scientific Corporation, Abbott Laboratories, Zimmer Biomet, Smith & Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Minimally Invasive Surgery Device Market Trends and Innovations
Artificial intelligence integration and disposable instrument architectures are converging to redefine surgical workflow economics, compressing traditional capital equipment lifecycles while elevating precision requirements.
Single-use robotic instrument cartridges are collapsing the reprocessing infrastructure that previously anchored hospital sterile supply departments. ASC networks in Florida and Texas are adopting cartridge-based platforms that eliminate autoclave dependency and reduce turnover time between cases. This shift is collapsing capital allocation patterns toward consumable revenue models that prioritize procedure volume over equipment longevity.
FDA guidance on AI-enabled surgical navigation is clarifying validation requirements for real-time tissue classification algorithms. Device sponsors are restructuring clinical trial designs to demonstrate non-inferiority against predicate manual techniques. Laparoscopic visualization systems with embedded machine learning are facing heightened scrutiny in 510(k) submissions, particularly for cancer margin detection applications.
Service unbundling is fragmenting traditional equipment-vendor relationships. Health systems are separating capital acquisition from maintenance, training, and data analytics components. Michigan and Wisconsin hospital networks are negotiating à la carte service tiers that limit vendor control over software updates and predictive maintenance algorithms.
United States Minimally Invasive Surgery Device Market Segmentation
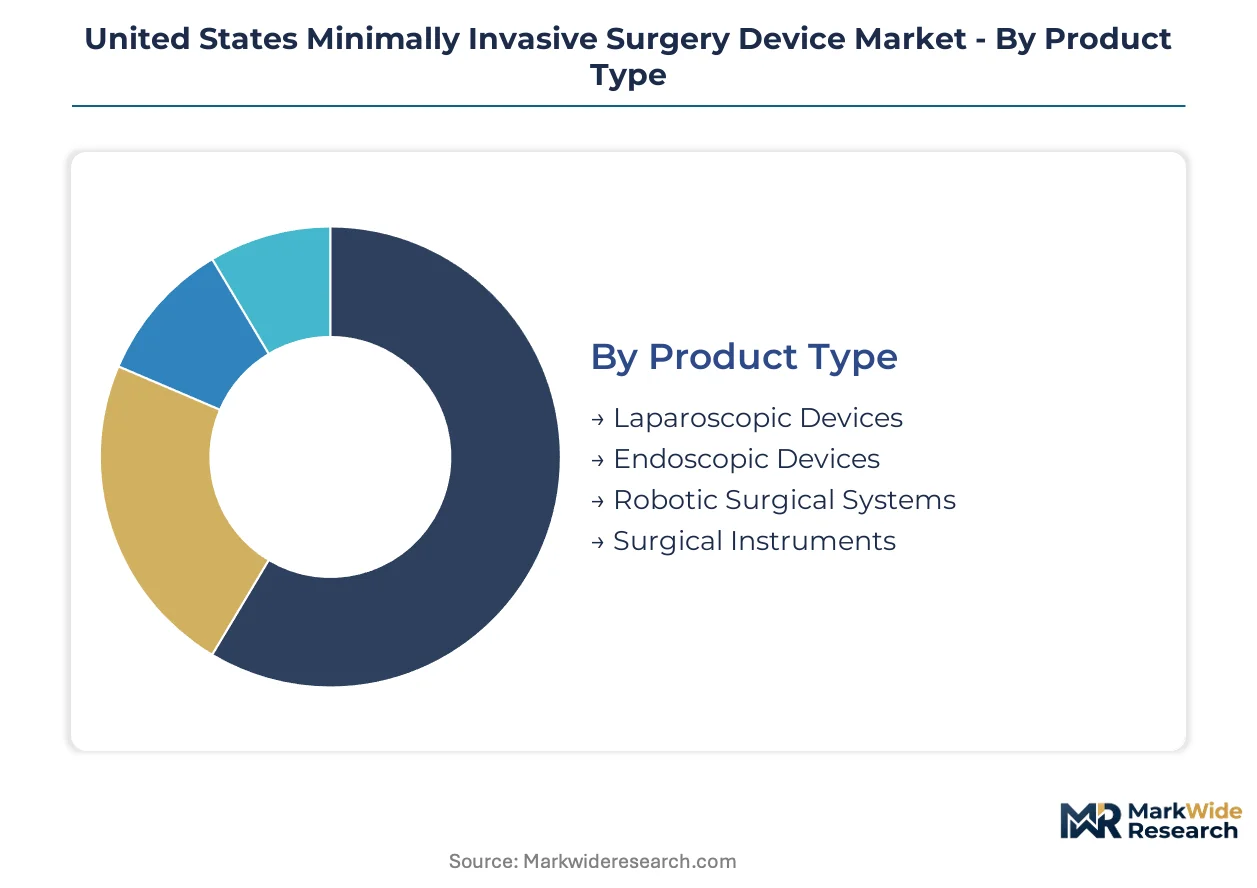
Device segmentation in the United States minimally invasive surgery market reveals how capital intensity, site-of-care economics, and procedural specialization reshape procurement priorities across hospital networks and ASCs. Understanding these category boundaries clarifies where margin pools concentrate and which technology platforms command pricing power.
Product Type:
Use-case spectrum spans disposable instruments through multi-million-dollar robotic platforms, with each tier demanding distinct capital deployment models and service architectures.
- Laparoscopic Devices:Trocars, graspers, and clip appliers constructed from medical-grade stainless steel and polymer composites enable multi-port access through 5-12mm incisions. Texas and California ASC networks are standardizing disposable trocar configurations to eliminate reprocessing liability and reduce turnover time between cases.
- Robotic Surgical Systems:Electromechanical platforms integrate stereoscopic visualization with wristed instrument articulation through proprietary console-surgeon interfaces. Teaching hospitals in Florida and Ohio are expanding installed bases under pay-per-procedure leasing arrangements that convert capital expenditure into operational budgets.
- Endoscopic Devices:Flexible and rigid optical systems with CMOS sensors and LED illumination enable natural orifice and small-port visualization across gastrointestinal and pulmonary applications.
- Surgical Instruments:Powered and manual tools including electrocautery devices, ultrasonic dissectors, and stapling systems complete procedural kits for tissue manipulation and hemostasis.
The dominant share belongs to Laparoscopic Devices, while Robotic Surgical Systems is closing the gap fastest.
Application:
Procedural volume concentrates in specialties where reimbursement clarity and clinical evidence support outpatient migration.
- Gynecology:Hysterectomy, myomectomy, and sacrocolpopexy procedures drive demand for uterine manipulation systems and morcellation containment technologies. Florida ASC networks report accelerating adoption of same-day discharge protocols for benign gynecologic robotics.
- Gastroenterology:Colorectal resection, fundoplication, and bariatric interventions require advanced energy devices and stapling platforms with tissue-sensing feedback. California hospital systems are mandating laparoscopic approaches for resectable colorectal malignancies to reduce length-of-stay penalties.
- Urology:Prostatectomy and partial nephrectomy applications leverage robotic precision for nerve-sparing dissection in confined pelvic anatomy.
- Orthopedics:Arthroscopic joint repair and spinal decompression utilize specialized visualization and powered shaver systems distinct from abdominal platforms.
Gynecology holds the largest procedure volume, with Gastroenterology climbing fastest as screening compliance drives early-stage intervention.
End User:
Site-of-care economics fragment purchasing authority between centralized hospital supply chains and decentralized ASC procurement committees.
- Hospitals:Integrated delivery networks maintain captive sterile processing departments and negotiate enterprise-wide robotic platform contracts with bundled training and service tiers. Academic medical centers in Pennsylvania and Michigan prioritize resident education pathways in platform selection criteria.
- Ambulatory Surgical Centers:Freestanding facilities under 10 operating rooms dominate laparoscopic volume through asset-light leasing and single-use instrument strategies. Texas ASC networks are consolidating purchasing through group purchasing organizations to match hospital pricing tiers.
- Specialty Clinics:Office-based endoscopy and minor procedural suites drive demand for compact, portable visualization systems with reduced sterilization infrastructure.
- Research Institutions:Preclinical and clinical trial sites require flexible platform configurations for investigational device exemption studies and surgeon training protocols.
Hospitals retain the dominant procurement volume, though Ambulatory Surgical Centers is expanding most quickly as site-neutral payment policies accelerate outpatient migration.
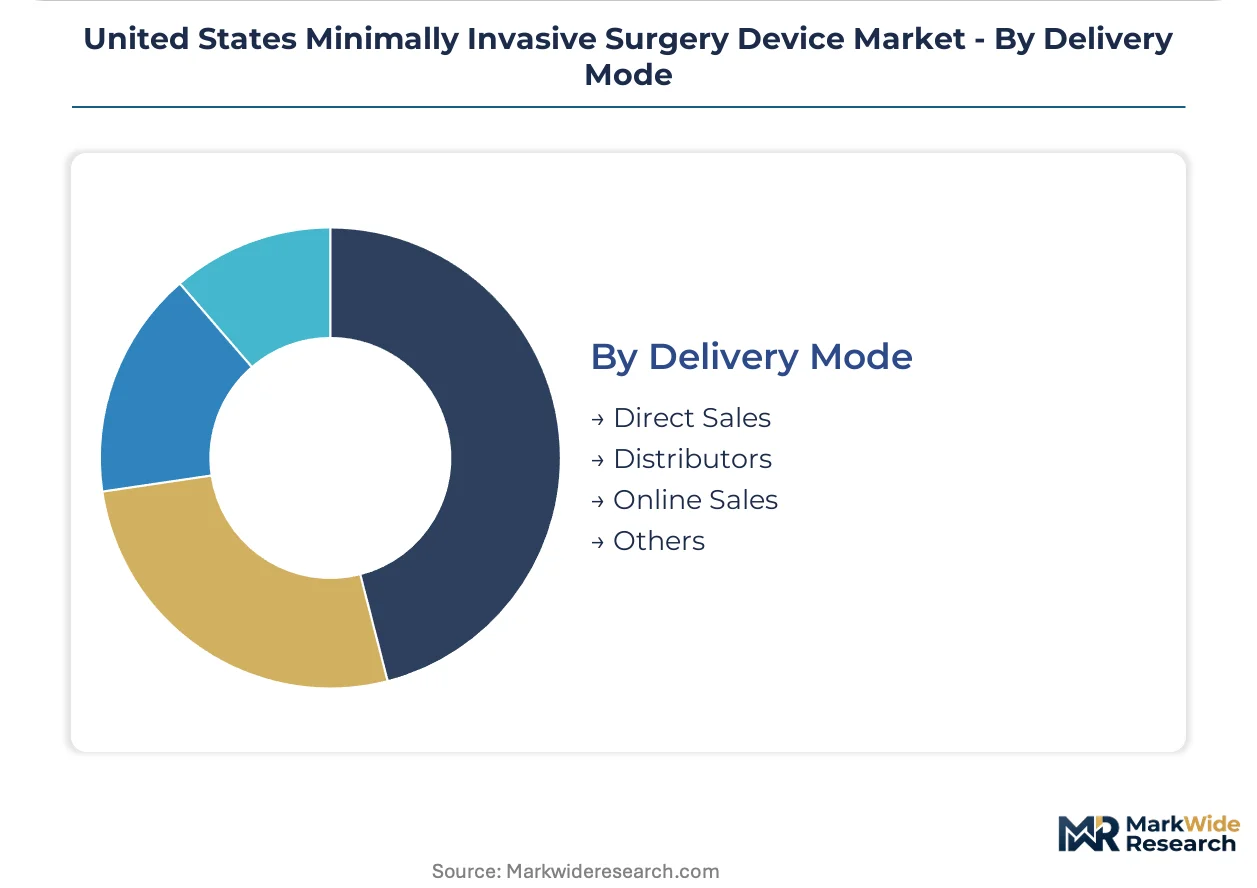
Delivery Mode:
Channel structure reflects capital equipment complexity versus consumable replenishment velocity.
- Direct Sales:Manufacturer field teams manage robotic platform placement, installation, and surgeon training through multi-year partnership agreements. Intuitive Surgical and Medtronic maintain dedicated account executives for top-100 hospital systems.
- Distributors:Regional medical-surgical distributors handle laparoscopic instrument logistics for mid-tier hospitals and ASCs below direct sales thresholds. Cardinal Health and McKesson networks cover secondary and tertiary markets.
- Online Sales:E-procurement portals enable standardized consumable replenishment with contracted pricing visibility for supply chain managers.
- Others:Group purchasing organizations and integrated delivery network central contracts aggregate demand across multiple facilities.
Direct Sales commands the highest value per transaction, while Distributors reach the broadest facility footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas ASC networks command premium pricing for robotic-assisted procedures while rural Montana hospitals absorb margin compression from mobile platform leasing fees. California's disposable instrument mandates drive 15-20% cost premiums over reprocessed alternatives. Florida's gynecologic robotics volume concentrates in Miami-Dade and Tampa Bay corridors.
Texas
Dallas-Fort Worth and Houston medical centers anchor the nation's largest ASC robotics deployment. CMS procedural code expansions for outpatient settings unlock reimbursement pathways that accelerate da Vinci system adoption. San Antonio's military health networks pilot augmented reality surgical training for trauma applications.
California
Los Angeles County hospital systems mandate single-use laparoscopic configurations to reduce surgical site infection liability. State-level sterility assurance requirements displace reprocessed instruments across Kaiser Permanente and Sutter Health networks. Stanford Medicine and UCSF anchor AI-enabled surgical navigation trials in the Bay Area.
Florida
Miami-Dade ASC networks report accelerating same-day discharge protocols for benign gynecologic robotics. Tampa Bay's teaching hospitals expand installed bases under pay-per-procedure leasing arrangements. Orlando's simulation centers train surgical teams for Caribbean and Latin American hospital partnerships.
Ohio
Cleveland Clinic and Ohio State University anchor holographic anatomical overlay pilots for resident training programs. Midwest manufacturing clusters in Cincinnati supply precision electromechanical components for articulating instruments. State Medicaid reimbursement shifts favor hospital outpatient departments over freestanding ASCs for complex procedures.
Pennsylvania
Philadelphia's academic medical centers prioritize resident education pathways in robotic platform selection criteria. Pittsburgh's health systems negotiate à la carte service tiers that limit vendor control over software updates. Hershey Medical Center integrates preoperative imaging datasets with augmented reality visualization for oncologic resections.
United States Minimally Invasive Surgery Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base concentrates around three structural tiers: capital-intensive robotic platform manufacturers, diversified surgical instrument conglomerates, and single-use disposable specialists. Two dominant competitive moves reshape positioning: pay-per-procedure leasing arrangements that convert capital expenditure to operational budgets, and proprietary instrument-software ecosystems that lock recurring revenue streams.
Within the platform integrator tier, Intuitive Surgical and Medtronic exemplify contrasting ecosystem architectures. Intuitive Surgical anchors the robotic-assisted segment through console-instrument integration that privileges recurring consumable revenue. Medtronic leverages end-to-end surgical ecosystem breadth to sustain installed base loyalty across hospital networks. Stryker occupies a diversified instrumentation position spanning powered surgical tools and visualization systems.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| Stryker |
| Johnson & Johnson |
| Olympus Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Zimmer Biomet |
| Smith & Nephew |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on precision-machined electromechanical articulation components from Massachusetts and Connecticut machining clusters determines both tiered pricing spreads and supply chain vulnerability. Tariff exposure on imported sterilization packaging materials feeds into cost compression at mid-tier ASCs while consolidating procurement power among integrated delivery networks.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium robotic platforms, standard laparoscopic suites, and economy disposable instruments. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contract depth. Pricing pressure stems from CMS site-neutral payment policies narrowing margin spreads between hospital outpatient departments and freestanding ASCs. Mid-tier ASCs in rural markets exhibit highest price sensitivity, while academic medical centers prioritize ecosystem integration over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements for electromechanical component vendors serving platform manufacturers. Precision machining clusters in Massachusetts, Connecticut, and Minnesota supply articulation joints and servo motors, while single-use polymer components draw from medical-grade resin suppliers in Ohio and Texas. Single-source vulnerability concentrates in instrument sterilization packaging where FDA-validated barrier materials face logistics chokepoints at East Coast ports. Distribution runs through manufacturer direct sales for capital platforms and regional medical-surgical distributors for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
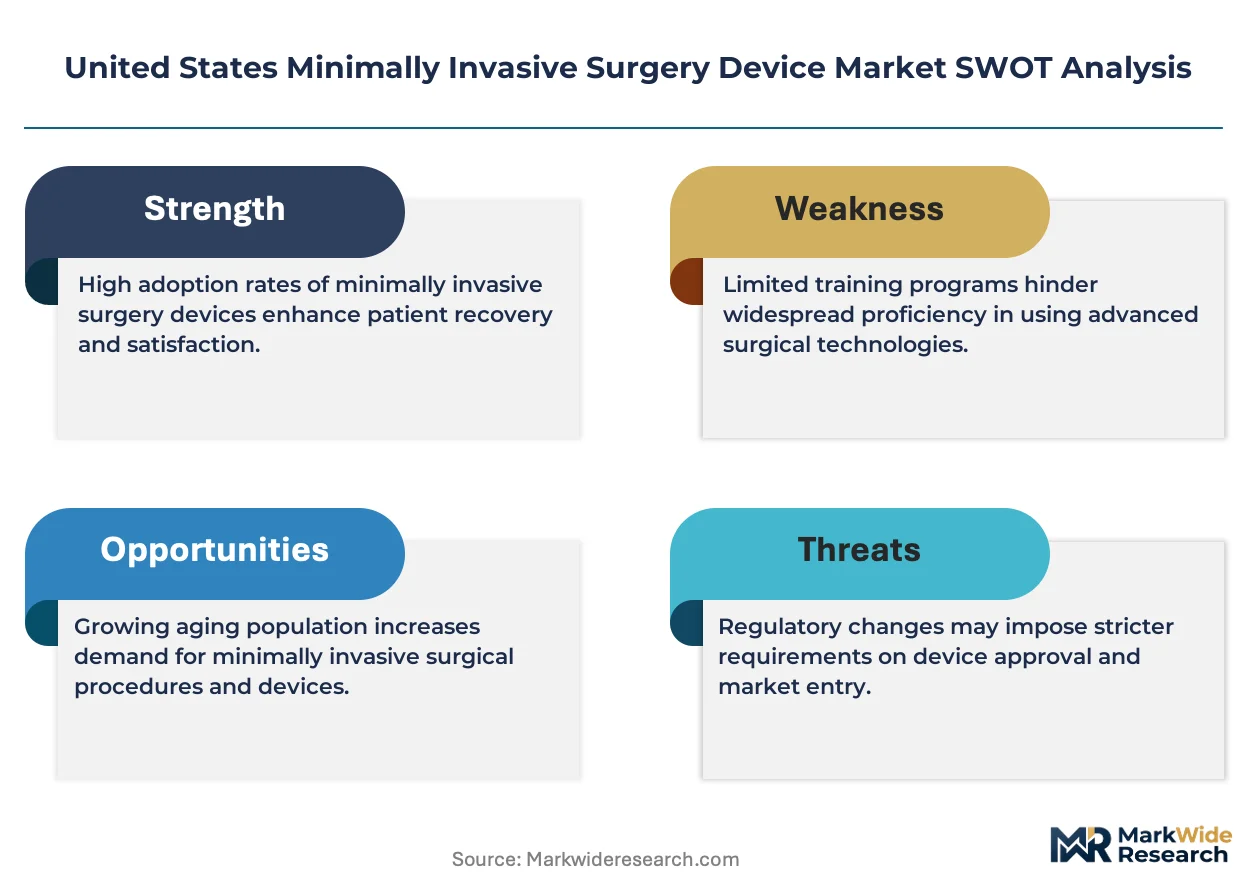
Regulatory entrenchment through FDA 510(k) predicate chains and CMS National Coverage Determinations constructs defensive moats around installed base loyalty. Switching costs lock health systems into proprietary instrument-software ecosystems that resist cross-platform standardization.
For Market Incumbents: Harden ecosystem stickiness by deepening proprietary instrument-software integration that resists interoperability mandates. Expand pay-per-procedure leasing footprints in Texas and Florida ASC networks to preempt emerging cartridge-based competitors. Prioritize AI-enabled surgical navigation 510(k) submissions ahead of predicate clearance backlogs. For New Entrants and Emerging Players: Rural hospital networks in Montana, Wyoming, and North Dakota operating below 15% laparoscopic adoption rates represent the most penetrable entry point for mobile surgical platform leasing. Single-use robotic instrument cartridges for gynecologic procedures offer white-space positioning against reprocessing-dependent incumbents. Pursue group purchasing organization channel partnerships to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: FDA guidance on AI-enabled surgical navigation reshapes the acquisition landscape toward algorithm-validated platform targets. Five-to-ten year viability favors disposable instrument specialists with sterilization-avoidance architectures over capital equipment manufacturers facing compressed replacement cycles. Monitor CMS procedural code valuations for robotic-assisted outpatient procedures as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | AI-enabled surgical navigation systems clear premarket pathways faster than predicate-based submissions. |
| Pay-per-Procedure Leasing Expansion | Texas and Florida ASC networks convert capital expenditure into operational budgets under revised fee schedules. |
| Single-Use Cartridge Development | Disposable robotic instrument architectures eliminate autoclave dependency and reduce turnover time between cases. |
| Hospital System Partnership Deepening | Integrated delivery networks negotiate enterprise-wide contracts with bundled training and service tiers. |
| Reimbursement Strategy Alignment | CMS National Coverage Determinations unlock outpatient pathways for robotic-assisted procedures. |
Research Methodology
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings. Primary fieldwork engaged robotic surgery program directors, ASC purchasing committee members, biomedical engineers, and GPO contracts managers across Texas, California, Florida, and Ohio markets. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement records, and OSHA workplace safety filings. Bottom-up procedure volume modeling and top-down equipment shipment analysis triangulate market sizing.
Calibration against historical robotic platform installation records and laparoscopic instrument shipment data informs the analytical framework across the analysis window. Segmentation dimensions span product type, application specialty, end-user site-of-care, and delivery channel. CAGRs derive from procedure volume elasticity to reimbursement shifts and capital equipment replacement cycle compression. Forecast inputs incorporate CMS fee schedule revision trajectories and FDA guidance timeline uncertainty for AI-enabled devices.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting ASC capital access or tariff regimes on precision-machined components would shift the trajectory. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory clearance velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Slip Disc Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Global Nebuliser Market
Medical Devices
China Ophthalmic Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Mediastinoscope Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Neurotechnology Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market