
 Wet Age-Related Macular Degeneration (Wet AMD) Market | 2026-2036
Wet Age-Related Macular Degeneration (Wet AMD) Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Age-Related Macular Degeneration (Wet AMD) Market Intelligence
Biosimilar formulations are pivoting treatment economics away from originator biologics across major markets. Regeneron Pharmaceuticals sustains its franchise through proprietary manufacturing scale and physician training networks. Novartis anchors European commercial infrastructure for intravitreal delivery. Bayer AG competes via geographic diversification across Asia-Pacific markets.
Wet age-related macular degeneration constitutes a chronic retinal vascular disorder characterized by choroidal neovascularization, abnormal blood vessel proliferation beneath the macula, and consequent central vision impairment requiring repeated intravitreal anti-VEGF administration. The condition demands sustained pharmacologic suppression of vascular endothelial growth factor to preserve photoreceptor function and prevent irreversible vision loss. Aflibercept and ranibizumab occupy mature positions within the product type landscape, while bevacizumab continues to capture cost-sensitive segments through off-label and biosimilar utilization. Hospital pharmacies dominate distribution channels for initial loading doses, though home care settings are gaining traction for maintenance regimens as injection technique standardization improves.
FDA, EMA, and PMDA each enforce distinct biosimilar interchangeability and pharmacovigilance requirements that shape market entry timelines and prescriber confidence. The FDA's interchangeable designation pathway and EMA's extrapolation rules directly influence payer contracting dynamics and formulary positioning across regulated markets. Stakeholders must monitor evolving real-world evidence requirements and regional pricing negotiation mechanisms to optimize portfolio allocation and patient access strategies.
Market Dynamics
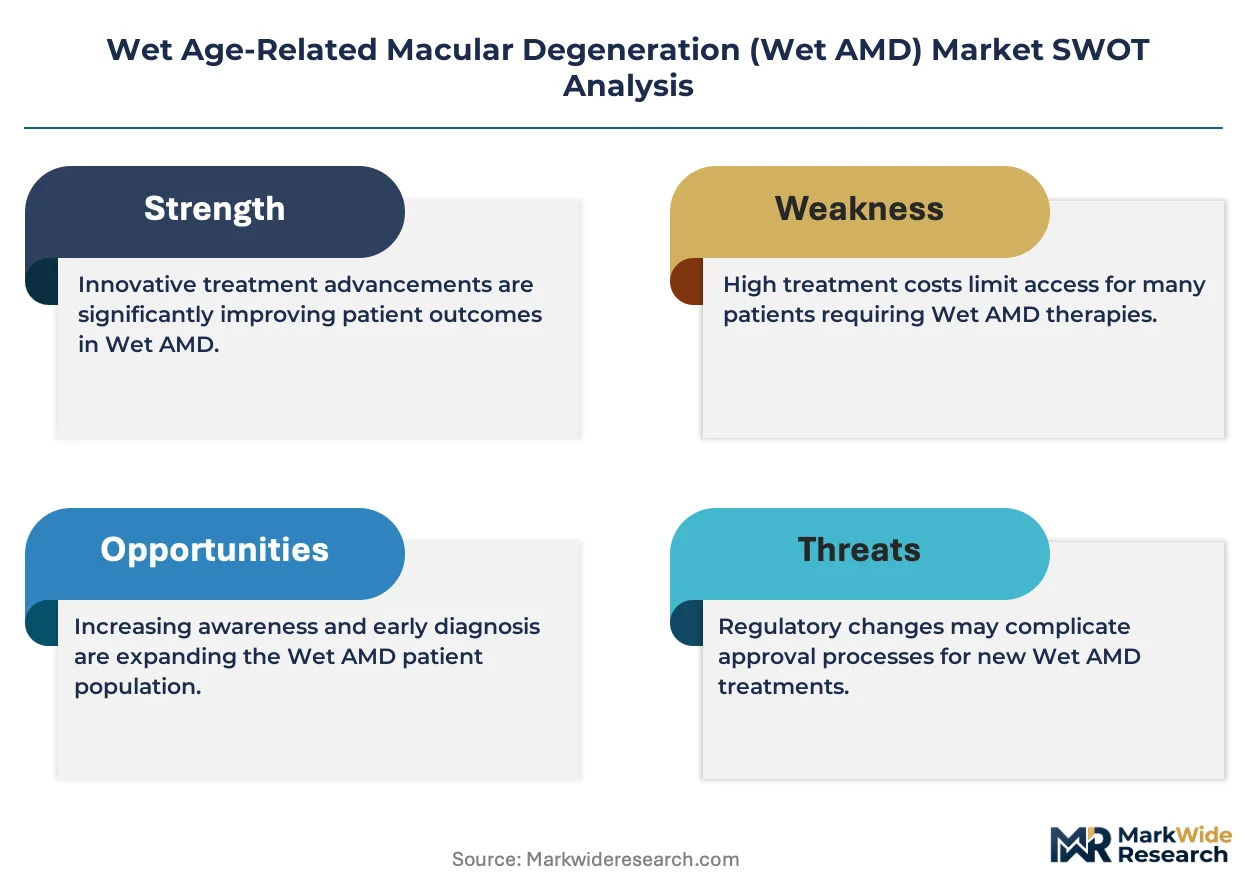
Biosimilar regulatory pathways at FDA and EMA are compressing originator pricing power while expanding patient access to anti-VEGF therapies across outpatient ophthalmology settings.
Growth Catalysts
- Interchangeable biosimilar designation:FDA's interchangeable pathway accelerates payer formulary adoption and reduces prior authorization friction for ranibizumab and aflibercept alternatives.
- Aging demographic concentration:Japan, Germany, and the United States exhibit accelerating prevalence of neovascular AMD as populations over 75 expand treatment-eligible pools.
- Intravitreal injection technique standardization:Improved training protocols and device-assisted delivery systems enable procedure migration from hospital suites to ambulatory surgical centers.
Market Restraints
- Biologics manufacturing concentration:Active pharmaceutical ingredient supply for anti-VEGF therapies concentrates among a limited set of contract manufacturing organizations in Switzerland and Singapore.
- Extended pharmacovigilance obligations:EMA's extrapolation rules impose post-market surveillance requirements that extend biosimilar commercialization timelines and inflate regulatory compliance costs.
- Treatment burden on elderly patients:Monthly or bimonthly injection schedules create adherence friction for patients with mobility limitations or caregiver dependency.
Strategic Opportunities
- Sustained-release delivery platforms:Port delivery systems and hydrogel depot technologies promise to extend dosing intervals from monthly to semi-annual administration.
- Home care channel expansion:Teleophthalmology oversight combined with visiting nurse injection services addresses rural and homebound patient segments currently excluded from treatment.
- Gene therapy pipeline maturation:Preclinical and early-stage programs targeting complement pathway modulation offer curative alternatives to chronic anti-VEGF suppression.
Industry Challenges
- Retinal specialist workforce constraints:Fellowship-trained vitreoretinal surgeons remain concentrated in academic medical centers, creating access bottlenecks for community-based injection volume growth.
- Cold chain integrity requirements:Temperature-sensitive biologics demand specialized logistics infrastructure that raises distribution costs for emerging market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Age-Related Macular Degeneration (Wet AMD) Market |
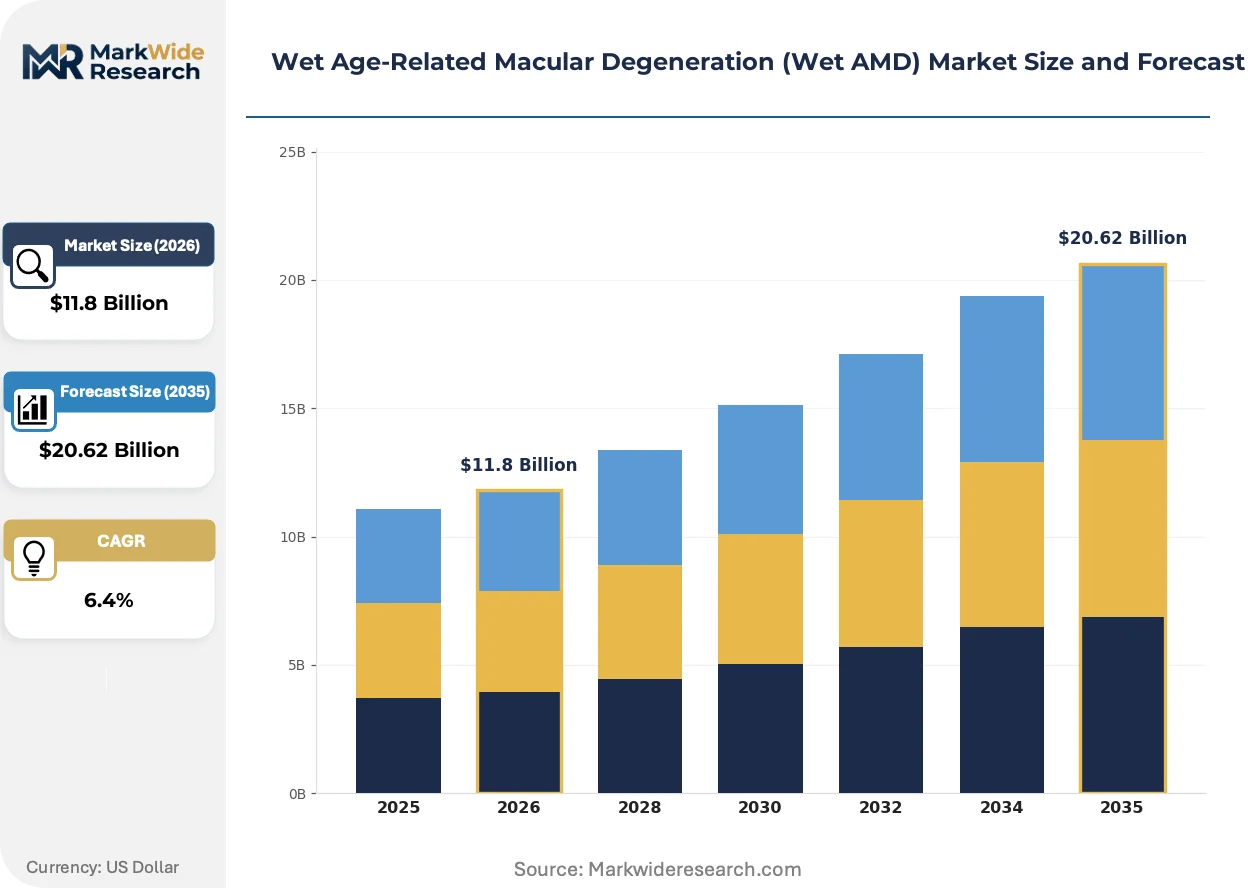
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aflibercept, Ranibizumab, Bevacizumab, Pegaptanib End User: Hospitals, Clinics, Home Care, Research Laboratories Treatment Approach: Injection, Laser Therapy, Photodynamic Therapy, Combination Therapy Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Others |
| Companies Covered | Bayer AG, Gilead Sciences Inc., Regeneron Pharmaceuticals Inc., Apellis Pharmaceuticals Inc., Pfizer Inc., F. Hoffmann-La Roche Ltd., Bausch Health Companies Inc., Kodiak Sciences Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Age-Related Macular Degeneration (Wet AMD) Market Strategic Shifts & Innovations
Delivery technology convergence and regulatory pathway maturation are restructuring competitive advantage around manufacturing scale and real-world evidence generation rather than molecular patent exclusivity alone.
Extended-release intravitreal implants are modularizing treatment paradigms by embedding anti-VEGF agents within biodegradable polymers or refillable reservoir devices. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for high-burden patients requiring frequent retreatment. The technology is modularizing the economics of chronic care by converting variable injection volume into predictable device procurement cycles.
EMA's extrapolation framework for ophthalmic biosimilars permits indication expansion beyond the reference product's approved uses based on mechanistic and pharmacokinetic similarity. This regulatory architecture compresses development timelines for second-generation biosimilars while intensifying pharmacovigilance obligations. European hospital pharmacies are responding by consolidating procurement around interchangeable products with robust real-world safety databases.
Patient self-referral through direct-to-specialist channels is displacing traditional optometric gatekeeping in urban United States markets. Large ophthalmology group practices in Florida and Arizona are capturing upstream diagnosis through in-house optical coherence tomography screening. This behavioral shift concentrates diagnostic and therapeutic revenue within integrated delivery networks while reducing community optometrist referral volume.
Wet Age-Related Macular Degeneration (Wet AMD) Market Segmentation
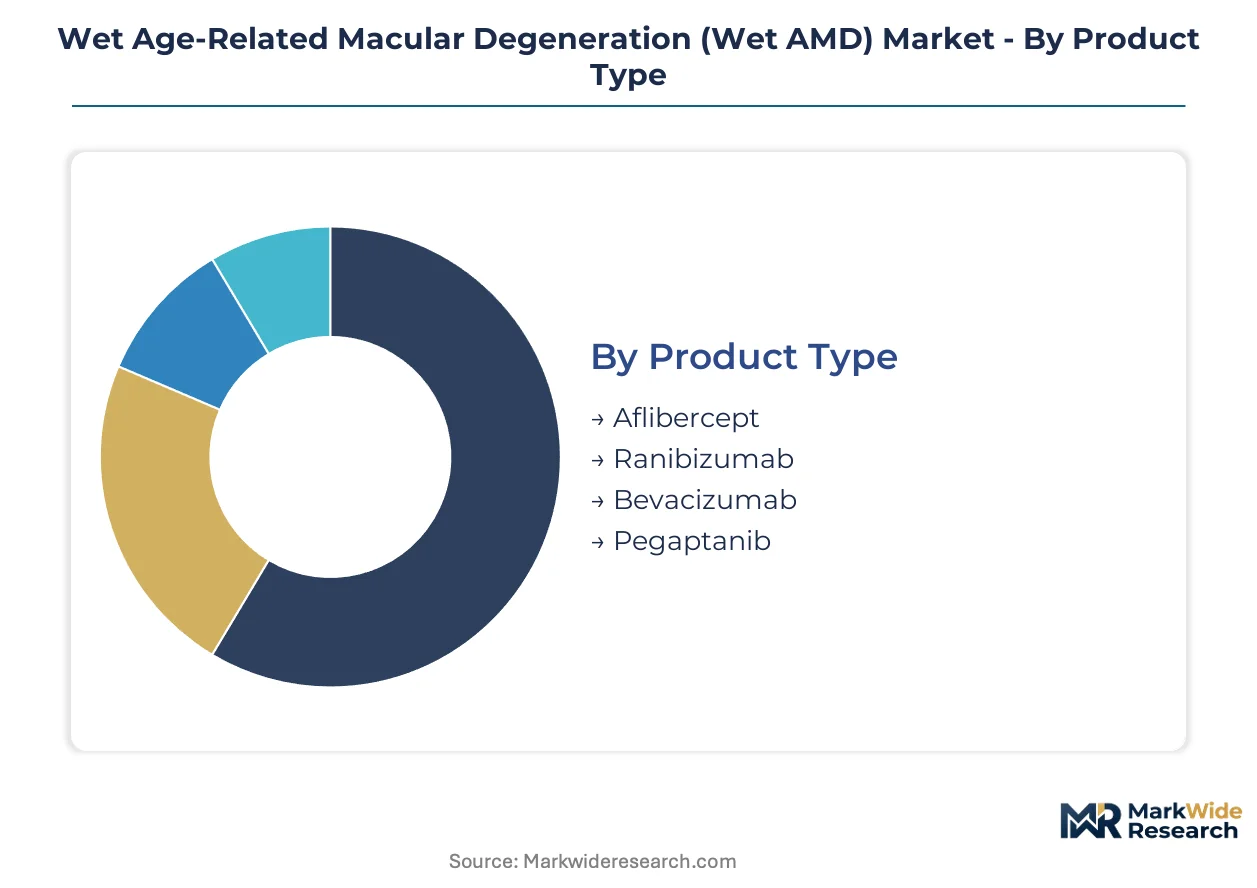
Wet AMD treatment selection hinges on pharmacoeconomic trade-offs between originator biologics and emerging biosimilars, with reimbursement tiers and injection frequency driving formulary positioning across outpatient settings. Segmentation reveals how delivery infrastructure, patient mobility constraints, and specialist workforce distribution reshape channel preferences and therapeutic modality adoption.
Product Type:
Cost tier determines access stratification, with originator molecules commanding premium reimbursement while biosimilar alternatives penetrate cost-sensitive segments.
- Aflibercept:A fusion protein binding VEGF-A, VEGF-B, and placental growth factor with extended half-life enabling bimonthly maintenance dosing. Demand concentrates in United States Medicare Part B reimbursement pathways where its longer dosing interval reduces injection burden for elderly patients with transportation limitations.
- Ranibizumab:A recombinant humanized monoclonal antibody fragment approved for monthly or treat-and-extend regimens, manufactured through E. coli expression systems. German statutory health insurance funds favor this molecule for its mature real-world safety database and established interchangeability protocols under EMA guidance.
- Bevacizumab:Full-length monoclonal antibody administered off-label or via biosimilar formulations at substantially lower per-dose cost.
- Pegaptanib:PEGylated aptamer targeting VEGF-165 isoform with narrower mechanism, reserved for select patient subpopulations.
Volume sits with ranibizumab; growth tilts toward aflibercept.
End User:
Patient mobility and disease severity dictate site-of-care selection, with stable maintenance patients migrating away from hospital-based delivery.
- Hospitals:Academic medical centers and tertiary ophthalmology departments manage complex neovascular AMD with concurrent retinal pathologies, performing initial loading doses and managing treatment-resistant cases requiring combination protocols or surgical intervention.
- Clinics:Ambulatory surgical centers and standalone ophthalmology practices capture routine intravitreal injection volume through streamlined scheduling and lower facility fees compared to hospital outpatient departments.
- Home Care:Visiting nurse services and teleophthalmology oversight enable injection delivery for homebound elderly patients in rural Japan and dispersed German regions.
- Research Laboratories:Academic centers and contract research organizations conduct Phase I-III trials for sustained-release implants and gene therapy candidates.
Clinics hold current volume leadership; home care channels are climbing the fastest.
Treatment Approach:
Injection dominance reflects anti-VEGF efficacy, while laser modalities persist for specific lesion anatomies and patient contraindications.
- Injection:Intravitreal administration of anti-VEGF agents constitutes first-line therapy for all lesion subtypes, with treat-and-extend protocols individualizing dosing intervals based on optical coherence tomography findings.
- Laser Therapy:Thermal laser photocoagulation targets extrafoveal choroidal neovascularization in patients unable to sustain frequent injection schedules.
- Photodynamic Therapy:Verteporfin-activated photochemical closure of neovascular membranes retains niche application for polypoidal choroidal vasculopathy subtypes.
- Combination Therapy:Sequential or concomitant anti-VEGF with photodynamic treatment addresses recalcitrant lesions in tertiary referral settings.
Injection captures overwhelming volume; combination approaches show steepest expansion trajectory in academic centers.
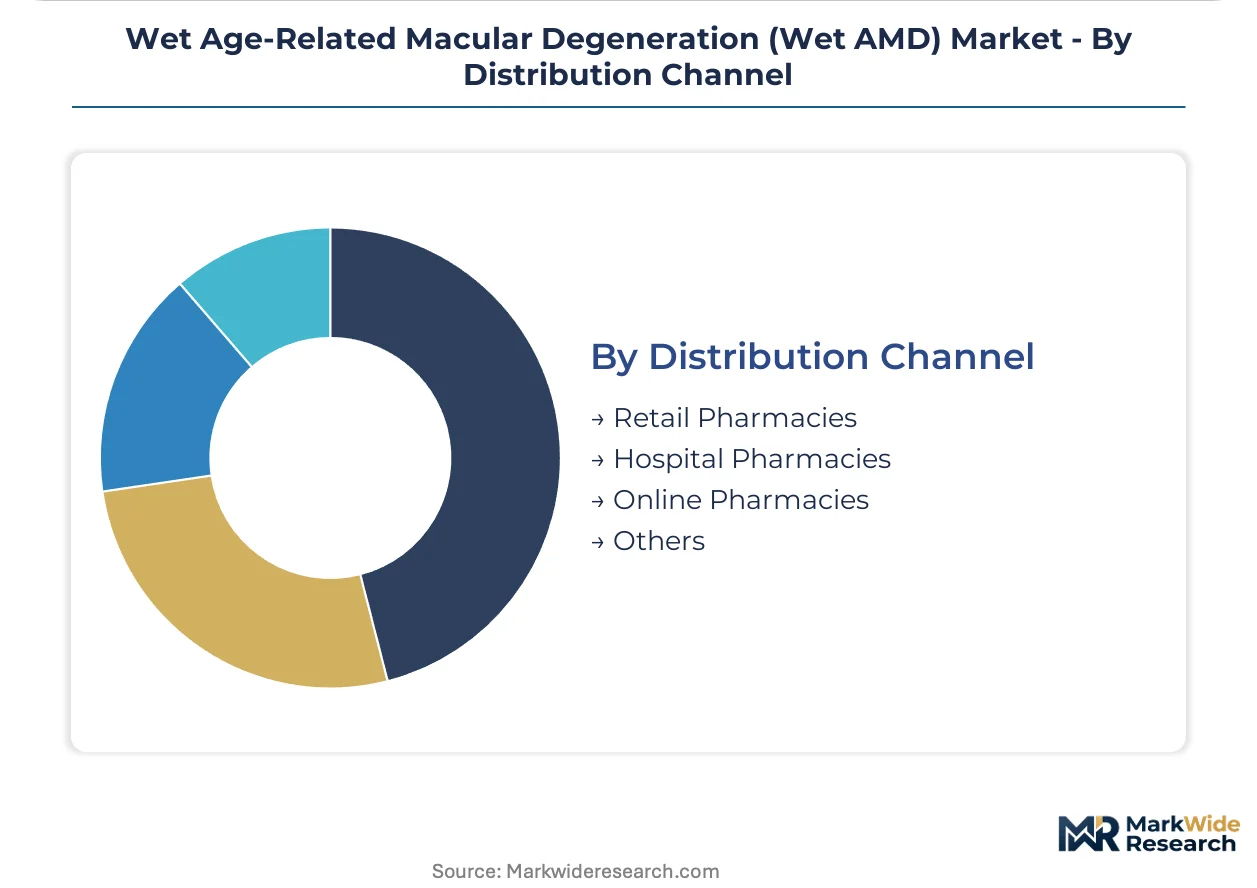
Distribution Channel:
Cold chain requirements and reimbursement mechanics concentrate biologic distribution through institutional pharmacies with specialized handling capabilities.
- Hospital Pharmacies:Institutional procurement departments manage temperature-controlled storage and unit-dose preparation for same-day injection administration, capturing originator biologic volume through 340B pricing and group purchasing organization contracts.
- Retail Pharmacies:Specialty pharmacy networks dispense maintenance doses for established patients with stable regimens, particularly in United States Medicare Part D and commercial insurance structures.
- Online Pharmacies:Mail-order distribution expands access for maintenance patients in remote geographies with predictable dosing schedules.
- Others:Direct-to-practice distribution and specialty distributor networks serve high-volume ophthalmology group practices.
Hospital pharmacies dominate current volume; specialty retail channels are gaining share fastest as maintenance therapy extends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and tax-advantaged biotech corridors in Switzerland concentrate anti-VEGF manufacturing infrastructure. These specialized economic zones attract contract manufacturing organizations through streamlined customs procedures and R&D tax credits. Wet AMD treatment access patterns diverge sharply across major markets based on reimbursement mechanics and specialist workforce distribution.
United States
Medicare Part B reimbursement clarity sustains high treatment volumes among patients over 75 in Florida and Arizona. The FDA's interchangeable biosimilar designation pathway accelerates payer formulary adoption for ranibizumab alternatives. Retinal specialist concentration in academic medical centers creates access bottlenecks for rural patients in the Mountain West and Great Plains states.
Germany
Statutory health insurance funds favor established anti-VEGF molecules with mature real-world safety databases. EMA extrapolation rules under the MDR framework permit indication expansion for ophthalmic biosimilars based on mechanistic similarity. University hospitals in Bavaria and Baden-Württemberg pilot sustained-release implant technologies for high-burden patients.
Japan
Aging demographics above 75 years expand treatment-eligible pools faster than specialist workforce growth. PMDA pharmacovigilance requirements impose extended post-market surveillance obligations on biosimilar entrants. Visiting nurse injection services in rural Tohoku and Kyushu regions address homebound elderly patient segments.
Switzerland
Active pharmaceutical ingredient manufacturing concentrates in Basel and Zurich biotech corridors serving global supply chains. Swissmedic enforces distinct biosimilar interchangeability standards that shape European market entry timelines. Contract manufacturing organizations in the Lemanic Arc region supply anti-VEGF drug substance to formulation facilities worldwide.
United Kingdom
NICE technology appraisals determine NHS England reimbursement for intravitreal therapies across primary care trusts. The MHRA post-Brexit regulatory framework maintains alignment with EMA pharmacovigilance requirements for ophthalmic biologics. London and Southeast England ophthalmology group practices capture diagnostic volume through in-house optical coherence tomography screening.
Wet Age-Related Macular Degeneration (Wet AMD) Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with originator biologics defending position through proprietary manufacturing scale while biosimilar entrants compress pricing power. The vendor base organizes around three strategic archetypes: integrated pharmaceutical conglomerates with ophthalmology franchises, pure-play retinal therapy developers, and contract manufacturing organizations supplying active pharmaceutical ingredient. Competitive moves concentrate on sustained-release delivery platform licensing and geographic expansion into Asia-Pacific markets.
Within the integrated pharmaceutical tier, Bayer AG and Novartis AG exemplify geographic diversification strategies across Asia-Pacific and European markets respectively. Regeneron Pharmaceuticals occupies a position emphasizing proprietary manufacturing scale and physician training networks. These three anchors represent divergent approaches to defending market position against biosimilar encroachment.
| Leading Market Players |
|---|
| Bayer AG |
| Gilead Sciences Inc. |
| Regeneron Pharmaceuticals Inc. |
| Apellis Pharmaceuticals Inc. |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bausch Health Companies Inc. |
| Kodiak Sciences Inc. |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Hospital pharmacy procurement departments in the United States, Germany, and Japan anchor pricing power through consolidated 340B and statutory insurance contracting, compressing margins for originator biologics while elevating interchangeable biosimilars. This buyer concentration forces manufacturers into value-based contracting tied to real-world efficacy data and injection frequency outcomes.
Pricing Analysis
Short lead-time premiums for temperature-sensitive anti-VEGF biologics command 15-25% markups over scheduled procurement cycles, while spot inventory discounts attract cost-sensitive clinics in rural markets. Three-tier pricing structure across premium originator, standard biosimilar, and economy bevacizumab segments stratifies access by reimbursement tier and patient mobility constraints. Pricing pressure stems from EMA extrapolation rules accelerating European biosimilar substitution and Medicare Part B reimbursement compression in the United States. German statutory health insurance funds exhibit highest price sensitivity through mandatory tendering, while Japanese academic medical centers absorb premium pricing for sustained-release implant pilot programs.
Supply Chain Analysis
Specialized biologics manufacturing workforce scarcity in Basel, Singapore, and Zurich biotech corridors constrains active pharmaceutical ingredient expansion for anti-VEGF fusion proteins and monoclonal antibodies. Supply chains draw from Swiss contract manufacturing organizations for drug substance, German university hospitals for clinical validation, and Japanese visiting nurse networks for last-mile injection delivery. Single-source vulnerability concentrates in E. coli expression system suppliers and biodegradable polymer implant materials. Distribution runs through hospital pharmacies with cold chain integrity requirements, though specialty retail channels are gaining share for stable maintenance patients with predictable dosing schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinal specialist workforce bottlenecks in academic medical centers prop pricing power for incumbent manufacturers, as limited injection capacity creates artificial scarcity that sustains premium reimbursement tiers for originator biologics.
For Market Incumbents: Extend proprietary manufacturing scale into sustained-release delivery platforms to convert variable injection revenue into predictable device procurement cycles. Defend against biosimilar encroachment by deepening physician training networks and locking hospital pharmacy contracts through real-world evidence partnerships. Vertical integration into biodegradable polymer supply buffers raw material cost volatility from Swiss and Singaporean contract manufacturers. For New Entrants and Emerging Players: Visiting nurse services and teleophthalmology platforms represent the most penetrable channel for homebound elderly segments in rural Japan and dispersed German regions. Target cost-sensitive clinics in United States Mountain West states where retinal specialist scarcity creates access gaps for maintenance injection patients. Pursue EMA interchangeable designation early to accelerate European payer formulary adoption and bypass originator loyalty programs. For Investors and Strategic Acquirers: The window for entry favors sustained-release delivery technology developers with Phase II implant data and established manufacturing partnerships in Basel or Singapore. Long-term viability hinges on gene therapy pipeline maturation offering curative alternatives to chronic anti-VEGF suppression. Watch FDA interchangeable biosimilar approval velocity as the inflection indicator for pricing compression timelines across Medicare Part B reimbursement pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Release Implant Development | Port delivery systems from Regeneron and hydrogel depots from academic medical centers extend dosing intervals from monthly to semi-annual administration. |
| Biosimilar Interchangeability Pathway | FDA designation accelerates payer formulary adoption and reduces prior authorization friction for ranibizumab and aflibercept alternatives in Medicare Part B. |
| Home Care Channel Expansion | Teleophthalmology oversight combined with visiting nurse injection services addresses rural and homebound patient segments in Japan and Germany. |
| Gene Therapy Pipeline Investment | Preclinical programs targeting complement pathway modulation at Apellis and Kodiak Sciences offer curative alternatives to chronic anti-VEGF suppression. |
| EMA Extrapolation Strategy | Mechanistic similarity rules permit indication expansion beyond reference product uses, compressing development timelines for second-generation ophthalmic biosimilars. |
Research Approach
Independent corroboration across formulary database audits, ClinicalTrials.gov registries, and CMS Medicare Part B claims data underwrites the qualitative findings on treatment volume and reimbursement dynamics. Primary interviews with retinal specialists, hospital pharmacy procurement managers, payer access specialists, and regulatory affairs leads at EMA and FDA complemented secondary validation from SEC 10-K filings, EMA submission documents, and GPO contract databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation forecasts.
Rate-of-change decomposition across the projection horizon disaggregates volume growth into aging demographic expansion, biosimilar substitution effects, and sustained-release technology adoption. Segmentation dimensions modeled include product type, end user site-of-care, treatment approach, and distribution channel, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differentiation. CAGRs derived from treatment-eligible population projections, injection frequency assumptions, and pricing tier migration patterns across originator, biosimilar, and off-label segments.
Caveats apply where FDA interchangeable designation delays, EMA pharmacovigilance requirement extensions, or retinal specialist workforce attrition could materially shift the outlook. Forecasts reflect assumptions on biosimilar uptake velocity, sustained-release implant commercialization timelines, and gene therapy regulatory pathways. Material deviation in these triggers warrants pause and re-evaluation of volume and value projections across the analysis window.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Rhabdomyosarcoma Market