
 North America Digital Radiology Market | 2026-2036
North America Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Radiology Market Analytics
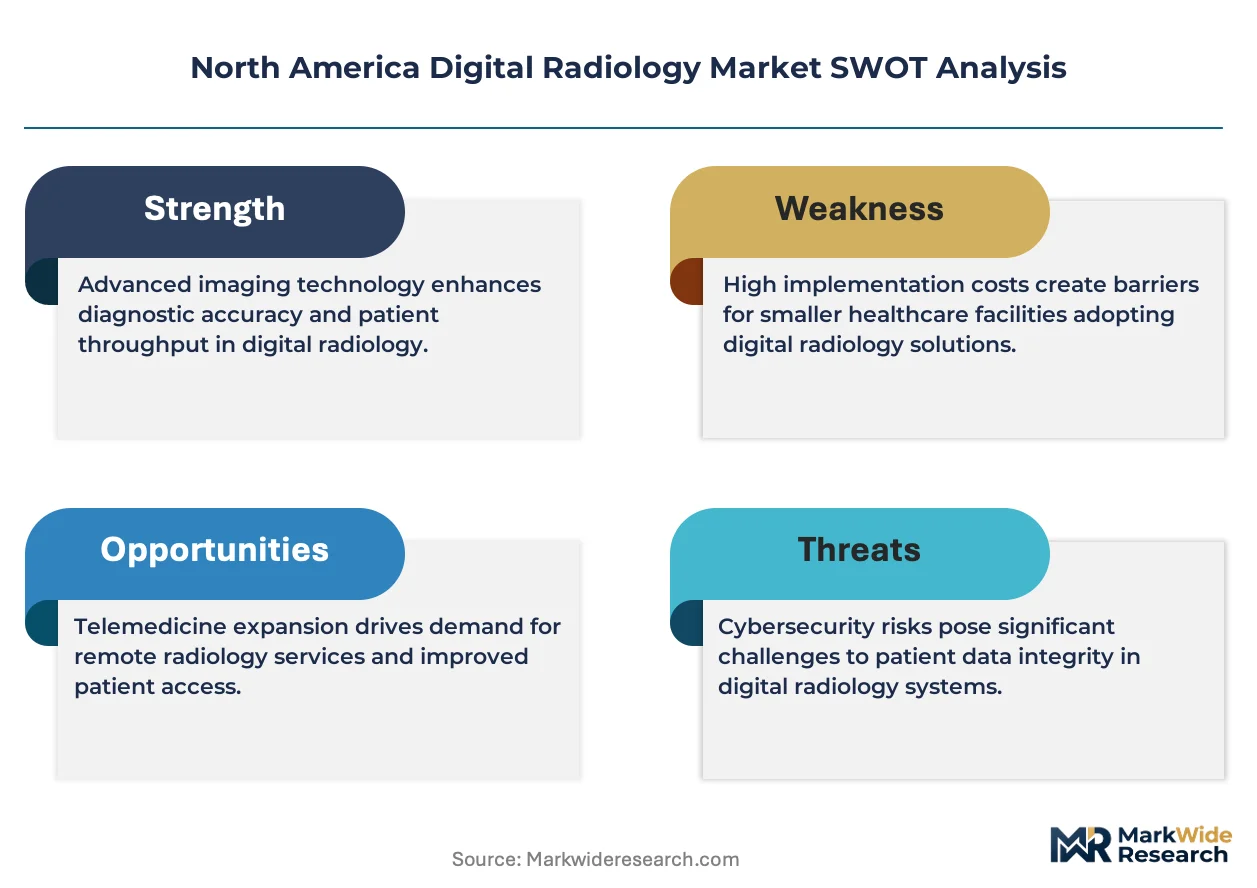
FDA 510(k) clearance cycles for digital radiology systems is collapsing from historical norms, compressing competitive windows for new entrants. GE Healthcare leverages its installed base of imaging platforms to sustain recurring service revenue across hospital networks. Siemens Healthineers anchors its North American position through direct detector manufacturing scale. Philips Healthcare differentiates via integrated informatics that connect radiology workflows to enterprise electronic health records.
Digital radiology encompasses the capture, processing, storage, and transmission of diagnostic images using solid-state detectors with spatial resolution typically exceeding 2.5 line pairs per millimeter, replacing analog film and phosphor plate technologies. CT scanners command the largest product type segment due to throughput advantages in emergency departments and trauma protocols. Direct radiography technology leads technology adoption among diagnostic centers seeking faster image acquisition than computed radiography cassette-based workflows. Oncology applications drive premium system configurations as staging protocols demand multi-planar reconstruction capabilities.
FDA quality system regulation and software-as-medical-device guidance govern product design controls and algorithm validation for AI-enhanced imaging. The Canadian regulatory framework through Health Canada aligns with FDA predicate device pathways while maintaining distinct labeling requirements. Stakeholders must monitor evolving reimbursement thresholds from CMS for radiology procedures that determine capital equipment purchasing cycles.
Market Dynamics
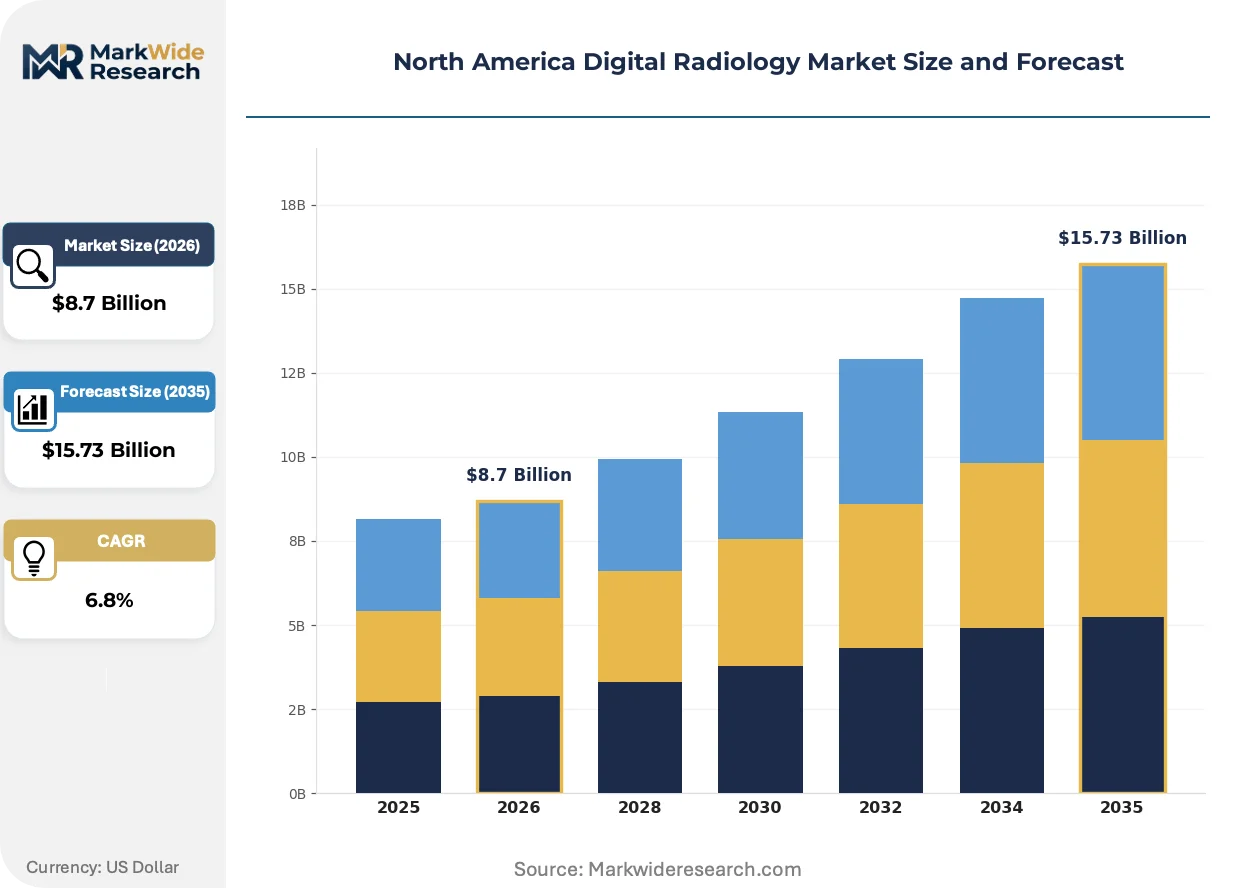
Hospital capital budgets across the United States are compressing replacement cycles for analog-to-digital radiology transitions as CMS reimbursement thresholds tighten and outpatient imaging center construction accelerates in Sun Belt states.
Growth Catalysts
- CMS Reimbursement Alignment:Medicare payment schedules for digital radiology procedures now favor detector-based systems over computed radiography, pulling hospital procurement decisions toward direct radiography platforms.
- Sun Belt Imaging Center Construction:Outpatient diagnostic facilities in Texas, Florida, and Arizona are outpacing national construction averages, concentrating equipment demand in high-migration corridors.
- AI-Enhanced Workflow Integration:FDA software-as-medical-device guidance for algorithm validation is creating predictable pathways for vendors to embed diagnostic assistance into radiology informatics stacks.
Market Restraints
- Detector Manufacturing Concentration:Direct radiography flat-panel detector supply concentrates among East Asian component fabricators, exposing North American OEMs to input volatility and logistics friction.
- FDA 510(k) Cycle Compression:Accelerated clearance timelines for predicate device pathways are narrowing competitive windows for new entrants to establish installed bases before incumbent refresh cycles.
- Computed Radiography Residual Value:Cassette-based systems retain operational utility in low-volume rural clinics, delaying full market conversion and fragmenting replacement demand.
Strategic Opportunities
- Canadian Health System Modernization:Health Canada's alignment with FDA predicate pathways creates expedited market access for vendors already cleared in the United States, with distinct labeling requirements as the primary adaptation.
- Oncology Staging Protocol Convergence:Multi-planar reconstruction capabilities for cancer diagnosis are driving premium system configurations in academic medical centers and specialized cancer institutes.
- Enterprise EHR Integration:Radiology informatics that connect imaging workflows to hospital electronic health records are differentiating vendor offerings as health systems consolidate IT infrastructure.
Industry Challenges
- AI Algorithm Validation Talent:FDA quality system regulation demands specialized expertise in software design controls and clinical validation protocols that outpaces current workforce supply.
- Legacy PACS Integration Complexity:New digital detector arrays must interface with heterogeneous picture archiving and communication systems across hospital networks, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Radiology Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, CT Scanners, MRI, Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Computed Radiography, Direct Radiography, Hybrid Systems, Digital Fluoroscopy Application: Oncology, Orthopedics, Cardiovascular, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Carestream Health, Agfa-Gevaert Group, Konica Minolta, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Radiology Market Evolving Landscape
Workflow automation and detector material science are compressing image acquisition times while regulatory frameworks for artificial intelligence reshape product development roadmaps across the vendor landscape.
Direct radiography is supplanting computed radiography in diagnostic centers seeking faster throughput. Hospital emergency departments and trauma protocols are adopting solid-state detector arrays with spatial resolution exceeding 2.5 line pairs per millimeter. This transition is supplanting cassette-based workflows that require manual handling and separate scanning stations, collapsing examination room turnaround times.
FDA software-as-medical-device guidance governs algorithm validation for AI-enhanced imaging systems. The regulation mandates specific design controls and clinical performance documentation that extend development timelines. Vendors targeting oncology applications face the most stringent documentation requirements as staging protocols demand reproducible multi-planar reconstruction capabilities.
After-sales service unbundling is fragmenting traditional vendor-customer relationships. Hospital procurement departments are separating equipment purchases from maintenance contracts, engaging third-party service providers for detector calibration and software updates. This pattern is most visible in the American Sun Belt states where independent outpatient imaging centers lack capital reserves for bundled long-term agreements.
North America Digital Radiology Market Segmentation
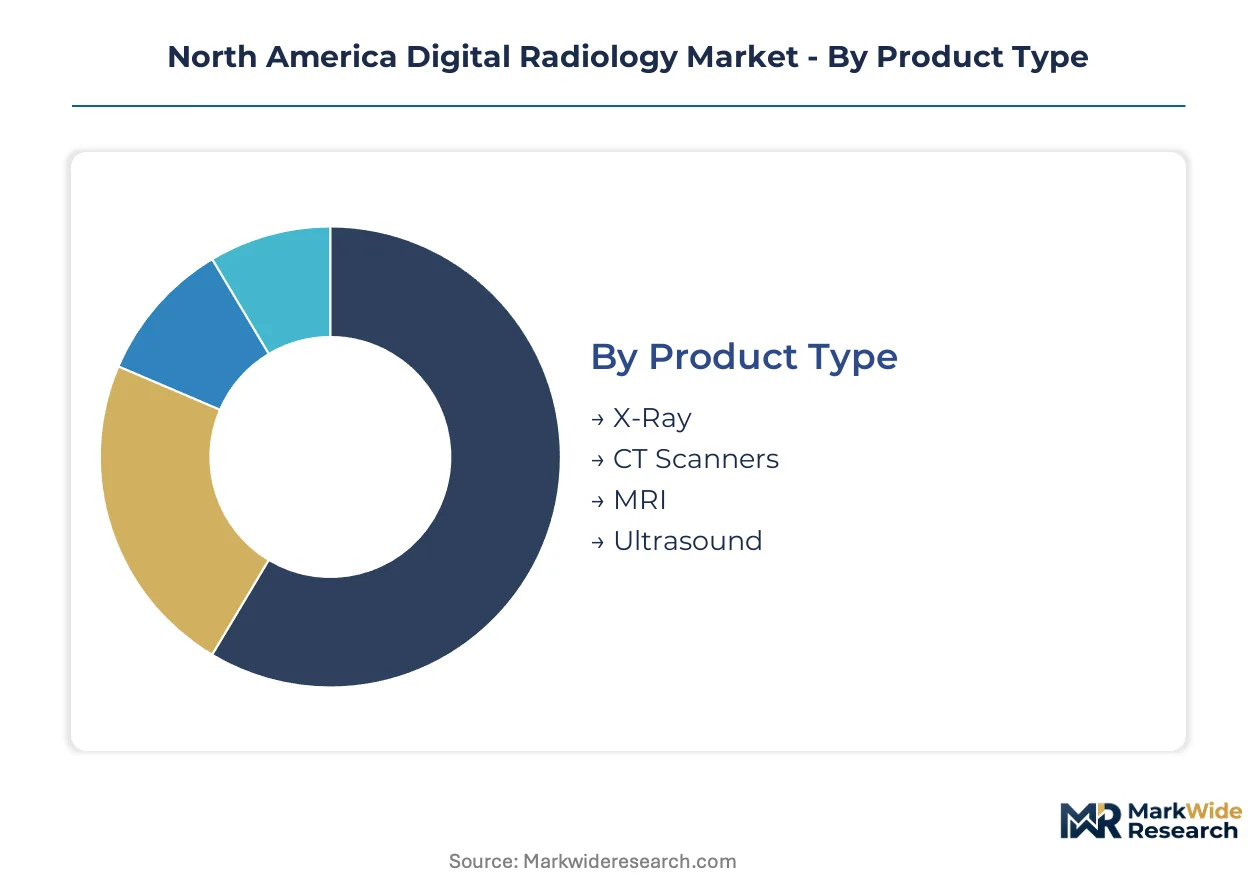
Digital radiology equipment segments diverge sharply in capital intensity and replacement velocity. Understanding margin distribution across product types, technologies, and end-use settings clarifies where vendors can defend pricing power.
Product Type:
Margin pools concentrate in systems requiring precision mechanical subsystems and software integration rather than commodity detector assemblies.
- CT Scanners:Multi-slice helical systems with sub-millimeter isotropic resolution dominate emergency department throughput requirements. Texas and Florida hospital systems are prioritizing 256-slice configurations for trauma protocols as Sun Belt population growth strains imaging capacity.
- X-Ray:Fixed and mobile radiography units with solid-state flat-panel detectors deliver the highest unit volumes. Diagnostic centers across Arizona are standardizing on wireless detector platforms to collapse room turnaround times and maximize daily examination throughput.
- MRI:Superconducting magnet systems with 1.5T and 3T field strengths serve neurovascular and musculoskeletal protocols. Academic medical centers anchor demand for advanced gradient performance.
- Ultrasound:Cart-based and point-of-care systems with matrix array transducers address cardiac and abdominal imaging. Clinics favor portable configurations for bedside deployment flexibility.
CT Scanners hold installed capacity. X-Ray is rotating up the share rankings.
End User:
Procurement authority and capital access differentiate customer segments more than clinical application requirements.
- Hospitals:Integrated health systems with centralized purchasing negotiate enterprise imaging contracts spanning multiple facilities. CMS reimbursement thresholds directly shape their capital equipment refresh cycles.
- Diagnostic Centers:Independent outpatient facilities concentrate in Sun Belt migration corridors where construction activity outpaces national averages. These operators prioritize detector-based systems that maximize daily throughput per room.
- Clinics:Primary care and specialty practices with limited capital reserves favor refurbished equipment and third-party service contracts over bundled vendor agreements.
- Research Institutions:Academic medical centers and university hospitals drive demand for premium configurations with advanced reconstruction algorithms and multi-planar capabilities.
Hospitals command procurement volume. Diagnostic Centers are expanding footprint fastest.
Technology:
Technology selection determines workflow velocity and total cost of ownership across examination room operations.
- Direct Radiography:Amorphous silicon or selenium-based flat-panel detectors capture images in seconds without cassette handling. Diagnostic centers across the American Sun Belt are displacing computed radiography to achieve higher daily examination volumes.
- Computed Radiography:Photostimulable phosphor plates require separate scanning stations and manual cassette workflows. Rural clinics retain these systems where low daily volumes cannot justify direct radiography capital outlays.
- Digital Fluoroscopy:Real-time image acquisition systems with pulsed exposure modes support interventional and gastrointestinal procedures. Cardiovascular applications anchor demand for high frame-rate configurations.
- Hybrid Systems:Dual-modality platforms combining radiography with fluoroscopy or tomography address specialized orthopedic and trauma protocols. Academic centers evaluate these for protocol consolidation.
Direct Radiography holds technology leadership. Digital Fluoroscopy is climbing the fastest.
Application:
Clinical application determines system configuration complexity and reimbursement intensity.
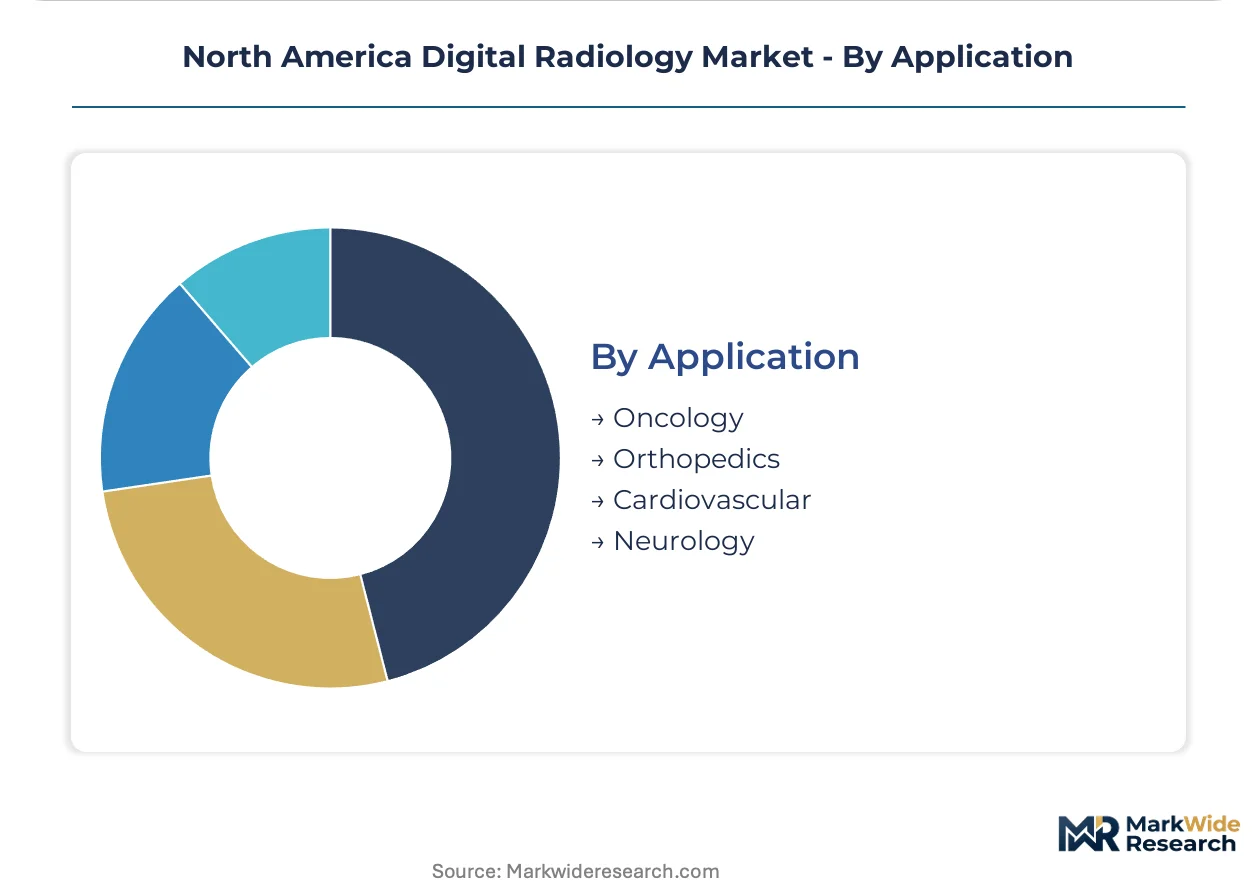
- Oncology:Staging protocols demand multi-planar reconstruction and contrast-enhanced imaging capabilities. Cancer institutes configure premium CT and MRI systems for treatment planning precision.
- Orthopedics:Weight-bearing radiography and high-resolution extremity imaging drive demand for specialized detector formats. Sports medicine centers prioritize mobile C-arm systems for intraoperative guidance.
- Cardiovascular:Coronary CT angiography and cardiac MRI require temporal resolution below 100 milliseconds. Academic medical centers anchor demand for advanced reconstruction algorithms.
- Neurology:Brain perfusion imaging and functional MRI protocols depend on high-field magnet stability and gradient performance. Stroke centers prioritize rapid acquisition sequences.
Oncology commands premium pricing. Orthopedics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and independent diagnostic centers concentrate equipment demand in migration corridors with favorable reimbursement environments. Buyer archetypes split between integrated health systems negotiating enterprise contracts and outpatient operators prioritizing throughput per room.
United States
The American Sun Belt anchors equipment demand as Texas, Florida, and Arizona outpatient imaging centers outpace national construction averages. FDA 510(k) clearance cycles for digital radiology systems compress competitive windows for new market entrants. Houston and Phoenix metropolitan clusters concentrate detector-based system deployments where population growth strains imaging capacity.
Canada
Provincial health system modernization drives replacement of analog film-based systems across Ontario and Quebec hospital networks. Health Canada's alignment with FDA predicate device pathways expedites market access for vendors already cleared in the United States. Toronto and Montreal academic medical centers anchor demand for premium CT configurations with multi-planar reconstruction capabilities.
Mexico
Private hospital chains in Mexico City and Monterrey accelerate digital detector array adoption as medical tourism infrastructure expands. COFEPRIS regulatory pathways for medical devices maintain distinct documentation requirements from FDA frameworks. Guadalajara's diagnostic center cluster concentrates mid-range radiography system deployments serving regional referral networks.
North America Digital Radiology Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with installed base leverage. Three multinational healthcare technology groups dominate procurement negotiations through enterprise imaging contracts spanning hospital networks. Strategic archetypes include platform-integrated service providers, direct detector manufacturers, and informatics-focused workflow integrators. Competitive moves center on recurring service revenue capture and AI-enhanced software stack differentiation.
Within the platform-integrated tier, GE Healthcare leverages imaging platform installed bases to sustain service revenue across United States hospital networks. Siemens Healthineers anchors its North American position through direct detector manufacturing scale. Philips Healthcare exemplifies the informatics-focused archetype via radiology workflow integration with enterprise electronic health records.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Agfa-Gevaert Group |
| Konica Minolta |
| Hologic |
| Others |
Value Network & Pricing Analysis
Ninety-day detector inventory cycles at East Asian component fabricators directly determine pricing leverage for North American OEMs, compressing margin buffers when logistics friction spikes and amplifying buyer power during supply gluts.
Pricing Analysis
Cost-plus contracts with rare-earth indexation dominate flat-panel detector procurement, tethering equipment pricing to neodymium and terbium spot movements. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center configurations from outpatient diagnostic center bundles and refurbished rural clinic systems. Pricing pressure stems from CMS reimbursement threshold compression, forcing vendors to absorb detector cost volatility rather than pass through to hospital procurement committees. Independent diagnostic centers in Sun Belt states exhibit highest price sensitivity due to capital reserve constraints, while integrated health systems leverage enterprise contract scale for least sensitivity.
Supply Chain Analysis
Port of Long Beach throughput constraints expose detector manufacturing concentration across South Korea, Japan, and Taiwan to cascading delivery delays. Amorphous silicon substrates, selenium deposition chambers, and scintillator crystals feed from specialized chemical processing clusters in these jurisdictions. Single-source vulnerability concentrates in photodiode array fabrication, where qualified secondary suppliers require twelve-month validation cycles. Distribution runs through OEM direct sales forces for hospital systems and independent imaging equipment distributors serving outpatient diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device guidance for AI-enhanced imaging creates a regulatory inflection that rewards algorithm validation capabilities and punishes hardware-only vendors, positioning this market for high-growth disruption through informatics differentiation.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance algorithms into service contracts before third-party calibration vendors capture aftermarket share. Deepen backward integration into direct detector manufacturing to reduce exposure to East Asian component volatility, while accelerating Health Canada parallel submissions to exploit predicate pathway alignment.
For New Entrants and Emerging Players: AI algorithm validation talent scarcity in FDA quality system regulation compliance creates a service-layer gap where incumbents under-serve mid-tier diagnostic centers. Penetrate the Arizona and Texas outpatient imaging center clusters through subscription-based informatics bundles that separate software purchasing from capital equipment procurement, avoiding head-to-head detector pricing competition with Siemens Healthineers and GE Healthcare.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because radiology informatics integration with enterprise EHR systems creates winner-take-most dynamics in hospital network procurement. Target acquisition profiles should emphasize vendors with FDA-cleared AI algorithms and established GPO contract relationships. Monitor Health Canada approval velocity for US-cleared devices as the signal indicating regulatory pathway efficiency and near-term market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | Software-as-medical-device clearance unlocks premium pricing in oncology staging configurations. |
| Detector Manufacturing Scale-Up | Captive amorphous silicon production insulates margins from rare-earth price volatility. |
| Hospital System Partnership | Enterprise EHR integration contracts lock out competing informatics vendors. |
| Third-Party Service Unbundling | Independent calibration offerings fragment traditional vendor recurring revenue streams. |
| Sun Belt Geographic Expansion | Texas and Arizona diagnostic center construction concentrates equipment demand growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, outpatient imaging center operations directors, GPO contracts managers, and radiology informatics specialists. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement records, and Health Canada medical device licensing filings. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis were triangulated to converge on market sizing.
Across the analysis window, forecasts were constructed through segmented modeling by product type, technology adoption curve, end-user capital access tier, and clinical application intensity. CAGRs were derived from equipment replacement velocity patterns and reimbursement threshold elasticity. Detector manufacturing capacity expansion timelines and AI algorithm validation pipeline throughput served as industry-specific demand-side and supply-side forecast inputs.
Forecasts assume regulatory continuity in FDA software-as-medical-device guidance and Health Canada predicate alignment; material policy shifts would require re-modeling clearance timeline assumptions and cross-border market access protocols. Practitioners should keep alternative scenarios live as CMS reimbursement compression intensity and East Asian logistics friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
India Mammography Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Functional Brain Imaging Systems Market