
 Australia Spinal Surgery Devices Market | 2026-2036
Australia Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Spinal Surgery Devices Market Outlook
Private orthopedic clinics is reorganizing procurement patterns across the Australia spinal surgery devices landscape, displacing traditional hospital-centric purchasing as ambulatory capabilities expand. Stryker Corporation leverages its integrated instrument-and-implant portfolio to sustain channel relationships with these emerging buyers. Medtronic PLC anchors its position through deep robotic-assisted surgery infrastructure. Evolution Surgical competes on specialized distribution reach into regional Australian markets.
Australia spinal surgery devices encompass implantable hardware, precision instruments, biologic graft materials, and specialized surgical tables designed to stabilize, decompress, or correct spinal pathologies, typically manufactured from titanium alloys, PEEK polymers, or demineralized bone matrix with fatigue resistance exceeding ten million cycles. Their primary purpose is restoring structural integrity and neurological function in patients with degenerative, traumatic, or deformity-related spinal conditions. Implants and instruments together command the dominant revenue share, reflecting the high unit value of pedicle screw systems and interbody cages. Minimally invasive surgery technology represents the fastest-expanding application mode, as smaller incisions reduce recovery times and expand eligibility for outpatient settings. Biomaterials remain a concentrated margin pool, where synthetic bone graft substitutes and cellular matrices differentiate premium offerings from commodity hardware.
TGA registration requirements under the Australian Register of Therapeutic Goods shape market access timelines and clinical evidence standards for all implantable spinal devices. The Medical Device Regulation framework, aligned with EU MDR convergence pathways, elevates post-market surveillance obligations and biocompatibility documentation. Stakeholders must monitor TGA reclassification timelines and state-level hospital procurement consolidation to anticipate which compliance investments will determine competitive viability.
Market Dynamics
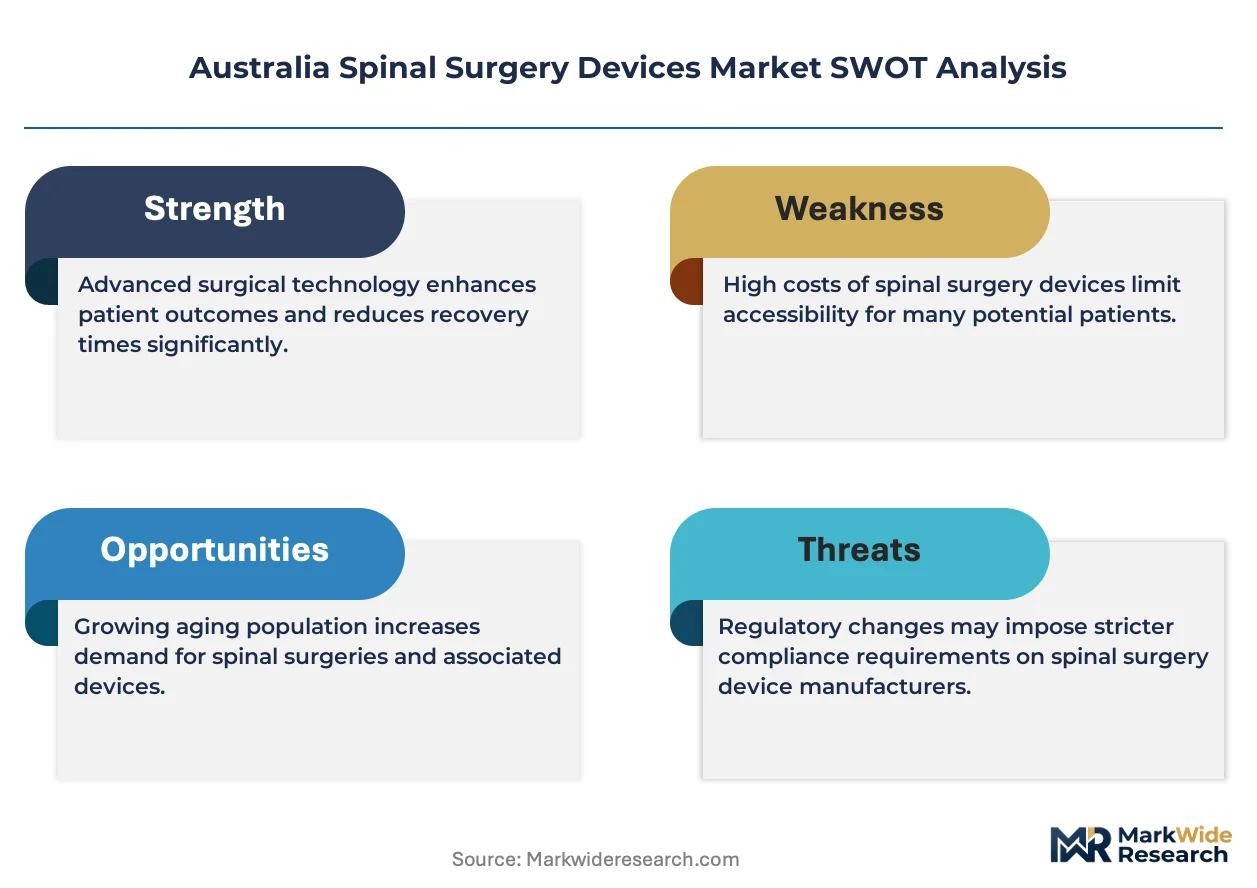
Private orthopedic clinics in New South Wales and Victoria are accelerating procedural capacity expansion, diverting spinal fusion volumes from metropolitan hospitals and forcing device manufacturers to restructure channel relationships around ambulatory surgical capabilities.
Growth Catalysts
- Minimally invasive surgery technology:Smaller incisions reduce recovery times and expand patient eligibility for outpatient settings, particularly in private clinics across Sydney and Melbourne.
- TGA regulatory alignment with EU MDR:Convergence pathways elevate post-market surveillance standards, creating competitive moats for manufacturers with robust clinical evidence portfolios.
- Queensland regional hospital upgrades:Public infrastructure investment in Brisbane and Gold Coast facilities is expanding surgical volumes beyond traditional demand centers.
Market Restraints
- Titanium alloy price volatility:Raw material cost fluctuations compress margins on pedicle screw systems and interbody cages, particularly affecting mid-tier suppliers.
- Biologics supply concentration:Synthetic bone graft substitute production clusters with limited domestic manufacturers, creating import dependency for demineralized bone matrix.
- Extended TGA registration timelines:The Australian Register of Therapeutic Goods approval processes delay market entry for novel implantable hardware by 18-24 months relative to European benchmarks.
Strategic Opportunities
- Western Australia underpenetration:Perth and regional centers maintain lower spinal surgery density per capita than eastern states, offering volume expansion potential for distributors with specialized logistics.
- Robotic-assisted surgery convergence:Integration of navigation platforms with implant systems creates bundled value propositions for high-volume private hospital groups.
- Day surgery licensing reforms:State-level regulatory changes in Victoria are enabling extended recovery stays in ambulatory facilities, broadening procedure mix eligibility.
Industry Challenges
- Specialized surgical training deficits:Fellowship-trained spine surgeons concentrate in Sydney and Melbourne, constraining procedural expansion in Adelaide and Brisbane markets.
- Legacy hospital information system integration:Implant tracking and inventory management platforms require costly middleware development to interface with state health procurement networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Spinal Surgery Devices Market |
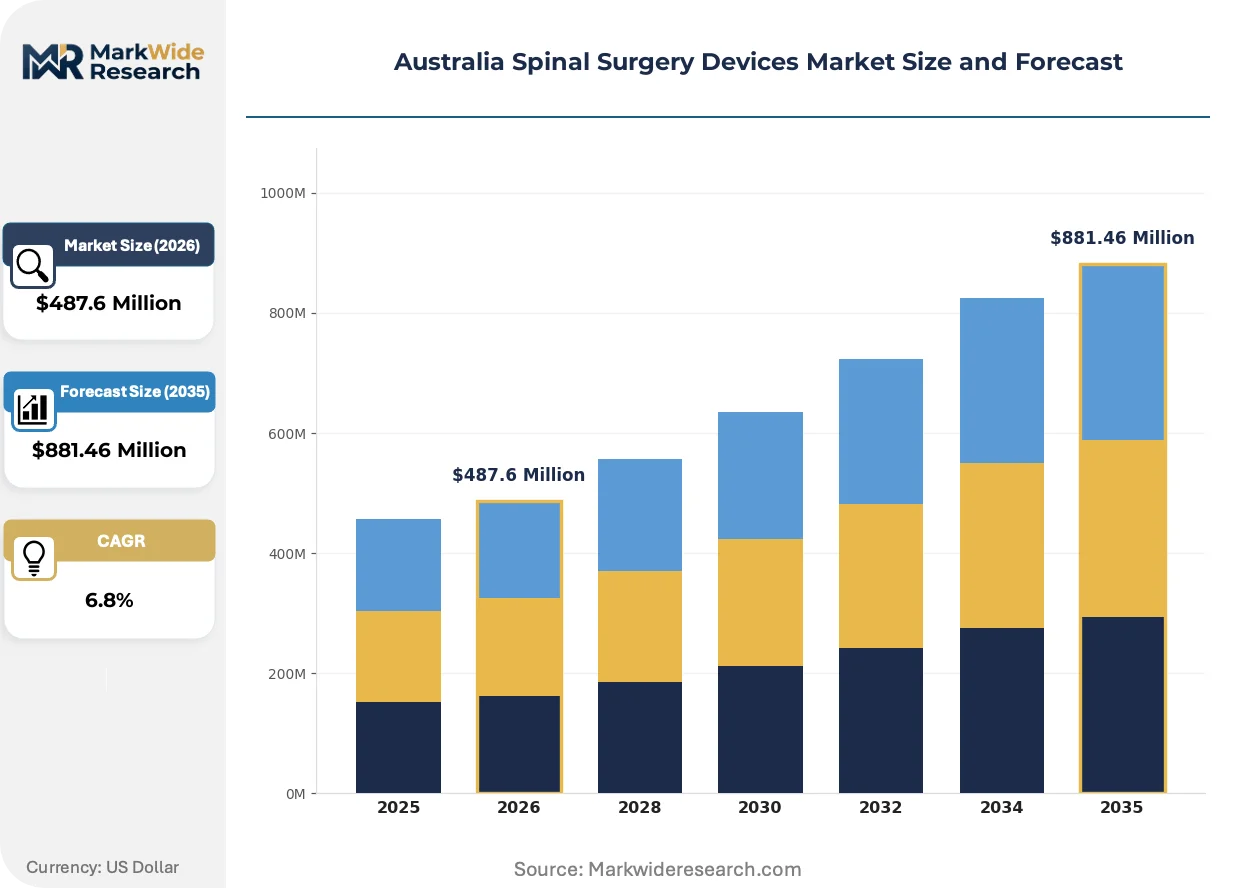
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Instruments, Biomaterials, Surgical Tables Technology: Robotic-Assisted Surgery, Minimally Invasive Surgery, Traditional Surgery, Augmented Reality End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, Orthopedic Clinics Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Zimmer Biomet Holdings Inc., Stryker Corporation, DePuy Synthes Spine Inc. (Johnson & Johnson), Evolution Surgical, KARL STORZ, Medtronic PLC, Orthofix Holdings Inc., Prism Surgical, NuVasive Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Spinal Surgery Devices Market Strategic Shifts
Device manufacturers are reconfiguring product architectures around outpatient compatibility, compressing instrument footprints and prioritizing sterile-packed convenience to match the operational rhythms of ambulatory surgical centers.
PEEK polymer interbody cages are displacing titanium alternatives in single-level fusions performed at private orthopedic clinics, where radiolucency and modulus-matching properties reduce subsidence rates. Surgeons in Victoria's day surgery facilities are adopting these devices at twice the rate of traditional hospital settings. The shift is compressing average selling prices for titanium cage systems while expanding addressable procedure volumes.
TGA's Medical Device Regulation framework is tightening biocompatibility documentation requirements for implantable spinal hardware, extending pre-market assessment durations. Manufacturers with existing EU MDR certifications gain accelerated pathway access, while domestic-only suppliers face elongated evidence generation cycles. Pediatric deformity correction devices encounter the steepest compliance escalation under revised classification rules.
Hospital procurement consolidation in New South Wales is centralizing purchasing authority for spinal implants under state health network tenders, displacing individual facility contracting. Private clinic groups in Sydney are responding by forming buying cooperatives to preserve volume leverage. The tension is most acute for mid-tier distributors serving mixed public-private customer bases.
Australia Spinal Surgery Devices Market Segmentation
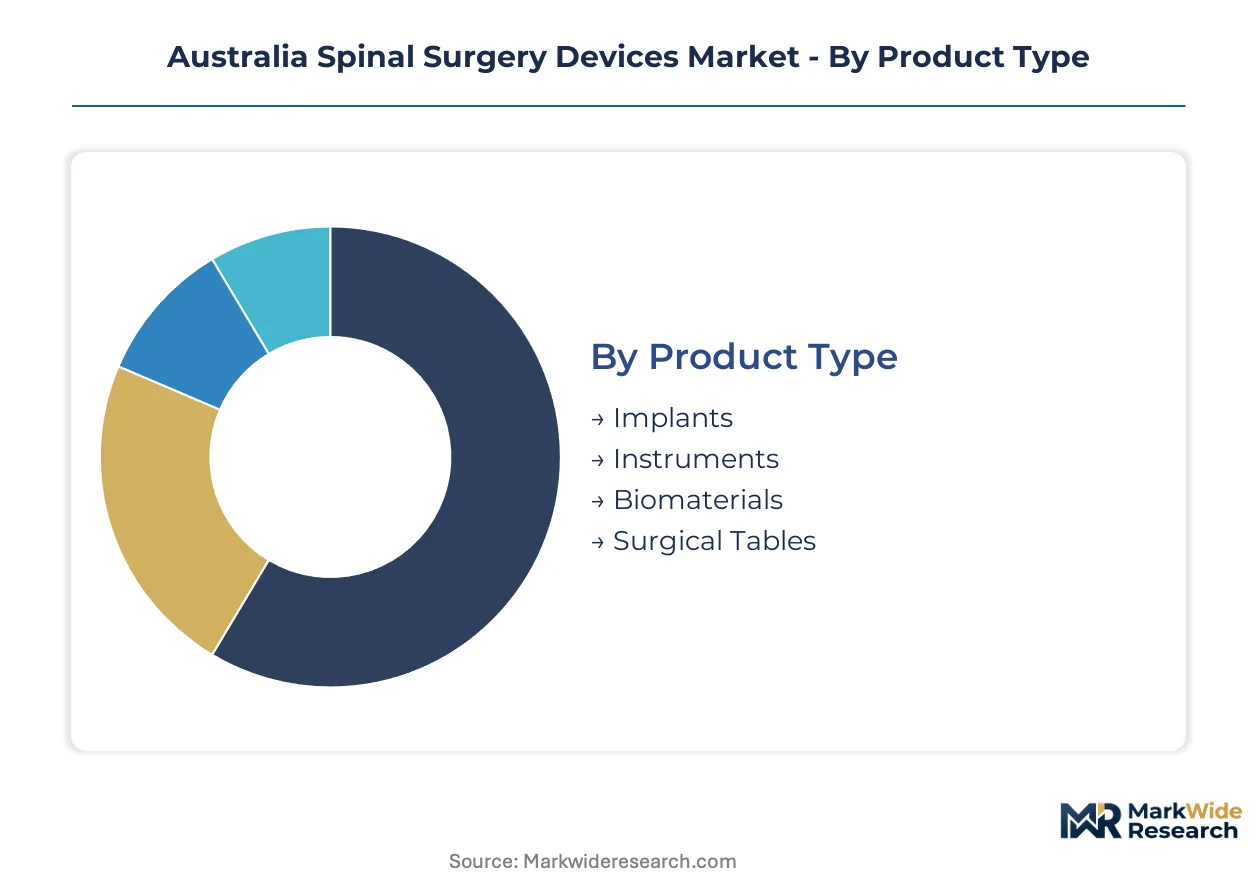
Spinal surgery device segmentation in Australia reflects divergent regulatory pathways under TGA's Australian Register of Therapeutic Goods, where implantable hardware faces stricter biocompatibility documentation than capital equipment. Manufacturers must align product portfolios with these compliance tiers to optimize market entry timelines.
Product Type:
TGA classification rules differentiate implantable devices from non-implantable equipment, elevating clinical evidence requirements for hardware that remains in the body.
- Implants:Titanium alloy pedicle screw systems and PEEK polymer interbody cages dominate revenue concentration. Sydney and Melbourne private orthopedic clinics drive demand for modulus-matched cages that reduce subsidence rates in single-level fusions.
- Instruments:Precision-machined retractors, drills, and navigation probes manufactured from surgical-grade stainless steel. Queensland regional hospital upgrades are expanding instrument procurement beyond traditional New South Wales and Victoria demand centers.
- Biomaterials:Demineralized bone matrix and synthetic graft substitutes face import dependency constraints with limited domestic manufacturing.
- Surgical Tables:Motorized positioning systems with radiolucent tops for intraoperative imaging compatibility.
Established volume favors Implants; emerging adoption favors Biomaterials as synthetic substitutes displace autograft harvesting.
Technology:
Reimbursement differentiation across Australian states shapes technology adoption curves, with private insurers more readily covering advanced navigation than public hospital networks.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce tissue disruption and enable outpatient eligibility. Victoria's day surgery licensing reforms are accelerating MIS adoption in Melbourne ambulatory facilities.
- Robotic-Assisted Surgery:Navigation-integrated implant placement platforms command premium positioning in high-volume private hospital groups. Adelaide and Brisbane markets show constrained penetration due to specialized surgical training deficits.
- Traditional Surgery:Open posterior approaches with direct visualization remain standard for complex deformity corrections.
- Augmented Reality:Head-mounted displays overlaying preoperative planning onto surgical fields.
Procedure economics favor Minimally Invasive Surgery; capital investment cycles favor Robotic-Assisted Surgery.
End User:
Procurement authority fragmentation between public hospital networks and private clinic cooperatives creates divergent channel strategies.
- Hospitals:Metropolitan facilities in New South Wales anchor complex fusion volumes with centralized purchasing under state health network tenders.
- Orthopedic Clinics:Sydney and Melbourne private practices are reorganizing procurement through buying cooperatives to preserve volume leverage against manufacturer pricing.
- Ambulatory Surgical Centers:Extended recovery stay authorizations in Victoria are broadening procedure mix eligibility for lumbar decompressions.
- Rehabilitation Centers:Post-acute facilities managing non-operative spinal care and recovery monitoring.
Contract consolidation favors Hospitals; margin expansion favors Orthopedic Clinics.
Application:
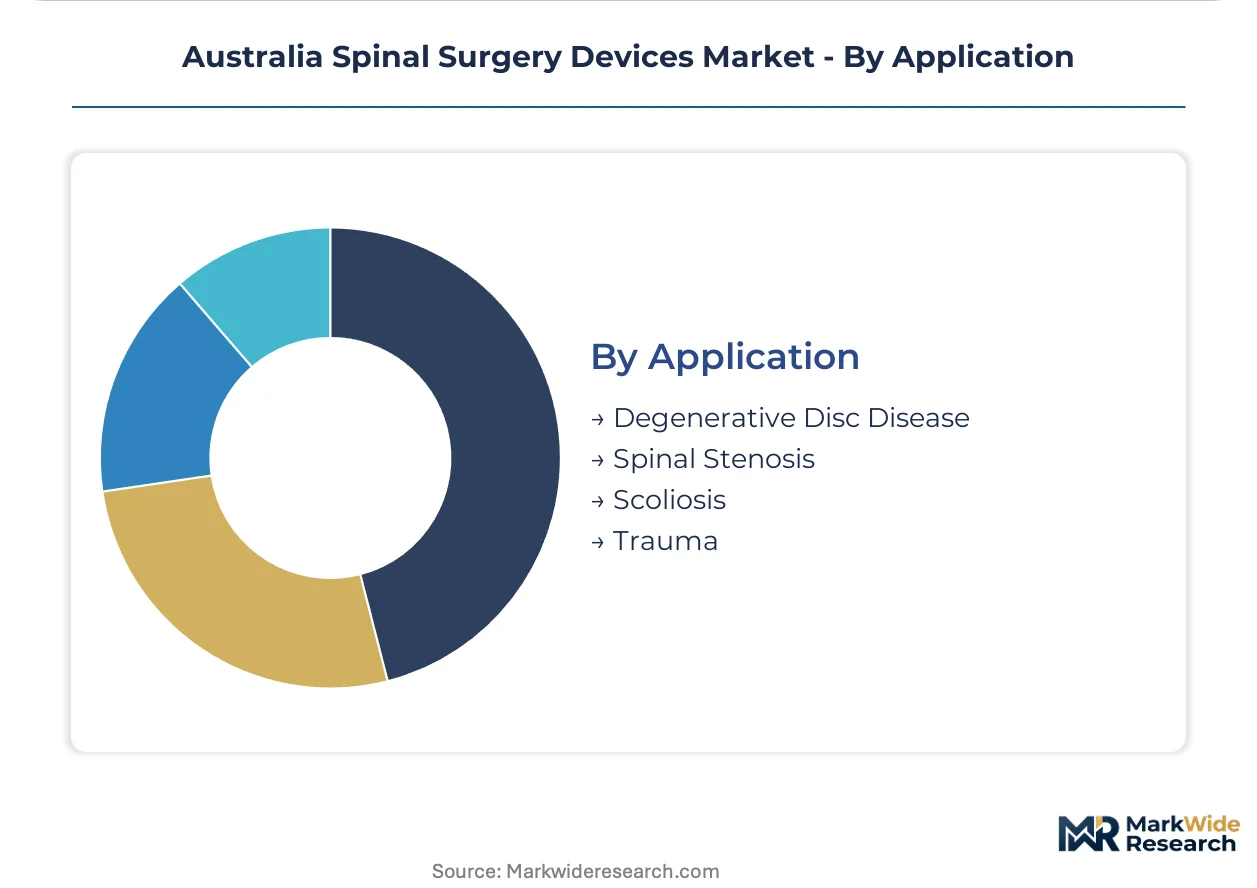
Patient demographics and surgical complexity determine device selection criteria across pathology types.
- Degenerative Disc Disease:Interbody fusion devices and motion-preserving disc replacements address the highest procedure volume. Perth and Western Australia regional centers show underpenetration relative to eastern state benchmarks.
- Spinal Stenosis:Decompression instruments and interspinous spacers target geriatric patient expansion. TGA reclassification of pediatric deformity devices creates compliance escalation for early-onset scoliosis hardware.
- Scoliosis:Multi-level correction systems with derotation capabilities for adolescent and adult deformity.
- Trauma:Stabilization hardware for fracture management and spinal cord injury protocols.
Volume concentration favors Degenerative Disc Disease; regulatory complexity favors Spinal Stenosis as aging demographics intersect with TGA surveillance expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss precision instrument manufacturers export spinal navigation platforms to Australian private hospital networks, while US-based implant specialists supply titanium pedicle screw systems through Sydney distribution hubs.
New South Wales
Metropolitan Sydney hospitals anchor complex spinal fusion volumes through centralized state health network tenders. TGA registration requirements under the Australian Register of Therapeutic Goods shape procurement compliance timelines for implantable hardware entering this market. Private orthopedic clinics in North Sydney and Parramatta are reorganizing procurement through buying cooperatives to preserve volume leverage against manufacturer pricing consolidation.
Victoria
Melbourne ambulatory surgical centers drive demand for PEEK polymer interbody cages and minimally invasive surgery technology with smaller instrument footprints. Day surgery licensing reforms enable extended recovery stays, broadening procedure mix eligibility for lumbar decompressions. Surgeon adoption of radiolucent cages in Victoria's private clinics runs at twice the rate of traditional hospital settings.
Queensland
Public infrastructure investment in Brisbane and Gold Coast facilities expands surgical volumes beyond traditional eastern state demand centers. Regional hospital upgrades are accelerating instrument procurement for degenerative disc disease procedures. Spine surgeon training deficits in Adelaide and Brisbane constrain robotic-assisted surgery penetration despite capital equipment availability.
Western Australia
Perth and regional centers maintain lower spinal surgery density per capita than eastern states, creating volume expansion potential for distributors with specialized logistics capabilities. Underpenetration in degenerative disc disease procedures relative to New South Wales benchmarks signals addressable market opportunity. Biomaterials import dependency concentrates supply risk for demineralized bone matrix in this isolated geography.
Australia Spinal Surgery Devices Market Competitive Environment
Player mix skews toward multinational implant manufacturers with integrated instrument portfolios and specialized regional distributors serving mixed public-private customer bases. Market structure concentrates around three strategic tiers: global orthopedic conglomerates with robotic-assisted surgery infrastructure, mid-tier suppliers competing on titanium alloy hardware pricing, and niche biomaterials specialists addressing synthetic graft substitute demand. Dominant competitive moves include portfolio diversification into outpatient-compatible device architectures and strategic partnerships with private clinic buying cooperatives to secure volume commitments.
Among US-based orthopedic conglomerates, Stryker Corporation and Medtronic PLC exemplify the integrated-systems archetype, anchoring positions through deep navigation platform infrastructure and channel relationships with high-volume private hospital groups. Evolution Surgical represents the specialized distribution archetype, occupying a position focused on regional Australian market reach outside metropolitan Sydney and Melbourne corridors. Zimmer Biomet Holdings Inc. and DePuy Synthes Spine Inc. sit within the comprehensive implant portfolio tier, serving state health network tender requirements with broad hardware offerings spanning pedicle screw systems and interbody cages.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings Inc. |
| Stryker Corporation |
| DePuy Synthes Spine Inc. (Johnson & Johnson) |
| Evolution Surgical |
| KARL STORZ |
| Medtronic PLC |
| Orthofix Holdings Inc. |
| Prism Surgical |
| NuVasive Inc. |
| Others |
Value Chain & Pricing Dynamics
TGA's Australian Register of Therapeutic Goods certification tiers simultaneously gate supplier qualification and stratify price positioning, as EU MDR-aligned documentation requirements elevate compliance costs that manufacturers recover through premium positioning on implantable hardware while mid-tier competitors absorb margin compression on non-certified alternatives.
Pricing Analysis
Next-generation robotic-assisted surgery platforms command 40-60% premiums over conventional navigation systems, while prior-generation titanium pedicle screw systems face commoditization in state health network tenders. Three-tier pricing structure across premium, standard, and economy levels reflects TGA certification status and clinical evidence depth, with private orthopedic clinics in Sydney and Melbourne showing lowest price sensitivity due to bundled procedure economics, and regional Queensland hospitals exhibiting acute sensitivity to titanium alloy cost fluctuations.
Supply Chain Analysis
Strategic stockpiling of PEEK polymer feedstock dominates inventory strategy among Australian distributors, buffering against six-month ocean freight cycles from Germany and Switzerland. Manufacturing concentration in the United States, Germany, and Switzerland anchors precision instrument supply, while titanium alloy forging depends on Japanese and Chinese metallurgical suppliers. Single-source vulnerability concentrates in demineralized bone matrix, where limited domestic biologics manufacturing forces reliance on US tissue banks. Distribution runs through Sydney-based specialized medical device distributors with direct hospital and clinic field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private clinic procedural expansion constitutes a high-growth disruption, as Victoria's day surgery licensing reforms reclassify spinal fusion eligibility and compress hospital-centric volume concentration.
For Market Incumbents: Secure channel control through exclusive instrument-and-implant bundling contracts with emerging private clinic buying cooperatives in North Sydney and Parramatta, while accelerating EU MDR certification pathways to maintain TGA registration velocity against emerging competitors lacking parallel regulatory infrastructure. For New Entrants and Emerging Players: TGA's Medical Device Regulation fast-track for EU MDR-certified manufacturers creates expedited market entry, enabling penetration of Western Australia's underpenetrated Perth regional centers where specialized logistics capabilities remain scarce and incumbent distributor relationships are underdeveloped. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational orthopedic conglomerates divesting non-core instrument portfolios, particularly precision-machined retractor and navigation probe product lines that regional Australian distributors could integrate with captive PEEK cage distribution to capture margin expansion in ambulatory surgical center channels.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Fast-Track | Accelerates TGA registration timelines by 12-18 months for implantable hardware manufacturers. |
| Private Clinic Cooperative Partnership | Locks volume commitments from Sydney and Melbourne buying groups before state tender consolidation advances. |
| PEEK Polymer Interbody Cage Portfolio Expansion | Captures Victoria's day surgery licensing reform-driven demand for radiolucent modulus-matched devices. |
| Regional Western Australia Distribution Buildout | Addresses Perth underpenetration with specialized logistics for degenerative disc disease procedure expansion. |
| Biologics Domestic Manufacturing Investment | Reduces import dependency for demineralized bone matrix in isolated Western Australia geography. |
Study Parameters
Operator-level perspectives from spine surgeons, hospital purchasing committee chairs, biomedical engineers at major Sydney and Melbourne facilities, and GPO contracts managers anchored the qualitative base, cross-referenced against TGA registration databases, state health network tender documentation, private clinic procurement records, and customs import data for titanium alloy and PEEK polymer feedstocks. Bottom-up procedure volume estimates triangulated with top-down manufacturer shipment data.
Sensitivity analysis tested forecast robustness across TGA reclassification scenarios, titanium price volatility bands, and private clinic licensing reform adoption curves. Segmentation dimensions modeled include product type, technology generation, end-user procurement authority, and application pathology across the projection horizon. CAGRs derived from procedure volume elasticity to demographic aging, surgical training pipeline expansion, and reimbursement rate trajectories.
Decision-makers should treat outputs as directional under stable TGA-EU MDR convergence and continued private clinic licensing liberalization; material deviation would warrant model refresh. Revision becomes warranted when Queensland regional hospital upgrade timelines or Western Australia surgeon recruitment rates cross thresholds altering volume distribution assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Russia Massage Equipment Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
North America C-Arms Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Hormonal Implants Market
Medical Devices
Airway Management Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Global Electrotherapy Devices Market