
 Global Laboratory Information Management System (LIMS) Market | 2026-2036
Global Laboratory Information Management System (LIMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Information Management System (LIMS) Market Foresight
The gap between premium enterprise LIMS and commodity laboratory software is consolidating around configurability, integration depth, and validated compliance workflows. Thermo Fisher Scientific Inc. leverages its instrument-to-informatics connectivity to anchor high-budget pharmaceutical accounts. LabWare sustains dominance in heavily regulated environments through deep workflow customization and multi-site deployment expertise. Autoscribe Informatics competes on modular architecture that lets mid-sized laboratories scale functionality without full platform replacement.
A Laboratory Information Management System is a software platform that automates sample tracking, workflow management, instrument integration, and regulatory reporting for laboratories, typically operating through relational database architectures with audit trail capabilities and role-based access controls. Its primary purpose is to ensure data integrity, accelerate throughput, and maintain compliance with standards such as ISO 17025 and Good Laboratory Practice across testing and research operations. Cloud-based deployment leads growth among segments as laboratories seek reduced capital expenditure and remote accessibility, while on-premise systems retain strength in defense and classified research settings where data sovereignty overrides flexibility. Pharmaceutical application demand outpaces other verticals because drug sponsors face intensifying regulatory scrutiny on data provenance from FDA and EMA reviewers.
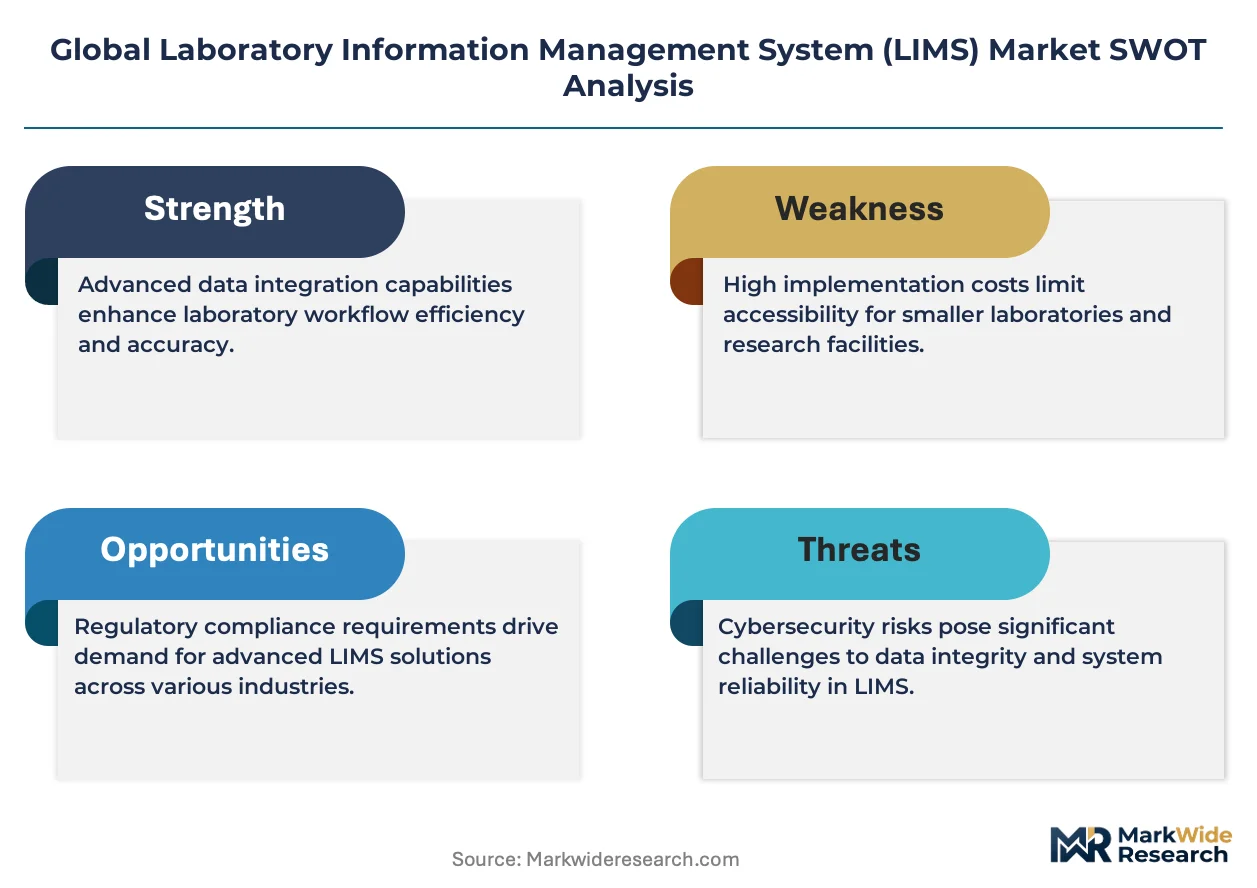
FDA 21 CFR Part 11, EU GMP Annex 11, and ISO 15189 standards collectively shape LIMS procurement by mandating electronic signature integrity, audit trail immutability, and inter-laboratory data comparability. The EPA and EMA both require traceable environmental and clinical data submissions, forcing vendors to embed compliance validation into core platform architecture rather than bolt-on modules. Stakeholders must monitor how AI-enabled data interpretation triggers new regulatory classification debates at FDA and EMA, as algorithm-assisted decision-making redraws boundaries between software tool and medical device.
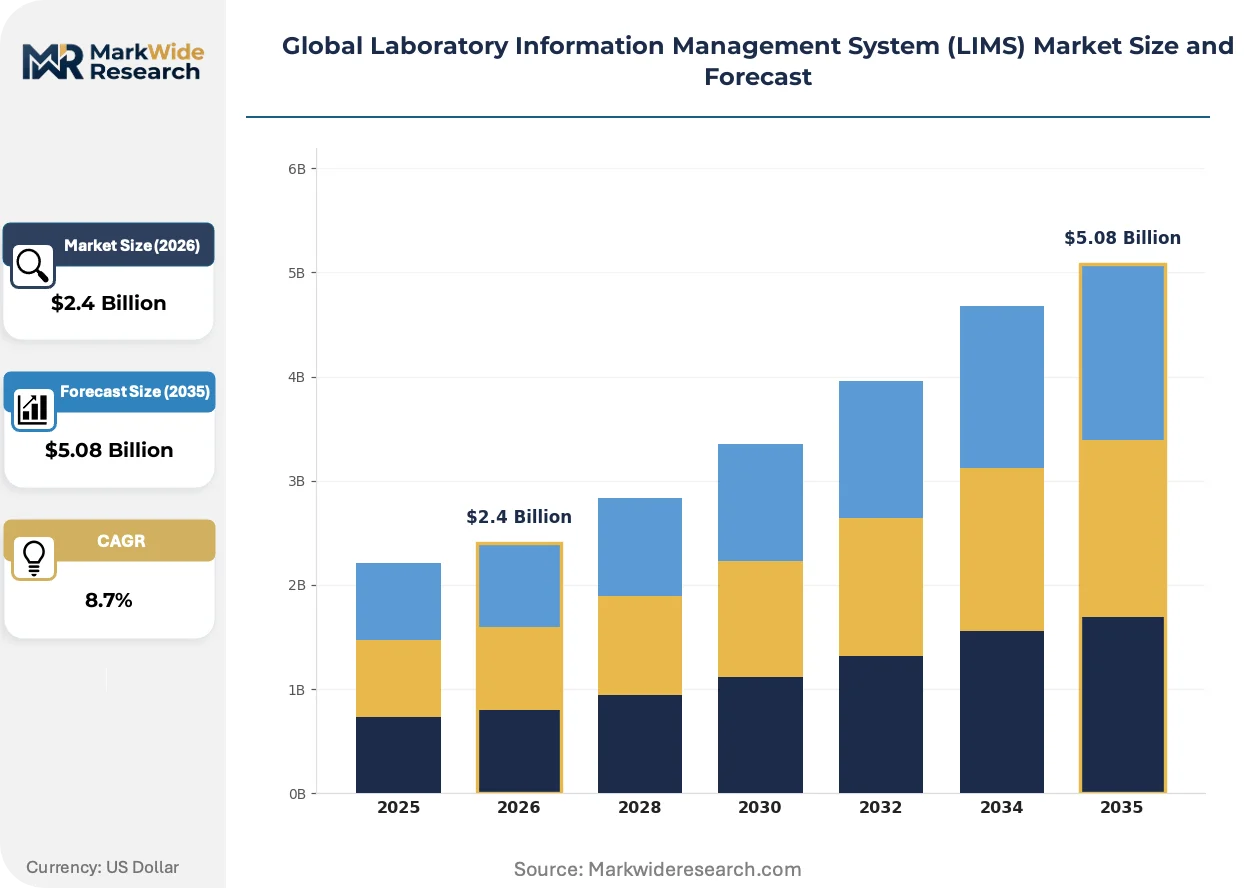
Market Dynamics
Cloud-native architecture is compressing deployment cycles from months to weeks, forcing incumbent vendors to re-platform legacy codebases while specialized SaaS entrants capture mid-market accounts previously locked out by enterprise licensing costs.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates in the United States compel regulated laboratories to upgrade from paper-based or non-validated systems, creating replacement demand across pharmaceutical quality control operations.
- Biopharma R&D expansion:Cell and gene therapy pipelines require sample lineage tracking across distributed manufacturing networks, pulling LIMS investment into contract development and manufacturing organizations.
- Multi-tenant cloud infrastructure:Shared-tenant architectures reduce per-laboratory IT overhead, enabling academic research consortia and regional hospital networks to adopt capabilities previously exclusive to large enterprises.
Market Restraints
- Validation cost concentration:Computer system validation for GxP environments consumes 40-60% of total implementation budgets, with documentation and testing labor concentrated among specialized consultants in the United States and Switzerland.
- Data sovereignty requirements:Defense and intelligence laboratories in the United States, France, and China mandate air-gapped on-premise deployments, blocking cloud migration for a structurally significant customer segment.
- Legacy system entrenchment:Decades of custom workflow coding in installed bases creates switching friction that extends replacement cycles beyond typical software refresh timelines.
Strategic Opportunities
- India pharmaceutical exports:CDSCO's alignment with ICH guidelines and the country's role as a generic drug supplier to regulated markets creates demand for validated LIMS in quality control laboratories across Mumbai and Hyderabad clusters.
- AI-assisted data interpretation:Convergence of machine learning models with structured laboratory data is absorbing anomaly detection and predictive maintenance functions, opening subscription revenue streams beyond core platform licensing.
- EU Green Deal compliance:Environmental monitoring laboratories across Germany, Netherlands, and Denmark require enhanced sample tracking and chain-of-custody documentation for emissions verification and circular economy material testing.
Industry Challenges
- CSV talent scarcity:Qualified computer system validation specialists with GxP experience command premium rates, extending project timelines for laboratories in secondary markets.
- Multi-vendor instrument integration:Proprietary data formats from chromatography, mass spectrometry, and automated liquid handling equipment force costly custom interface development.
- Regulatory divergence:EMA's evolving stance on AI-enabled decision support versus FDA's draft guidance on software as a medical device creates compliance uncertainty for vendors developing algorithmic features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Information Management System (LIMS) Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Web-Based Application: Pharmaceutical, Food Safety, Environmental Testing, Forensics, Chemical Testing End User: Research Institutes, Quality Control Labs, Contract Research Organizations, Academic Institutions Deployment Model: Single Laboratory, Multi-Laboratory, Enterprise Level, Department Level |
| Companies Covered | LabWare, Abbott, Thermo Fisher Scientific Inc., Illumina, Inc., Autoscribe Informatics, Siemens, PerkinElmer Inc., LabLynx, Inc., LabVantage Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Information Management System (LIMS) Market Shifts & Advancements
Platform architecture is bifurcating between configurable low-code environments for enterprise pharmaceutical accounts and API-first microservices for agile biotech startups, with regulatory validation depth becoming the primary differentiator rather than feature breadth.
Containerized deployment is absorbing the complexity of multi-site laboratory networks. Kubernetes-orchestrated LIMS instances enable pharmaceutical sponsors to maintain identical validated environments across United States, European, and Asian manufacturing sites without hardware replication. Thermo Fisher and LabWare are embedding container management into their enterprise offerings, compressing the time required for global rollout programs from years to quarters.
EMA's Annex 11 revision and the EU AI Act are tightening requirements for algorithmic transparency in laboratory decision support. Vendors must now document training data provenance and model drift monitoring for any AI-assisted release testing, pushing compliance engineering resources toward explainability tooling rather than raw predictive accuracy. German and Swiss pharmaceutical quality departments are demanding vendor-provided algorithmic risk classification documentation before procurement approval.
Consolidated procurement through group purchasing organizations is concentrating vendor selection authority at the health system level rather than individual laboratory directors. United States academic medical centers and European hospital networks are negotiating enterprise licenses covering pathology, clinical chemistry, and research operations simultaneously, displacing the fragmented point-solution purchasing that historically characterized the market. This concentration favors vendors with cross-domain workflow expertise over specialized clinical or research-only platforms.
Global Laboratory Information Management System (LIMS) Market Segmentation
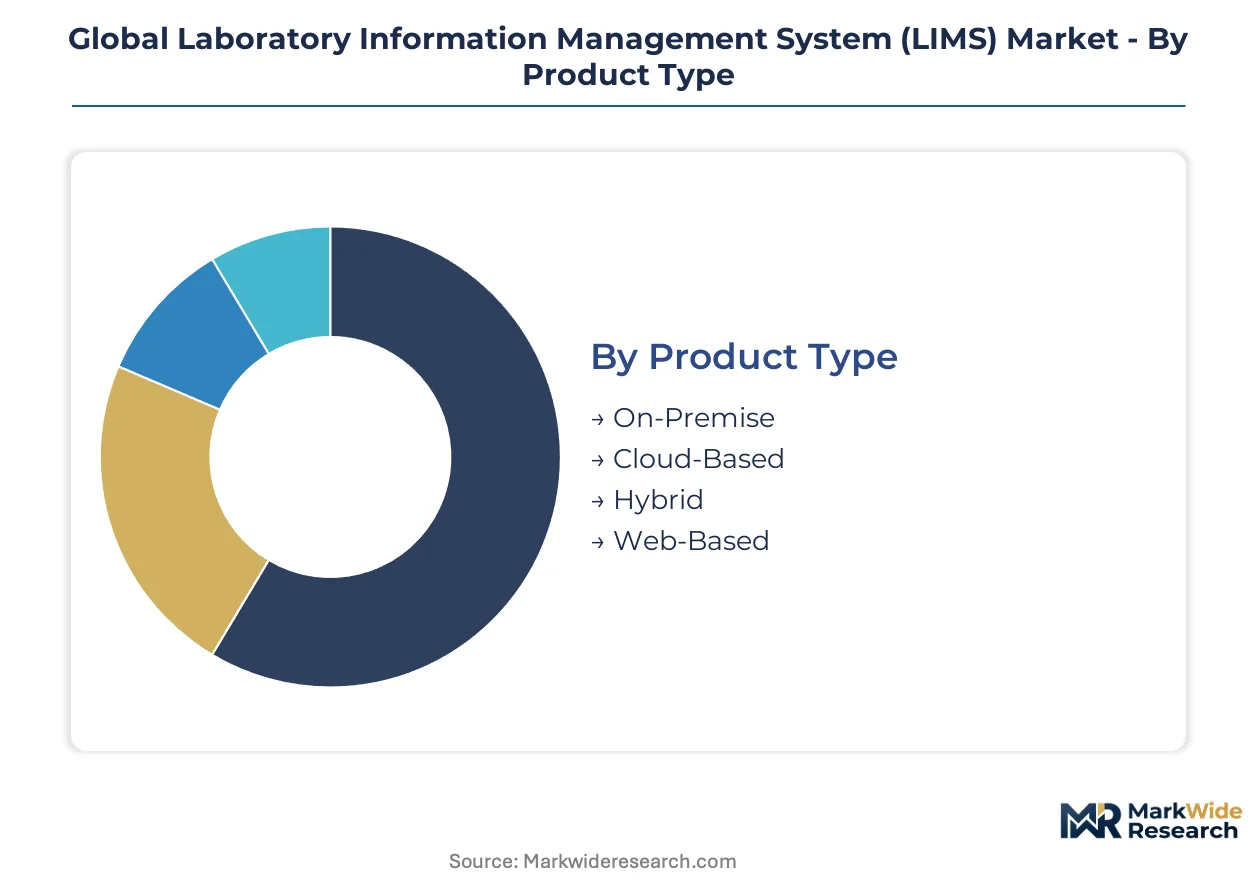
LIMS procurement patterns diverge sharply across deployment architectures and laboratory scales. Upgrade cycles and compliance validation requirements create distinct replacement timelines for each segment category.
Product Type:
Platform replacement cycles accelerate where cloud migration reduces validation burden and infrastructure overhead.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance and compress deployment timelines. Pharmaceutical quality control laboratories in the United States and Germany prioritize these platforms to satisfy FDA 21 CFR Part 11 and EU GMP Annex 11 without dedicated IT staff.
- On-Premise:Air-gapped installations run on laboratory-owned hardware with full data sovereignty. Defense and intelligence facilities in the United States, France, and China mandate this architecture despite higher capital expenditure and longer implementation cycles.
- Hybrid:Sensitive data remains on-premise while analytics and reporting leverage cloud elasticity.
- Web-Based:Browser-accessible platforms reduce client-side software distribution for distributed laboratory networks.
Volume placements concentrate in On-Premise systems; the faster expansion belongs to Cloud-Based platforms.
Application:
Regulatory scrutiny intensity determines solution sophistication requirements and average contract values.
- Pharmaceutical:Drug development workflows demand sample lineage tracking across distributed manufacturing networks. Cell and gene therapy pipelines in the United States, Switzerland, and Singapore pull investment into contract development organizations requiring validated environments.
- Environmental Testing:Emissions verification and circular economy material testing drive chain-of-custody documentation needs. Laboratories across Germany, Netherlands, and Denmark upgrade systems to meet EU Green Deal compliance deadlines.
- Food Safety:HACCP documentation and pathogen traceability requirements shape procurement specifications.
- Forensics:Evidence integrity standards mandate tamper-proof audit trails and role-based access controls.
- Chemical Testing:REACH compliance and hazardous substance tracking influence platform selection criteria.
Contract values peak in Pharmaceutical applications; Environmental Testing shows the steepest expansion trajectory from baseline.
End User:
Budget authority centralization and validation expertise availability shape purchasing patterns across laboratory types.
- Contract Research Organizations:Multi-sponsor data segregation and rapid study onboarding requirements demand configurable workflow engines. CROs in India and Eastern Europe invest to capture outsourced pharmaceutical work from regulated markets.
- Quality Control Labs:Release testing and batch record management require validated electronic signature capabilities. Facilities in the United States and Switzerland face the highest compliance engineering costs.
- Research Institutes:Grant-funded installations prioritize flexibility over pre-validated workflows.
- Academic Institutions:Shared-infrastructure consortia negotiate enterprise licenses covering multiple departments.
Procurement volume clusters in Quality Control Labs; CROs are climbing the fastest as outsourcing expands.
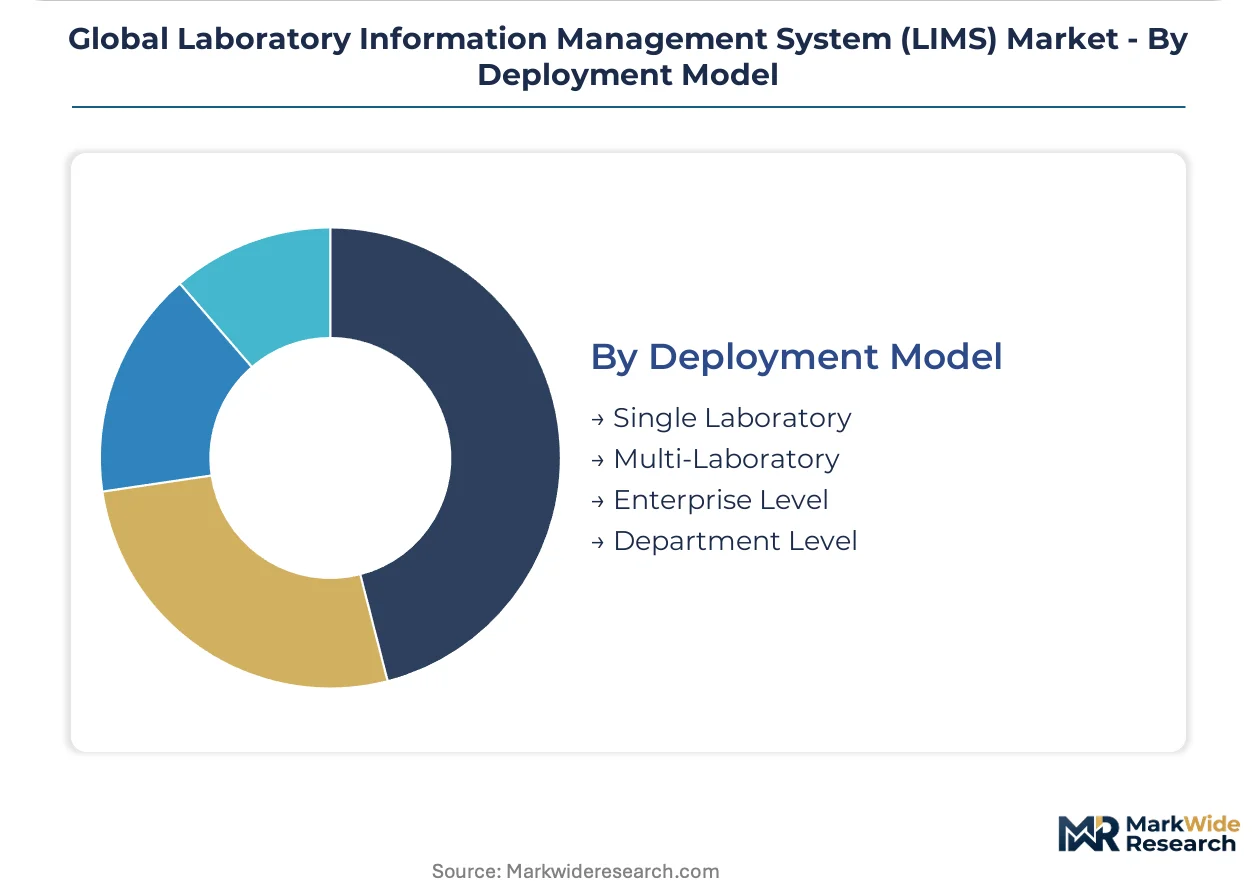
Deployment Model:
Organizational scale dictates integration complexity and change management requirements.
- Enterprise Level:Global pharmaceutical sponsors deploy identical validated environments across United States, European, and Asian manufacturing sites. Containerized orchestration compresses rollout timelines from years to quarters.
- Multi-Laboratory:Regional hospital networks and academic medical centers coordinate standardization across pathology, clinical chemistry, and research operations.
- Single Laboratory:Standalone installations serve specialized testing facilities with minimal inter-site coordination needs.
- Department Level:Sub-organizational deployments within larger institutions address specific workflow requirements.
Implementation spending concentrates at Enterprise Level; Multi-Laboratory deployments gain share fastest through group purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor anchors North American biopharma informatics procurement, with pharmaceutical sponsors and contract research organizations driving validated LIMS deployments across distributed manufacturing networks.
United States
FDA 21 CFR Part 11 compliance mandates and biopharma R&D tax incentives sustain replacement demand from paper-based systems. The National Institutes of Health laboratory modernization programs funnel federal procurement toward cloud-validated platforms. Massachusetts and California clusters concentrate enterprise deployments for cell and gene therapy pipeline tracking.
Germany
EU GMP Annex 11 requirements and REACH compliance deadlines pressure environmental testing laboratories to upgrade chain-of-custody documentation. The country's pharmaceutical quality control facilities in Baden-Württemberg and Bavaria prioritize audit trail immutability for batch release testing. German automotive suppliers extend LIMS adoption into battery materials verification for electric vehicle supply chains.
India
CDSCO's ICH guideline alignment and pharmaceutical export growth to regulated markets create demand for validated quality control systems. Mumbai and Hyderabad manufacturing clusters invest in multi-site LIMS to satisfy FDA pre-approval inspection requirements. Contract development organizations in Bangalore and Pune scale informatics capabilities to capture outsourced biopharma work.
Switzerland
Swissmedic's stringent data integrity standards and the country's concentration of biologics manufacturing sustain premium platform procurement. Basel and Zurich pharmaceutical quality departments demand vendor-provided algorithmic risk documentation for AI-assisted release testing. Swiss contract manufacturers deploy containerized LIMS across United States, European, and Asian sites to maintain validation parity.
China
NMPA's data integrity enforcement and dual carbon goals accelerate environmental monitoring laboratory upgrades. Shanghai and Suzhou pharmaceutical clusters adopt validated systems for generic drug export compliance. State-owned defense and aerospace facilities mandate air-gapped on-premise deployments, constraining cloud migration for a significant customer segment.
Global Laboratory Information Management System (LIMS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across configurability depth and regulatory validation expertise. The vendor base stratifies between instrument-integrated suites, workflow-customization specialists, and modular SaaS entrants. Three archetypes dominate: enterprise pharmaceutical platforms with global deployment capabilities, mid-market configurable systems, and API-first cloud-native solutions. M&A activity concentrates on acquiring specialized compliance validation expertise, while strategic partnerships between instrument manufacturers and software vendors tighten data flow integration.
Within the enterprise tier, Thermo Fisher Scientific Inc. and LabWare anchor high-budget pharmaceutical accounts through instrument connectivity and multi-site deployment expertise. Autoscribe Informatics occupies a position among modular architecture specialists serving mid-sized laboratories seeking scalable functionality without full platform replacement. These three exemplify the competitive vectors of integration depth, customization capability, and deployment flexibility that structure procurement decisions across regulated industries.
| Leading Market Players |
|---|
| LabWare |
| Abbott |
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Autoscribe Informatics |
| Siemens |
| PerkinElmer Inc. |
| LabLynx, Inc. |
| LabVantage Solutions Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal compliance deadlines gate qualified supply and premium-tier pricing access for environmental testing laboratories, forcing vendors to embed carbon footprint tracking and chain-of-custody documentation into validated platforms before procurement approval.
Pricing Analysis
Throughput-based pricing anchors enterprise pharmaceutical contracts, with annual recurring revenue tied to sample volume processed rather than seat licenses. Pricing stratifies across premium, standard, and economy tiers based on validation depth and multi-site deployment complexity. Cost compression in the mid-market intensifies as cloud-native entrants absorb price-sensitive academic consortia. Quality control laboratories in Switzerland and Germany exhibit the lowest price sensitivity due to regulatory non-negotiability, while regional hospital networks in India and Eastern Europe drive hardest on per-laboratory cost reduction.
Supply Chain Analysis
Dual-sourcing requirements from United States defense and pharmaceutical buyers mandate multi-supplier qualification for both software development and validation consulting services. Platform engineering concentrates in the United States, Germany, and India, with specialized computer system validation labor anchored in Switzerland and the United States. Proprietary instrument interface development rests on chromatography and mass spectrometry OEM partnerships. Single-source vulnerability in GxP-qualified validation talent extends implementation timelines. Distribution runs through direct enterprise sales for pharmaceutical accounts and channel partners for mid-market deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory validation depth, with FDA 21 CFR Part 11 compliance costs forcing commodity software vendors toward acquisition or exit.
For Market Incumbents: Extend containerized deployment capabilities to compress global rollout timelines for pharmaceutical sponsors operating across United States, European, and Asian manufacturing sites. Acquire specialized computer system validation consultancies in Switzerland and the United States to internalize the 40-60% implementation cost currently captured by third parties. Cloud-native entrants with modular API architectures threaten mid-market share; counter by embedding low-code configurability into enterprise platforms without sacrificing validation rigor. For New Entrants and Emerging Players: Capture the India pharmaceutical export opportunity by building pre-validated quality control workflows aligned with CDSCO and FDA inspection requirements for Mumbai and Hyderabad manufacturing clusters. Target contract development organizations in Bangalore and Pune with subscription pricing that undercuts enterprise licensing by 50-70% while delivering core sample lineage tracking. Lead with AI-assisted anomaly detection as a differentiated module rather than full platform replacement. For Investors and Strategic Acquirers: EMA's Annex 11 revision and EU AI Act algorithmic transparency requirements are the leading indicator that compliance engineering capabilities will command acquisition premiums. Position for a 5-10 year window where validated workflow depth outperforms feature breadth. Target acquisition archetype: mid-sized LIMS vendors with existing FDA 21 CFR Part 11 validation packages and installed bases in pharmaceutical quality control. Watch for CDSCO inspection citation rates as the signal for India market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Platform Deployment | Kubernetes-orchestrated instances enable pharmaceutical sponsors to maintain identical validated environments across multi-continental manufacturing sites without hardware replication. |
| Computer System Validation Consultancy Acquisition | Internalizing GxP-qualified documentation and testing labor captures the 40-60% of implementation budgets currently flowing to Swiss and United States specialists. |
| AI Explainability Tooling Investment | EMA's EU AI Act mandates training data provenance documentation for algorithmic release testing, redirecting R&D resources from raw accuracy toward regulatory-compliant transparency. |
| India Market Pre-Validation Packaging | CDSCO-aligned quality control workflows reduce FDA pre-approval inspection risk for Mumbai and Hyderabad generic drug exporters. |
| Multi-Tenant Cloud Infrastructure Buildout | Shared-tenant architectures reduce per-laboratory IT overhead, unlocking academic research consortia and regional hospital networks previously priced out of enterprise licensing. |
Research Methodology
Document review covered FDA 21 CFR Part 11 guidance documents, EMA Annex 11 revisions, ISO 15189 standards, and CDSCO inspection reports, complemented by interviews with LIMS vendor product managers, pharmaceutical quality control directors, contract research organization informatics leads, and computer system validation consultants across the United States, Germany, Switzerland, and India. Secondary sources included SEC filings from publicly traded instrument manufacturers, NIH laboratory modernization program procurement records, and EU Green Deal environmental monitoring laboratory upgrade announcements. Bottom-up triangulation of deployment counts by laboratory type and top-down reconciliation against aggregate pharmaceutical R&D spending produced convergent market sizing.
Segment-level outputs across cloud-based, on-premise, hybrid, and web-based deployment architectures were generated over the projection horizon, with pharmaceutical, environmental testing, food safety, forensics, and chemical testing applications modeled separately. Organization scale segmentation captured enterprise, multi-laboratory, single laboratory, and department-level deployments. CAGRs were derived from regression analysis of historical replacement cycles against regulatory deadline clustering, with biopharma R&D tax incentive schedules and federal laboratory modernization program funding trajectories serving as demand-side inputs.
The model holds under stable FDA and EMA regulatory enforcement intensity; deviation in AI-enabled decision support classification debates or CDSCO inspection capacity expansion would shift replacement timeline assumptions. Forecasts reflect documented compliance cost structures and validated workflow implementation patterns. A model refresh is warranted upon material change in EMA Annex 11 final guidance or NMPA data integrity enforcement escalation in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare EDI Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Global E-Health Market
Health Informatics
AI in Healthcare Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Global Health IT Security Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Healthcare BI Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Allergy Care Market
Health Informatics
Global Ambulatory EHR Market