
 Handheld Dental X-Ray Systems Market | 2026-2036
Handheld Dental X-Ray Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Dental X-Ray Systems Market Foresight
Mobile dental clinics and field outreach programs is unwinding the historical dominance of fixed-installation hospital radiology departments in handheld system procurement. VATECH leverages its CMOS sensor integration to sustain premium positioning across Asian export markets. Genoray anchors its competitive footprint through concentrated Korean manufacturing scale and domestic channel control. Carestream Dental LLC differentiates via established North American service networks that bind clinic customers to replacement cycles.
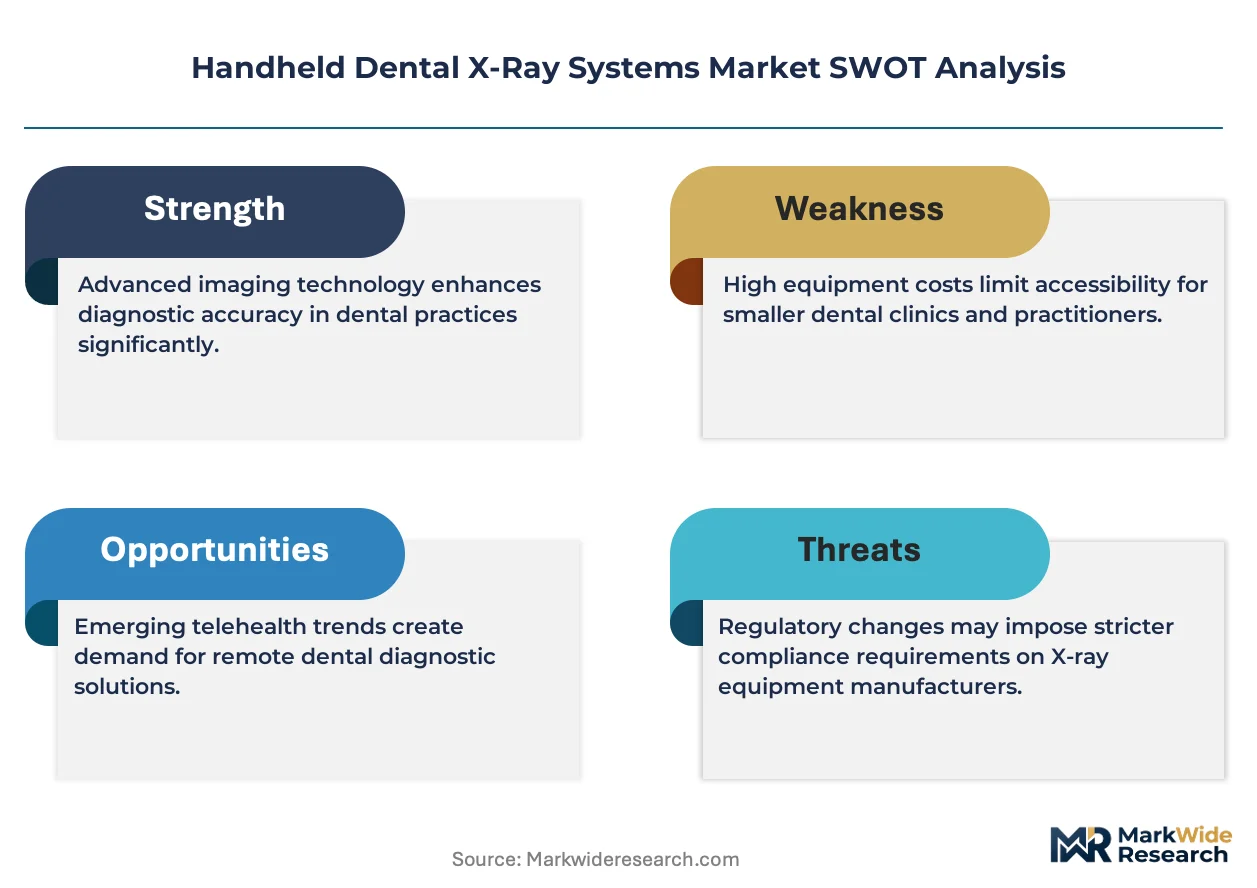
Handheld dental X-ray systems are self-contained, battery-operated radiographic emitters typically weighing under six pounds, designed to capture intraoral images without tethered power or fixed wall mounts; they employ solid-state digital sensors or phosphor plates to convert ionizing radiation into diagnostic images at chairside, eliminating patient repositioning and reducing procedure time in high-throughput practices. Wireless product configurations command the widest installed base due to elimination of cable sterilization burdens and tripping hazards in cramped operatory environments. Direct digital radiography technology leads replacement demand as practices retire film-based and computed radiography workflows, though conventional X-ray persists in budget-constrained rural clinics where sensor retrofit costs deter conversion.
FDA 510(k) clearance requirements and ALARA radiation safety principles govern device authorization and operator training protocols in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds and post-market surveillance obligations on manufacturers seeking CE marking access. Japan's PMDA maintains distinct pharmaceutical and medical device review standards that create separate compliance pathways for Asian-market entrants. Stakeholders must monitor evolving cybersecurity guidance for networked imaging devices and anticipate convergence between handheld dental units and AI-assisted diagnostic software platforms.
Market Dynamics
Mobile dental clinics and field outreach programs are unwinding the historical dominance of fixed-installation hospital radiology departments in handheld system procurement. Battery-powered units are displacing tethered wall-mounted systems in ambulatory settings where patient throughput and operatory flexibility determine equipment selection.
Growth Catalysts
- ALARA dose optimization protocols:US FDA 510(k) clearance pathways now mandate reduced radiation exposure thresholds, accelerating replacement of legacy high-dose equipment in high-throughput practices.
- Mobile clinic deployment:Field outreach programs across underserved rural counties and urban health deserts are creating sustained demand for battery-operated, sterilizable units that eliminate fixed infrastructure requirements.
- CMOS sensor integration:Solid-state digital sensors are capturing intraoral images at chairside with resolution parity to fixed systems, compressing procedure time and eliminating patient repositioning delays.
Market Restraints
- Sensor cost volatility:CMOS and scintillator material inputs remain concentrated among Asian semiconductor foundries, exposing manufacturers to supply disruption and input price swings.
- EU MDR clinical evidence thresholds:Stricter post-market surveillance obligations and expanded clinical data requirements for CE marking are extending authorization timelines and elevating compliance costs for market entrants.
- Computed radiography persistence:Phosphor plate systems retain installed base in budget-constrained rural clinics where direct digital sensor retrofit costs deter conversion, slowing technology turnover.
Strategic Opportunities
- AI-assisted diagnostic convergence:Handheld units integrating real-time caries detection algorithms and automated radiograph analysis are opening premium pricing tiers in specialty orthodontic and endodontic practices.
- Japanese PMDA pathway optimization:Distinct pharmaceutical and medical device review standards create first-mover advantages for manufacturers establishing localized regulatory expertise ahead of competitors.
- Veterinary dentistry extension:Equine and small-animal dental practices represent an underpenetrated channel where portable radiography addresses anatomical constraints that fixed systems cannot accommodate.
Industry Challenges
- Cybersecurity compliance for networked imaging:FDA guidance on medical device software security and EU MDR data integrity requirements are forcing firmware architecture redesigns and extended validation cycles.
- Operator certification fragmentation:State-level dental board radiation safety training mandates vary across jurisdictions, complicating national rollout of standardized training programs for clinic staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Dental X-Ray Systems Market |
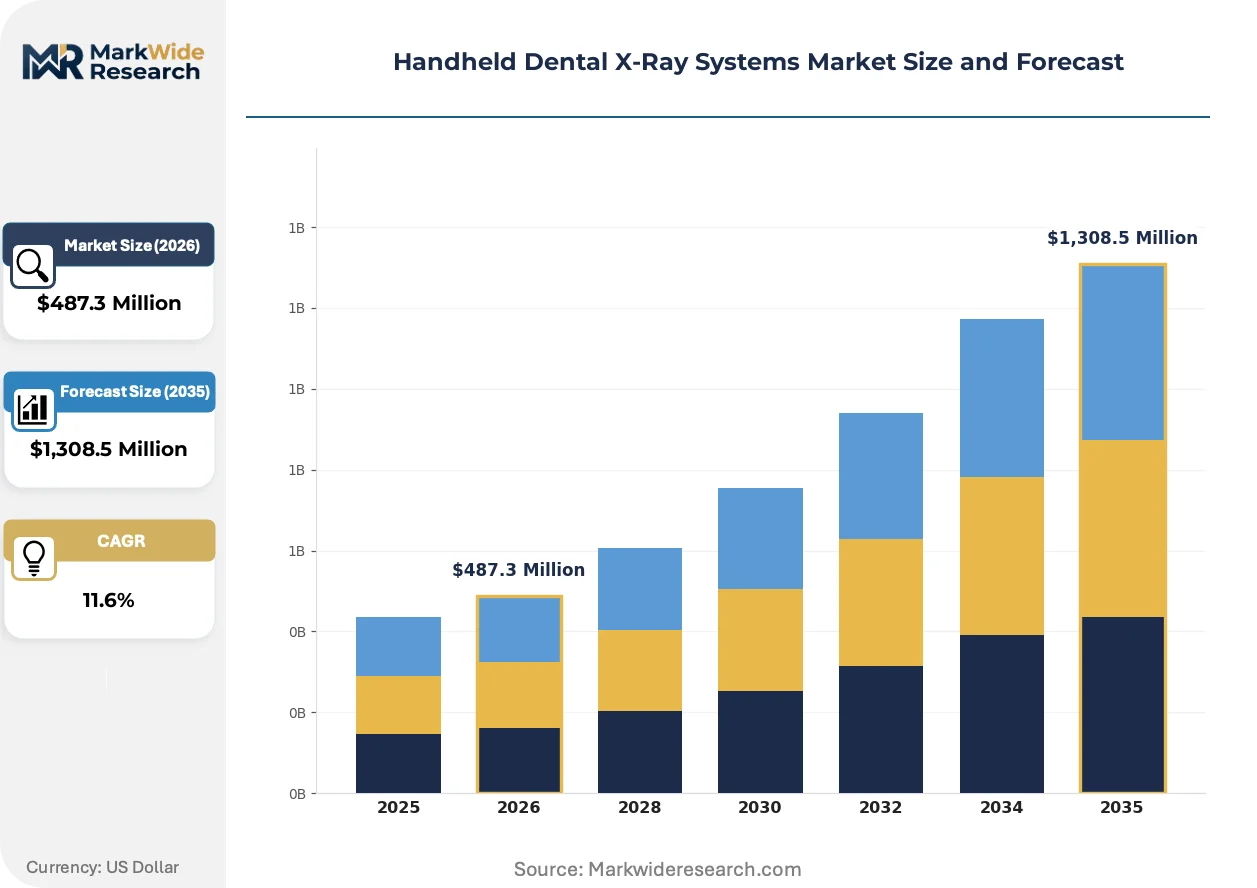
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless, Portable, Digital, Film-based Application: Oral Surgery, Orthodontics, Endodontics, General Dentistry End User: Dental Clinics, Diagnostic Centers, Hospitals, Research Institutions Technology: Computed Radiography, Direct Digital Radiography, Conventional X-Ray, Others |
| Companies Covered | Dental Imaging Technologies Corporation, Genoray, VATECH, Acteon, MaxRayDental, Digital Doc LLC, REMEDI Co Ltd, OXOS Medical, Carestream Dental LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Dental X-Ray Systems Market Shifts & Advancements
Wireless product configurations are commanding the widest installed base through elimination of cable sterilization burdens and tripping hazards in cramped operatory environments. Three developments are compressing replacement cycles and reshaping competitive positioning.
CMOS sensor technology is displacing charge-coupled device alternatives and legacy film-based workflows in high-throughput practices. Chairside digital capture eliminates darkroom processing delays and enables immediate diagnostic consultation. General dentistry groups with multiple operatories are prioritizing sensor interoperability across handheld and fixed units to standardize image archives.
Japan's PMDA maintains distinct pharmaceutical and medical device review standards that create separate compliance pathways for Asian-market entrants. Manufacturers seeking concurrent US and Japanese authorization must duplicate clinical evidence packages, elevating regulatory affairs staffing requirements. Korean and Chinese producers are responding by establishing Tokyo-based regulatory subsidiaries to accelerate localized approval timelines.
After-sales service unbundling is disrupting traditional equipment leasing models that bundled maintenance with hardware acquisition. Independent service organizations are capturing calibration and sensor replacement contracts from manufacturer-captive networks. This fragmentation is most visible in Germany, where dental equipment distributors face margin compression from direct manufacturer-to-clinic digital sales channels.
Handheld Dental X-Ray Systems Market Segmentation
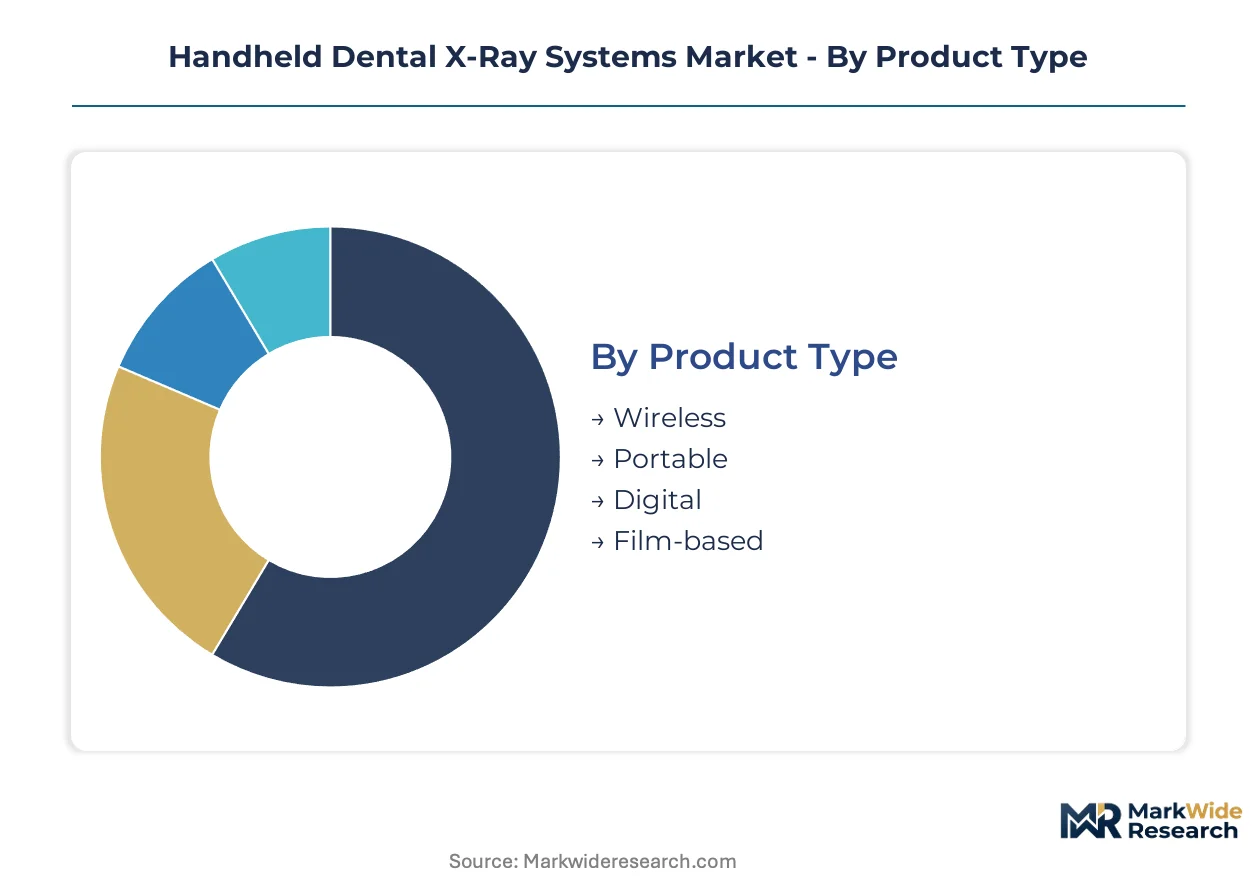
Segmentation in handheld dental X-ray systems reveals how procurement priorities diverge across clinical settings. Wireless configurations and direct digital radiography command premium positioning, while film-based systems persist in cost-constrained environments. Understanding these splits illuminates where manufacturers concentrate R&D spending and which channels warrant dedicated sales resources.
Product Type:
Margin pools concentrate in configurations that eliminate sterilization burdens and infrastructure dependencies, with wireless systems capturing the highest per-unit profitability.
- Wireless:Battery-powered units transmit images via Bluetooth or Wi-Fi, eliminating cable sterilization cycles and tripping hazards in cramped operatories. Demand concentrates in ambulatory dentistry groups across the United States and Germany where operatory throughput determines equipment selection. CMOS sensor integration and ALARA compliance protocols drive replacement of tethered legacy systems.
- Portable:Compact units under six pounds deploy across mobile dental clinics and field outreach programs, operating on rechargeable battery packs without fixed wall mounts. Japanese PMDA clearance pathways and EU MDR clinical evidence requirements shape product development timelines for manufacturers targeting concurrent multi-market authorization.
- Digital:Solid-state sensor systems capture chairside intraoral images with immediate display capability, replacing darkroom processing workflows in high-throughput practices.
- Film-based:Analog radiographic systems using silver halide emulsion retain installed base in rural clinics where sensor retrofit costs deter technology conversion.
Wireless holds installed capacity. Digital is rotating up the share rankings.
Application:
Volume concentrates in generalist settings, though specialty orthodontic and endodontic practices generate disproportionate revenue per procedure through precision imaging requirements.
- General Dentistry:Routine diagnostic imaging for caries detection and restorative treatment planning constitutes the highest procedure volume segment. Multi-operatory group practices in the United States standardize on interoperable sensor platforms across handheld and fixed units to consolidate image archives.
- Orthodontics:Cephalometric and panoramic adjunct imaging demands high-resolution sensors for treatment progression monitoring. German dental equipment distributors face margin compression from direct manufacturer-to-clinic digital sales channels in this premium application tier.
- Endodontics:Periapical imaging for root canal therapy requires precise angulation control and high-contrast resolution for file path verification.
- Oral Surgery:Preoperative and postoperative imaging for extraction and implant placement utilizes portable units in surgical suites where patient mobility is restricted.
General Dentistry dominates procedure volume. Orthodontics is gaining share fastest.
End User:
Procurement authority and replacement cycle frequency vary sharply across institutional settings, with independent clinics driving technology turnover and hospitals lagging in portable system adoption.
- Dental Clinics:Independent and group practice settings generate sustained demand for battery-operated, sterilizable units that eliminate fixed infrastructure. Mobile clinic deployment across underserved rural counties and urban health deserts creates additional channel volume.
- Hospitals:Fixed-installation radiology departments historically dominated procurement but are unwinding share as ambulatory dentistry expands. Tethered wall-mounted systems retain presence in surgical suites.
- Diagnostic Centers:Specialized imaging facilities utilize handheld units for overflow capacity and patient populations requiring chairside accommodation.
- Research Institutions:Academic dental schools and clinical trial sites deploy portable systems for training and protocol standardization across multiple operatories.
Dental Clinics anchor installed base. Diagnostic Centers are climbing the fastest.
Technology:
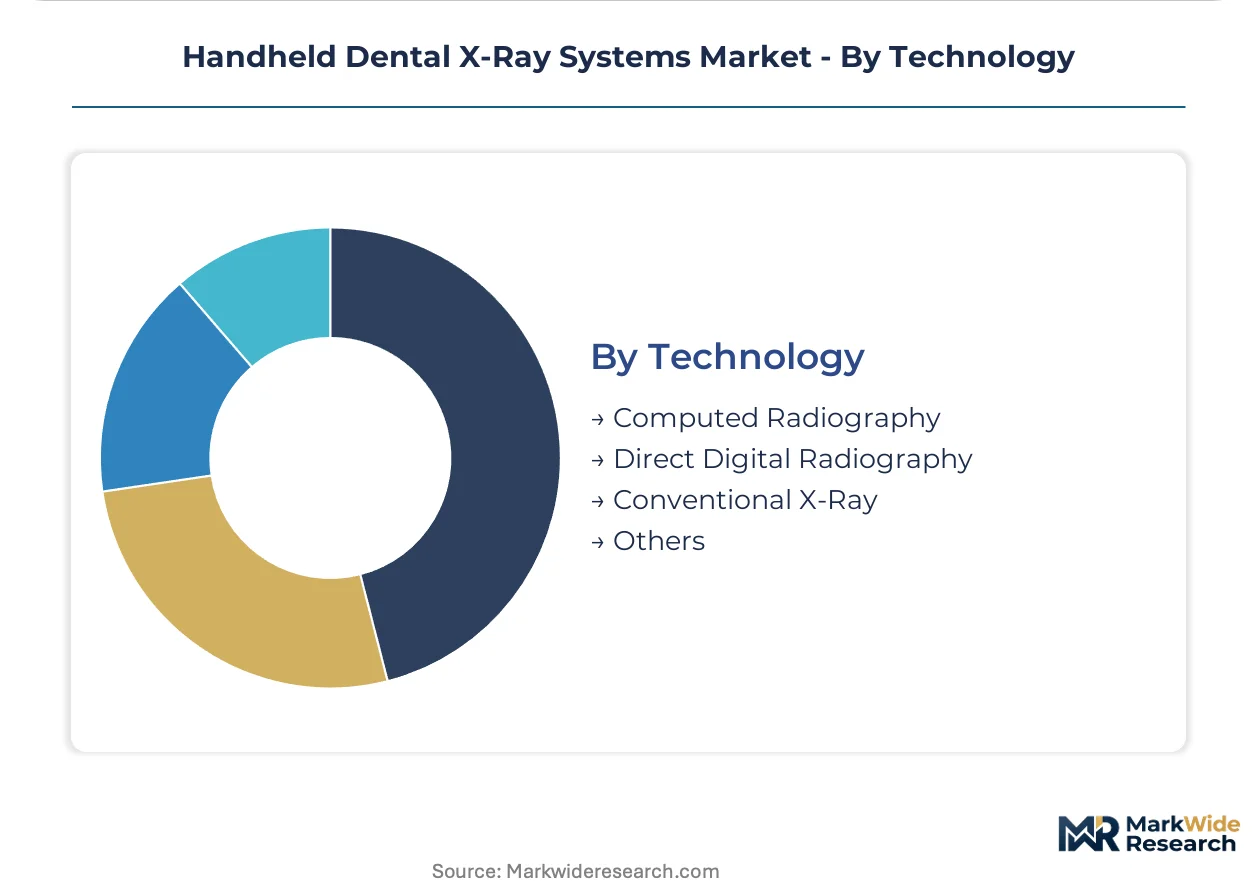
Technology maturity curves determine replacement urgency, with direct digital radiography compressing procedure time while computed radiography persists in budget-sensitive accounts.
- Direct Digital Radiography:CMOS and charge-coupled device sensors convert ionizing radiation immediately into digital images without intermediate processing. High-throughput practices in Japan and the United States prioritize this technology for chairside diagnostic consultation and immediate patient communication.
- Computed Radiography:Phosphor plate systems require scanning digitization after exposure, occupying intermediate cost tier between film and direct digital. Rural clinics with capital constraints defer conversion despite longer procedure times.
- Conventional X-Ray:Analog film-based workflows using chemical processing retain presence in legacy installations where equipment amortization extends replacement timelines.
- Others:Emerging sensor technologies including photon-counting detectors and scintillator materials under development for future product generations.
Direct Digital Radiography commands technology leadership. Computed Radiography maintains transitional installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific sensor component flows into the United States, while Hamburg's container terminals distribute CMOS modules across German manufacturing clusters. These logistics corridors determine where handheld dental X-ray assembly concentrates and which regulatory jurisdictions shape product authorization timelines.
United States
Ambulatory dentistry groups in Texas and Florida drive battery-powered unit procurement for multi-operatory practices. FDA 510(k) clearance pathways mandate ALARA dose optimization protocols that accelerate replacement of legacy high-dose equipment. Los Angeles County hosts the densest concentration of mobile dental clinics serving urban health deserts.
Germany
North Rhine-Westphalia dental equipment distributors face margin compression from direct manufacturer-to-clinic digital sales channels. EU Medical Device Regulation imposes stricter clinical evidence thresholds and post-market surveillance obligations on manufacturers seeking CE marking. Bavarian precision engineering clusters supply calibration equipment for sensor alignment systems.
Japan
Kanto region high-throughput practices prioritize CMOS sensor interoperability for immediate chairside diagnostic consultation. PMDA maintains distinct pharmaceutical and medical device review standards that create separate compliance pathways for Asian-market entrants. Tokyo-based regulatory subsidiaries accelerate localized approval timelines for Korean and Chinese producers.
South Korea
Domestic channel control in Seoul Capital Area sustains manufacturing scale advantages for export-oriented producers. MFDS alignment with international standards facilitates concurrent authorization with Japanese and US regulators. Busan-Ulsan semiconductor foundries concentrate scintillator material inputs for sensor production.
China
Yangtze River Delta dental schools deploy portable systems for training standardization across multiple operatories. NMPA medical device review standards are converging with international norms for imaging equipment authorization. Shenzhen hardware clusters produce wireless transmission modules for Bluetooth-enabled configurations.
Handheld Dental X-Ray Systems Market Competitive Landscape
Concentration sits with integrated sensor manufacturers and regional service network operators. The vendor base spans three tiers: multinational imaging conglomerates with captive distribution, specialized dental equipment fabricators with concentrated geographic footprints, and emerging portable technology developers targeting mobile clinic channels. Dominant competitive moves include backward integration into CMOS sensor supply and establishment of regulatory affairs subsidiaries in Tokyo and Seoul to accelerate multi-market authorization.
Among Korean-based fabricators, Genoray and VATECH occupy positions within the manufacturing-scale archetype, while Carestream Dental LLC represents the established North American service network tier. These three anchors illustrate how competitive positioning diverges between production-centric and channel-centric strategies in handheld dental radiography.
| Leading Market Players |
|---|
| Dental Imaging Technologies Corporation |
| Genoray |
| VATECH |
| Acteon |
| MaxRayDental |
| Digital Doc LLC |
| REMEDI Co Ltd |
| OXOS Medical |
| Carestream Dental LLC |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance pathways and ALARA dose optimization protocols gate both supplier qualification and price differentiation in handheld dental X-ray systems, compressing margins for non-compliant manufacturers while enabling premium positioning for certified entrants. CMOS sensor integration costs and battery-powered sterilizable designs stratify procurement budgets across ambulatory dentistry groups and rural clinics.
Pricing Analysis
Volume-discount tiering structures separate premium wireless configurations with integrated CMOS sensors from standard portable units and economy film-based alternatives. Certification grade differentiation—FDA 510(k) clearance versus pending authorization—drives price spreads exceeding two-to-one between authorized and non-compliant suppliers. Pricing pressure stems from independent service organizations capturing calibration contracts from manufacturer-captive networks, eroding aftermarket margins. Rural clinics exhibit highest price sensitivity due to capital constraints, while multi-operatory group practices prioritize interoperability over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and Hamburg container terminals concentrate CMOS module flows from Busan-Ulsan semiconductor foundries and Yangtze River Delta sensor fabricators. Scintillator materials, rechargeable battery packs, and wireless transmission modules draw from South Korean, Chinese, and Japanese production clusters. Single-source vulnerability in Asian semiconductor foundries exposes manufacturers to input disruption. Distribution runs through dental equipment distributors in Germany and direct manufacturer-to-clinic digital channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in multi-market regulatory expertise—simultaneous FDA, PMDA, and EU MDR navigation—separates viable competitors from stranded investments. Manufacturers lacking Tokyo or Seoul-based regulatory subsidiaries face authorization delays that compress commercialization windows.
For Market Incumbents: Secure backward integration into CMOS sensor supply chains to buffer against Asian foundry concentration and input price volatility. Consolidate service network coverage in North American ambulatory dentistry groups before independent service organizations capture replacement cycle contracts. Defend against emerging Korean and Chinese producers establishing localized PMDA expertise by accelerating multi-market submission timelines.
For New Entrants and Emerging Players: Anchor in veterinary dentistry extension channels—equine and small-animal practices—where portable radiography addresses anatomical constraints that fixed systems cannot accommodate. Target mobile dental clinic procurement in underserved rural counties and urban health deserts where infrastructure-light battery-powered units eliminate fixed installation requirements. Pursue direct digital radiography conversion opportunities in budget-constrained clinics through sensor leasing rather than capital purchase models.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational imaging conglomerates divesting non-core dental divisions to focus on hospital radiology systems. Long-term viability rests on regulatory affairs capabilities spanning three-plus jurisdictions rather than manufacturing scale alone. Monitor FDA cybersecurity guidance enforcement as inflection indicator for firmware architecture redesign costs that will strain undercapitalized competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Tokyo Regulatory Subsidiary Establishment | PMDA localized expertise accelerates Japanese authorization timelines ahead of Korean and Chinese competitors. |
| CMOS Sensor Backward Integration | Captive supply of scintillator materials buffers Busan-Ulsan foundry concentration and input price swings. |
| Independent Service Organization Partnership | Calibration and sensor replacement contract capture defends aftermarket revenue from manufacturer-captive networks. |
| Veterinary Dentistry Channel Entry | Equine and small-animal practices represent underpenetrated white space where anatomical constraints favor portable units. |
| AI Diagnostic Software Companion Development | Real-time caries detection algorithms open premium pricing tiers in orthodontic and endodontic specialty practices. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR clinical evidence submissions, PMDA authorization records, and hospital procurement databases. Dental equipment distributors, biomedical engineers, clinic purchasing managers, and regulatory affairs specialists provided structured input across the United States, Germany, Japan, South Korea, and China. Customs records for CMOS sensor imports and dental equipment trade flows supplied bottom-up volume validation against top-down ambulatory dentistry infrastructure expansion estimates.
Segmentation dimensions modeled include product configuration (wireless, portable, digital, film-based), application specialty (general dentistry, orthodontics, endodontics, oral surgery), end-user institution (dental clinics, hospitals, diagnostic centers, research institutions), and technology generation (direct digital radiography, computed radiography, conventional X-ray). CAGRs were derived from procedure volume elasticity to ambulatory dentistry expansion, replacement cycle compression from ALARA compliance mandates, and technology conversion rates from phosphor plate to solid-state sensor workflows across the projection horizon. Regulatory authorization timelines and cybersecurity compliance costs informed scenario-weighted outcomes.
Decision-makers should treat outputs as directional under assumptions of sustained FDA ALARA enforcement, stable CMOS foundry capacity, and continued mobile clinic deployment funding; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Mammography Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
South Korea Mammography Market